
 Vitamin Fortified and Mineral Enriched Food & Beverage Market | 2026-2036
Vitamin Fortified and Mineral Enriched Food & Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Fortified and Mineral Enriched Food & Beverage Market Insights
The EU Green Deal is realigning fortification standards across European packaged food categories. Nestlé SA leverages its dairy science infrastructure to sustain dominance in pediatric nutrition formulations. PepsiCo anchors its portfolio around functional beverages with electrolyte and vitamin complexes. Abbott Laboratories differentiates through clinical-grade nutritional platforms targeting metabolic health.
Vitamin fortified and mineral enriched food and beverage denotes products where micronutrients are added post-processing to achieve defined nutritional density thresholds, typically measured in percentage of daily value per serving. Manufacturers employ spray-drying, microencapsulation, and direct blending to preserve bioavailability through shelf life. Functional foods occupy the largest revenue pool due to embedded placement in daily consumption rituals. Nutritional beverages represent the fastest-expanding segment as athletes and elderly consumers prioritize portable hydration with electrolyte-vitamin matrices. Dietary supplements retain higher per-unit margins but face channel competition from food-format alternatives.
The FDA governs nutrient content claims through 21 CFR 101.54, while EFSA establishes population reference intakes that shape product formulation targets in Europe. India's FSSAI mandates fortification logos on packaged staples, accelerating compliance investments by multinational suppliers. Stakeholders must monitor evolving bioequivalence standards between synthetic and food-matrix nutrients as regulators tighten substantiation requirements.
Market Dynamics
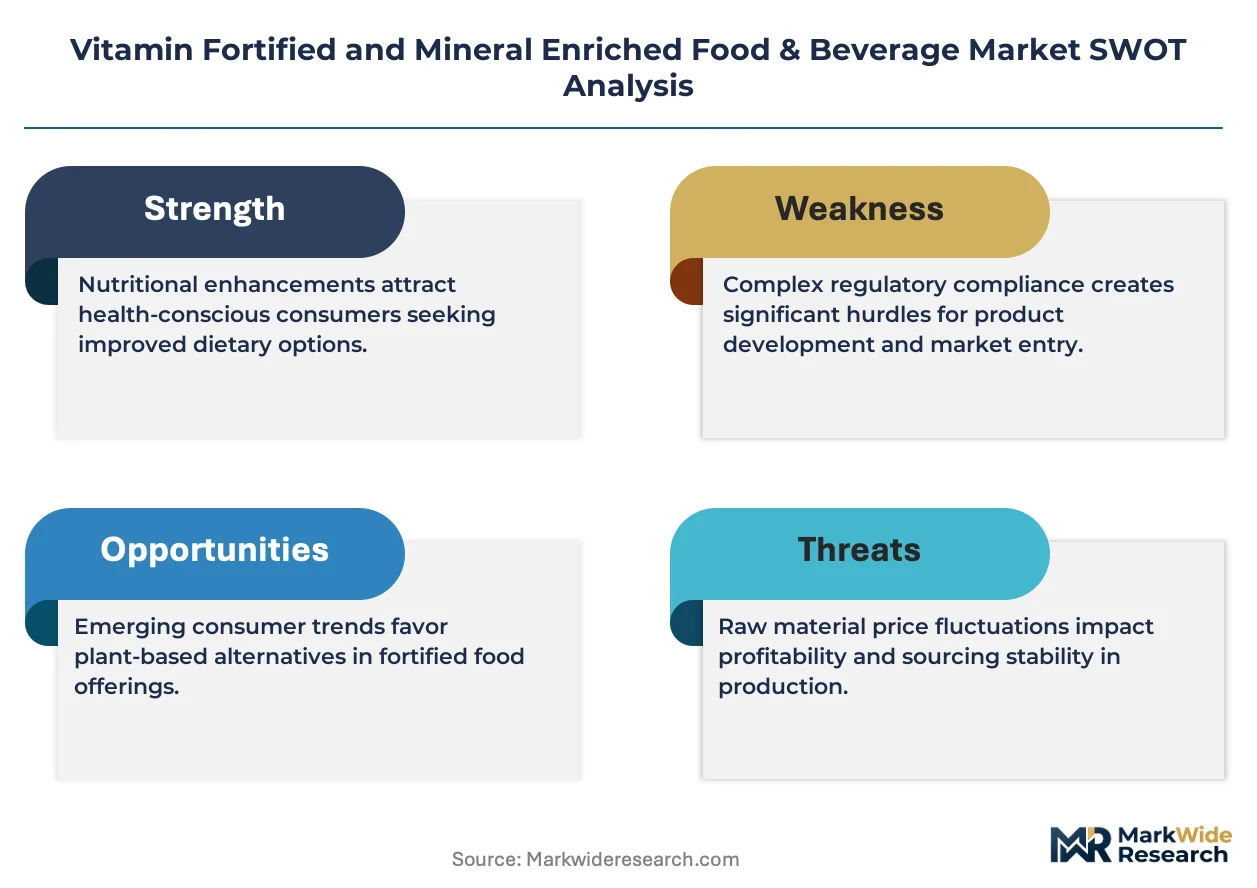
The EU's Nutrient Profiling Model is compressing permissible fortification claims across packaged goods, forcing manufacturers to reformulate portfolios around stricter bioavailability thresholds and substantiation requirements.
Growth Catalysts
- EFSA Population Reference Intakes:These thresholds provide formulation targets that reduce R&D uncertainty for European manufacturers entering pediatric and geriatric nutrition segments.
- India FSSAI fortification logos:Mandatory labeling on packaged staples accelerates compliance investments by multinational suppliers and expands addressable market for premix providers.
- Microencapsulation technology:Advanced coating methods preserve vitamin stability through thermal processing and extended shelf life in functional dairy applications.
Market Restraints
- Premix supply concentration:Three specialty chemical suppliers control the majority of food-grade vitamin D and iron premix capacity, creating input vulnerability for mid-sized formulators.
- Synthetic nutrient bioequivalence disputes:Regulators in multiple jurisdictions question whether isolated micronutrients deliver equivalent absorption to food-matrix sources, complicating label claims.
- Clean-label substitution:Consumer preference for minimally processed whole foods threatens demand for overtly fortified packaged products in premium retail channels.
Strategic Opportunities
- Clinical nutrition platforms:Hospital and long-term care facilities seek condition-specific formulations targeting metabolic syndrome and post-surgical recovery.
- Sports hydration with electrolyte-vitamin matrices:Athletes and fitness enthusiasts drive portable nutrition formats beyond traditional supplement powders.
- EU Green Deal alignment:Sustainable sourcing requirements create first-mover advantage for manufacturers with verified supply chain traceability and reduced carbon footprint premix logistics.
Industry Challenges
- Formulation scientist scarcity:The intersection of food chemistry, regulatory science, and sensory engineering requires specialized talent pools that remain underdeveloped in emerging manufacturing hubs.
- Dual certification timelines:Simultaneous FDA 21 CFR 101.54 compliance and EFSA novel food assessments extend product launch cycles by 18-24 months for multinational portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Fortified and Mineral Enriched Food & Beverage Market |
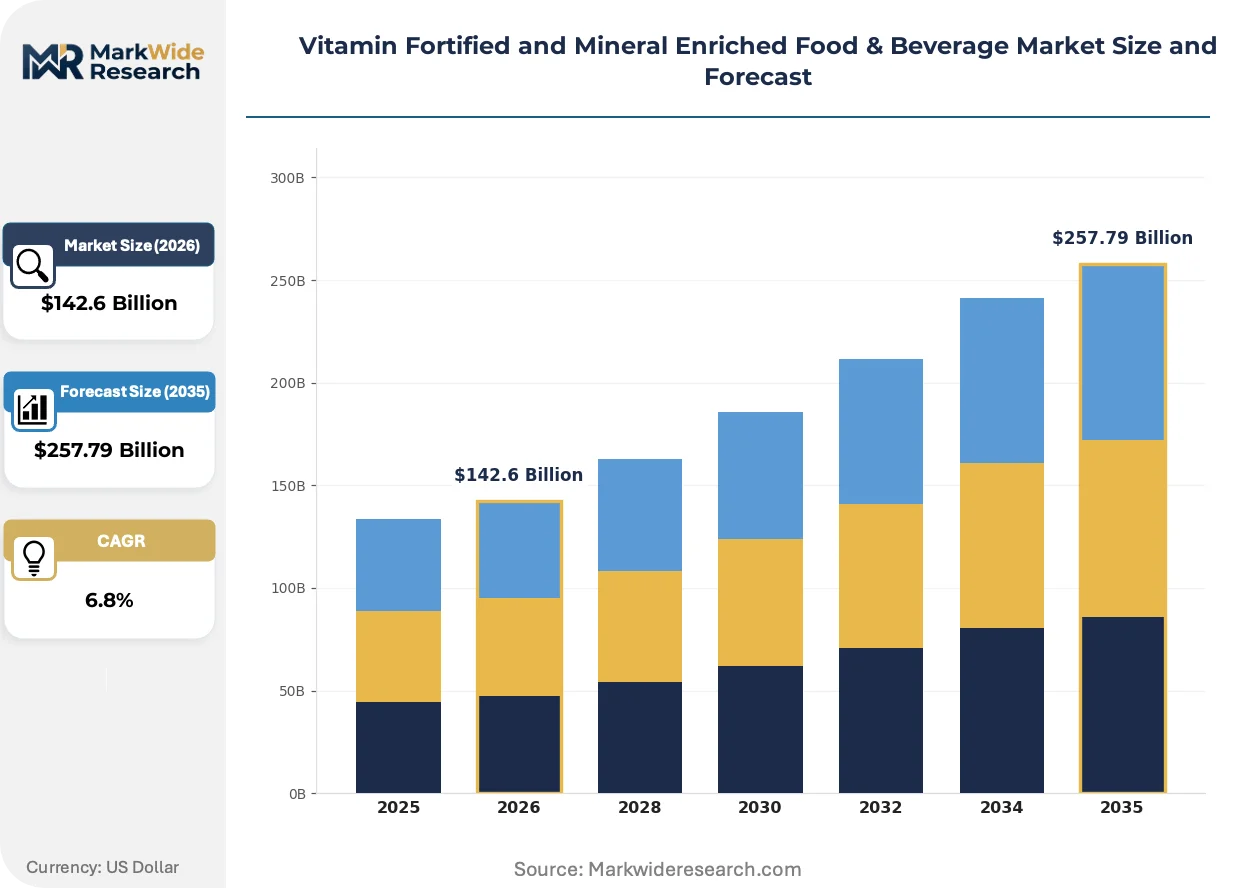
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Foods, Nutritional Beverages, Fortified Snacks, Dietary Supplements End User: Health-Conscious Consumers, Athletes, Children, Elderly Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Packaging Type: Bottles, Sachets, Tetra Packs, Pouches |
| Companies Covered | Amway Corporation, Abbott Laboratories, Nestlé SA, Kellogg Company, The Hain Celestial Group, Inc., PepsiCo, Inc., Kellanova, Fulfil, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Fortified and Mineral Enriched Food & Beverage Market Trends and Innovations
Formulation science and regulatory architecture are converging to reshape how micronutrients enter daily consumption rituals, with technology and policy jointly determining competitive viability.
Spray-dried lipid encapsulation systems are overtaking traditional dry blending in functional beverage manufacturing. Beverage brands targeting elderly consumers and endurance athletes now specify microencapsulated vitamin complexes that survive pasteurization and carbonation stress. This technology is compressing formulation failure rates and extending permissible shelf life claims.
EFSA's evolving guidance on health claims substantiation is tightening clinical evidence requirements for mineral-enriched products. Manufacturers must now commission human intervention trials rather than relying on compositional data alone. Pediatric nutrition and cognitive function segments face the steepest compliance cost increases as dossier preparation timelines lengthen.
Direct-to-consumer subscription models for personalized micronutrient testing and formulation are fragmenting traditional retail channel dominance. Wellness platforms integrate at-home biomarker assessment with algorithm-driven product recommendations, bypassing conventional pharmacy and supermarket distribution. This pattern concentrates in the United States and United Kingdom where regulatory frameworks permit telehealth-adjacent nutrition counseling.
Vitamin Fortified and Mineral Enriched Food & Beverage Market Segmentation
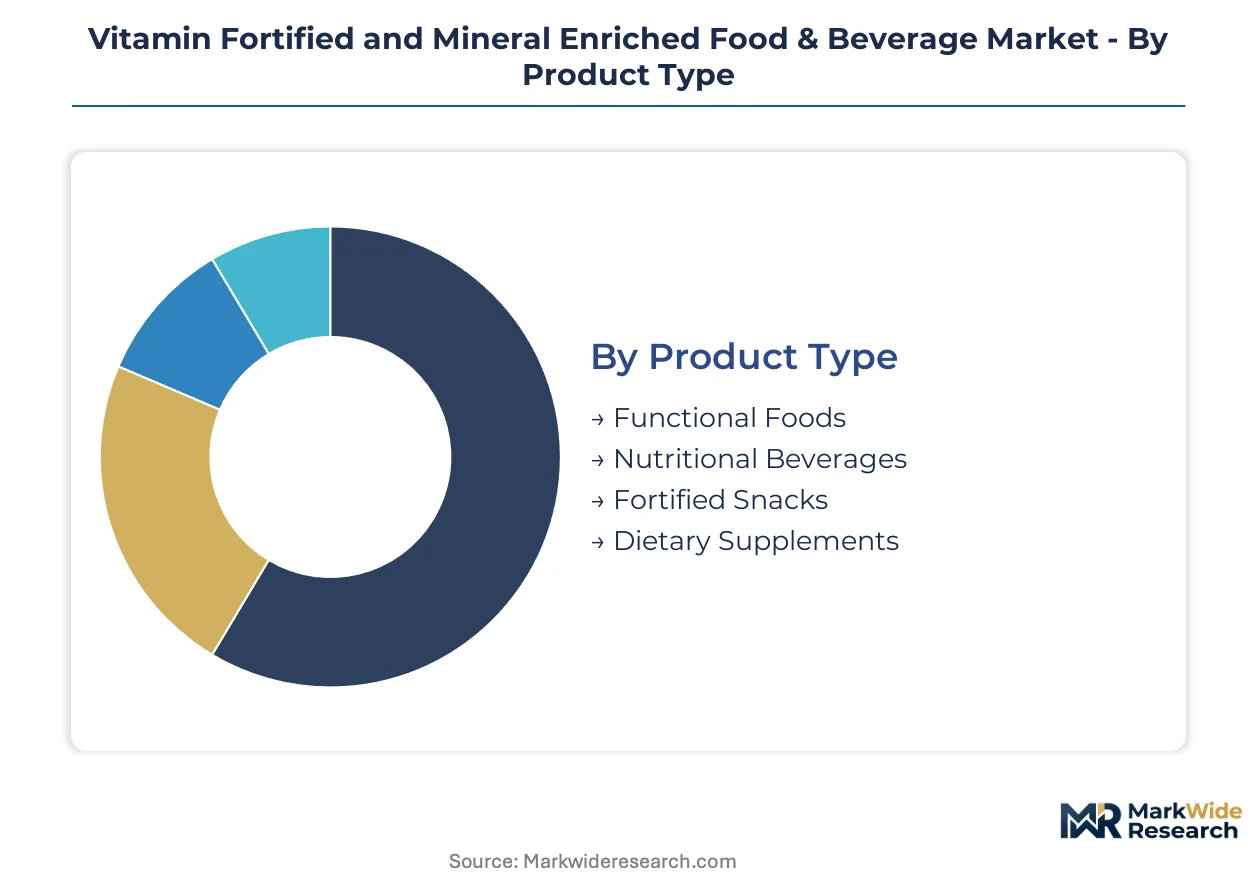
Segmentation in fortified nutrition reveals distinct procurement patterns across consumption occasions, age cohorts, and retail formats. Manufacturers calibrate formulation intensity, bioavailability engineering, and shelf-life protocols differently for each slice of demand.
Product Type:
Buyers in this category separate by consumption ritual frequency and nutritional density requirements rather than price sensitivity alone.
- Functional Foods:Embedded fortification in daily staples like dairy, bread, and breakfast cereals uses microencapsulation to preserve vitamin stability through thermal processing. Demand concentrates in the United States where fortified ready-to-eat cereals command permanent shelf placement in conventional retail.
- Nutritional Beverages:Ready-to-drink formats with electrolyte-vitamin matrices target portable hydration needs. Athletes and elderly consumers in Germany and the United Kingdom drive procurement of pasteurization-stable formulations with extended ambient shelf life.
- Fortified Snacks:Extruded and baked applications carry lower nutrient loads due to processing losses.
- Dietary Supplements:Capsule and tablet formats retain higher per-unit margins but face channel competition from food-format alternatives.
Functional Foods leads volumes today; Nutritional Beverages is gaining share fastest.
End User:
Formulation complexity escalates with physiological vulnerability and metabolic specificity of the target consumer.
- Health-Conscious Consumers:Adults seeking preventive nutrition drive demand for clean-label fortification with transparent supply chain documentation. This segment spans mass-market retail in France and premium channels in the United Kingdom.
- Children:Pediatric nutrition requires iron, zinc, and vitamin D at precise bioavailability thresholds governed by EFSA population reference intakes. Abbott Laboratories and Nestlé SA compete intensely for parental trust through clinical substantiation.
- Athletes:Performance-oriented hydration with electrolyte-vitamin complexes demands rapid gastric emptying and osmolality control.
- Elderly:Sarcopenia and malnutrition risk drive condition-specific formulations targeting protein-energy fortification with micronutrient density.
Health-Conscious Consumers anchors revenue today; Children shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines permissible health claims, temperature requirements, and margin structure for fortified products.
- Supermarkets:Mass retail chains in the United States and Germany enforce strict nutrient profiling criteria that filter permissible fortification claims. PepsiCo and Nestlé SA leverage direct buyer relationships to secure end-cap placement for functional beverage lines.
- Online Retail:Direct-to-consumer subscription models for personalized micronutrient testing bypass conventional pharmacy distribution. This channel concentrates in the United States and United Kingdom where telehealth-adjacent nutrition counseling operates under permissive frameworks.
- Health Food Stores:Specialty retail commands premium pricing for organic-certified fortification with non-synthetic nutrient sources.
- Convenience Stores:Impulse-driven procurement favors single-serve fortified beverages with immediate consumption positioning.
Supermarkets dominates volume today; Online Retail is climbing the fastest.
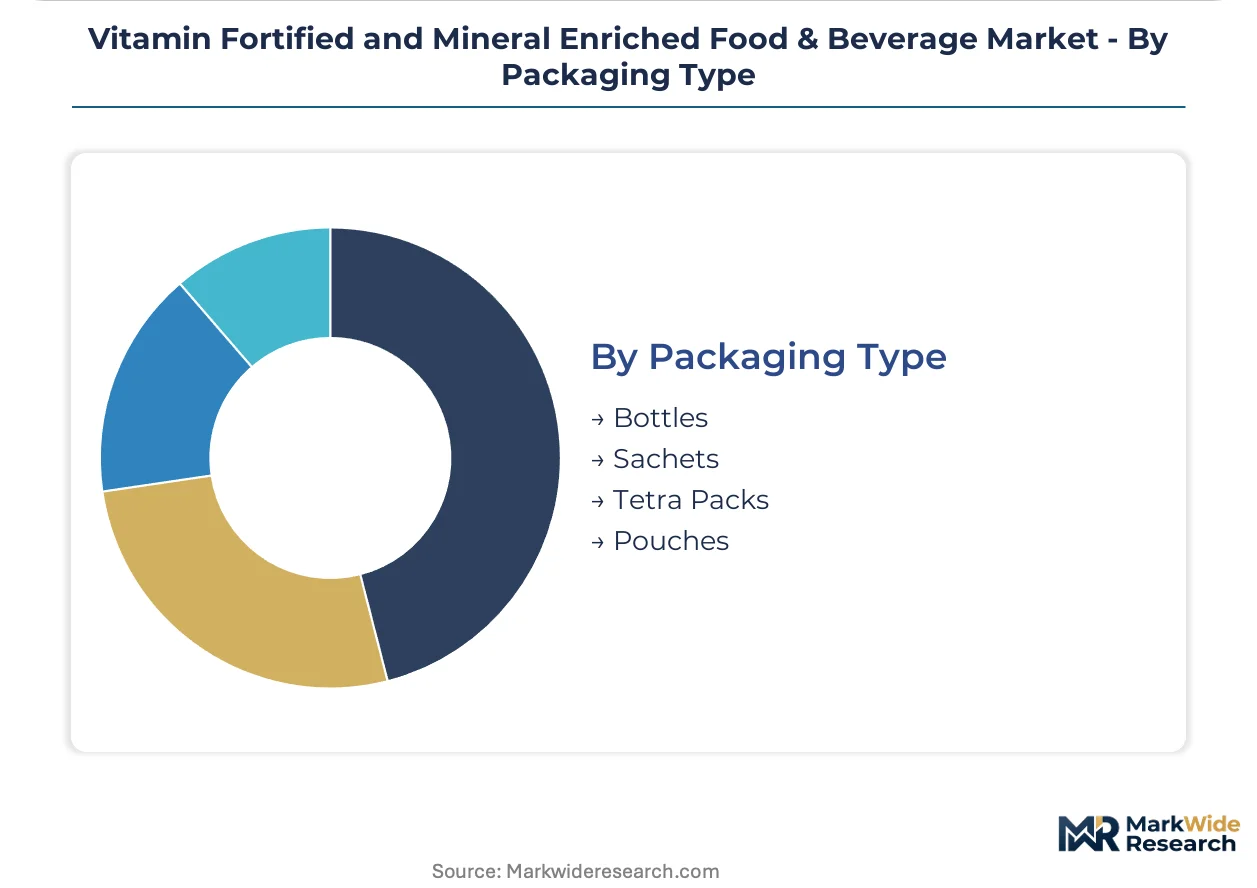
Packaging Type:
Packaging engineering directly determines oxygen barrier performance, light protection, and consumer portion control for bioactive stability.
- Bottles:PET and glass formats for beverages require UV-blocking additives to prevent riboflavin and vitamin A degradation. German and Japanese manufacturers specify multilayer barrier structures for ambient distribution.
- Tetra Paks:Aseptic carton systems enable shelf-stable liquid nutrition without refrigeration, critical for emerging market penetration.
- Sachets:Single-serve powder formats dominate supplement powders and fortified drink mixes.
- Pouches:Flexible stand-up formats reduce logistics cost for pureed and semi-liquid pediatric nutrition.
Bottles leads installed base today; Tetra Paks is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortified nutrition first achieved industrial scale in the United States during the 1940s, when wheat flour enrichment became mandatory to combat deficiency diseases. That regulatory precedent established the template for government-mandated micronutrient addition that now spans six continents.
United States
FDA's 21 CFR 101.54 governs nutrient content claims that manufacturers must navigate for cereal and dairy fortification. The agency's bioavailability substantiation requirements are tightening for pediatric formulations. Chicago and Minneapolis host the densest clusters of premix suppliers serving North American cereal and beverage manufacturers.
Germany
EFSA population reference intakes shape formulation targets for iron and vitamin D in functional dairy applications. The country's Federal Office of Consumer Protection and Food Safety enforces strict novel food assessments for bioactive ingredients. Bavaria's dairy processing corridor around Munich drives innovation in microencapsulated vitamin stability for extended shelf-life beverages.
India
FSSAI mandates fortification logos on packaged staples including wheat flour, rice, and edible oils, accelerating compliance investments by multinational suppliers. The regulator's dual certification requirements for imported premixes extend product launch timelines. Gujarat's food processing belt around Ahmedabad concentrates contract manufacturing for vitamin premix blending.
China
SAMR's national food safety standards specify permissible fortification levels across 16 micronutrient categories in liquid and solid formats. The regulator's 2023 revisions tightened documentation requirements for synthetic vitamin sources. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou dominate domestic production of infant formula fortification systems.
Brazil
ANVISA's fortification regulations mandate iron and folic acid addition to wheat and corn flours under national public health directives. The agency's bioequivalence requirements for mineral sources complicate premix sourcing from Asian suppliers. São Paulo state's dairy processing corridor anchors South America's largest functional beverage manufacturing base.
Vitamin Fortified and Mineral Enriched Food & Beverage Market Competitive Landscape
Premium-margin players sit above commodity-margin players across bioavailability engineering and clinical substantiation capabilities. The vendor base stratifies into three tiers: multinational nutrition conglomerates with dairy science infrastructure, beverage conglomerates with electrolyte formulation expertise, and specialty premix suppliers with microencapsulation patents. Consolidation pressures concentrate among mid-sized formulators lacking captive premix supply. Dominant competitive moves include backward integration into vitamin D and iron premix production, plus strategic partnerships with direct-to-consumer wellness platforms.
Within the clinical nutrition tier, Abbott Laboratories and Nestlé SA occupy positions defined by pediatric and geriatric formulation expertise. PepsiCo and The Coca-Cola Company exemplify beverage-centric archetypes prioritizing portable hydration formats with electrolyte-vitamin matrices. Amway Corporation represents the direct-to-consumer subscription model that is fragmenting traditional pharmacy distribution. Kellogg Company and Kellanova sit within the breakfast cereal fortification segment where thermal stability engineering determines competitive viability.
| Leading Market Players |
|---|
| Amway Corporation |
| Abbott Laboratories |
| Nestlé SA |
| Kellogg Company |
| The Hain Celestial Group, Inc. |
| PepsiCo, Inc. |
| Kellanova |
| Fulfil |
| The Coca-Cola Company |
| Others |
Pricing and Supply Chain Analysis
Health-conscious procurement of clinical-grade pediatric formulations in Germany and the United States is forcing manufacturers to absorb premium premix costs and recalibrate margin structures across functional dairy and nutritional beverage portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates fortified nutrition, with clinical substantiation and EFSA-compliant bioavailability engineering separating premium pediatric formulations from commodity-staple fortification. Price differentiation rests on certification tier and captive premix supply. Cost compression in standard-tier functional beverages is intensifying because clean-label substitution threatens shelf placement. Mass-market retailers exhibit highest price sensitivity; hospital and long-term care facilities show lowest.
Supply Chain Analysis
Single-source vulnerability sits with three specialty chemical suppliers controlling food-grade vitamin D and iron premix capacity. Manufacturing concentrates in Germany, India, and China. Raw material dependencies include vitamin A palmitate, microencapsulated iron, and lipid-based coating systems. Tariff exposure on imported premixes complicates dual certification timelines. Distribution runs through direct buyer relationships with supermarket chains and emerging direct-to-consumer wellness platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vitamin Fortified and Mineral Enriched Food & Beverage Market functions as a stable compounder, with mandatory fortification directives across India, Brazil, and EU member states generating predictable procurement baselines for compliant suppliers.
For Market Incumbents: Lock in backward integration into vitamin D and iron premix production to neutralize supply concentration risk from specialty chemical suppliers. Secure EFSA novel food dossier precedents for microencapsulated formats to extend product launch cycle advantages over mid-sized formulators lacking regulatory infrastructure. For New Entrants and Emerging Players: Direct-to-consumer wellness platforms offer the most penetrable channel entry point, particularly in the United States and United Kingdom where telehealth-adjacent nutrition counseling operates under permissive frameworks. Target sports hydration with electrolyte-vitamin matrices for athletes seeking portable alternatives to supplement powders, leveraging algorithm-driven personalization as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty premix suppliers holding microencapsulation patents and verified EU Green Deal supply chain traceability. Long-term viability favors acquisition targets with clinical-grade formulation capabilities spanning pediatric and geriatric nutrition segments. Monitor EFSA health claims substantiation rulings on cognitive function as the inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Production | Captive supply of vitamin D and iron reduces dependency on three dominant specialty chemical suppliers. |
| Microencapsulation Patent Acquisition | Thermal stability engineering for functional dairy applications extends permissible shelf life claims under FDA 21 CFR 101.54. |
| Direct-to-Consumer Platform Partnership | Algorithm-driven personalization bypasses conventional pharmacy distribution in United States and United Kingdom markets. |
| EFSA Novel Food Dossier Investment | Clinical substantiation for pediatric cognitive function claims creates 18-24 month launch cycle moats against mid-sized competitors. |
| EU Green Deal Supply Chain Certification | Verified traceability and reduced carbon footprint premix logistics secure first-mover advantage in sustainable sourcing requirements. |
Research Methodology
Direct dialogue with formulation scientists, regulatory affairs directors at multinational nutrition conglomerates, premix procurement managers, and pediatric nutrition brand managers anchored qualitative grounding. Secondary validation drew from FDA 21 CFR filings, EFSA health claims register entries, FSSAI fortification compliance notices, and customs records of food-grade vitamin imports. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling of functional foods, nutritional beverages, fortified snacks, and dietary supplements by bioavailability engineering tier, distribution channel, and end-user physiological vulnerability. CAGRs derived from regression analysis of historical premix pricing, regulatory compliance cost indices, and channel penetration rates for microencapsulated formats.
Revisions become necessary when EFSA substantiation requirements tighten beyond compositional data, when FSSAI expands mandatory fortification categories, or when clean-label substitution accelerates in premium retail channels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Vitamin D Market