
 Psyllium Products Market | 2026-2036
Psyllium Products Market Size, Share, and Industry Trends Forecast 2026-2036
Psyllium Products Market Outlook
Contract farming arrangements with advance payment structures is reconfiguring capital requirements for new entrants in psyllium processing. Satnam Psyllium Industries leverages captive cultivation across Saurashtra to secure husk supply consistency. Jyotindra International anchors export volumes through long-term offtake agreements with North American distributors. Premcem Gums Pvt. Ltd. differentiates via specialized milling equipment that achieves pharmaceutical-grade particle size.
Psyllium products derive from the seed husks of Plantago ovata, containing soluble fiber that forms a mucilaginous gel with water absorption capacity exceeding 50 times its dry weight, primarily serving laxative, cholesterol-management, and gluten-free binding applications. Psyllium husk dominates value capture due to premium pricing in pharmaceutical and nutraceutical channels, while psyllium capsules represent the fastest-growing product format as consumer preference shifts toward convenience dosing. Dietary supplements command the largest application share, though food additives are gaining traction as clean-label bakery formulators replace synthetic hydrocolloids.
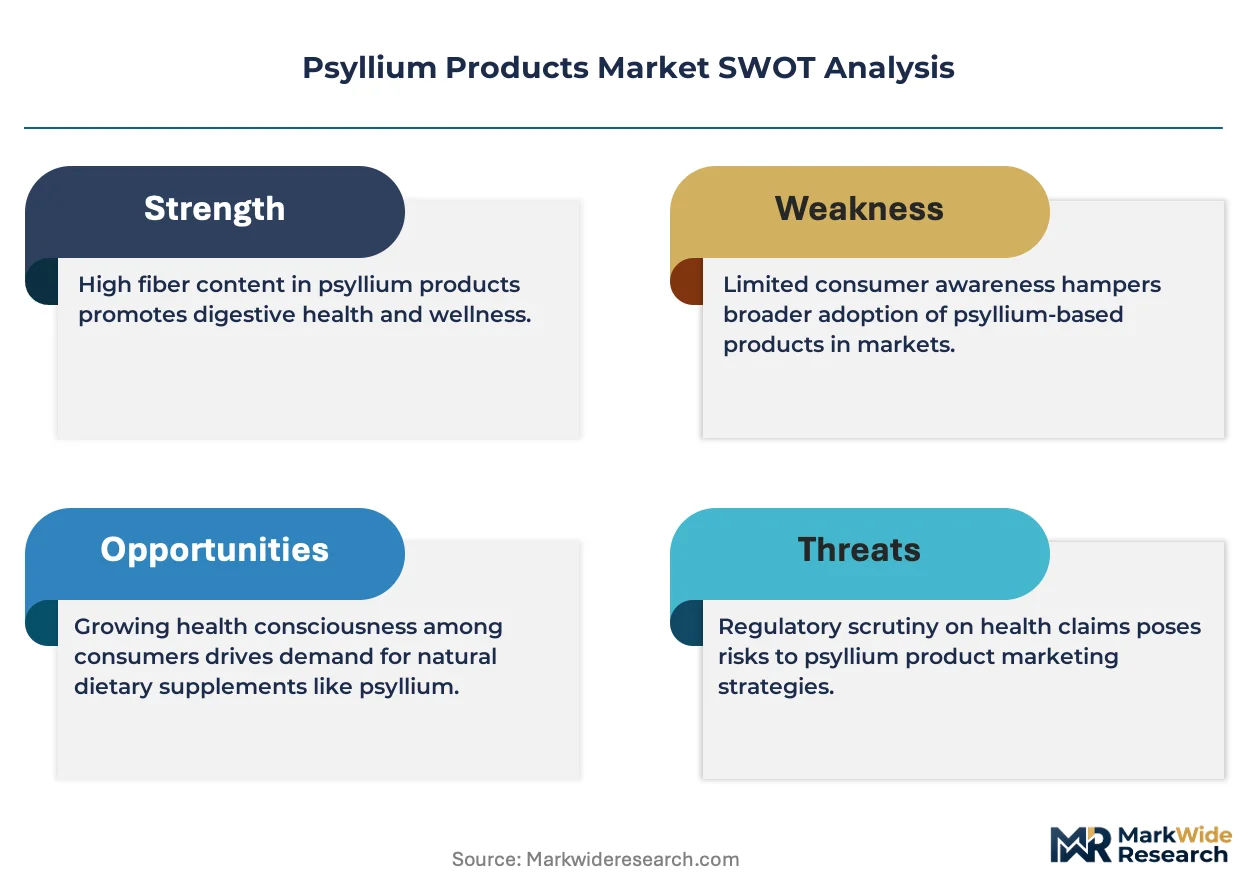
FSSAI regulations in India mandate microbial and heavy metal testing for psyllium exports, while FDA oversight in the United States requires New Dietary Ingredient notifications for novel psyllium-based formulations. ISO 22000 and HACCP certifications function as de facto market access requirements for European nutraceutical procurement teams. Stakeholders must monitor evolving fiber health claims frameworks in target jurisdictions to preempt reformulation cycles and label adjustment costs.
Market Dynamics
Contract farming networks in Gujarat and Rajasthan are consolidating raw husk supply under advance-payment structures, reconfiguring capital requirements for processing entrants and tightening quality control upstream.
Growth Catalysts
- FSSAI Purity Mandates:India's tightening dietary fiber benchmarks are forcing quality upgrades across export-oriented processing clusters, creating tiered market segmentation between pharmaceutical-grade and food-grade suppliers.
- Clean-Label Bakery Reformulation:Synthetic hydrocolloid displacement in gluten-free binding applications is pulling psyllium husk into industrial food additive channels at volume scales previously reserved for supplements.
- Soluble Fiber Health Claims:Cholesterol-management and digestive wellness positioning is expanding psyllium's addressable base beyond laxative categories into preventive nutraceutical portfolios.
Market Restraints
- Monocrop Concentration Risk:Over 80% of global Plantago ovata cultivation sits within 200 kilometers of Bhavnagar and Jodhpur, exposing supply chains to regional drought, pest outbreaks, and water table depletion.
- FDA NDI Notification Burden:Novel psyllium-based formulations require New Dietary Ingredient pre-market clearance, extending commercialization timelines and legal costs for functional food innovators.
- Synthetic Polymer Substitution:Methylcellulose and hydroxypropyl methylcellulose alternatives compete on price and processing consistency in industrial binding applications where clean-label premiums do not apply.
Strategic Opportunities
- Capsule Format Convenience Pivot:Consumer preference for portable, pre-measured dosing is displacing bulk powder sales in North American direct-to-consumer channels, commanding 40-60% price premiums per active gram.
- European ISO 22000 Certification Arbitrage:HACCP-compliant Indian processors can capture procurement preference from EU nutraceutical teams seeking audit-ready suppliers with documented heavy metal and microbial testing protocols.
- Microbiome Research Convergence:Prebiotic fiber positioning is virtualizing psyllium's brand identity from mechanical laxation to gut-brain axis modulation, opening formulation partnerships with synbiotic developers.
Industry Challenges
- Pharmaceutical-Grade Milling Expertise Scarcity:Particle size distribution specifications below 80 mesh require specialized equipment and operator training that concentrates in Saurashtra's established processing corridors.
- Heavy Metal Compliance Timeline Compression:FSSAI-mandated cadmium and lead testing protocols extend batch release cycles, tying up working capital in inventory awaiting laboratory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psyllium Products Market |
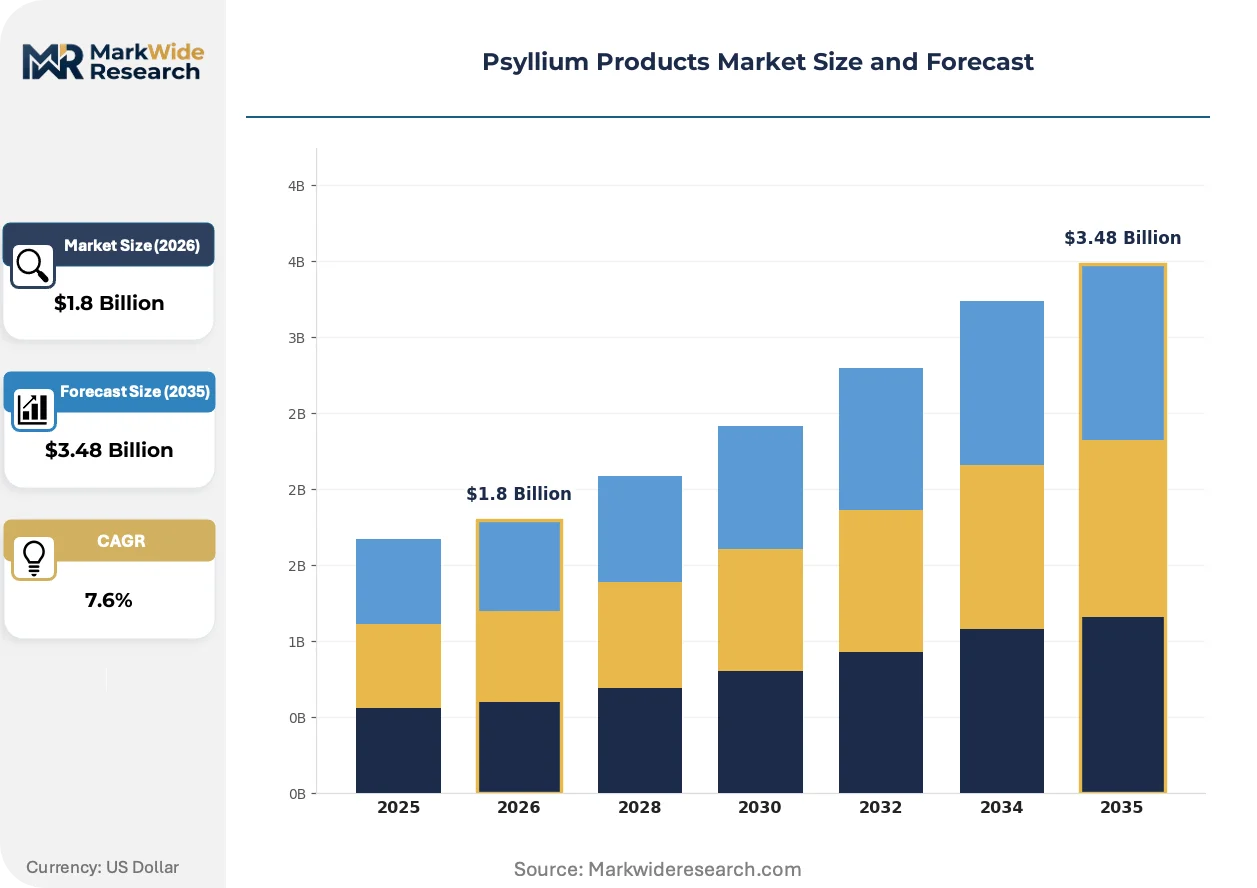
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psyllium Husk, Psyllium Powder, Psyllium Capsules, Psyllium Fiber Supplements Application: Dietary Supplements, Pharmaceuticals, Food Additives, Cosmetics End User: Healthcare Providers, Nutraceutical Companies, Food Manufacturers, Retail Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Satnam Psyllium Industries, Jyotindra International, Premcem Gums Pvt. Ltd., Shree Mahalaxmi Psyllium Pvt. Ltd., Abhyuday Industries, Keyur Industries, Gayatri Psyllium Industries, JYOT Overseas Pvt. Ltd., Rajganga Agro Product Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psyllium Products Market Strategic Shifts
Digital traceability platforms and precision agriculture tools are penetrating contract farming arrangements, while regulatory frameworks on both sides of the Atlantic harden documentation requirements for fiber health claims.
Near-infrared spectroscopy is virtualizing real-time moisture and purity assessment at farm-gate collection points. Large processors deploying handheld NIR units are compressing quality verification from days to minutes, enabling dynamic pricing tied to husk mucilage content rather than visual grading alone. This technology is virtualizing the traditional broker-mediated procurement model into direct farmer-processor relationships.
REACH registration requirements for novel psyllium derivatives entering EU cosmetic and pharmaceutical channels are forcing reformulation documentation that exceeds baseline food-grade specifications. ECHA substance evaluation timelines are extending product development cycles by 18-24 months for innovators seeking cross-category positioning. German and Dutch procurement teams are responding by consolidating supplier lists around pre-registered, fully dossiered raw material sources.
Subscription-based replenishment models are displacing pharmacy and health food store purchasing for chronic-condition consumers managing irritable bowel syndrome or cholesterol protocols. Direct-to-consumer platforms in the United States are capturing recurring revenue streams through algorithmic dosing reminders and auto-ship flexibility. This channel migration is most visible among 35-55 year-old urban professionals seeking discretion and convenience over in-person consultation.
Psyllium Products Market Segmentation
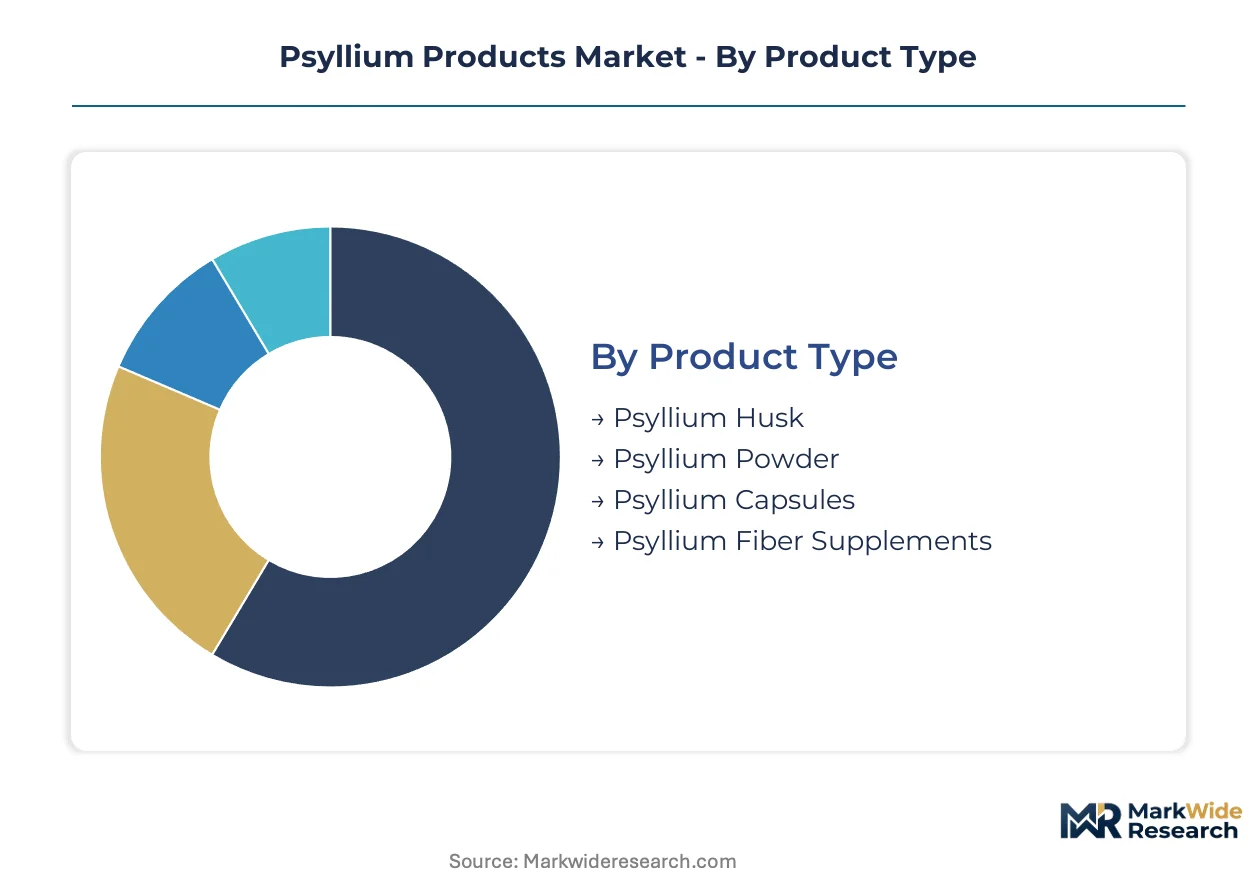
Psyllium product segmentation reflects divergent value capture across pharmaceutical purity grades and consumer convenience formats. Mature bulk categories compete on mucilage content specifications while emerging delivery systems command formulation premiums.
Product Type:
Mature formats dominate tonnage flows while emerging delivery systems reshape margin architecture.
- Psyllium Husk:Raw seed coat material containing 80-85% soluble fiber by dry weight, processed through mechanical dehulling and air classification. Pharmaceutical procurement in North America and Europe concentrates on 98%+ purity grades with heavy metal documentation under FDA and EMA frameworks. FSSAI-mandated microbial testing extends Indian export batch cycles.
- Psyllium Capsules:Pre-measured gelatin or vegetarian shell delivery containing 500-1000mg husk powder per unit. Direct-to-consumer subscription channels in the United States displace bulk powder purchases among IBS and cholesterol-management cohorts seeking portable dosing discretion.
- Psyllium Powder:Milled husk material passing 40-80 mesh screens for reconstitution in beverages or baking applications. Food manufacturers in Germany and the Netherlands source ISO 22000-certified powder for gluten-free binding reformulations.
- Psyllium Fiber Supplements:Blended formulations combining husk with probiotics, enzymes, or flavor masking agents. Functional positioning shifts toward prebiotic microbiome support under synbiotic research convergence.
Psyllium Husk retains volume leadership; Psyllium Capsules holds the steepest expansion curve.
Application:
Cost tier stratification separates premium pharmaceutical channels from commodity food additive placements.
- Dietary Supplements:Capsule, tablet, and powder formats positioned for digestive wellness and cholesterol management. US nutraceutical brands require FDA New Dietary Ingredient notifications for novel psyllium-probiotic combinations.
- Pharmaceuticals:Bulk laxative APIs and prescription fiber therapies meeting USP-NF monograph specifications. CDSCO registration requirements in India mandate stability testing for enteric-coated formulations.
- Food Additives:Clean-label hydrocolloid replacement in gluten-free bakery and meat analog applications. REACH-registered derivatives face ECHA substance evaluation timelines extending EU commercialization cycles.
- Cosmetics:Film-forming and moisture-binding agent in natural skincare emulsions. Limited penetration relative to food and pharmaceutical channels due to formulation compatibility constraints.
Dietary Supplements commands the largest revenue pool; Food Additives is climbing the fastest as industrial clean-label mandates accelerate.
End User:
Customer type fragmentation separates institutional procurement discipline from retail convenience preference.
- Nutraceutical Companies:Contract manufacturers and branded marketers sourcing pharmaceutical-grade husk for encapsulation and tableting. Long-term offtake agreements with Gujarat processors secure supply consistency.
- Food Manufacturers:Industrial bakery and plant-based meat formulators replacing methylcellulose with psyllium hydrocolloids. German and Dutch procurement teams prioritize HACCP-compliant suppliers with documented heavy metal protocols.
- Healthcare Providers:Hospital systems and clinical practices prescribing bulk-forming laxatives for constipation and IBS management. Reimbursement coding variations across US Medicare and private insurers influence prescribing patterns.
- Retail Consumers:Direct purchasers through e-commerce platforms and health food retailers. Algorithmic subscription models capture recurring revenue among urban professionals managing chronic conditions.
Retail Consumers represents the fastest-growing demand source; Nutraceutical Companies retains procurement volume leadership.
Distribution Channel:
Geography of sale determines margin retention and regulatory exposure intensity.
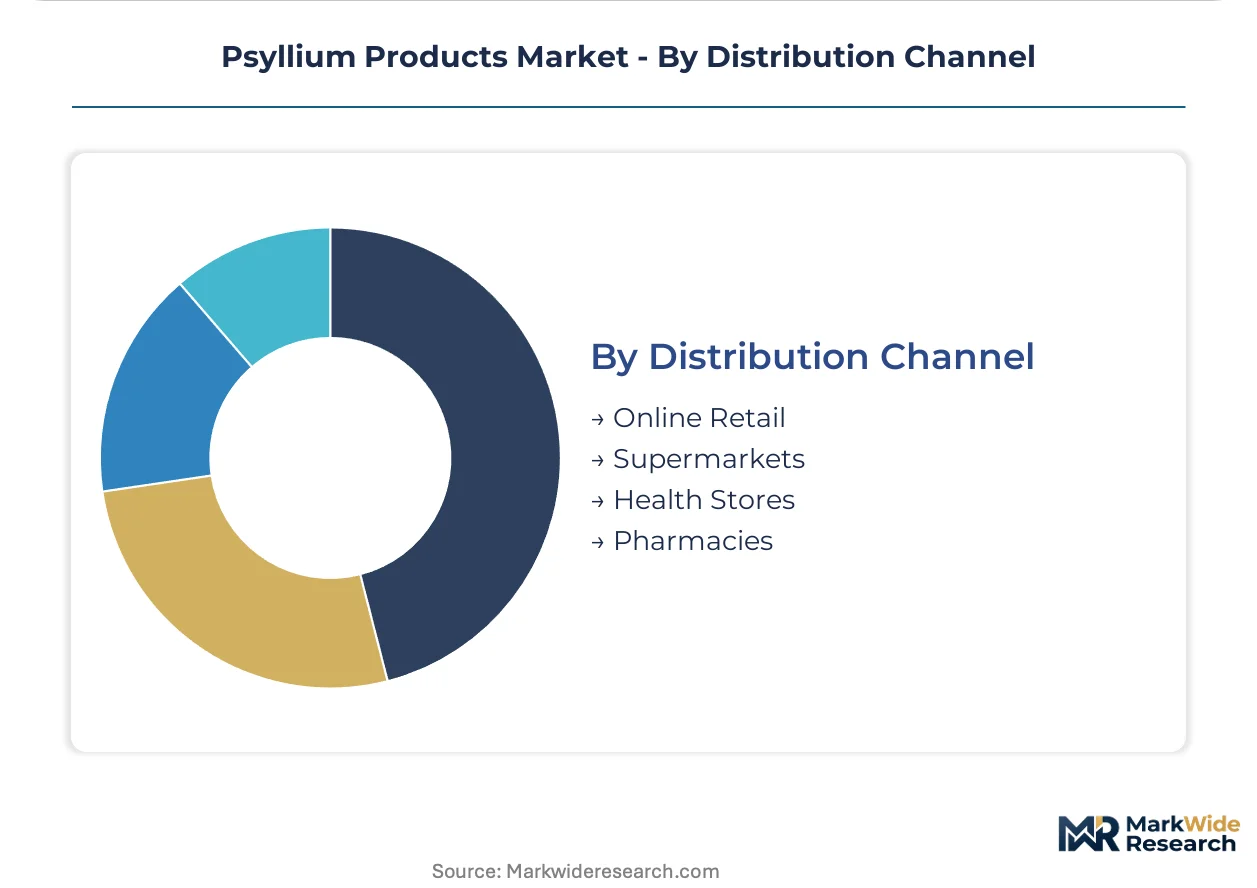
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing subscription-based replenishment. US-based algorithmic dosing reminders and auto-ship flexibility displace pharmacy purchasing among 35-55 year-old cohorts.
- Pharmacies:Brick-and-mortar drugstore chains and independent dispensaries stocking OTC fiber therapies. Pharmacist recommendation influence persists among first-time laxative purchasers seeking clinical validation.
- Health Stores:Specialized natural products retailers emphasizing organic certification and non-GMO positioning. Staff expertise drives premium product selection in European urban markets.
- Supermarkets:Mass-market grocery channels carrying private-label psyllium alongside branded supplements. Clean-label bakery ingredient placement in French and German retail chains expands food-grade penetration.
Supermarkets retains transaction volume leadership; Online Retail is expanding most quickly as subscription mechanics capture chronic-condition consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in psyllium products tilts heavily toward North American nutraceutical channels, where subscription-based direct-to-consumer models capture 40-60% premiums per active gram, while Indian export processors operate under FSSAI-mandated cost pressures that compress margins on pharmaceutical-grade batches.
United States
Direct-to-consumer subscription platforms and algorithmic dosing reminders now capture recurring revenue streams among 35-55 year-old urban professionals managing IBS and cholesterol protocols. FDA New Dietary Ingredient notifications extend commercialization timelines for novel psyllium-probiotic combinations. Processing demand concentrates in New Jersey and Pennsylvania nutraceutical corridors where contract manufacturers service branded marketers.
India
FSSAI purity mandates for dietary fiber exports are forcing quality upgrades across Gujarat and Rajasthan processing clusters, creating tiered segmentation between pharmaceutical-grade and food-grade suppliers. CDSCO registration requirements mandate stability testing for enteric-coated formulations entering domestic pharmacy channels. Bhavnagar and Jodhpur anchor raw husk supply through contract farming networks with advance-payment structures.
Germany
Clean-label bakery reformulation is pulling psyllium husk into industrial food additive channels at volume scales previously reserved for supplements. REACH registration requirements for novel derivatives force reformulation documentation exceeding baseline food-grade specifications. Cologne and Hamburg procurement teams consolidate supplier lists around pre-registered, fully dossiered raw material sources.
Netherlands
ISO 22000 and HACCP certifications function as de facto market access requirements for EU nutraceutical procurement teams seeking audit-ready Indian suppliers. ECHA substance evaluation timelines extend product development cycles by 18-24 months for innovators. Rotterdam distribution hubs channel pharmaceutical-grade powder into German and French manufacturing networks.
Canada
Health Canada oversight of natural health products requires site licensing for psyllium-based laxative formulations entering pharmacy channels. Prairie provinces host growing contract manufacturing capacity serving US cross-border demand. Toronto and Vancouver health food retailers emphasize organic certification positioning for premium husk products.
Psyllium Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream where milling expertise and purity certification create defensible positions. The psyllium processing sector exhibits moderate concentration around Saurashtra-based operators with captive cultivation or long-term offtake arrangements. Three archetypes dominate: vertically integrated processors controlling farm-gate supply, export-specialized traders anchoring North American distribution, and pharmaceutical-grade refiners investing in specialized particle-size equipment. Competitive intensity manifests through backward integration into contract farming and certification arbitrage targeting EU procurement standards.
Among Gujarat-based processors, Satnam Psyllium Industries, Jyotindra International, and Premcem Gums Pvt. Ltd. occupy distinct positioning within this tiered structure. Satnam exemplifies the captive-cultivation archetype through Saurashtra farming networks. Jyotindra represents export-volume leadership via North American distributor relationships. Premcem occupies the pharmaceutical-grade specialization tier where milling equipment achieves particle specifications below 80 mesh. These three entities collectively illustrate how supply security, channel anchoring, and technical differentiation segment competitive advantage in Indian psyllium processing.
| Leading Market Players |
|---|
| Satnam Psyllium Industries |
| Jyotindra International |
| Premcem Gums Pvt. Ltd. |
| Shree Mahalaxmi Psyllium Pvt. Ltd. |
| Abhyuday Industries |
| Keyur Industries |
| Gayatri Psyllium Industries |
| JYOT Overseas Pvt. Ltd. |
| Rajganga Agro Product Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Gujarat and Rajasthan contract farming networks supplying Plantago ovata raw husk anchor margin distribution toward pharmaceutical-grade processors with FSSAI certification and specialized milling capabilities, while uncertified food-grade suppliers compete on volume at compressed returns.
Pricing Analysis
Configured-to-order pharmaceutical-grade psyllium commands substantial premiums over standard food-grade powder through subscription-based direct-to-consumer channels. Three-tier pricing structure across pharmaceutical, nutraceutical, and industrial food additive levels separates buyers by certification stringency and particle size specifications. Cost compression in food-grade tiers is intensifying because synthetic hydrocolloid substitutes compete on processing consistency. Industrial bakery formulators exhibit highest price sensitivity; North American nutraceutical brands demonstrate lowest sensitivity due to health claim premiums.
Supply Chain Analysis
Plantago ovata seed feedstock draws from concentrated cultivation belts within Gujarat and Rajasthan states in India, with secondary sourcing from Pakistan and limited Afghan production. Raw husk, specialized dehulling equipment, and pharmaceutical-grade milling infrastructure constitute critical input dependencies. Single-source vulnerability around Bhavnagar-Jodhpur processing corridors exposes supply chains to regional drought and water table depletion. Distribution runs through Rotterdam hub-and-spoke networks into German and French manufacturing clusters, with direct-to-consumer platforms bypassing traditional pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where FSSAI purity mandates and FDA New Dietary Ingredient notification requirements create certification barriers that protect incumbent positions from commodity competition.
For Market Incumbents: Insulate pharmaceutical-grade positioning through captive cultivation expansion in Saurashtra and investment in sub-80 mesh particle milling equipment that emerging competitors cannot replicate. Synthetic polymer substitution in industrial binding applications threatens food-grade margin pools; channel control through long-term offtake agreements with North American distributors secures volume stability against price volatility. For New Entrants and Emerging Players: Mid-tier nutraceutical capsule manufacturing for European ISO 22000-certified procurement teams represents the most penetrable entry point where established players have underinvested in audit-ready documentation. Direct-to-consumer subscription mechanics for IBS and cholesterol-management cohorts offer a go-to-market angle bypassing incumbent distributor relationships through algorithmic dosing platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Gujarat processors holding FSSAI pharmaceutical-grade registrations and established North American distributor relationships. Five-to-ten year viability hinges on prebiotic microbiome research convergence sustaining premium positioning; the signal to watch is ECHA substance evaluation timeline compression for novel psyllium derivatives entering EU cosmetic channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Satnam Psyllium Industries leverages captive Saurashtra cultivation to secure husk supply consistency against regional drought risk. |
| Pharmaceutical-Grade Milling Equipment Investment | Premcem Gums achieves particle specifications below 80 mesh that food-grade competitors cannot replicate for API applications. |
| ISO 22000 Certification Arbitrage | Jyotindra International captures EU procurement preference through documented heavy metal and microbial testing protocols. |
| Direct-to-Consumer Subscription Launch | Algorithmic dosing reminders capture recurring revenue among 35-55 year-old urban professionals managing chronic conditions. |
| Synbiotic Formulation Partnership | Prebiotic fiber positioning opens collaboration channels with microbiome research developers beyond traditional laxative categories. |
Study Parameters
A standing panel of nutraceutical procurement managers, FSSAI regulatory consultants, Gujarat contract farming coordinators, and pharmaceutical formulation scientists provided ongoing calibration across primary fieldwork and secondary validation. FDA New Dietary Ingredient notification databases, ECHA REACH registration filings, FSSAI export certification records, and EU customs trade statistics supplied documentary anchors. Bottom-up volume modeling from processor capacity assessments triangulated against top-down demand aggregation from end-use industry consumption patterns.
Scenario-bracketing around drought severity, regulatory timeline compression, and synthetic substitution elasticity bounded projection ranges across the analysis window. Segmentation dimensions spanned product format, application purity grade, end-user procurement archetype, and regional regulatory cluster. CAGRs derived from log-linear trend fitting to historical trade flows and capacity expansion announcements. Near-infrared spectroscopy adoption curves and subscription platform penetration rates informed technology-disruption adjustments.
Stress conditions across monsoon failure frequency, cadmium testing protocol extensions, and methylcellulose price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions about FSSAI enforcement continuity and FDA notification backlog clearance that material regulatory shifts could revise. Cross-checking against Indian customs psyllium husk export volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Hen Egg White Protein Market
Ingredients
Sodium Caseinate Market
Ingredients
Edible Oils and Fats Market
Ingredients
Elecampane Root Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Guar Gum Market
Ingredients
Africa Fats and Oil Market
Ingredients
Yeast Flakes Market
Ingredients
Phytogenic Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Glucuronolactone Market
Ingredients
Synephrine Market