
 Soy Protein Ingredients Market | 2026-2036
Soy Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Protein Ingredients Market Intelligence
A shift from single-source contracts to multi-source procurement for non-GMO soy is rebalancing supply chain power. Archer Daniels Midland Company leverages its extensive global origination and processing network to manage price volatility. Cargill Incorporated competes on the basis of its wide portfolio of functional ingredients, including isolates and concentrates. DuPont specializes in high-value, functional soy proteins for specialized applications like infant nutrition.
Soy protein ingredients are derived from defatted soy flakes and processed to achieve specific protein concentrations, typically exceeding 50%. Their primary commercial purpose is to enhance nutritional value, improve texture, and provide emulsification in food and beverage products. Soy protein isolates, with the highest protein content, command premium pricing and are essential for sports nutrition and dairy alternatives. Textured soy protein represents the fastest-growing product segment, driven by its use as a primary component in meat alternatives.
The U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) enforce strict allergen labeling and define criteria for health claims on packaging. Simultaneously, market access into China is contingent upon adherence to GB standards for food additives, managed by the State Administration for Market Regulation (SAMR). Ingredient manufacturers must therefore balance investments in non-GMO supply chains against the cost of compliance with these varied international frameworks.
Market Dynamics
The central force shaping the soy protein ingredients market is the strategic realignment of supply chains toward verified non-GMO sources. This pivot, driven by regulatory pressures and consumer demand for transparency, is altering procurement power and forcing investment in segregated origination and processing infrastructure.
Growth Catalysts
- Meat Alternatives Expansion:The rapid growth of the meat alternatives sector, particularly in North America and Europe, creates sustained demand for textured soy protein and soy protein concentrates as primary structural and nutritional ingredients.
- Favorable Health Regulations:Health claims authorized by bodies like the U.S. Food and Drug Administration (FDA), linking soy protein consumption to reduced risk of heart disease, support its inclusion in functional foods and beverages.
- Food Processing Industrialization:Large-scale food processing industries in countries like the United States and Brazil drive high-volume demand for functional soy proteins to improve texture, emulsification, and nutritional content in mass-market products.
Market Restraints
- Input Price Volatility:Fluctuation in the price of non-GMO soybeans, driven by weather, agricultural policy, and global trade dynamics, creates margin pressure and complicates long-term contract pricing for ingredient manufacturers.
- Substitution from Other Plant Proteins:Competition from alternative plant proteins, such as pea, fava bean, and chickpea, is intensifying, especially in formulations targeting allergen-free claims or specific textural properties not easily achieved with soy.
- Allergen Labeling Complexity:Stringent allergen labeling mandates from regulators, including the EFSA in Europe, classify soy as a major allergen, which can limit its application in certain product categories and increases compliance costs for food producers.
Strategic Opportunities
- High-Purity Functional Isolates:Developing soy protein isolates with superior purity, solubility, and neutral flavor profiles opens opportunities in high-value segments like infant nutrition and clinical dietary products where specific functional properties are required.
- Fermentation Technology Integration:Applying fermentation processes to soy protein can enhance digestibility and mitigate off-flavors, addressing key consumer barriers and creating a new category of value-added ingredients for the food and beverage industry.
- Expansion in Southeast Asian Markets:Underpenetrated markets in Southeast Asia present significant growth potential as rising disposable incomes and urbanization fuel demand for convenient, protein-fortified processed foods, beverages, and dairy alternatives.
Industry Challenges
- Segregated Supply Chain Management:Establishing and maintaining fully segregated, identity-preserved supply chains for non-GMO soy from farm to processing facility presents a significant logistical and financial challenge, requiring substantial capital investment and rigorous oversight.
- Navigating Divergent Global Standards:Manufacturers face the operational burden of aligning product specifications with a complex web of international regulations, including China's GB standards, European food safety laws, and FDA requirements in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Protein Ingredients Market |
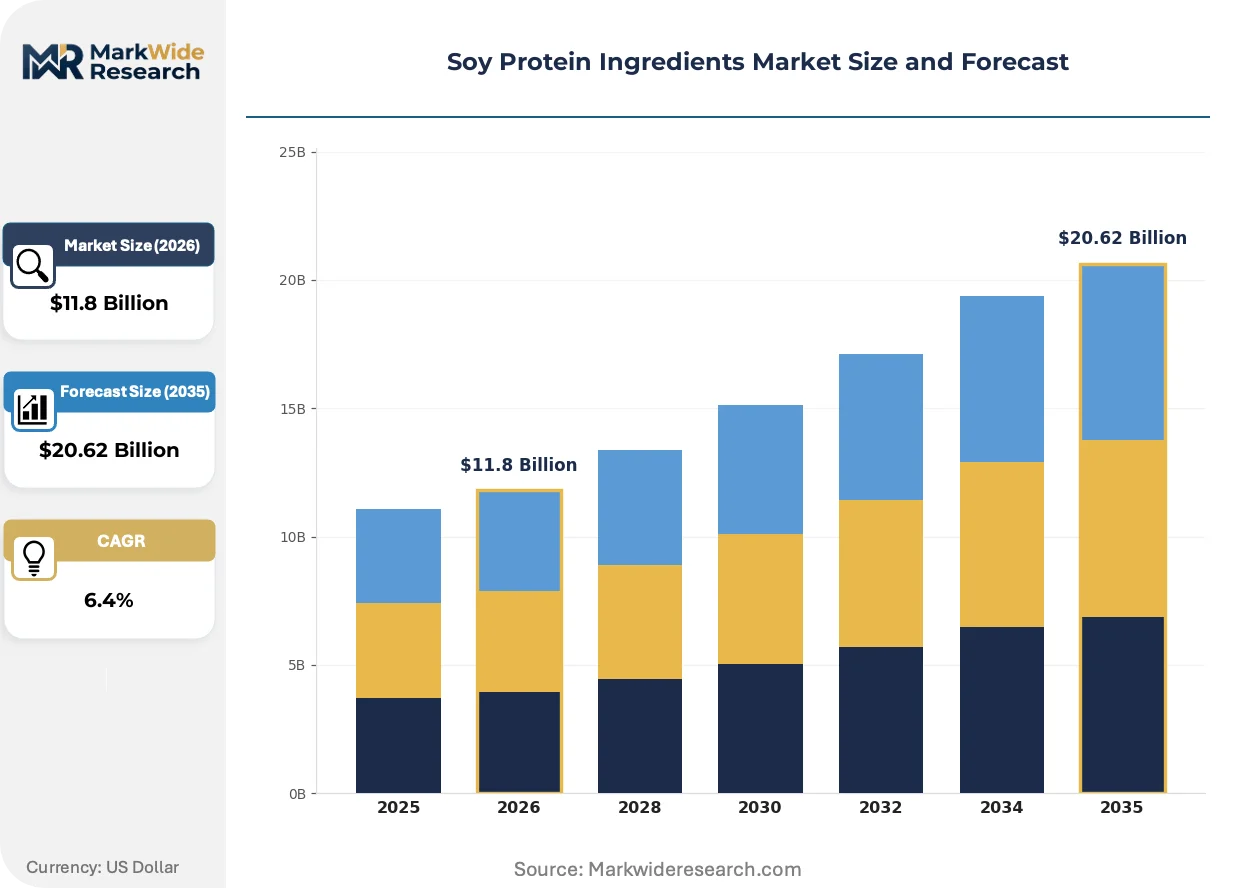
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein Isolate, Soy Protein Concentrate, Textured Soy Protein, Soy Flour Application: Meat Alternatives, Bakery Products, Dairy Alternatives, Sports Nutrition, Infant Nutrition End User: Food & Beverage Manufacturers, Nutraceutical Companies, Animal Feed Producers, Dietary Supplement Companies Form: Powder, Granules, Liquid, Chips |
| Companies Covered | Wilmar International Limited, Bunge Limited, Archer Daniels Midland Company, International Flavors & Fragrances Inc, Kerry Group plc, Cargill Incorporated, CHS Inc., The Scoular Company, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Protein Ingredients Market Strategic Shifts & Innovations
Functional performance and clean-label sourcing are the twin pressures reshaping product development. Innovation is now focused on enhancing the sensory properties and nutritional bioavailability of soy ingredients while simultaneously simplifying ingredient declarations and verifying supply chain integrity through certification.
High-moisture extrusion technology is a key process for creating fibrous, meat-like structures from soy protein concentrates and isolates. Food manufacturers in the plant-based meat sector are rapidly adopting this method to improve product quality. This texturization process is converging with advanced flavor-masking science to produce finished goods that more closely mimic the sensory experience of conventional meat.
China's national GB standards, enforced by the State Administration for Market Regulation (SAMR), set precise specifications for imported food ingredients. This framework dictates minimum protein levels, processing aid residues, and purity for soy proteins used in domestic food production. The infant formula and specialized nutrition segments are most affected, compelling ingredient suppliers to develop China-specific formulations to secure market access.
A notable shift in B2B purchasing behavior involves non-GMO project verification evolving from a premium attribute to a standard requirement. This change is disrupting the conventional market structure by compelling suppliers to invest in certified supply chains to remain competitive. The trend is most visible within the European food manufacturing sector, where retailer specifications and consumer expectations for clean-label products are particularly stringent.
Soy Protein Ingredients Market Segmentation
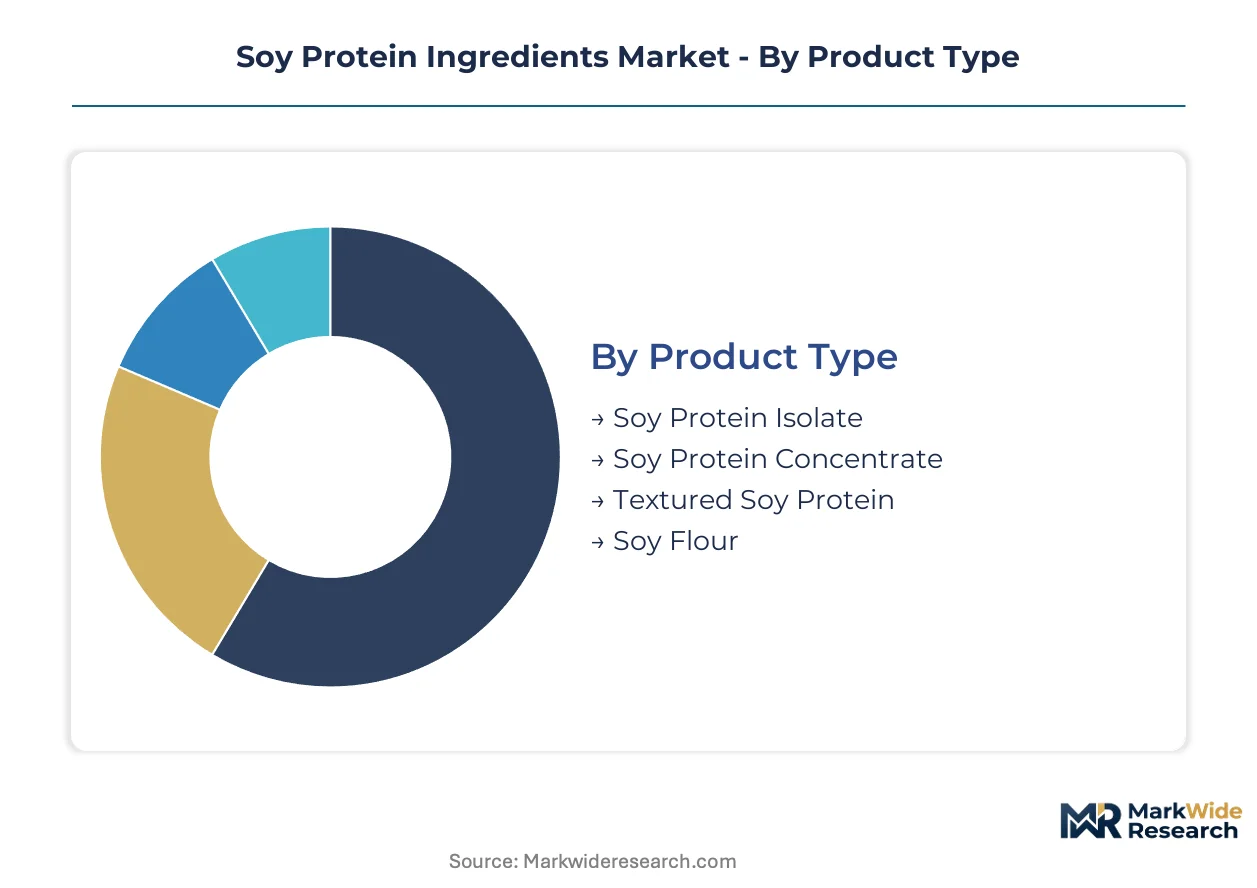
Understanding the distinct segments within the soy protein ingredients market reveals the specialized demands driving innovation and supply chain adjustments. Different product types cater to varied functional requirements, while diverse applications shape ingredient specifications. This granular view helps manufacturers align their offerings with specific industry needs and regulatory frameworks.
Product Type:
The functional specifications and processing methods define the various soy protein product types available to industrial buyers.
- Soy Protein Isolate:This highly refined soy protein contains at least 90% protein on a moisture-free basis, undergoing extensive purification to remove carbohydrates and fats. Demand for isolates is strong in sports nutrition and dairy alternatives, where high protein content and neutral flavor are critical.
- Textured Soy Protein:Produced through extrusion of soy flour or concentrate, textured soy protein offers a fibrous, meat-like structure. Its primary consumption is within the rapidly expanding meat alternatives sector, particularly in the United States and Brazil, for its textural and binding properties.
- Soy Protein Concentrate:This ingredient typically contains 65-70% protein, retaining some fiber and carbohydrates, and finds use in processed meats and baked goods.
- Soy Flour:Fine powder from ground, defatted soy flakes, soy flour provides protein enrichment and emulsification in bakery items and snacks.
Mature deployment sits with Soy Protein Concentrate. Newer deployment is concentrated in Textured Soy Protein.
Application:
Diverse food and beverage sectors integrate soy protein ingredients for their nutritional, textural, and functional benefits.
- Meat Alternatives:This segment uses soy proteins, especially textured soy protein, as a foundational ingredient to mimic the texture and nutritional profile of conventional meat products. Its expansion is a central driver for overall market growth, particularly in North America and Europe.
- Sports Nutrition:Soy protein isolates are key ingredients in protein powders, bars, and ready-to-drink beverages for athletes and active consumers. These products prioritize high protein content, digestibility, and muscle recovery benefits.
- Infant Nutrition:Specialized soy protein formulations provide essential amino acids for infants with dairy allergies or specific dietary needs.
- Dairy Alternatives:Soy proteins contribute to the creamy texture and protein content in plant-based milks, yogurts, and cheeses.
- Bakery Products:Soy flour and concentrates enhance protein content, moisture retention, and dough strength in breads, pastries, and snacks.
The meat alternatives sector is expanding most quickly, while infant nutrition demands highly specialized functional ingredients.
End User:
Different types of industrial customers procure soy protein ingredients based on their manufacturing processes and final product portfolios.
- Food & Beverage Manufacturers:These large-scale producers integrate soy proteins into a wide array of products, including processed foods, snacks, and beverages. Their demand spans all soy protein types, driven by cost-effectiveness and functional versatility.
- Nutraceutical Companies:These firms formulate health-oriented products, often using soy protein isolates for their high protein purity and functional properties. Their focus is on products supporting specific health outcomes, such as heart health or weight management.
- Dietary Supplement Companies:These companies utilize soy protein in various supplement forms, such as powders, capsules, and bars, targeting general wellness and specific nutritional gaps.
- Animal Feed Producers:Soy protein provides a cost-effective and high-quality protein source for livestock and aquaculture feeds, supporting animal growth and health.
Food & Beverage Manufacturers represent the largest volume segment, while Nutraceutical Companies drive demand for high-value isolates.
Form:
The physical form of soy protein ingredients dictates their handling, solubility, and integration into various manufacturing processes.
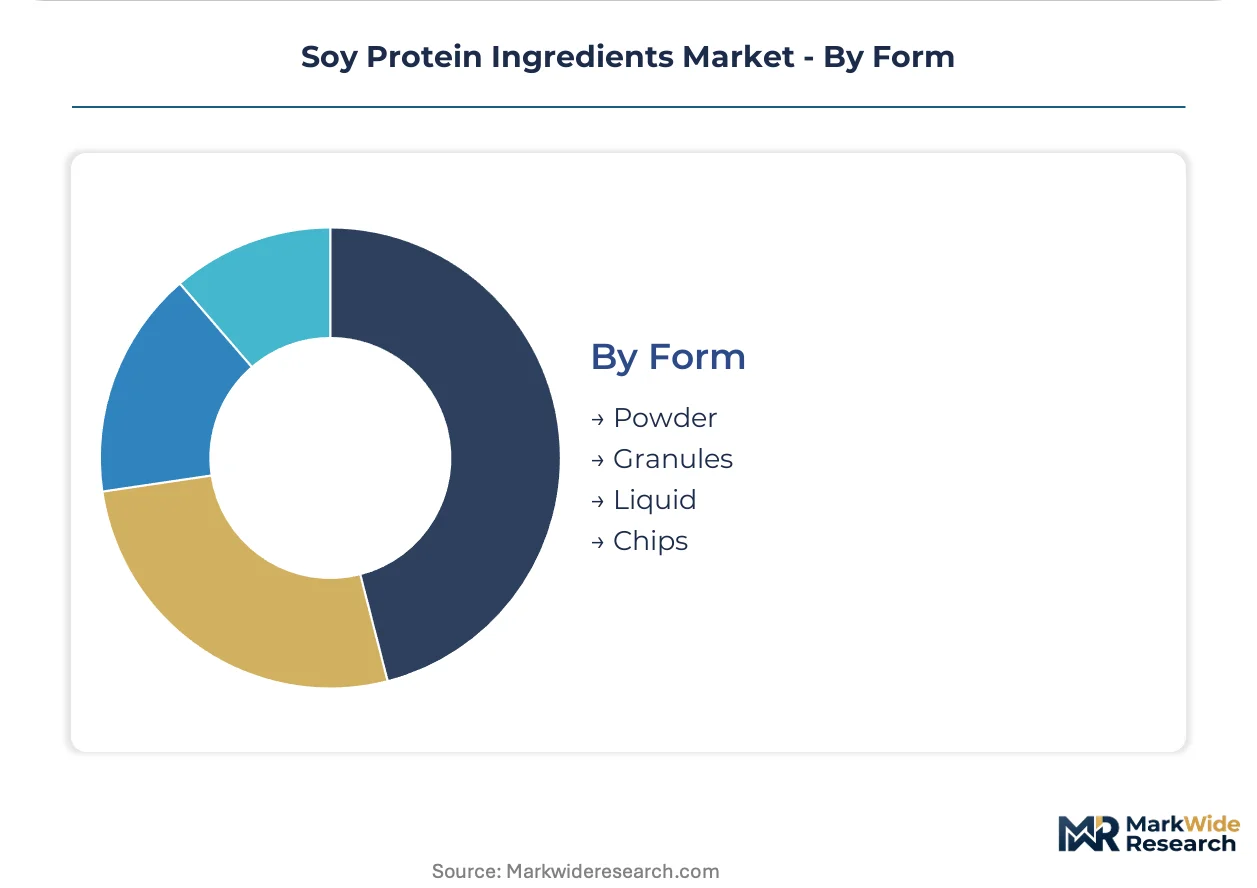
- Powder:This is the most common form, offering ease of blending and dispersion in beverages, protein mixes, and dry food formulations. Powdered soy proteins are highly versatile for industrial applications across multiple sectors.
- Granules:Granular forms, particularly textured soy protein granules, are crucial for meat alternative applications, providing bulk and chewiness. This form allows for hydration and expansion, mimicking ground meat textures.
- Liquid:Liquid soy protein formulations are used in ready-to-drink beverages and some processed food applications requiring specific viscosity.
- Chips:Soy protein chips offer textural elements and protein fortification in snack foods, cereals, and other convenience products.
Powdered forms offer the broadest applicability due to their ease of handling, while granules are critical for specific textural requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for soy protein ingredients is evident across major food processing hubs and regions with high plant-based food adoption. Established meat alternative markets and stringent food safety regulations drive significant ingredient procurement. This regional focus shapes supply chain strategies and product innovation.
United States
The United States market exhibits substantial demand for textured soy protein, driven by its expansive meat alternatives sector and sports nutrition products. The U.S. Food and Drug Administration (FDA) authorizes health claims. Food processing centers in the Midwest, particularly around Chicago, concentrate high-volume demand for functional soy proteins.
Brazil
Brazilian food processing industries generate strong demand for textured soy protein, integrating it into mass-market food products and meat alternatives. ANVISA regulations govern food additives and ingredient purity. The São Paulo region, a major food industry hub, sees significant investment in soy protein processing capabilities.
China
Market access into China depends on adherence to its stringent GB standards for food additives and ingredient purity. The State Administration for Market Regulation (SAMR) enforces these specifications for specialized nutrition. Food manufacturing clusters in the Yangtze River Delta actively seek China-specific soy protein formulations.
Germany
European consumer preferences for plant-based and clean-label products drive significant soy protein demand within Germany. The European Food Safety Authority (EFSA) mandates strict allergen labeling and non-GMO verification. Food manufacturers in North Rhine-Westphalia adopt high-moisture extrusion for meat alternative production.
India
Rising disposable incomes and urbanization in India fuel demand for protein-fortified processed foods and beverages. The Food Safety and Standards Authority of India (FSSAI) regulates ingredient standards and health claims. Manufacturers in Maharashtra are expanding their use of soy proteins in dairy alternatives and snacks.
Soy Protein Ingredients Market Key Industry Players
Investment in segregated supply chains dominates the current landscape, driven by regulatory pressures and consumer demand for non-GMO verification. The market structure is moderately consolidated, with a few large players controlling significant origination and processing capabilities. Strategic archetypes include global agricultural processors, specialized functional ingredient manufacturers, and regional commodity suppliers. Portfolio diversification into high-value isolates and geographic expansion into emerging markets are also key competitive moves.
At the scale-driven end, Archer Daniels Midland Company exemplifies players leveraging extensive global origination and processing networks to manage price volatility. Cargill Incorporated sits within the archetype of diversified agricultural giants, competing on its wide portfolio of functional ingredients. DuPont represents specialized manufacturers, focusing on high-value, functional soy proteins for demanding applications like infant nutrition. These firms anchor market stability through their integrated operations and commitment to regulatory compliance across varied international frameworks.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Bunge Limited |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc |
| Kerry Group plc |
| Cargill Incorporated |
| CHS Inc. |
| The Scoular Company |
| DuPont |
| Others |
Cost & Logistics Intelligence
Agricultural labor productivity in key non-GMO soy cultivation regions directly influences raw material costs, creating distinct pricing tiers for certified ingredients.
Pricing Analysis
Service bundling with technical support and formulation expertise differentiates premium soy protein offerings from commodity transactions. Pricing models span contract-based long-term offtake for isolates and transactional spot pricing for soy flour. Protein purity, non-GMO verification, and volume scale drive price differentiation. Input price volatility for non-GMO soybeans creates upward pressure, affecting price-sensitive Food & Beverage Manufacturers more than infant nutrition segments prioritizing quality.
Supply Chain Analysis
Regional distribution centers near major food processing hubs facilitate efficient delivery of soy protein ingredients. Global soy protein supply largely originates from the United States, Brazil, and China, relying on defatted soy flakes and processing enzymes. Managing fully segregated non-GMO supply chains from farm to processing facility presents a significant logistical and financial challenge. Downstream distribution primarily occurs direct-to-manufacturer, with suppliers managing specialized logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soy protein ingredients market currently operates under supply-constrained conditions, with specialized high-moisture extrusion capacity for textured proteins representing a key bottleneck propping pricing for advanced meat alternative ingredients.
For Market Incumbents:Extend non-GMO origination networks to secure long-term, identity-preserved supply, mitigating input price volatility and regulatory scrutiny. Invest in high-purity isolate R&D for infant nutrition and deepen vertical integration into specialized processing technologies like high-moisture extrusion. Competition from alternative plant proteins and stringent allergen labeling pose ongoing market challenges. Leverage existing global distribution channels to penetrate underpenetrated Southeast Asian markets.
For New Entrants and Emerging Players:Enter via niche functional segments demanding superior solubility and neutral flavor profiles, such as clinical dietary products. Focus on fermentation technologies to enhance digestibility and flavor masking for novel ingredient categories. The dairy alternatives sector offers a receptive entry point for innovative soy protein formulations. Partner with local food manufacturers to co-develop region-specific products aligning with local tastes and regulatory frameworks.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized functional ingredient manufacturers given sustained demand from the meat alternatives and infant nutrition sectors. The market demonstrates robust long-term viability, underpinned by evolving consumer preferences for plant-based diets and health-conscious products. Seek out mid-sized companies with proprietary processing technologies or established non-GMO supply chains. Monitor the pace of regulatory harmonization for non-GMO and allergen labeling across key global markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand High-Moisture Extrusion Capacity | Supports the rapid growth of the plant-based meat sector, improving textural mimicry. |
| Invest in Fermentation Technology R&D | Addresses off-flavors and digestibility concerns, opening new application avenues. |
| Secure Certified Non-GMO Supply Chains | Ensures compliance with stringent European and North American clean-label requirements. |
| Develop China-Specific Formulations | Facilitates market access and adherence to GB standards for specialized nutrition products. |
| Geographic Expansion into Southeast Asia | Captures demand from rising disposable incomes and urbanization in underpenetrated markets. |
Research Approach
European Food Safety Authority (EFSA) mandates, U.S. Food and Drug Administration (FDA) guidelines, and State Administration for Market Regulation (SAMR) GB standards formed the secondary backbone. Primary interviews with R&D directors, procurement leads, and supply chain managers supplemented secondary validation. Customs data, company annual reports, and academic literature provided additional data. Bottom-up segment assessment and top-down market validation ensured data integrity.
Historical trendline analysis established foundational growth trajectories for key product types and applications across the analysis window. The analytical framework modeled product type, application, end-user industry, and geographic region. Compound Annual Growth Rates derived from integrating volume growth, price evolution, and market penetration. Consumer dietary preferences and allergen labeling changes served as critical forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme commodity price volatility or regulatory shifts. Forecasts reflect assumptions about geopolitical stability and consumer demand. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
Astragalus Root Extract Market
Ingredients
Bean Pasta Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Passion Fruit Powder Market
Ingredients
Brewer's Yeast Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Oyster Shell Powder Market
Ingredients
Palm Mid-Fraction Market
Ingredients
L-Arabinose Market
Ingredients
Pea Starch Market
Ingredients
Europe Malt Extract Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Soybean Meal Market
Ingredients
Lupin Flour Market