
 Soy Hydrolysates Market | 2026-2036
Soy Hydrolysates Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Hydrolysates Market Analytics
Pea protein isolate is hardening as the benchmark against which soy hydrolysate suppliers must compete on cost and functionality. Archer Daniels Midland Company leverages its North American crushing footprint to sustain captive soy hydrolysate supply chains. Cargill, Incorporated anchors global foodservice relationships through specialized enzymatic hydrolysate portfolios. Kerry Group Plc differentiates via integrated flavor systems that embed soy hydrolysates into finished seasoning blends.
Soy hydrolysates are water-soluble protein mixtures produced by enzymatic, acid, or microbial breakdown of defatted soy meal, typically yielding peptides between 500 and 3000 daltons with degree of hydrolysis values from 4% to 20%. These hydrolysates function primarily as flavor precursors, nutritional fortifiers, and emulsifying agents across formulated food and feed systems. Enzymatic hydrolysates command premium positioning due to cleaner taste profiles and superior amino acid bioavailability compared with acid-hydrolyzed alternatives. Food & Beverage end users represent the dominant demand pool, though functional foods applications within this category are expanding fastest as sports nutrition and senior nutrition brands reformulate with plant-derived peptides. Spray-dried hydrolysates concentrate margin capture through extended shelf stability and reduced logistics costs relative to liquid concentrates.
FDA GRAS determinations and USDA organic certification requirements shape product development pathways for soy hydrolysate suppliers targeting North American food manufacturers. EFSA maximum residue limits for 3-MCPD and 1,3-DCP in hydrolyzed vegetable proteins impose strict process controls on European production facilities. China's SAMR national food safety standards for hydrolyzed plant proteins create additional compliance layers for exporters. Stakeholders must monitor evolving peptide-specific health claims regulations across jurisdictions to anticipate where formulation investments will unlock premium positioning.
Market Dynamics
Enzymatic hydrolysis technology is displacing acid-based processing as the dominant production pathway, driven by EFSA contaminant thresholds and clean-label procurement mandates from European flavor houses. This shift concentrates investment in purification infrastructure and peptide fractionation capabilities among suppliers seeking premium positioning.
Growth Catalysts
- EFSA 3-MCPD Limits:Tightened maximum residue thresholds for chloropropanols in hydrolyzed vegetable proteins are accelerating capital deployment toward enzymatic systems by European manufacturers seeking compliance advantage.
- Meat-Alternative Formulation:German startups and established plant-based brands are scaling soy hydrolysate offtake for umami depth and texture modulation in burger and sausage analogs.
- Senior Nutrition Reformulation:Functional food brands targeting sarcopenia prevention are embedding soy-derived peptides for amino acid bioavailability in ready-to-drink medical nutrition products.
Market Restraints
- Defatted Soy Meal Volatility:Crush margin compression at North American oilseed processors transmits directly to hydrolysate feedstock costs, squeezing mid-tier supplier margins.
- Pea Protein Substitution:Isolate and concentrate alternatives from yellow pea are capturing clean-label positioning in sports nutrition, forcing soy hydrolysate suppliers into price-competitive tenders.
- REACH Registration Burden:European chemical substance registration requirements for novel peptide fractions impose documentation costs that disadvantage smaller enzymatic hydrolysate producers.
Strategic Opportunities
- China SAMR Export Window:National food safety standard harmonization for hydrolyzed plant proteins creates compliance pathways for European suppliers into functional beverage and condiment manufacturing.
- Spray-Dried Format Premiumization:Extended shelf stability and reduced cold-chain dependency position dried hydrolysates for penetration into African and Southeast Asian seasoning markets.
- Flavor System Integration:Partnership models with seasoning blend houses allow hydrolysate suppliers to capture margin upstream through embedded ingredient positioning rather than commodity sales.
Industry Challenges
- Peptide Characterization Expertise Gap:Analytical chemistry talent capable of molecular weight distribution validation and bioactivity assay development commands premium compensation, constraining mid-scale facility expansion.
- Organic Certification Timelines:USDA National Organic Program accreditation for enzymatic processing requires 18-24 month verification cycles, delaying product launch schedules for North American clean-label contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Hydrolysates Market |
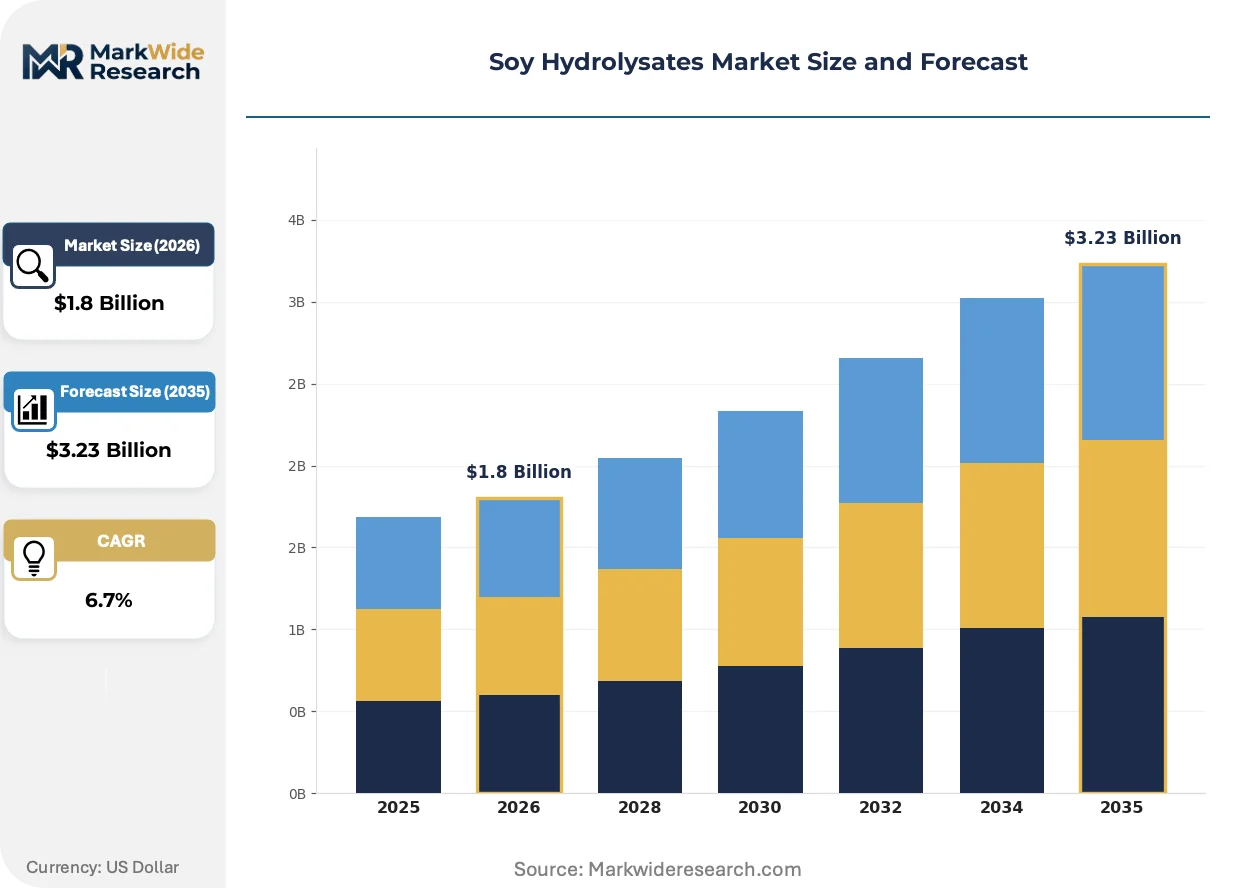
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Hydrolysates, Acid Hydrolysates, Fermented Hydrolysates, Spray-Dried Hydrolysates End User: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Feed Application: Food Flavoring, Nutritional Supplements, Personal Care Products, Functional Foods Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Bunge Limited, Wilmar International Limited, CHS Inc., Kerry Group Plc, DuPont Nutrition & Biosciences, Koninklijke FrieslandCampina N.V., Sojaprotein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Hydrolysates Market Evolving Landscape
Membrane filtration and precision enzymatic engineering are compressing production cycles while enabling peptide fractionation that was previously unattainable at commercial scale. These advances are redrawing competitive boundaries between commodity hydrolysate suppliers and specialized bioactive peptide producers.
Precision enzymatic engineering employing substrate-specific proteases is converging with membrane filtration sequences to yield narrow molecular weight distributions in the 500-1500 dalton range. Sports nutrition formulators in Germany and the Netherlands are specifying these fractions for rapid absorption claims. The technology is converging with clean-label positioning requirements to compress market share for acid-hydrolyzed alternatives in premium applications.
REACH authorization requirements for novel processing aids are forcing European suppliers to document enzymatic catalyst safety profiles through extended toxicological dossiers. Industrial consequence includes 12-18 month delays for new product introductions and elevated regulatory affairs staffing ratios. Small and mid-scale enzymatic hydrolysate producers in France and Italy are responding through shared-service compliance consortia to amortize registration costs.
Direct procurement contracts between hydrolysate manufacturers and meat-alternative brand technical teams are displacing traditional distributor-mediated supply relationships. German and Dutch plant-based protein startups are embedding supplier R&D personnel into formulation sprints, compressing development cycles from 18 months to 6 months. This pattern is most visible in Berlin and Amsterdam clusters where flavor houses and alternative protein brands co-locate technical facilities.
Soy Hydrolysates Market Segmentation
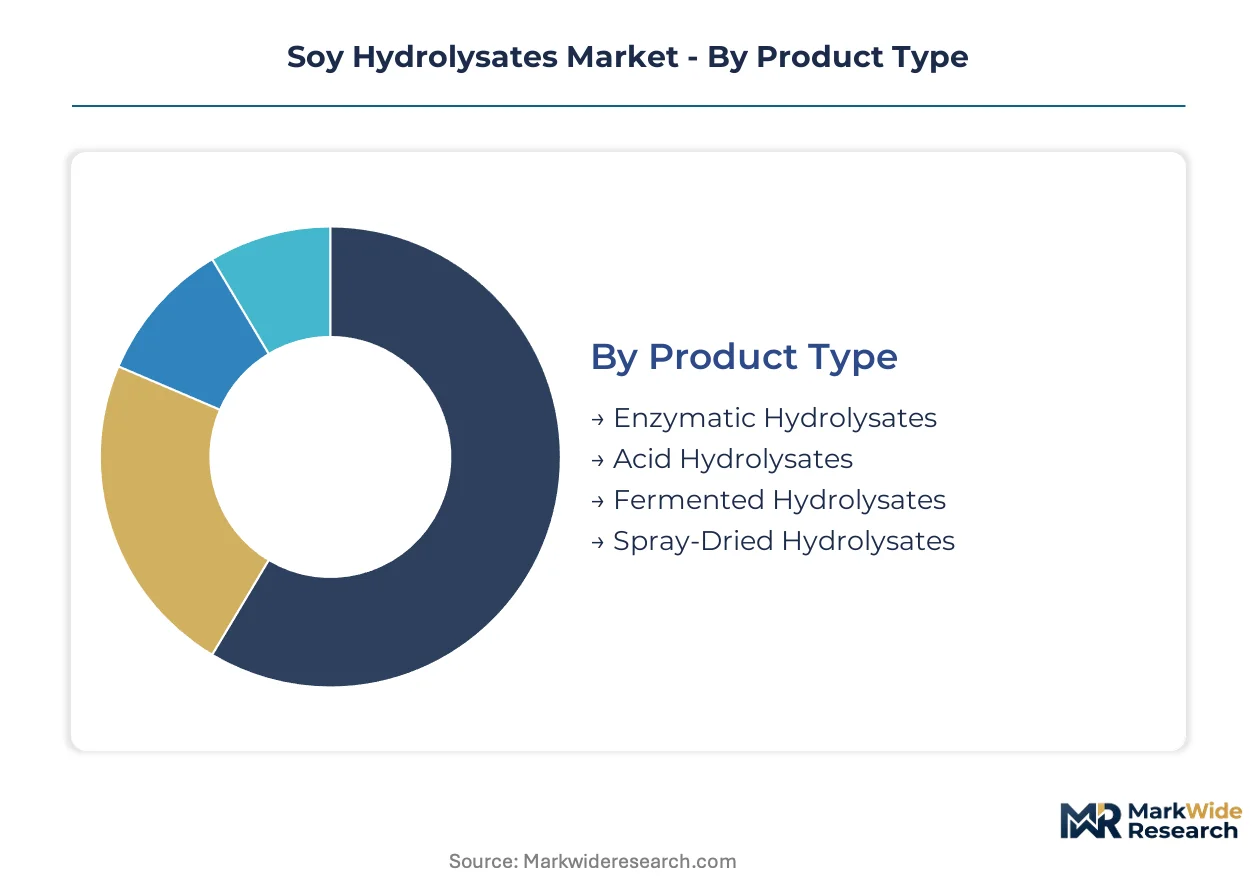
Soy hydrolysate procurement decisions hinge on regulatory alignment, with enzymatic variants commanding premium positioning under EFSA contaminant thresholds while acid-based alternatives face volume constraints. Understanding segment-specific certification burdens and end-use concentration patterns enables suppliers to optimize production allocation and margin capture.
Product Type:
EFSA maximum residue limits for 3-MCPD and 1,3-DCP apply differentially across production pathways, with enzymatic systems requiring peptide characterization dossiers under REACH while acid hydrolysates face outright prohibition in premium European flavor applications.
- Enzymatic Hydrolysates:These hydrolysates employ substrate-specific proteases yielding peptide distributions between 500 and 1500 daltons with degree of hydrolysis values from 4% to 10%. German meat-alternative startups and Dutch sports nutrition brands are concentrating procurement here for clean-label umami depth and rapid absorption claims. FDA GRAS determinations and EFSA safety dossiers constitute the dual certification burden for North American and European supply.
- Acid Hydrolysates:Hydrochloric acid-catalyzed breakdown produces broader molecular weight distributions with characteristic savory notes but elevated chloropropanol contamination risk. Demand concentrates in Asian condiment manufacturing where cost sensitivity outweighs clean-label positioning, though SAMR national food safety standards in China are tightening allowable limits.
- Fermented Hydrolysates:Microbial protease systems developed through solid-state fermentation yield distinctive flavor precursors with partial bioactive peptide retention.
- Spray-Dried Hydrolysates:Dehydrated powder formats eliminate cold-chain dependency and extend shelf stability to 24 months under ambient storage.
Leading the category by volume: Enzymatic Hydrolysates. Growing fastest: Spray-Dried Hydrolysates.
End User:
Customer procurement scale and technical sophistication vary sharply across end-use categories, with pharmaceutical and functional food buyers demanding batch-level peptide characterization that commodity food manufacturers rarely specify.
- Food & Beverage:Dominant demand pool encompassing flavor modulation, nutritional fortification, and texture engineering across processed foods, beverages, and meat alternatives. German and Dutch plant-based protein startups are embedding supplier R&D personnel into formulation sprints, compressing development cycles.
- Pharmaceuticals:Medical nutrition and sarcopenia prevention formulations require bioactive peptide fractions with validated molecular weight distributions and amino acid bioavailability data. Regulatory filing burdens include drug master files with FDA and clinical evidence packages for health claims.
- Cosmetics:Personal care applications leverage soy-derived peptides for moisturizing and anti-aging claims in topical formulations.
- Animal Feed:Aquaculture and pet food manufacturers utilize hydrolysates for palatability enhancement and protein supplementation in extruded feeds.
Highest margin capture: Pharmaceuticals. Steepest volume expansion: Food & Beverage.
Application:
Application-specific performance requirements dictate peptide fractionation depth and purification intensity, with flavoring applications tolerating broader molecular distributions than nutritional supplements demanding narrow bioactive ranges.
- Food Flavoring:Hydrolysates function as umami precursors and Maillard reaction substrates in savory seasonings, soups, and sauces. European flavor houses are specifying enzymatic variants to meet clean-label procurement mandates and EFSA contaminant thresholds.
- Nutritional Supplements:Sports nutrition and senior nutrition brands reformulate with plant-derived peptides targeting rapid absorption and sarcopenia prevention. Clinical validation requirements and peptide-specific health claims regulations shape supplier R&D investment.
- Personal Care Products:Cosmetic formulators incorporate hydrolysates for humectant and antioxidant properties in skin and hair care.
- Functional Foods:Medical nutrition and condition-specific formulations embed bioactive peptides for targeted physiological effects.
Deepest technical barriers: Nutritional Supplements. Broadest addressable base: Food Flavoring.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with direct sales dominating formulation-intensive applications while retail channels serve commodity repositioning.
- Online Retail:E-commerce platforms aggregate small-batch procurement from craft food manufacturers and independent cosmetic formulators, with limited technical support and standardized specifications.
- Specialty Stores:Ingredient distributors serving regional flavor houses and mid-tier food processors provide localized inventory and basic application guidance.
- Supermarkets:Mass-market retail captures consumer-facing nutritional supplement brands with simplified product positioning and price-competitive tenders.
- Direct Sales:Long-term supply agreements between hydrolysate manufacturers and meat-alternative brand technical teams are displacing traditional distributor relationships, with embedded R&D collaboration compressing development cycles.
Fastest channel shift: Direct Sales. Highest transaction frequency: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meat-alternative startups and Dutch sports nutrition brands are concentrating procurement of enzymatic hydrolysates, while Chinese condiment manufacturers sustain acid-hydrolysate demand despite tightening SAMR standards.
Germany
Berlin and Hamburg harbor Europe's densest cluster of plant-based protein startups, with Rofu and LikeMeat embedding supplier technical teams directly into formulation sprints. EFSA maximum residue limits for 3-MCPD and 1,3-DCP are forcing flavor houses in Frankfurt-Rhine-Main to specify enzymatic variants exclusively. The Baden-Württemberg region hosts specialized peptide fractionation facilities serving pharmaceutical-grade medical nutrition contracts.
United States
Sports nutrition brands in California and senior nutrition formulators in Florida are driving spray-dried hydrolysate procurement for extended shelf stability. FDA GRAS determinations and USDA National Organic Program requirements shape product development timelines, with 18-24 month accreditation cycles delaying clean-label launches. Chicago-based oilseed processors transmit crush margin volatility directly to hydrolysate feedstock costs.
China
Shanghai and Guangdong condiment manufacturers represent the largest remaining acid-hydrolysate demand pool, though SAMR national food safety standards are tightening allowable chloropropanol limits. Yangtze River Delta flavor houses are pivoting toward enzymatic systems to access European export markets. Domestic biotechnology firms in Zhejiang are developing solid-state fermentation capabilities for distinctive flavor precursor production.
Netherlands
Amsterdam and Rotterdam anchor direct procurement relationships between hydrolysate manufacturers and meat-alternative technical teams, compressing development cycles from 18 months to 6 months. REACH authorization requirements for novel processing aids are forcing 12-18 month delays for new enzymatic product introductions. Wageningen University partnerships supply analytical chemistry talent for peptide characterization and bioactivity assay development.
India
Maharashtra and Gujarat-based nutraceutical exporters are targeting SAMR-compliant hydrolysate production for Chinese functional beverage markets. FSSAI food safety regulations and BIS standards create dual compliance layers for domestic and export-oriented production. Mumbai specialty chemical distributors are building peptide fractionation capabilities to serve regional pharmaceutical formulation demand.
Soy Hydrolysates Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated agribusinesses dominating commodity hydrolysate supply and enzymatic specialists capturing premium positioning. Three archetypes define competitive structure: North American oilseed majors with captive crushing infrastructure, European flavor-system integrators with embedded hydrolysate portfolios, and Asian plantation-to-processing conglomerates with cost-advantaged acid-hydrolysate output. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct technical collaboration agreements displacing traditional distributor relationships in formulation-intensive applications.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill, Incorporated exemplify North American players leveraging crushing footprint control over feedstock supply. Kerry Group Plc occupies a position among European flavor-system specialists, embedding hydrolysates into finished seasoning blends rather than commodity ingredient sales. These three entities represent divergent strategic postures: upstream resource control versus downstream formulation integration versus hybrid models spanning both vectors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Bunge Limited |
| Wilmar International Limited |
| CHS Inc. |
| Kerry Group Plc |
| DuPont Nutrition & Biosciences |
| Koninklijke FrieslandCampina N.V. |
| Sojaprotein |
| Others |
Value Network & Pricing Analysis
German meat-alternative startups and Dutch sports nutrition brands concentrate procurement power in enzymatic hydrolysate tiers, anchoring contract-based long-term offtake as the dominant pricing model across premium applications. This buyer concentration compresses spot-market liquidity and transmits formulation-specific technical requirements directly into supplier margin structures.
Pricing Analysis
Volume concentrates in acid-hydrolysate tiers serving Asian condiment manufacturers, while margin capture clusters in enzymatic fractions for European clean-label applications. Three-tier pricing structure across premium enzymatic, standard food-grade, and economy acid-hydrolyzed levels separates certification-burdened European supply from cost-optimized Asian output. Pricing pressure stems from pea protein substitution in sports nutrition, forcing soy hydrolysate suppliers into price-competitive tenders for mid-tier contracts. Commodity food manufacturers exhibit highest price sensitivity, while pharmaceutical-grade buyers prioritize batch-level peptide characterization over unit cost.
Supply Chain Analysis
Freight cost differentials between spray-dried powder and liquid concentrate formats reshape procurement geography, with dried hydrolysates penetrating African and Southeast Asian seasoning markets previously inaccessible to cold-chain-dependent supply. Production concentrates in the United States, Germany, and China, with North American oilseed processors leveraging captive crushing infrastructure for feedstock cost control. Supply chain risk centers on defatted soy meal volatility transmitting crush margin compression directly to hydrolysate input costs. Distribution runs through direct technical collaboration agreements displacing traditional distributor relationships in formulation-intensive meat-alternative and pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry talent scarcity for peptide characterization and bioactivity assay development constrains mid-scale facility expansion, propping pricing power for incumbents with validated molecular weight distribution capabilities.
For Market Incumbents: Cement defensive positioning through backward integration into North American crushing infrastructure to insulate feedstock costs from oilseed processor margin volatility. Prioritize EFSA-compliant enzymatic capacity additions in Baden-Württemberg to capture pharmaceutical-grade medical nutrition contracts. Lock in direct procurement relationships with Berlin and Amsterdam plant-based protein startups before peptide fractionation expertise gaps close. For New Entrants and Emerging Players: Begin with spray-dried format production targeting African and Southeast Asian seasoning markets where cold-chain limitations exclude incumbent liquid concentrate suppliers. White-space opportunity concentrates in SAMR-compliant hydrolysate exports from India to Chinese functional beverage manufacturers. Go-to-market angle should leverage solid-state fermentation capabilities for distinctive flavor precursors in Yangtze River Delta condiment houses. For Investors and Strategic Acquirers: The window for entry favors specialized enzymatic hydrolysate producers with validated peptide fractionation capabilities and existing EFSA safety dossiers. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Target acquisition archetype: mid-cap European enzymatic specialists with REACH-registered processing aids and embedded R&D relationships with meat-alternative brands. Signal to watch: FDA GRAS determination timelines for novel peptide-specific health claims indicating where formulation investments will unlock premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Fractionation Capacity Expansion | Baden-Württemberg facilities capture pharmaceutical-grade medical nutrition contracts requiring validated molecular weight distributions. |
| Backward Integration into Crushing Infrastructure | North American oilseed processor partnerships insulate enzymatic hydrolysate margins from defatted soy meal price volatility. |
| EFSA Safety Dossier Investment | REACH-registered enzymatic catalyst profiles unlock premium positioning in European flavor house procurement. |
| Spray-Dried Format Production Scale-Up | Ambient-stable powder formats penetrate African and Southeast Asian seasoning markets beyond cold-chain limitations. |
| Direct Technical Collaboration Agreements | Berlin and Amsterdam meat-alternative startups compress development cycles from eighteen months to six months through embedded R&D. |
Research Methodology
Trade databases, EFSA contaminant threshold filings, and SAMR national food safety standards formed the secondary backbone, cross-referenced against primary interviews with enzymatic hydrolysate plant managers, European flavor house procurement leads, sports nutrition brand formulators, and pharmaceutical peptide characterization specialists. Bottom-up and top-down triangulation validated production capacity estimates against customs records and oilseed processor crush margin disclosures.
Bottom-up modeling anchored volume projections in segment-specific peptide fractionation capacity and degree of hydrolysis specifications across enzymatic, acid, and fermented production pathways. Top-down constraints incorporated EFSA regulatory cluster adoption curves and FDA GRAS determination timelines. CAGRs derived from elasticity-adjusted price-volume relationships across food flavoring, nutritional supplements, and pharmaceutical applications, with spray-dried format penetration serving as a key cross-segment growth amplifier throughout the projection horizon.
Underlying measurement precision varies by segment; pharmaceutical-grade hydrolysates with validated bioactive peptide fractions carry tighter precision than commodity acid-hydrolysate volumes in Asian condiment manufacturing. Forecasts reflect assumptions regarding EFSA enforcement consistency, enzymatic catalyst registration timelines, and pea protein substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fresh Yeast Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Caramel Ingredient Market
Ingredients
Konjac Flour Market
Ingredients
Icing Shortening Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Kairomones Market
Ingredients
Resistant Starch Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
PHO Oils Market
Ingredients
Agar Agar Flakes Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Gluten-Free Flour Market