
 Pet Food Ingredients Market | 2026-2036
Pet Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Ingredients Market Analysis
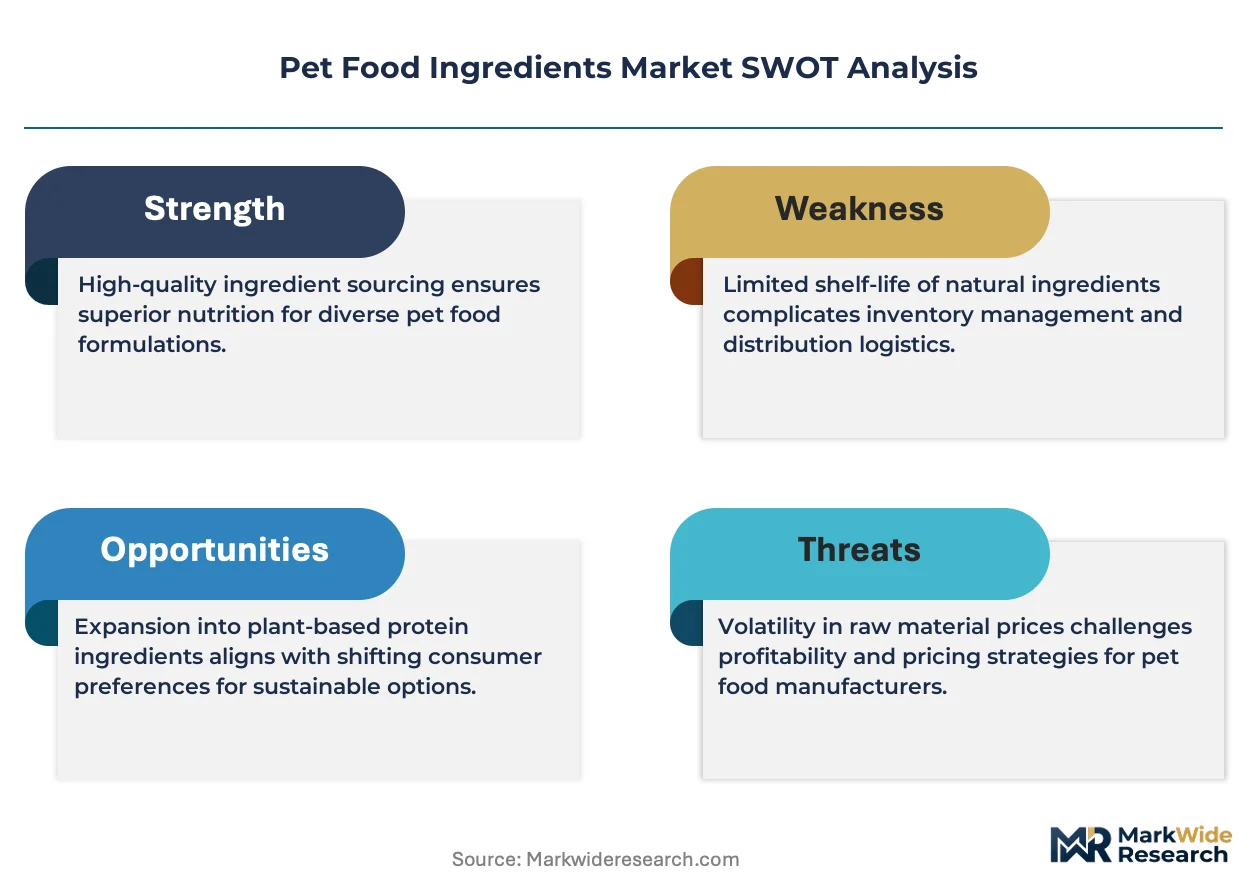
Thailand's expanding aquaculture-grade protein processing infrastructure is reconfiguring supply routes for premium fish-based ingredients entering Western markets. Cargill Incorporated leverages its integrated oilseed and animal protein platforms to control input costs across multiple ingredient categories. Darling Ingredients anchors North American rendering capacity, converting food industry by-products into standardized pet food proteins and fats. BASF SE competes through synthetic vitamin and carotenoid premixes that sustain nutritional consistency in large-scale formulation.
Pet food ingredients encompass the formulated raw inputs—proteins, carbohydrates, lipids, vitamins, minerals, and functional additives—that are combined, extruded, or retorted to produce nutritionally complete feeds for companion animals, with specifications typically requiring minimum crude protein of 18-22% for adult maintenance and digestibility coefficients exceeding 80% for premium positioning. Animal-based proteins occupy the dominant margin pool due to palatability premiums and amino acid completeness, while plant-based alternatives are gaining formulation share as price-sensitive brands navigate input volatility. Additives represent the fastest-growing structural segment, driven by probiotic, omega-3, and joint-health functional claims that command per-kilogram value multiples over base nutrients.
The FDA's Food Safety Modernization Act preventive controls for animal food, coupled with AAFCO nutrient profiles and state-level feed inspection regimes, create layered compliance thresholds that filter smaller suppliers and favor documented traceability systems. In Europe, the EU Feed Hygiene Regulation and FEDIAF nutritional guidelines impose parallel standards that shape export-oriented ingredient specifications. Stakeholders must monitor evolving regulatory divergence between jurisdictions to avoid reformulation costs and market access friction.
Market Dynamics
The FDA's Food Safety Modernization Act preventive controls are compressing supplier qualification timelines while concentrating procurement among vertically integrated renderers and oilseed processors with documented traceability infrastructure.
Growth Catalysts
- FSMA Preventive Controls:The FDA's mandatory hazard analysis and risk-based preventive controls for animal food are filtering smaller ingredient suppliers and consolidating volume among qualified processors with validated food safety plans.
- Humanization of Pet Nutrition:Pet owners are applying human dietary preferences to companion animal formulations, accelerating demand for clean-label proteins, grain-free carbohydrates, and functional additives previously confined to human food.
- Midwest Rendering Cluster Concentration:Illinois, Iowa, and Nebraska host the densest concentration of USDA-inspected rendering facilities, creating input cost advantages for regional pet food manufacturers sourcing standardized animal proteins and fats.
Market Restraints
- Animal Protein Input Volatility:Rendering yields fluctuate with livestock processing volumes and food industry by-product availability, creating margin pressure for formulators dependent on standardized poultry meal and porcine plasma.
- Thailand-to-Western Supply Route Concentration:Premium aquaculture-grade fish proteins increasingly route through Bangkok and Samut Sakhon processing zones, exposing buyers to port congestion and cold-chain integrity risks.
- AAFCO Nutrient Profile Rigidity:The Association of American Feed Control Officials' model regulations for complete and balanced claims restrict novel ingredient incorporation until feeding trials or nutrient database validation is completed.
Strategic Opportunities
- Cellular Agriculture Proteins:Cultivated meat and precision fermentation-derived proteins offer pathway to bypass rendering capacity constraints and appeal to sustainability-positioned premium brands.
- Veterinary Therapeutic Nutrition:Prescription diet formulations for renal, diabetic, and gastrointestinal conditions command per-kilogram premiums and require clinical validation that creates formulation stickiness.
- IRA Clean Energy Tax Credits:The Inflation Reduction Act's biofuel and biogas incentives are redirecting animal fats toward renewable diesel, potentially tightening pet food lipid supply and rewarding backward-integrated processors.
Industry Challenges
- Traceability System Integration:FSMA's enhanced record-keeping requirements demand lot-level tracking from raw material receipt through finished product distribution, straining legacy ERP systems at mid-tier formulators.
- Novel Ingredient GRAS Determination:FDA Generally Recognized as Safe self-affirmation timelines for postbiotic compounds and alternative proteins extend 18-36 months, delaying product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Ingredients Market |
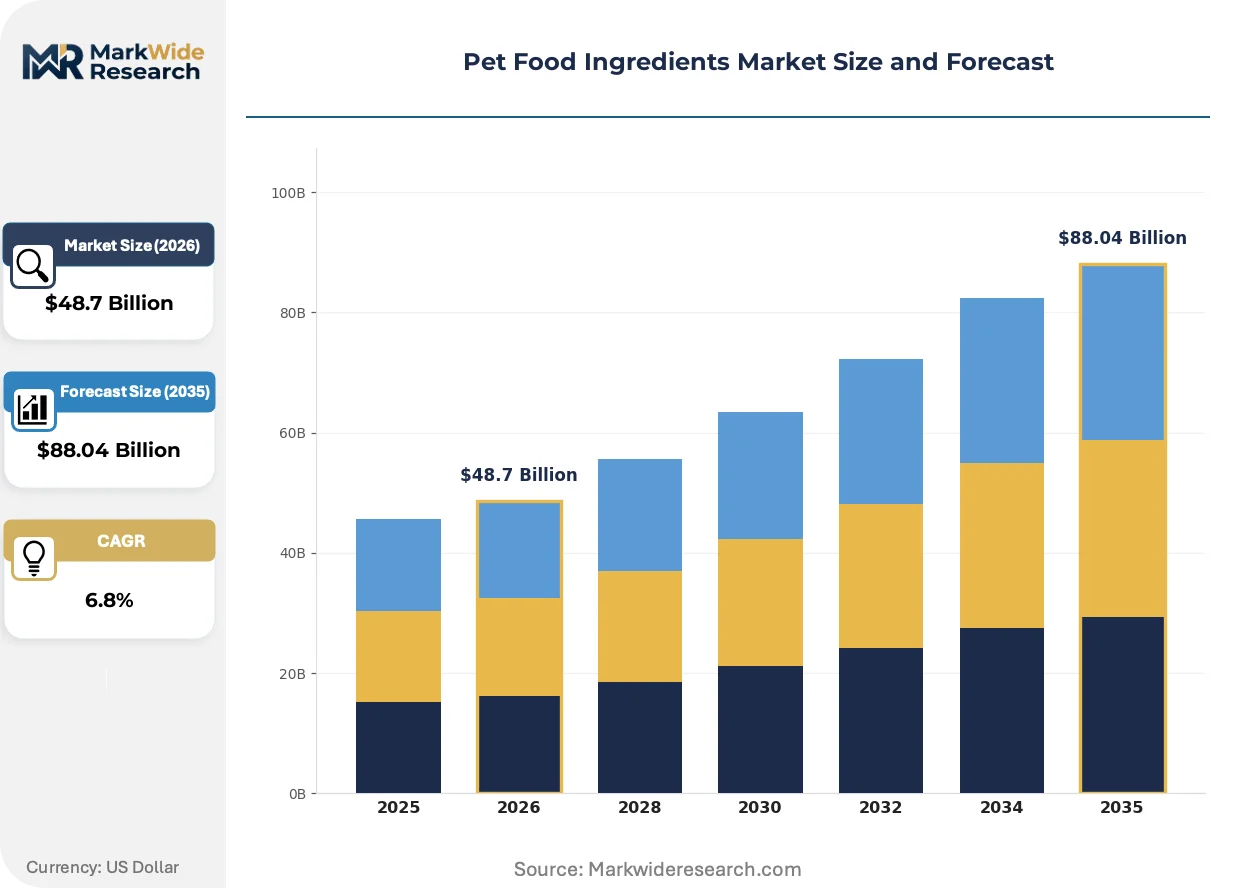
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Proteins, Carbohydrates, Fats, Additives Source: Animal-based, Plant-based, Synthetic, By-products Form: Dry, Wet, Semi-moist, Freeze-dried Target Animal: Dogs, Cats, Birds, Fish |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Darling Ingredients, BASF SE, Koninklijke DSM N.V., Symrise AG, Tyson Foods, Nestle Purina PetCare, Mars Petcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Ingredients Market Emerging Trajectories
Ingredient sourcing is bifurcating between commodity-scale supply chains and specialized functional additive channels, with technology and regulatory forces compressing traditional procurement patterns.
Near-infrared spectroscopy combined with blockchain-based lot tracking is digitizing ingredient quality verification at receiving docks. Large contract manufacturers are deploying these systems to compress certificate-of-analysis validation from days to hours. This technology stack is digitizing supplier risk assessment and enabling just-in-time inventory positions previously impractical for perishable animal proteins.
The EU Feed Hygiene Regulation's extended compliance deadlines for third-country exporters are restructuring import documentation requirements. European pet food manufacturers must now verify that non-EU ingredient suppliers operate under equivalent sanitary standards certified by competent authorities. This regulatory friction most affects Brazilian and Thai fish meal exporters, who are accelerating HACCP accreditation investments to maintain market access.
Direct sourcing from rendering cooperatives and oilseed crush facilities is displacing traditional distributor intermediaries among mid-sized pet food brands. Buyers are establishing volume commitments with named processing plants to secure price stability and provenance documentation. This channel compression is most visible in the Upper Midwest, where Minnesota and Wisconsin formulators are building captive supply relationships with regional protein processors.
Pet Food Ingredients Market Segmentation
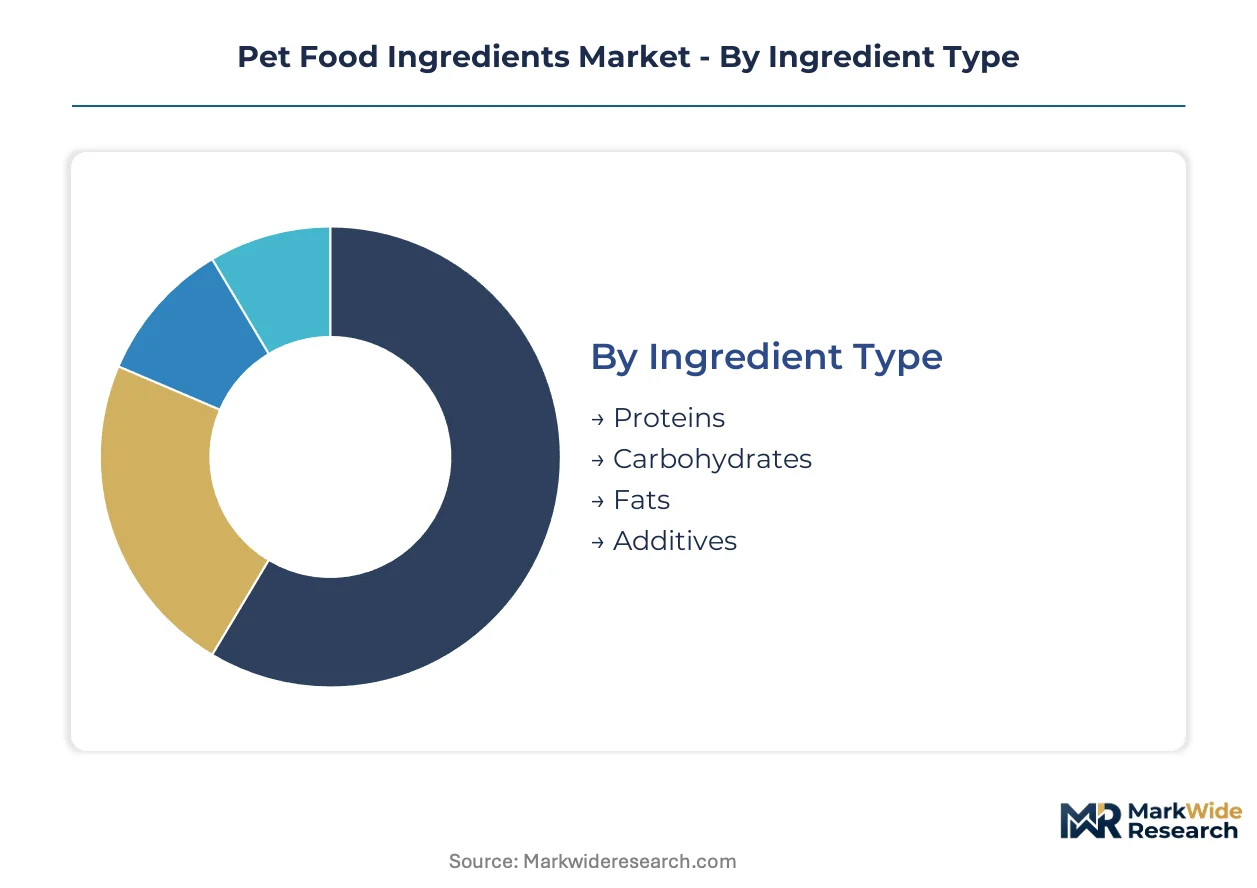
Pet food ingredient procurement strategies diverge sharply across technical specifications, forcing manufacturers to align formulation investments with distinct margin profiles and regulatory pathways. Segmentation clarity enables targeted supplier qualification and inventory positioning against volatile input markets.
Ingredient Type:
Cost tier determines procurement priority, with base nutrients commanding volume contracts while functional inputs absorb disproportionate R&D spend.
- Proteins:Animal-derived meals, isolates, and hydrolysates supply essential amino acids with digestibility coefficients exceeding 80% for premium positioning. Concentrated demand from Illinois and Nebraska rendering clusters leverages USDA-inspected infrastructure for standardized poultry meal and porcine plasma.
- Additives:Probiotics, omega-3 fatty acids, joint-support compounds, and palatability enhancers command per-kilogram value multiples over base nutrients. FSMA preventive controls and AAFCO feeding trial requirements extend novel additive validation timelines, consolidating share among established premix suppliers with documented GRAS determinations.
- Carbohydrates:Grains, legumes, and tubers provide caloric density and extrusion functionality, with grain-free formulations accelerating alternative starch sourcing from cassava and pea processors.
- Fats:Rendered tallows, poultry fats, and refined oils deliver energy density and essential fatty acids, though Inflation Reduction Act biofuel incentives are redirecting animal fats toward renewable diesel production.
Proteins hold installed capacity. Additives is rotating up the share rankings.
Source:
Supply concentration shapes supplier qualification intensity, with traceability requirements filtering channel access by processing geography.
- Animal-based:Rendering-derived meals, plasma, and fats dominate palatability-driven formulations, anchored by Darling Ingredients and regional cooperatives across the Upper Midwest. FDA FSMA preventive controls mandate validated food safety plans, compressing qualified supplier pools.
- By-products:Secondary cuts, organs, and processing residuals from human food channels provide cost-advantaged protein inputs, with supply fluctuating alongside livestock processing volumes and food industry waste streams.
- Plant-based:Soy, pea, and lentil proteins gain formulation share as price-sensitive brands navigate animal protein volatility, though amino acid completeness requires strategic supplementation.
- Synthetic:Laboratory-derived vitamins, amino acids, and carotenoids from BASF SE and comparable suppliers sustain batch-to-batch nutritional consistency in large-scale formulation.
Animal-based maintains the steepest expansion trajectory. Plant-based is climbing the fastest among alternatives.
Form:
Moisture content dictates processing equipment investment, shelf stability requirements, and distribution channel compatibility.
- Dry:Extruded kibbles and meals with moisture below 10% enable ambient distribution and extended shelf life, dominating mass-market volume through grocery and club retail channels.
- Wet:Canned and pouched products with 75-85% moisture content command per-unit premiums and require retort or aseptic processing infrastructure concentrated among contract manufacturers.
- Freeze-dried:Raw nutrition preservation through sublimation drying supports premium raw-feeding positioning, with limited processing capacity constraining supply expansion.
- Semi-moist:Intermediate moisture formulations with humectant stabilization occupy niche training treat and convenience segments, requiring specialized packaging barriers.
Dry holds installed capacity. Freeze-dried is rotating up the share rankings.
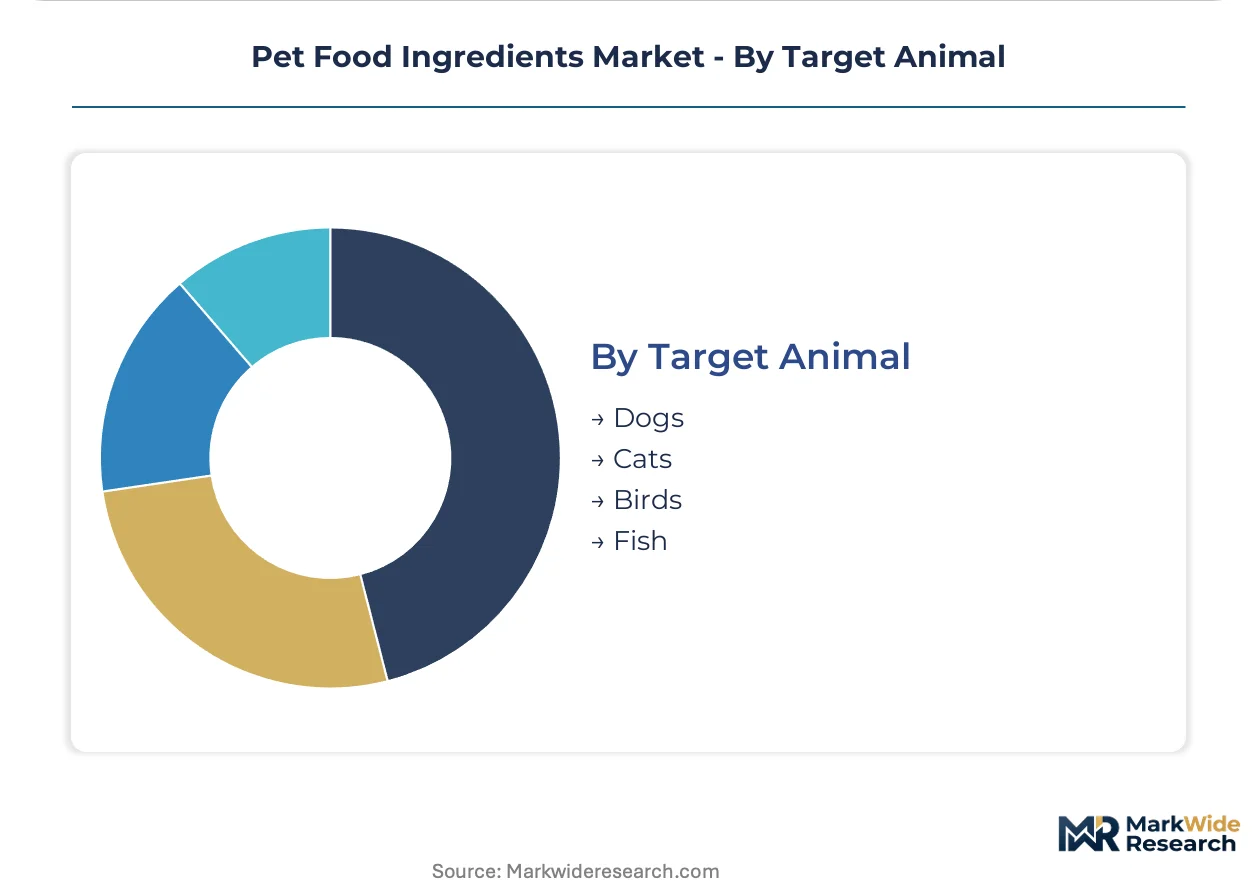
Target Animal:
Species-specific nutritional requirements drive distinct formulation specifications and regulatory claim pathways.
- Dogs:Omnivore-adapted formulations span maintenance, performance, and veterinary therapeutic segments, with prescription renal and diabetic diets commanding clinical validation premiums.
- Cats:Obligate carnivore requirements mandate higher protein inclusion and taurine supplementation, supporting ingredient cost premiums and specialized supplier relationships.
- Birds:Seed, pellet, and nectar formulations for psittacines and passerines require distinct mineral and vitamin premix specifications with limited supplier specialization.
- Fish:Aquarium and pond formulations demand specialized protein digestibility and water stability characteristics, with aquaculture-grade fish meal routing increasingly through Thai processing infrastructure.
Dogs holds installed capacity. Cats is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient procurement patterns diverge sharply by geography, with North American buyers prioritizing traceable rendering infrastructure while Asian markets emphasize aquaculture-grade protein processing for export positioning.
United States
The Upper Midwest corridor concentrates USDA-inspected rendering capacity across Illinois, Iowa, and Nebraska, supplying standardized poultry meal and porcine plasma to domestic formulators. FDA FSMA preventive controls mandate validated food safety plans, compressing qualified supplier pools toward vertically integrated processors. Chicago and Des Moines anchor regional procurement networks where Darling Ingredients and Cargill Incorporated maintain captive supply relationships with mid-sized pet food brands.
Thailand
Bangkok and Samut Sakhon processing zones reconfigure supply routes for premium aquaculture-grade fish proteins entering Western markets. The country's national feed regulator enforces HACCP accreditation investments to maintain EU market access under extended third-country compliance deadlines. Cold-chain infrastructure expansion at Laem Chabang port addresses congestion risks for temperature-sensitive fish meal exports.
Germany
Synthetic vitamin and carotenoid premix production concentrates around Ludwigshafen and surrounding chemical corridors. EFSA nutritional guidelines and EU Feed Hygiene Regulation impose parallel standards that shape export-oriented ingredient specifications. BASF SE anchors batch-to-batch nutritional consistency for large-scale European formulation through laboratory-derived inputs.
Brazil
São Paulo state processors navigate EU-equivalent sanitary certification requirements for poultry by-product meal exports. The national agricultural regulator accelerates HACCP investments to preserve European market access amid restructuring import documentation requirements. Santos port infrastructure supports soy protein concentrate shipments competing with Midwest oilseed processors on price-sensitive formulation contracts.
Netherlands
Rotterdam and Amsterdam distribution hubs intermediate between Thai fish meal exporters and European compound feed manufacturers. FEDIAF nutritional guidelines filter novel ingredient incorporation until feeding trial validation is completed. DSM N.V. maintains premix formulation capacity serving prescription diet manufacturers targeting veterinary therapeutic nutrition segments.
Pet Food Ingredients Market Vendor Landscape
Capability concentration sits with specialized premix and additive suppliers; scale advantage sits with integrated oilseed and rendering processors. The market structures around three tiers: multinational agribusiness conglomerates controlling upstream raw material flows, dedicated rendering and protein specialists with regional density, and premix formulators competing on nutritional consistency and regulatory documentation. Consolidation pressures favor backward integration into rendering capacity and captive supply relationships with named processing plants.
Within the integrated agribusiness tier, Cargill Incorporated exemplifies platform breadth spanning oilseed crush and animal protein processing. Darling Ingredients occupies a position as a rendering specialist with North American density. BASF SE represents the synthetic nutrient archetype, competing through laboratory-derived consistency rather than agricultural commodity exposure. These three anchors illustrate divergent strategic postures: input cost control, regional supply security, and formulation precision respectively.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Darling Ingredients |
| BASF SE |
| Koninklijke DSM N.V. |
| Symrise AG |
| Tyson Foods |
| Nestle Purina PetCare |
| Mars Petcare |
| Others |
Supply Flow & Price Mechanics
The Illinois-Iowa-Nebraska rendering corridor concentrates USDA-inspected poultry meal and porcine plasma capacity, translating upstream livestock processing volumes into downstream pricing leverage for regional pet food formulators. This geographic density enables volume commitments with named processing plants that compress input cost volatility compared to buyers dependent on distributed supplier networks.
Pricing Analysis
Long-term offtake agreements dominate procurement for standardized animal proteins, while spot markets govern specialty additive inputs. Pricing stratifies across premium, standard, and economy tiers based on digestibility certification and FSMA preventive control documentation. Cost compression in economy-tier plant proteins is intensifying as pea and lentil processors compete with Midwest oilseed crush facilities. Price-sensitive private-label brands absorb the tightest margins, while prescription diet manufacturers demonstrate lowest elasticity due to clinical validation requirements.
Supply Chain Analysis
Tariff exposure between Thailand and EU member states dominates risk planning for aquaculture-grade fish meal procurement. Supply concentrates in Thailand, Brazil, and the Upper Midwest, with raw material flows drawing from livestock processing by-products, soy crush operations, and marine capture fisheries. Single-source vulnerability runs through Bangkok and Samut Sakhon processing zones where cold-chain integrity failures would disrupt premium protein exports. Distribution runs through Rotterdam and Chicago hub-and-spoke networks serving compound feed manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet food ingredients sit in early-cycle expansion as humanization of pet nutrition accelerates clean-label protein adoption beyond historical commodity formulations. Functional additive penetration remains underdeveloped relative to human food analogues, creating runway for probiotic and omega-3 ingredient suppliers.
For Market Incumbents: Build traceability infrastructure moats through blockchain-enabled lot tracking and FSMA-validated food safety plans. Consolidate rendering capacity in the Upper Midwest to defend against cellular agriculture protein substitutes. Secure backward integration into named processing plants before IRA biofuel incentives redirect animal fat supply toward renewable diesel production. For New Entrants and Emerging Players: Pursue veterinary therapeutic nutrition formulations where clinical validation creates formulation stickiness and per-kilogram premiums. Target freeze-dried raw nutrition segments constrained by limited processing capacity. Establish direct sourcing relationships with Thai aquaculture processors to bypass established distributor intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among premix formulators with documented GRAS determinations and multi-year supply contracts. Five-to-ten year viability favors suppliers with regulatory documentation depth over commodity-scale processors exposed to input volatility. Watch FDA novel ingredient approval velocity as the signal for additive segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FSMA Preventive Control Certification | Validates supplier qualification for FDA-regulated pet food manufacturers seeking documented traceability. |
| Backward Integration into Rendering Capacity | Secures captive supply of poultry meal and porcine plasma against IRA biofuel incentive competition. |
| Thai Processing Infrastructure Investment | Addresses cold-chain integrity risks at Laem Chabang port for aquaculture-grade fish meal exports. |
| Novel Additive GRAS Self-Affirmation | Accelerates postbiotic and alternative protein launch timelines currently extending 18-36 months. |
| Veterinary Therapeutic Partnership | Creates prescription diet formulation stickiness through clinical validation requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from rendering plant managers, pet food formulator procurement leads, FDA regulatory affairs specialists, and veterinary nutritionists, then refined through secondary validation. Trade data from USDA and Thai national feed regulators, SEC filings of integrated agribusiness conglomerates, AAFCO nutrient profile databases, and EU Feed Hygiene Regulation compliance records anchored supply-side quantification. Bottom-up volume estimates from named processing facilities triangulated against top-down market sizing from ingredient category spend.
Demand-supply balance modeling across the projection horizon incorporated protein digestibility tiering, FSMA compliance segmentation, and regional rendering capacity utilization. CAGRs were derived from growth rate convergence analysis applied to ingredient type, source, form, and target animal dimensions. Forecast inputs included livestock processing volume projections, aquaculture capture trends, and biofuel policy incentive trajectories affecting animal fat allocation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by cellular agriculture protein developers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Phytosterols Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Global Dry Yeast Market
Ingredients
White Wheat Malt Market
Ingredients
US Choline Bitartrate Market
Ingredients
North America Brewing Enzymes Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Revivable Yeast Market
Ingredients
Tuberose Extract Market
Ingredients
Botanical Extracts Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
MCT Oil Market
Ingredients
Baobab Powder Market
Ingredients
Cognitive Ingredients Market
Ingredients
Commercial Flour Market