
 Vitamin C Market | 2026-2036
Vitamin C Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin C Market Intelligence
Asset-light contract manufacturing models are reshaping competitive positioning for new entrants in the vitamin C space. This allows smaller brands to compete without heavy capital investment in fermentation or synthesis facilities. In contrast, established producers like CSPC Pharmaceutical Group Limited leverage massive production scale to control costs. DSM Nutritional Products AG differentiates through its focus on high-purity formulations and branded ingredients for premium applications.
Vitamin C, or ascorbic acid, is a water-soluble vitamin essential for biosynthesis and antioxidant functions in the human body. It is primarily produced through a two-step fermentation process, a modification of the original Reichstein process. Nutritional supplements remain the largest application segment, with tablets and powders representing mature product forms. The functional foods category, however, offers higher margin potential, while online retail is the fastest-expanding distribution channel.
Regulatory frameworks established by the US FDA, the European Food Safety Authority (EFSA), and China's NMPA govern purity standards and health claims. These regulations directly impact market access and labeling for dietary supplements and fortified foods. Suppliers must navigate divergent regional requirements for dosage recommendations and allowable marketing language. The key decision for manufacturers is whether to pursue pharmaceutical-grade certification or focus on the less stringent food-grade segment.
Market Dynamics
The vitamin C market is defined by a fundamental split between high-volume, cost-driven commodity production, primarily centered in China, and the development of high-margin, application-specific formulations for the functional foods and premium supplement sectors.
Growth Catalysts
- FSSAI Fortification Mandates:India's food safety authority, FSSAI, is promoting food fortification, compelling manufacturers of staples like milk and edible oils to incorporate micronutrients, including vitamin C, into their product lines.
- Functional Foods Expansion:The functional foods and beverages industry is a primary demand driver, with consumers seeking products fortified with vitamin C for its antioxidant and immune support properties.
- Rising Health Consciousness in China:A growing middle class and heightened awareness of preventative healthcare in China are stimulating domestic demand for dietary supplements and fortified products, absorbing a significant portion of local production.
Market Restraints
- Input Material Volatility:The two-step fermentation process is dependent on agricultural feedstocks like corn or tapioca, exposing producers to price fluctuations and supply disruptions in global commodity markets.
- Production Concentration Risk:Heavy geographic concentration of ascorbic acid manufacturing capacity in China creates supply chain vulnerabilities related to regional energy policies, environmental regulations, and potential trade friction.
- Divergent Regulatory Standards:Manufacturers face complexity and added costs navigating disparate health claim and labeling rules between major regulatory bodies like the US FDA and the European Food Safety Authority (EFSA).
Strategic Opportunities
- Cosmeceutical Formulations:The "beauty from within" trend creates an opportunity for vitamin C in topical and ingestible cosmeceuticals, leveraging its role in collagen synthesis for anti-aging skin care products.
- Direct-to-Consumer (D2C) Channels:The expansion of online retail enables brands to bypass traditional distribution and engage directly with consumers, offering personalized supplement plans and subscription-based models.
- Advanced Fermentation Processes:Developing single-step fermentation or alternative bio-synthesis pathways presents a significant opportunity to reduce production costs, energy consumption, and environmental impact compared to the modified Reichstein process.
Industry Challenges
- Pharmaceutical-Grade Certification:Securing and maintaining pharmaceutical-grade certifications, such as those from the USP or Ph. Eur., is a capital-intensive and time-consuming process that presents a high barrier for many food-grade producers.
- Supply Chain Traceability:As regulators like the FDA enforce stricter labeling and source-of-origin requirements, implementing robust, end-to-end traceability systems from raw material to finished good becomes a critical operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin C Market |
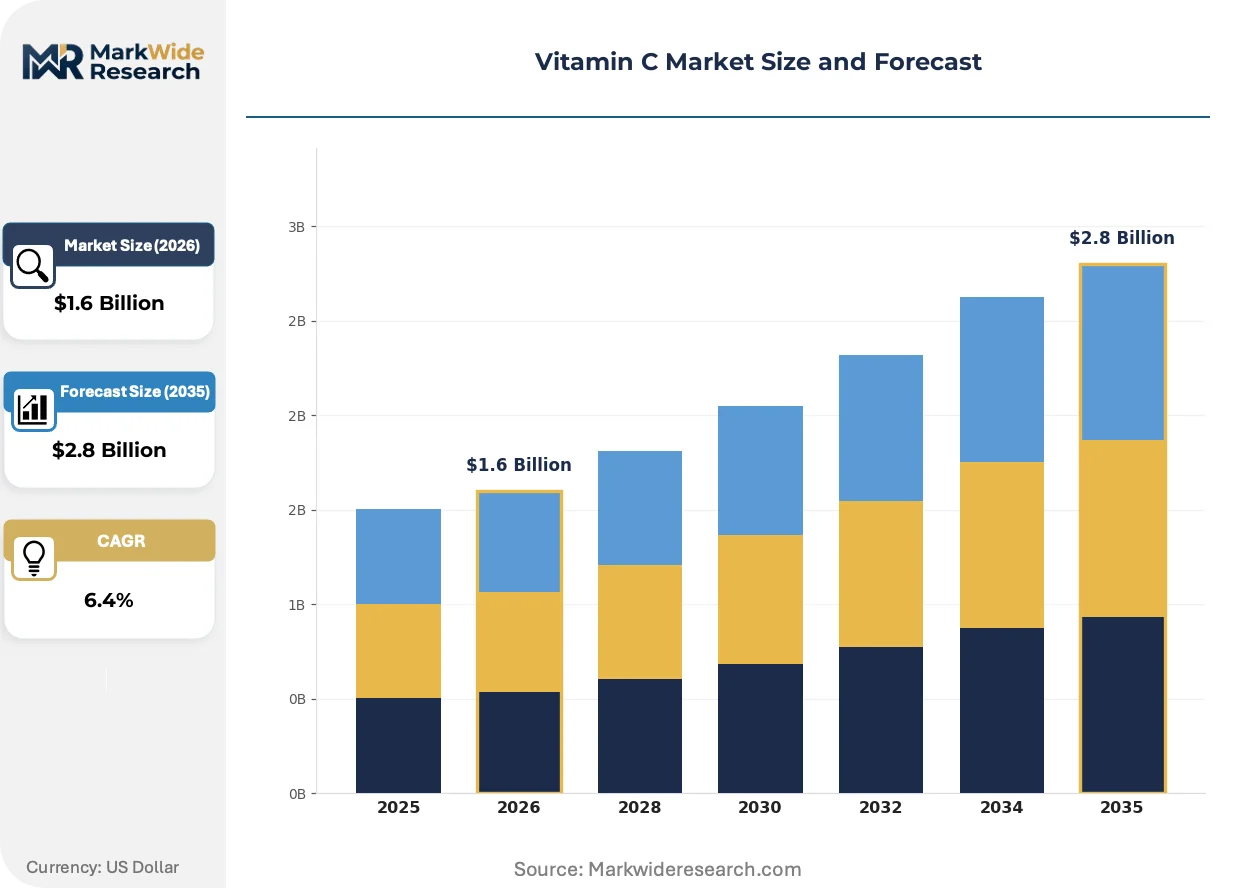
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powders, Effervescent, Liquid Application: Nutritional Supplements, Pharmaceuticals, Cosmetic Products, Functional Foods Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores End User: Adults, Children, Athletes, Seniors |
| Companies Covered | DSM Nutritional Products AG, CSPC Pharmaceutical Group Limited, BASF SE, Merck & Co., Inc., Pfizer Inc., Shandong Luwei Pharmaceutical Co., Ltd., Northeast Pharmaceutical Group Co., Ltd., Abbott Laboratories, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin C Market Strategic Shifts & Innovations
Product formulation is evolving beyond simple ascorbic acid powders and tablets toward value-added delivery systems that enhance bioavailability. This shift is supported by clearer regulatory pathways for health claims and a consumer pull for more effective, targeted nutritional solutions.
Liposomal encapsulation is a delivery technology that uses lipid bilayers to protect vitamin C from degradation in the digestive system. Premium supplement and functional beverage brands are adopting this technology to offer superior absorption. This advanced formulation strategy is rendering obsolete the conventional belief that higher milligram dosages alone equate to greater efficacy.
The European Food Safety Authority's (EFSA) rigorous evaluation of health claims under Regulation (EC) No 1924/2006 influences product marketing across the continent. This regulation compels manufacturers to provide strong scientific evidence for any benefit claims beyond those officially authorized. The dietary supplement segment in the EU is most affected, prompting a focus on marketing language aligned with approved claims for immune function and collagen production.
Consumer purchasing behavior is moving toward personalized nutrition, often guided by health apps, at-home testing kits, or subscription-based advisory services. This trend disrupts the traditional, mass-market model of selling standardized vitamin formulas through pharmacy and grocery channels. This shift is most prominent in North American and European markets, where direct-to-consumer brands are building loyalty with customized product offerings.
Vitamin C Market Segmentation
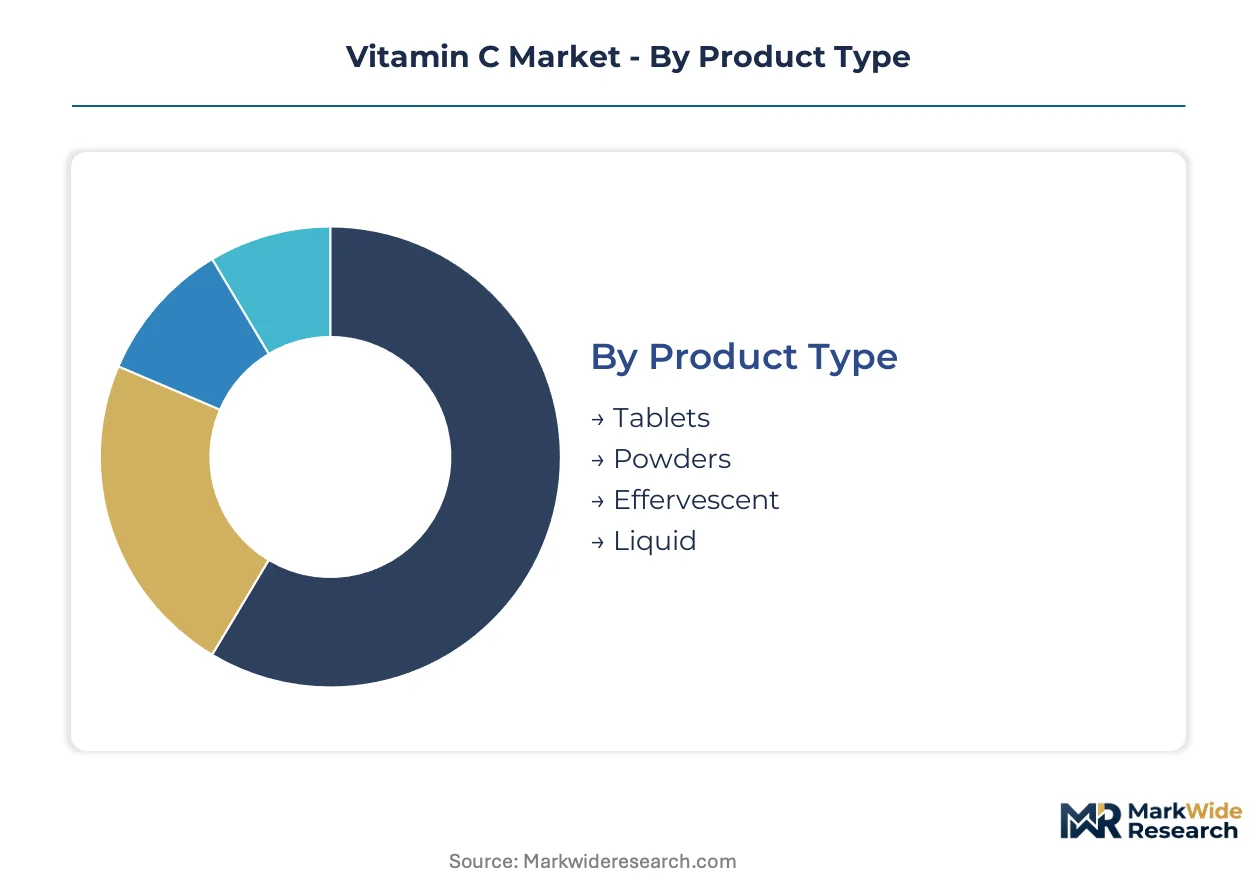
Understanding the varied segments within the vitamin C market reveals distinct consumption patterns and strategic opportunities. This granular analysis highlights where demand concentrates and how product forms, applications, distribution, and end-user preferences shape market dynamics. Manufacturers align product development and marketing efforts with these specific segment needs.
Product Type:
The intensity of after-sales service requirements often differentiates product types, influencing consumer loyalty and repeat purchases for vitamin C formulations. Delivery format significantly impacts user convenience and absorption efficacy, driving diverse consumer choices.
- Tablets:These solid dosage forms typically contain specific milligram dosages of ascorbic acid, often combined with binders and fillers. Demand for tablets remains robust in established markets like the US and Europe, driven by their convenience for daily supplementation.
- Powders:Comprising pure ascorbic acid or blends, powders offer dosage flexibility and are easily mixed into beverages or foods. China's large manufacturing base and consumer preference for bulk or customizable doses support strong demand for powdered vitamin C.
- Effervescent:These tablets dissolve in water, offering a palatable and quickly absorbed form of vitamin C.
- Liquid:Liquid vitamin C formulations provide an easy-to-swallow option, particularly suitable for children or individuals with dysphagia.
Tablets holds the largest share; momentum sits with Effervescent.
Application:
Cost-tiering strategies are evident across vitamin C applications, with premium formulations targeting specialized health outcomes and commodity forms serving basic nutritional needs. Each application category leverages vitamin C's unique properties differently.
- Nutritional Supplements:This segment includes a broad range of products, from single-ingredient ascorbic acid to multi-vitamin complexes, designed to augment dietary intake. North American and European consumers consistently drive this demand for immune support and general wellness.
- Functional Foods:Incorporating vitamin C into everyday food items like beverages, cereals, and dairy products enhances their nutritional profile and market appeal. India's FSSAI fortification mandates are significantly boosting vitamin C inclusion in staple foods.
- Pharmaceuticals:Vitamin C in pharmaceutical applications adheres to stringent purity standards for use in medical treatments and specialized formulations.
- Cosmetic Products:Topical and ingestible cosmetic formulations utilize vitamin C for its antioxidant properties and role in collagen synthesis for skin health.
Nutritional Supplements maintains the largest market presence, with Functional Foods expanding most quickly.
Distribution Channel:
Volume throughput and logistical complexity vary significantly across distribution channels, influencing pricing structures and market reach for vitamin C products. Each channel caters to distinct consumer purchasing behaviors and preferences.
- Online Retail:This channel includes e-commerce platforms and direct-to-consumer websites, offering convenience, wider product selection, and competitive pricing. The expansion of online retail in North America and Europe facilitates personalized supplement sales.
- Pharmacies:Pharmacies and drugstores provide a trusted point of sale for vitamin C, often accompanied by professional advice from pharmacists. This channel is crucial for consumers seeking medically endorsed or higher-grade supplements.
- Supermarkets:Grocery chains and hypermarkets offer mass-market accessibility for vitamin C products, often alongside other food and health items.
- Health Stores:Specialized health food stores cater to consumers focused on natural products, organic options, and specific dietary needs for vitamin C.
Supermarkets account for a substantial volume, while Online Retail is gaining share fastest.
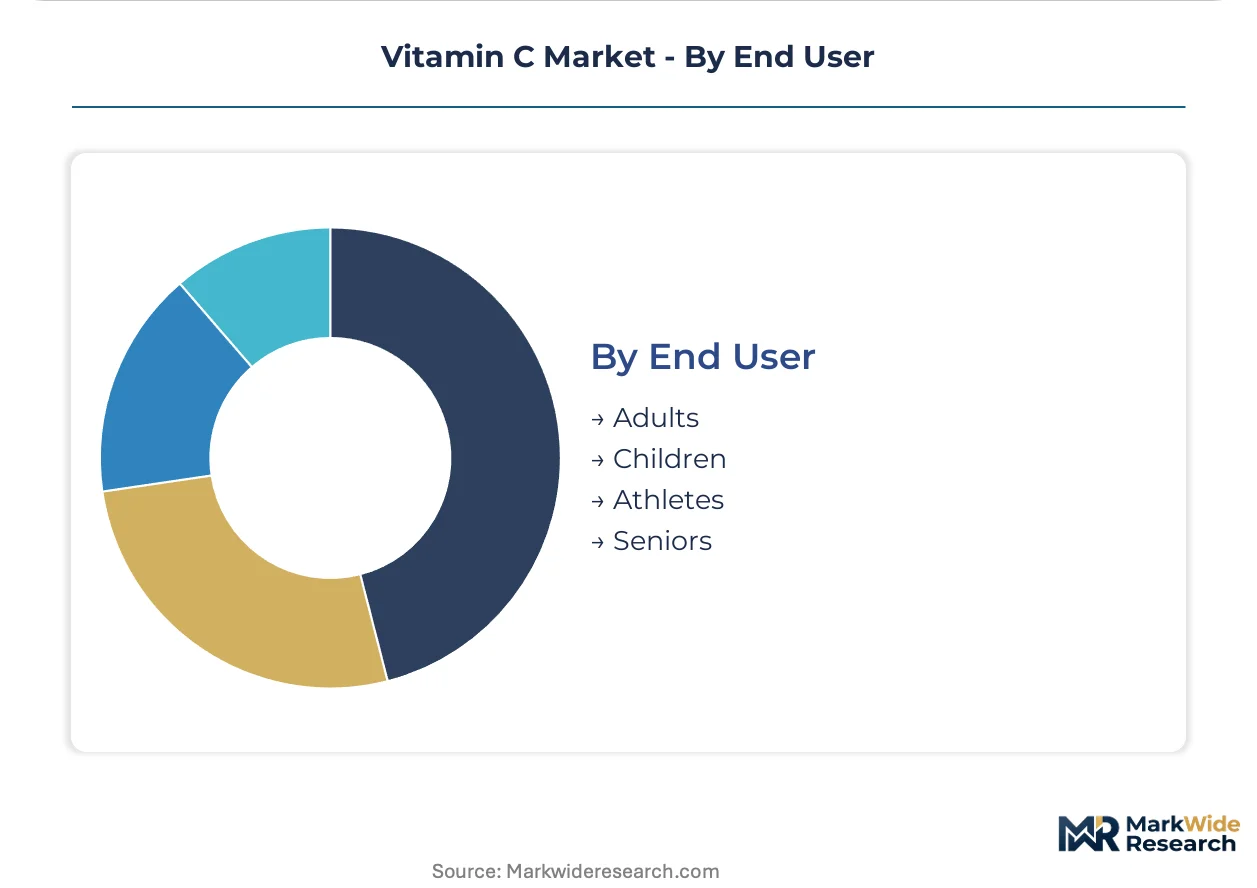
End User:
Customer type segmentation reveals distinct health priorities and purchasing power, guiding manufacturers to tailor vitamin C product formulations and marketing messages. Specific demographics exhibit varying needs for supplementation.
- Adults:This broad demographic uses vitamin C for general wellness, immune support, and antioxidant benefits, often through daily supplements. Health-conscious adults across all major economies represent a consistent and substantial demand base.
- Seniors:Older adults seek vitamin C for immune function, collagen maintenance, and bone health, often due to age-related nutritional needs. The aging populations in Japan and Western Europe drive specific demand for senior-focused formulations.
- Children:Pediatric vitamin C formulations focus on immune system development and general growth, often available in palatable forms.
- Athletes:High-performance athletes use vitamin C to support recovery, reduce oxidative stress, and maintain immune health during intense training.
Adults constitute the largest end-user segment; Seniors show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FSSAI fortification mandates are compelling manufacturers to incorporate micronutrients like vitamin C into staple foods, significantly influencing regional demand patterns. Regulatory frameworks across major economies shape market access and product formulation strategies. This global policy push stimulates localized production and consumption.
China
China's significant manufacturing capacity drives global supply and domestic consumption, fueled by rising consumer health consciousness. The NMPA's purity standards and health claim regulations directly influence local product development. Major production hubs in Shandong province continue to absorb substantial raw material volumes for ascorbic acid synthesis.
India
FSSAI fortification mandates are expanding vitamin C inclusion in essential food items, boosting demand for functional foods. The FSSAI's guidelines on micronutrient levels directly impact food manufacturers' product lines. Food processing clusters near Mumbai are actively integrating vitamin C into dairy and edible oil products.
United States
Robust demand for nutritional supplements and the expansion of online retail channels characterize the US market. US FDA regulations govern dietary supplement labeling and health claims, ensuring product safety and efficacy. Dietary supplement brands in California are increasingly leveraging direct-to-consumer models for personalized offerings.
Germany
Premium applications and high-purity formulations drive demand in Germany, reflecting consumer preference for quality. The European Food Safety Authority (EFSA) rigorous evaluation of health claims influences marketing strategies across the country. Specialty chemical producers in Ludwigshafen focus on pharmaceutical-grade vitamin C production.
Japan
An aging population and the trend toward personalized nutrition stimulate specific vitamin C demand in Japan. The PMDA's oversight ensures product quality and safety for pharmaceutical and supplement applications. Supplement companies in Tokyo are developing customized product offerings to cater to individual health needs.
Vitamin C Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with high-volume commodity producers coexisting with specialized ingredient manufacturers. New entrants leverage asset-light contract manufacturing models to enter the market without significant capital investment. Established producers often focus on massive production scale or high-purity formulations. Competitive moves include strategic partnerships for distribution and continuous capacity expansion to meet global demand.
On the premium-tier vector, DSM Nutritional Products AG represents a focus on high-purity formulations and branded ingredients for specialized applications, particularly in the European and North American markets. CSPC Pharmaceutical Group Limited, a Chinese-based pharmaceutical company, exemplifies the scale-driven end of the market, leveraging extensive production capacity for global distribution of commodity vitamin C. BASF SE, a German chemical company, occupies a position bridging commodity supply and specialized ingredient solutions, serving diverse industrial and consumer sectors with its broad chemical portfolio. These entities collectively illustrate the varied strategic approaches within the vitamin C industry.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| CSPC Pharmaceutical Group Limited |
| BASF SE |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Shandong Luwei Pharmaceutical Co., Ltd. |
| Northeast Pharmaceutical Group Co., Ltd. |
| Abbott Laboratories |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Shandong province's massive ascorbic acid production capacity significantly influences global vitamin C pricing. This concentration of manufacturing power allows large Chinese producers to control cost structures and exert downward pressure on international spot prices.
Pricing Analysis
Certification level (USP/Ph. Eur.) creates the primary spread in vitamin C pricing. The market operates on a hybrid model combining commodity spot pricing for bulk food-grade material and long-term contracts for pharmaceutical-grade ingredients. Pricing softness reflects oversupply from Chinese producers, making food-grade buyers highly price-sensitive. Pharmaceutical companies, conversely, prioritize consistent quality and certification over lowest cost.
Supply Chain Analysis
Export-control regimes do not directly limit vitamin C flows, but production concentration in China creates significant geopolitical risks. The supply chain draws from agricultural feedstocks like corn and tapioca, primarily cultivated in Asia. This heavy geographic concentration in China creates supply chain vulnerabilities related to regional energy policies and potential trade friction. Downstream distribution runs through online retail, pharmacies, and supermarkets, with online channels expanding most rapidly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitamin C market presents distinct opportunities where specialized capabilities are scarce. Expertise in advanced fermentation processes and high-purity formulation represents a critical asset gap for many participants.
For Market Incumbents: Entrench market position by investing in advanced fermentation R&D to reduce reliance on the modified Reichstein process. Consolidate supply chains through long-term feedstock contracts to mitigate input material volatility. The threat of new entrants leveraging asset-light contract manufacturing models necessitates continuous process innovation. Capacity expansion in strategic regions serves as a key lever.
For New Entrants and Emerging Players: Build out direct-to-consumer channels in North American and European personalized nutrition segments. Focus on cosmeceutical formulations that leverage vitamin C's role in collagen synthesis for anti-aging. The functional foods category in India, driven by FSSAI mandates, represents a penetrable application. A subscription-based model offering customized product bundles provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a specialized ingredient technology play because demand for high-purity, application-specific formulations is expanding. Target acquisition profiles include companies with patented liposomal encapsulation or novel biosynthesis pathways. A significant uptick in pharmaceutical-grade certifications by non-traditional producers serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | This initiative aligns with FSSAI mandates and captures demand from the functional foods sector. |
| Investment in Liposomal Encapsulation | This technology enhances bioavailability for premium supplement and functional beverage brands. |
| Pharmaceutical-Grade Certification Pursuit | Securing USP or Ph. Eur. certification unlocks higher-margin applications in medical treatments. |
| Direct-to-Consumer Channel Development | Online retail expansion allows brands to offer personalized supplement plans to North American consumers. |
| Diversification into Cosmeceutical Formulations | This move capitalizes on the "beauty from within" trend and collagen synthesis benefits for skin health. |
Research Approach
Desk research of regulatory filings, industry reports, and trade publications preceded structured interviews with R&D directors, procurement leads, and regulatory affairs specialists. This primary fieldwork provided qualitative insights and validated market dynamics. Secondary data from FDA, EFSA, and FSSAI guidelines informed purity standards. Bottom-up and top-down triangulation ensured data consistency and comprehensive market sizing.
Assumptions regarding regulatory stability and feedstock availability were held constant, while consumer health consciousness and functional foods demand were varied. The analytical framework modeled market dynamics across the analysis window, segmented by product type, application, distribution channel, and end-user. Compound annual growth rates (CAGRs) were derived from historical trends. Regional fortification mandates were a key forecast input.
Sensitivities concentrate around unforeseen shifts in regulatory frameworks or significant disruptions in agricultural commodity markets. Forecasts reflect assumptions documented at the time of publication. Continuous validation against operating reality is the recommended discipline for market participants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Fortified Juices Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Pantothenic Acid Market