
 Seaweed Derivatives Market | 2026-2036
Seaweed Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Derivatives Market Analysis
Plant-based meat alternatives is repositioning demand for carrageenan and alginates as texture-modifying agents in clean-label formulations. CP Kelco leverages its biotechnology platform to dominate microbial fermentation alternatives, while Gelymar S.A. anchors its position in South American red seaweed sourcing for premium carrageenan grades. Cargill, Incorporated extends its supply chain control through backward integration into sustainable seaweed aquaculture partnerships.
Seaweed derivatives comprise polysaccharide extracts—primarily carrageenan from Rhodophyta, alginates from Phaeophyta, and agar from Gelidium species—functioning as gelling, thickening, and stabilizing agents across industrial applications. Carrageenan leads in volume due to its cost-performance ratio in dairy and processed meat systems, while alginates command premium positioning in pharmaceutical controlled-release matrices and wound dressings. Food Industry applications retain the largest share of value generation, though Cosmetics represents the fastest-expanding margin pool as marine bioactive claims drive formulation premiums in K-beauty and European natural skincare.
EU REACH and the EU Green Deal shape market access by mandading traceable, low-carbon harvesting practices for marine biomass imports into European food and cosmetic supply chains. The FDA GRAS framework and EFSA novel food evaluations determine which seaweed-derived ingredients achieve commercialization pathways in North America and Europe. Stakeholders must monitor evolving bioprospecting regulations and marine spatial planning policies that could restrict wild harvest access while favoring certified aquaculture expansion.
Market Dynamics
EU Green Deal mandates and the EU F-Gas Regulation are compressing carbon footprints across marine biomass supply chains, forcing processors to abandon wild-harvest models for certified aquaculture partnerships that satisfy REACH traceability requirements.
Growth Catalysts
- Plant-based meat formulation:Carrageenan and alginates serve as essential texture-modifying agents in clean-label meat alternatives, with food manufacturers reformulating to eliminate methylcellulose and synthetic binders.
- MFDS functional food approvals:South Korea's Ministry of Food and Drug Safety has accelerated hydrocolloid registrations for digestive health and immunity-positioned products, expanding addressable SKUs in Asian retail channels.
- EU Green Deal procurement mandates:European institutional buyers now require documented low-carbon harvesting credentials for marine-sourced inputs, redirecting volume toward certified sustainable suppliers.
Market Restraints
- Red seaweed supply concentration:Premium carrageenan-grade Rhodophyta harvesting concentrates in Chilean and Indonesian coastal zones, exposing processors to El Niño disruption and geopolitical friction.
- Microbial fermentation substitution:CP Kelco's biotechnology platform produces fermentation-derived hydrocolloids with performance parity, threatening price premiums for traditional seaweed extracts in commodity applications.
- Wild harvest access restrictions:Marine spatial planning policies in EU member states and New Zealand are constraining licensed collection areas, elevating raw material costs for non-integrated processors.
Strategic Opportunities
- K-beauty marine bioactive positioning:South Korean cosmetics formulators are premiumizing seaweed-derived fucoidan and phlorotannin extracts for anti-aging serums, creating margin expansion beyond commodity hydrocolloids.
- Pharmaceutical controlled-release matrices:Alginates in wound dressings and oral drug delivery systems command pricing multiples versus food-grade applications, with FDA GRAS-plus-pharma dual certification unlocking hospital procurement channels.
- Integrated aquaculture partnerships:Backward integration into seaweed farming operations in Norway and Scotland satisfies ESG audit requirements while securing captive supply for European cosmetic and food manufacturing clients.
Industry Challenges
- Phycocolloid extraction expertise scarcity:Skilled technicians capable of optimizing carrageenan yield and gel strength across variable biomass quality are concentrated in legacy processing regions, constraining new facility ramp rates.
- EFSA novel food evaluation timelines:Seaweed-derived ingredients without substantial consumption history face 18-24 month safety assessment periods, delaying commercialization for innovative species or extraction methods.
- Multi-jurisdiction certification complexity:Simultaneous compliance with FDA GRAS, EFSA novel food, and MFDS functional food frameworks requires redundant toxicology and stability testing, inflating R&D budgets for multinational launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Derivatives Market |
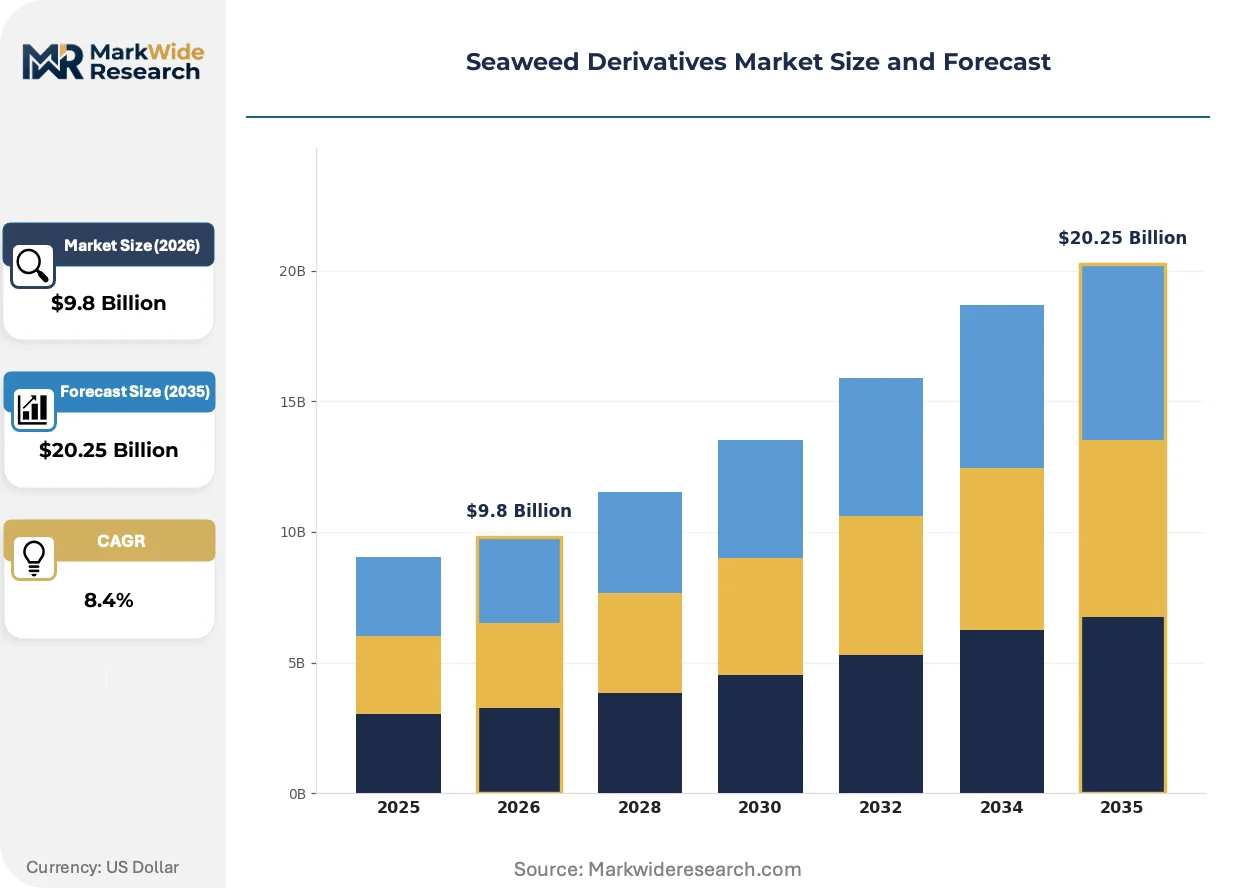
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Carrageenan, Alginates, Seaweed Extracts Application: Food Industry, Cosmetics, Pharmaceuticals, Agriculture End User: Food Manufacturers, Cosmetic Companies, Nutraceutical Firms, Soil Conditioners Form: Powder, Liquid, Granule, Sheet |
| Companies Covered | W Hydrocolloids, Inc., KIMICA Corporation, DuPont de Nemours, Inc., Gelymar S.A., CP Kelco, ALGAIA, Cargill, Incorporated, Compañía Española de Algas Marinas, S.A., Arthur Branwell & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Derivatives Market Emerging Trajectories
Biotechnology platforms and precision fermentation are compressing traditional extraction economics while regulatory carbon-accounting frameworks reshape competitive positioning across marine ingredient supply chains.
Enzymatic hydrolysis systems are unifying previously separate processing stages for carrageenan refinement, enabling simultaneous demineralization and molecular weight standardization in continuous-flow configurations. Mid-sized hydrocolloid processors in Denmark and France are retrofitting batch facilities with these integrated units, collapsing capital requirements for premium-grade production while reducing energy intensity by eliminating multi-stage washing and filtration sequences.
REACH registration deadlines for polymer imports are tightening documentation requirements for seaweed-derived polysaccharides entering EU cosmetic and food contact applications. The European Chemicals Agency's extended safety data sheet mandates now cover carrageenan molecular weight fractions below 100 kDa, forcing Asian exporters to invest in analytical certification capabilities or cede position to European-integrated suppliers with in-house toxicology testing infrastructure.
Clean-label procurement committees at major dairy and meat processors are disqualifying synthetic hydrocolloids and demanding third-party certified sustainable seaweed sourcing. This certification-driven preference rotation is compressing spot-market volumes for uncertified carrageenan while expanding long-term offtake agreements with aquaculture-verified suppliers, with the shift most visible in German and Dutch retail private-label reformulations.
Seaweed Derivatives Market Segmentation
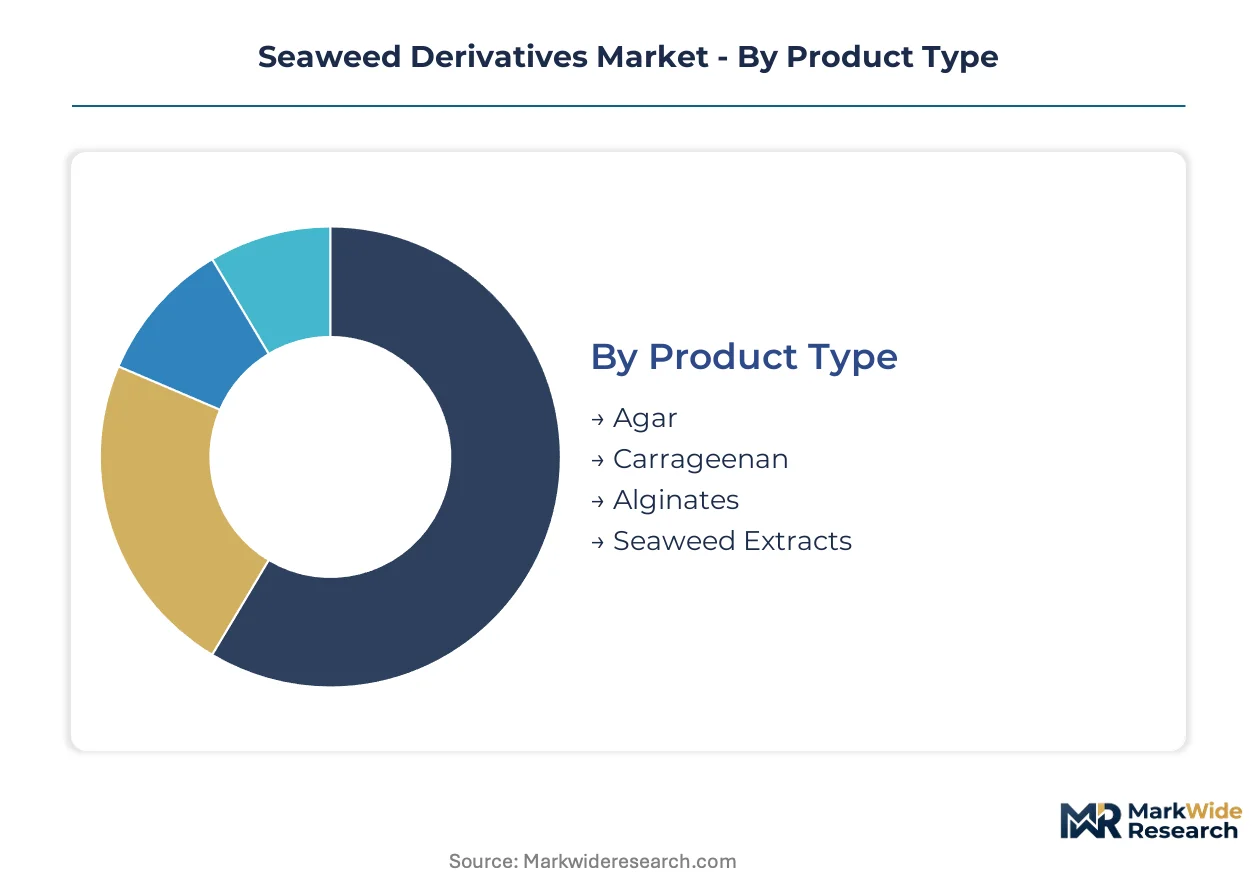
Seaweed derivatives fragment across extraction chemistry, functional performance, and regulatory compliance tiers. Buyers prioritize gel strength specifications, EFSA novel food status, and REACH traceability credentials over commodity pricing.
Product Type:
Procurement committees weight cost-performance ratios against clean-label positioning and microbial fermentation substitution risk.
- Carrageenan:Kappa, iota, and lambda fractions from Rhodophyta species deliver thermoreversible gelation for dairy and processed meat systems. German and Dutch retail private-label reformulations favor certified aquaculture-sourced grades over wild-harvest alternatives.
- Alginates:Block copolymer structures of mannuronic and guluronic acids from Laminaria and Macrocystis enable ionotropic gelation with calcium. Pharmaceutical controlled-release matrices in wound dressings and oral drug delivery command pricing multiples versus food-grade applications.
- Agar:Polysaccharide gel matrix from Gelidium and Gracilaria species provides superior clarity and melting point control for microbiological media and confectionery.
- Seaweed Extracts:Fucoidan, phlorotannin, and laminarin concentrates target marine bioactive claims in K-beauty anti-aging serums and functional food positioning.
Carrageenan leads on scale; seaweed extracts lead on momentum.
Application:
Margin pools diverge sharply between commodity hydrocolloid volumes and premium bioactive ingredient positioning.
- Food Industry:Texture modification in plant-based meat alternatives drives carrageenan and alginate demand as methylcellulose replacements. South Korea's MFDS functional food approvals expand hydrocolloid registrations for digestive health claims.
- Cosmetics:Marine-derived polysaccharides and phenolic compounds command formulation premiums in K-beauty and European natural skincare. Fucoidan and phlorotannin extracts represent the steepest expansion trajectory as anti-aging actives.
- Pharmaceuticals:Alginate wound dressings and controlled-release oral matrices require FDA GRAS-plus-pharma dual certification for hospital procurement channels.
- Agriculture:Seaweed-based biostimulants and soil conditioners leverage oligosaccharide content for crop stress tolerance and root development.
Food Industry anchors volume generation; Cosmetics captures margin expansion.
End User:
Technical specification requirements and certification burdens separate enterprise procurement from mid-tier buyer flexibility.
- Food Manufacturers:Dairy and meat processors demand third-party certified sustainable sourcing with documented low-carbon harvesting credentials under EU Green Deal procurement mandates.
- Cosmetic Companies:South Korean formulators premiumize marine bioactive positioning while European natural skincare brands prioritize REACH-registered polysaccharide fractions.
- Nutraceutical Firms:EFSA novel food evaluations and MFDS functional food registrations determine commercialization pathways for immunity-positioned seaweed ingredients.
- Soil Conditioners:Agricultural input distributors specify oligosaccharide concentration and heavy metal limits for organic farming compliance.
Food Manufacturers dominate procurement volume; Cosmetic Companies drive specification premiumization.
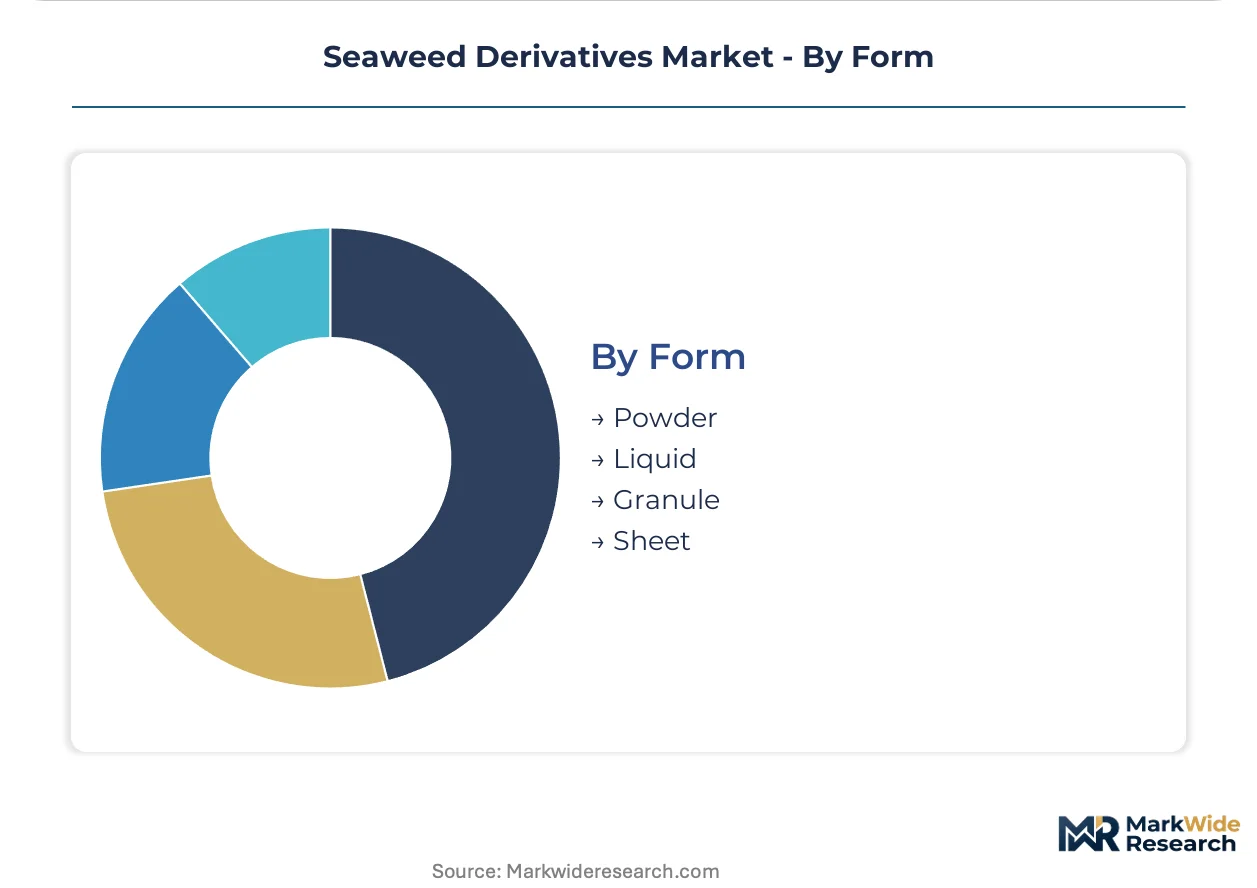
Form:
Processing economics and dissolution kinetics dictate format selection across industrial versus artisanal use cases.
- Powder:Standardized particle size distributions enable precise dosing in automated food production and pharmaceutical tableting operations.
- Liquid:Pre-hydrated hydrocolloid solutions eliminate dispersion equipment requirements for small-batch cosmetic and nutraceutical manufacturers.
- Granule:Intermediate surface area balances dissolution speed with storage stability for agricultural biostimulant applications.
- Sheet:Pre-formed alginate and agar matrices serve specialized wound care and laboratory culture media preparation.
Powder commands manufacturing scale; Liquid gains share in artisanal processing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting seaweed derivative production toward jurisdictions where aquaculture certification costs and carbon-accounting compliance burdens remain lower than European benchmarks. Processors are relocating extraction capacity to exploit these cost-of-compliance gaps while maintaining REACH-registered distribution channels for finished goods.
South Korea
MFDS functional food approvals for hydrocolloid-based digestive health claims are accelerating SKU expansion in Seoul's retail channels. The Ministry of Food and Drug Safety maintains accelerated registration pathways for marine-sourced ingredients with established safety profiles. Busan-Ulsan processing clusters dominate red seaweed refinement for both domestic K-beauty formulators and export pharmaceutical contracts.
Chile
Premium carrageenan-grade Rhodophyta harvesting concentrates along Chilean coastal zones exposed to El Niño disruption risk. The national fisheries service enforces seasonal quotas and marine spatial planning restrictions that elevate raw material security premiums. Puerto Montt and Chiloé Island anchor the country's hydrocolloid extraction infrastructure serving North American dairy processors.
Germany
EU Green Deal procurement mandates require documented low-carbon harvesting credentials for marine-sourced inputs entering German retail private-label supply chains. ECHA REACH registration deadlines for polymer imports now cover carrageenan molecular weight fractions below 100 kDa. Hamburg and Bremen harbor zones concentrate analytical certification laboratories serving Asian exporters seeking European market access.
Indonesia
Wild-harvest red seaweed supply chains face mounting pressure from EU traceability requirements and domestic marine spatial planning restrictions. The national coordinating ministry for maritime affairs is licensing collection zones to reduce unregulated harvesting in Sulawesi and Nusa Tenggara waters. Makassar processing facilities are retrofitting for aquaculture-verified supply integration to retain European cosmetic manufacturer contracts.
Norway
Integrated aquaculture partnerships in Norwegian coastal waters satisfy ESG audit requirements for European food and cosmetic manufacturing clients. The Norwegian Food Safety Authority aligns domestic regulations with EFSA novel food evaluation standards to accelerate commercialization timelines. Trøndelag and Nordland counties host kelp farming operations supplying alginate processors with captive raw material streams.
Seaweed Derivatives Market Vendor Landscape
Backward integration into aquaculture operations dominates the current landscape as processors secure captive supply against wild-harvest access restrictions. The vendor base stratifies across biotechnology-enabled fermentation specialists, legacy hydrocolloid extractors with regional biomass relationships, and diversified food ingredient conglomerates with sustainability certification infrastructure. Three archetypes define positioning: fermentation-platform disruptors, red seaweed sourcing specialists, and integrated aquaculture operators. Capacity expansion in certified farming zones and strategic partnerships with ESG-audited suppliers represent the dominant competitive moves.
Within the integrated aquaculture tier, Cargill, Incorporated and ALGAIA exemplify upstream control strategies through seaweed farming partnerships in European waters. CP Kelco occupies a position representing biotechnology-enabled fermentation alternatives that threaten traditional extraction economics. Gelymar S.A. anchors the red seaweed sourcing specialist archetype with South American biomass relationships. These three entities collectively illustrate the competitive tension between biological manufacturing platforms and marine harvest-dependent supply models.
| Leading Market Players |
|---|
| W Hydrocolloids, Inc. |
| KIMICA Corporation |
| DuPont de Nemours, Inc. |
| Gelymar S.A. |
| CP Kelco |
| ALGAIA |
| Cargill, Incorporated |
| Compañía Española de Algas Marinas, S.A. |
| Arthur Branwell & Co. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap hydrocolloid processors in Denmark and France anchor pricing discipline through generational biomass relationships and conservative leverage structures. Their ownership profile limits aggressive price competition while reinforcing long-term offtake loyalty with aquaculture-certified suppliers, compressing spot-market volatility for premium carrageenan grades.
Pricing Analysis
Distributor margin layers absorb certification cost premiums before product reaches German and Dutch retail private-label buyers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade alginates separates wound dressing manufacturers from dairy processors. Pricing pressure stems from CP Kelco's fermentation-derived hydrocolloids achieving performance parity at lower input cost. Mid-tier food manufacturers exhibit highest price sensitivity, while pharmaceutical formulators prioritize FDA GRAS-plus-pharma dual certification over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from European cosmetic manufacturers now mandate qualified suppliers in both Chile and Indonesia for red seaweed biomass. Raw material supply draws from Rhodophyta harvesting zones, Laminaria kelp farms in Norway, and Gelidium collection in Morocco. Single-source vulnerability concentrates in El Niño-exposed Chilean coastal zones where premium carrageenan-grade seaweed harvesting faces seasonal quota restrictions. Distribution runs through Rotterdam and Hamburg harbor zones for analytical certification before REACH-registered release to downstream formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Seaweed Derivatives Market compounds steadily as plant-based meat reformulations permanently embed carrageenan and alginate demand into clean-label food manufacturing. Regulatory carbon-accounting frameworks across EU member states reinforce premium positioning for certified aquaculture-sourced grades.
For Market Incumbents: Extend backward integration into Norwegian and Scottish kelp farming operations to secure captive supply against wild-harvest access restrictions. Deepen analytical certification capabilities in Hamburg harbor zones to capture Asian exporter compliance spending. Microbial fermentation substitution from biotechnology platforms threatens traditional extraction economics; incumbents must lock ESG-audited aquaculture partnerships before marine spatial planning policies tighten further. For New Entrants and Emerging Players: Enter via South Korean MFDS functional food registration pathways where accelerated approval timelines for hydrocolloid-based digestive health claims create white-space expansion. Target K-beauty marine bioactive positioning for fucoidan and phlorotannin extracts where margin multiples exceed commodity hydrocolloids. Partner with Busan-Ulsan processing clusters for shared extraction infrastructure rather than greenfield capital deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy hydrocolloid extractors with regional biomass relationships but lacking ESG certification infrastructure. Five-to-ten year viability hinges on aquaculture transition completion before EU Green Deal procurement mandates harden. Acquisition target archetype: mid-cap processors in Denmark or France with enzymatic hydrolysis retrofit potential and existing European cosmetic manufacturer relationships. Signal to watch is EFSA novel food evaluation timeline compression for innovative seaweed species.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aquaculture | Captive supply secures against El Niño disruption and marine spatial planning restrictions in Chile. |
| Enzymatic Hydrolysis Retrofit | Continuous-flow refinement collapses energy intensity for premium-grade carrageenan production in Denmark. |
| MFDS Functional Food Registration | Accelerated pathway in South Korea expands addressable SKUs for digestive health-positioned hydrocolloids. |
| REACH Analytical Certification Investment | In-house toxicology infrastructure captures Asian exporter compliance spending for sub-100 kDa fractions. |
| Pharmaceutical Dual Certification | FDA GRAS-plus-pharma status unlocks hospital procurement channels for alginate wound dressing manufacturers. |
Methodological Framework
Multiple input streams — regulatory filing databases, customs trade records, and aquaculture partnership disclosures — were reconciled against primary interviews with hydrocolloid plant managers, cosmetic formulator procurement leads, and pharmaceutical regulatory affairs directors. Secondary validation drew from ECHA REACH registration data, MFDS functional food approval logs, EU Green Deal procurement mandate documentation, and SEC 10-K filings from diversified food ingredient conglomerates. Bottom-up volume modeling across extraction chemistry tiers was cross-checked against top-down market sizing from trade association aggregates.
Historical capacity expansion patterns were cross-referenced with expert panel input from Norwegian kelp farming operators and Chilean fisheries quota administrators. Segmentation dimensions modeled included polysaccharide chemistry type, application vertical, certification tier, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand projections incorporating substitution risk from microbial fermentation platforms. Industry-specific forecast inputs captured EFSA novel food evaluation pipeline status and marine spatial planning policy implementation trajectories.
Inputs from ECHA registration databases and MFDS approval logs were available through the study window; gaps in real-time aquaculture yield data introduce uncertainty bands around biomass supply assumptions. Forecasts reflect documented regulatory timelines and disclosed partnership structures. Deviation in EU Green Deal procurement mandate enforcement intensity or El Niño frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Pastry Flour Market
Ingredients
South America Malt Ingredient Market
Ingredients
US Choline Bitartrate Market
Ingredients
Cheese Ingredients Market
Ingredients
Halal Ingredients Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
South America Vegetable Oil Market
Ingredients
United States Gelatin Market
Ingredients
Germany Gelatin Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Cooking Oil Market
Ingredients
Feed Premix Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Lupine Peptides Market
Ingredients
USA Yeast Extracts Market
Ingredients
Arrowroot Starch Market