
 Bread Premix Market | 2026-2036
Bread Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Premix Market Outlook
Asset-light leasing models for industrial mixing equipment are reconfiguring how mid-sized bakeries enter the premix category without capital-intensive facility overhauls. Corbion N.V. leverages its fermentation expertise to sustain margins in enzyme-enhanced formulations. Puratos Group anchors European supply through its sourdough competency centers and regional milling partnerships. Kerry Group plc differentiates via taste-modulation technologies that reduce sodium without compromising crust development.
Bread premix denotes a pre-blended combination of flour, leavening agents, emulsifiers, enzymes, and functional ingredients requiring only the addition of water or minimal wet ingredients before baking, with typical moisture specifications below 14% to ensure shelf stability. Commercial baking operations deploy these formulations to standardize output across multi-site production networks. Whole wheat and multigrain variants command premium positioning as fiber-content labeling gains traction in retail channels. Powder form dominates institutional procurement due to extended storage viability and freight efficiency, while ready-to-use liquid formats occupy niche positions in food service environments where labor minimization drives purchasing decisions.
The EU Green Deal and REACH frameworks restrict certain preservative chemistries, compelling reformulation toward enzyme-based shelf-life extension. FDA guidance on whole-grain health claims shapes how U.S. manufacturers position multigrain premix portfolios. BIS fortification mandates in India create compliance-driven demand for micronutrient-enhanced blends. Stakeholders must monitor evolving clean-label definitions across jurisdictions to anticipate which ingredient technologies will retain formulation approval.
Market Dynamics
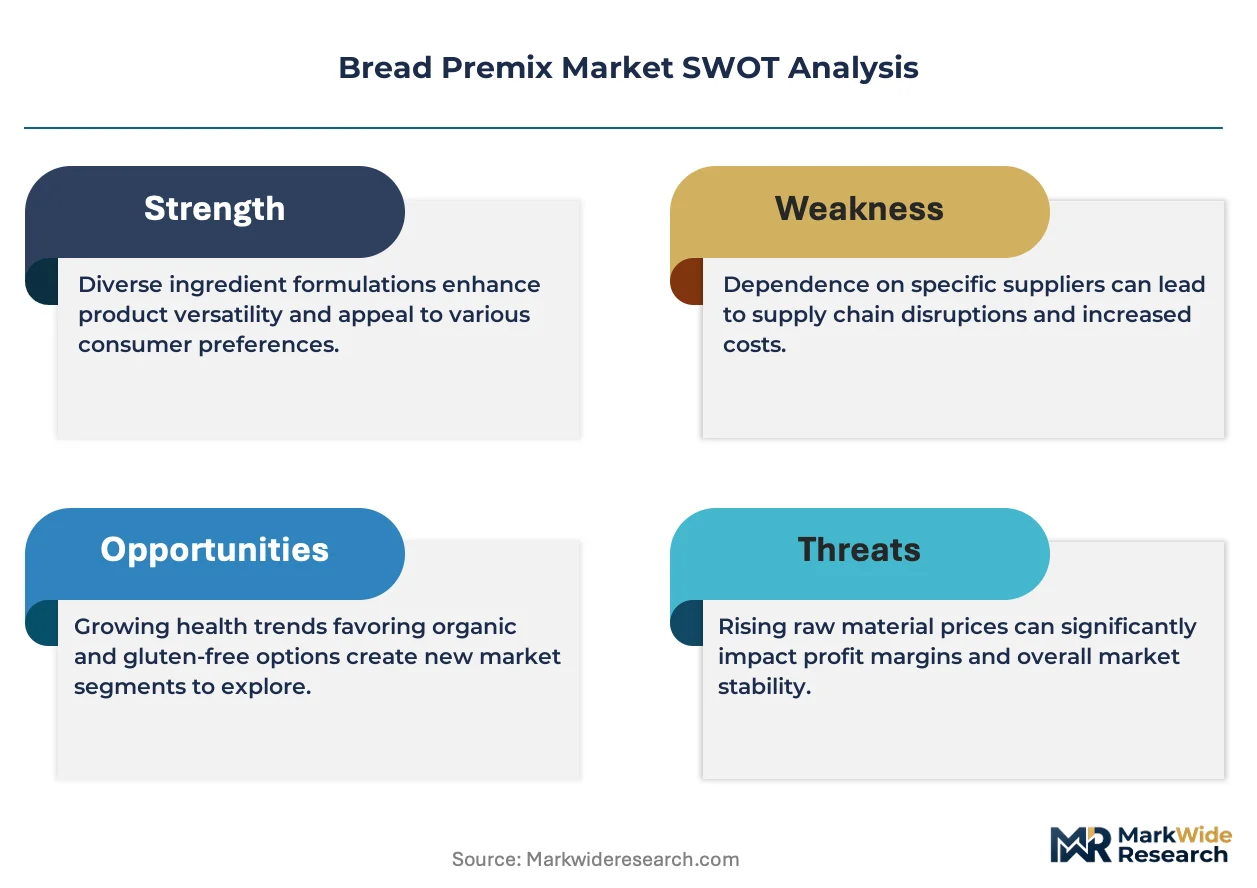
Clean-label mandates under the EU Green Deal and FDA guidance are forcing enzyme-based shelf-life extension to replace legacy preservative chemistries, compressing formulation cycles and redrawing supplier qualification criteria across commercial baking networks.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH frameworks ban specific preservative classes, compelling bakeries toward enzyme-enhanced premix portfolios that command premium positioning.
- Artisan bakery expansion:Specialty bread consumption in Germany sustains procurement of multigrain and sourdough premix variants with extended fermentation stability.
- Asset-light equipment leasing:Mid-sized bakeries deploy leased industrial mixing systems to enter premix categories without facility overhauls.
Market Restraints
- Wheat price volatility:Input cost swings in grain futures compress margin predictability for standard flour-based premix formulations.
- Enzyme supply concentration:Fermentation-derived shelf-life extenders depend on a narrow supplier base concentrated in Western European biotechnology clusters.
- Clean-label technical ceilings:Natural preservation systems face stability limitations in high-moisture applications that synthetic chemistries previously addressed.
Strategic Opportunities
- BIS fortification mandates:India's micronutrient enhancement requirements create compliance-driven demand for vitamin-mineral premix blends in commercial baking.
- Liquid format food service penetration:Ready-to-use wet premixes displace powder formats in quick-service bakery channels where labor minimization dominates purchasing.
- Sourdough competency convergence:Regional milling partnerships combined with controlled fermentation technologies open premium positioning in European artisan segments.
Industry Challenges
- Enzyme formulation expertise gap:Commercial bakeries lack in-house biochemists to optimize dose-response curves for clean-label shelf-life extension.
- Multi-site standardization complexity:Industrial baking networks struggle to maintain output consistency across facilities with varying humidity and altitude conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Premix Market |
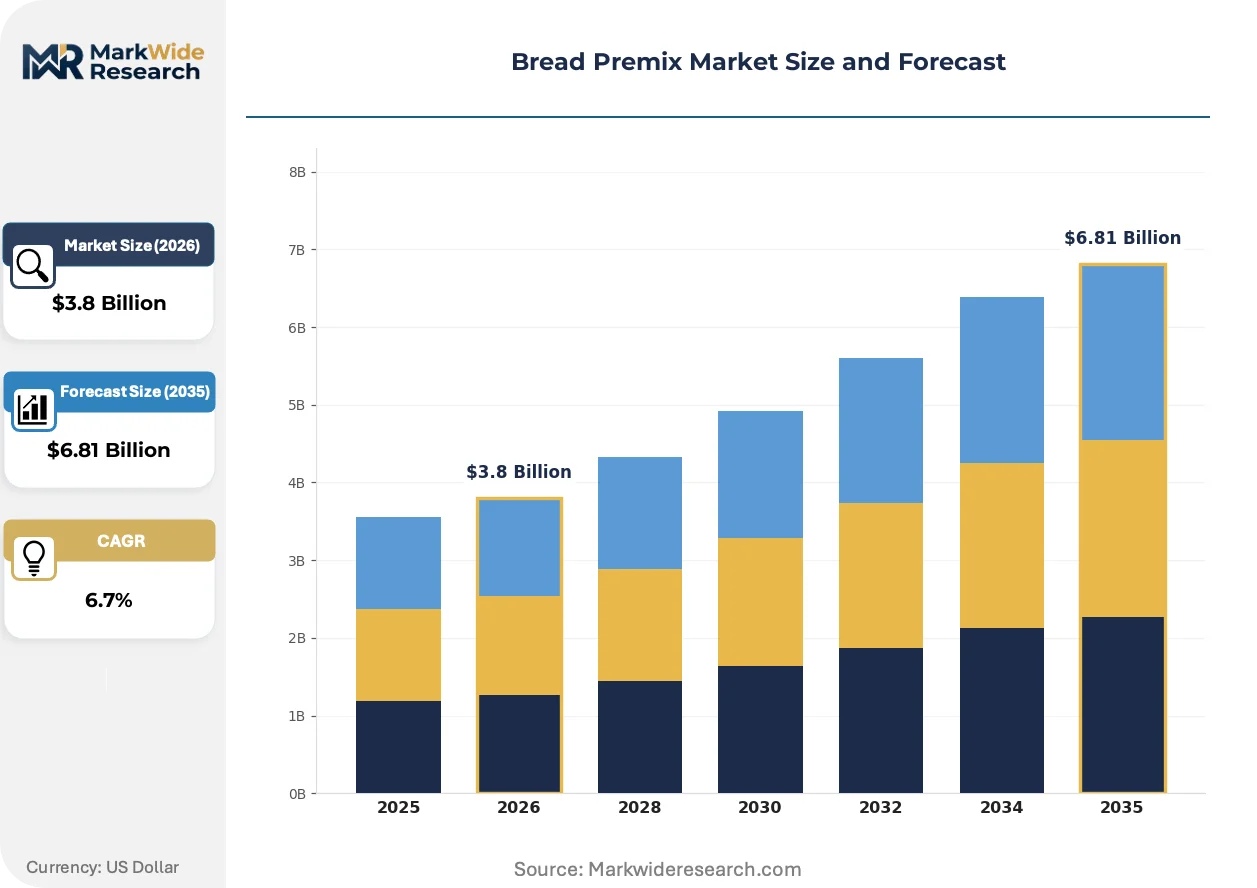
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Gluten-Free, Multigrain, White Bread Application: Commercial Baking, Home Baking, Food Service, Artisan Form: Powder, Liquid, Ready-to-Use, Frozen Distribution Channel: Online, Supermarkets, Specialty Stores, Food Distributors |
| Companies Covered | Bakels Group, Corbion N.V., Puratos Group, Oy Karl Fazer AB, Kerry Group plc, Cargill, Incorporated, Lesaffre, Nisshin Seifun Group Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Premix Market Strategic Shifts
Active fermentation control and taste-modulation technologies are compressing the traditional trade-off between clean-label positioning and sensory performance, enabling new formulation architectures that previously required synthetic intervention.
Fermentation-derived enzyme systems is migrating from niche organic applications into mainstream commercial baking operations. Large-scale industrial bakeries in Germany and the Netherlands are adopting these systems at accelerated procurement cycles. The technology is migrating from premium positioning into cost-competitive standard formulations as supplier scale economies reduce unit costs.
REACH chemical authorization restrictions now prohibit certain propionate and sorbate classes in EU-member bakery applications. Industrial formulators must rebuild preservation architectures around approved enzyme and cultured-wheat alternatives. Powder premix variants bound for German retail channels face the steepest compliance timelines.
Consolidated procurement by multi-site bakery chains is compressing supplier negotiation cycles and unbundling technical service from ingredient supply contracts. Regional distributors lose margin to direct manufacturer relationships as buyers centralize specification authority. This concentration is most visible in French and Italian industrial baking clusters where cooperative purchasing organizations dominate volume allocation.
Bread Premix Market Segmentation
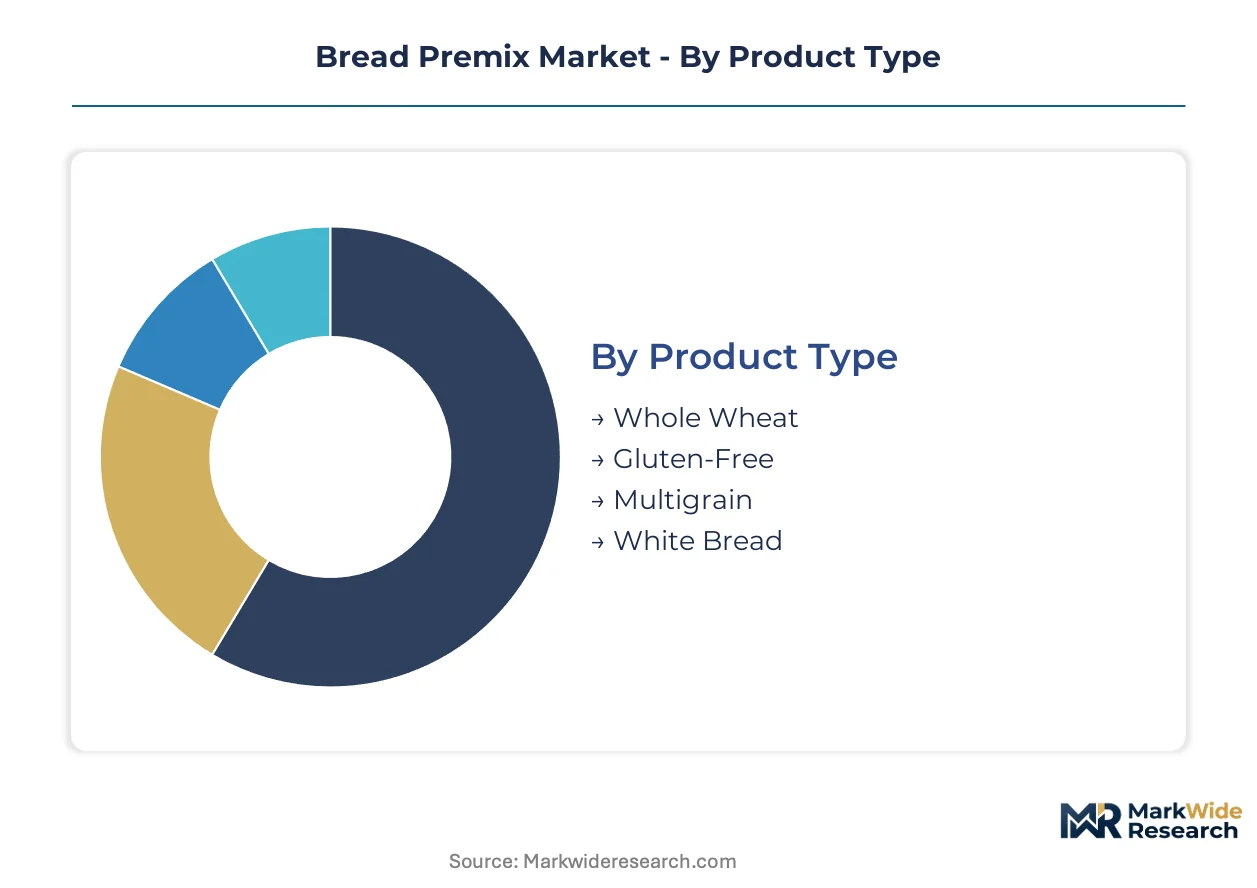
Bread premix segmentation reveals distinct technical service requirements across product architectures. Formulation complexity drives after-sales intensity, with enzyme-enhanced variants demanding sustained technical support versus commodity flour blends.
Product Type:
After-sales-service intensity peaks in enzyme-stabilized and fiber-dense formulations requiring fermentation optimization support.
- Whole Wheat:Fiber content above 12% demands specialized hydration protocols and extended mixing cycles. German industrial bakeries sustain procurement volumes as clean-label positioning commands retail shelf placement premiums.
- Gluten-Free:Hydrocolloid and starch systems replace wheat protein matrices, requiring precise water-binding calibration. North American commercial baking networks concentrate demand here as celiac certification expands distribution access.
- Multigrain:Composite flour systems with added seeds and ancient grains target premium artisan positioning.
- White Bread:Standardized formulations dominate high-volume institutional procurement with minimal technical intervention.
By volume, White Bread leads. By growth pace, Gluten-Free is climbing the fastest.
Application:
Cost tier separation distinguishes capital-intensive commercial operations from labor-minimizing food service deployments.
- Commercial Baking:Multi-site production networks standardize output through centralized premix specification. German and Dutch industrial clusters drive volume as enzyme-based shelf-life extension replaces synthetic preservatives under REACH frameworks.
- Artisan:Extended fermentation protocols and sourdough competency requirements elevate technical service dependence. Specialty consumption in France and Italy sustains premium positioning for small-batch formulations.
- Food Service:Labor-constrained channels favor ready-to-use formats over powder premixes.
- Home Baking:Convenience-oriented retail packaging targets occasional bakers with simplified instruction sets.
Commercial Baking captures the largest revenue pool. Artisan applications show the steepest margin expansion trajectory.
Form:
Volume economics favor powder logistics, while moisture content thresholds determine shelf-stability architecture.
- Powder:Sub-14% moisture specifications enable extended storage and freight efficiency. Institutional procurement across Germany and the Netherlands concentrates here as powder formats integrate with existing dry-ingredient handling systems.
- Liquid:Pre-hydrated systems eliminate mixing stages but constrain distribution radius due to weight and spoilage risk. Quick-service bakery channels in urban France drive adoption where labor minimization overrides freight costs.
- Ready-to-Use:Complete wet formulations target food service environments with zero technical staff.
- Frozen:Par-baked or frozen dough systems extend distribution timelines for remote bakery operations.
Powder dominates tonnage. Liquid formats are gaining share fastest in metropolitan food service corridors.
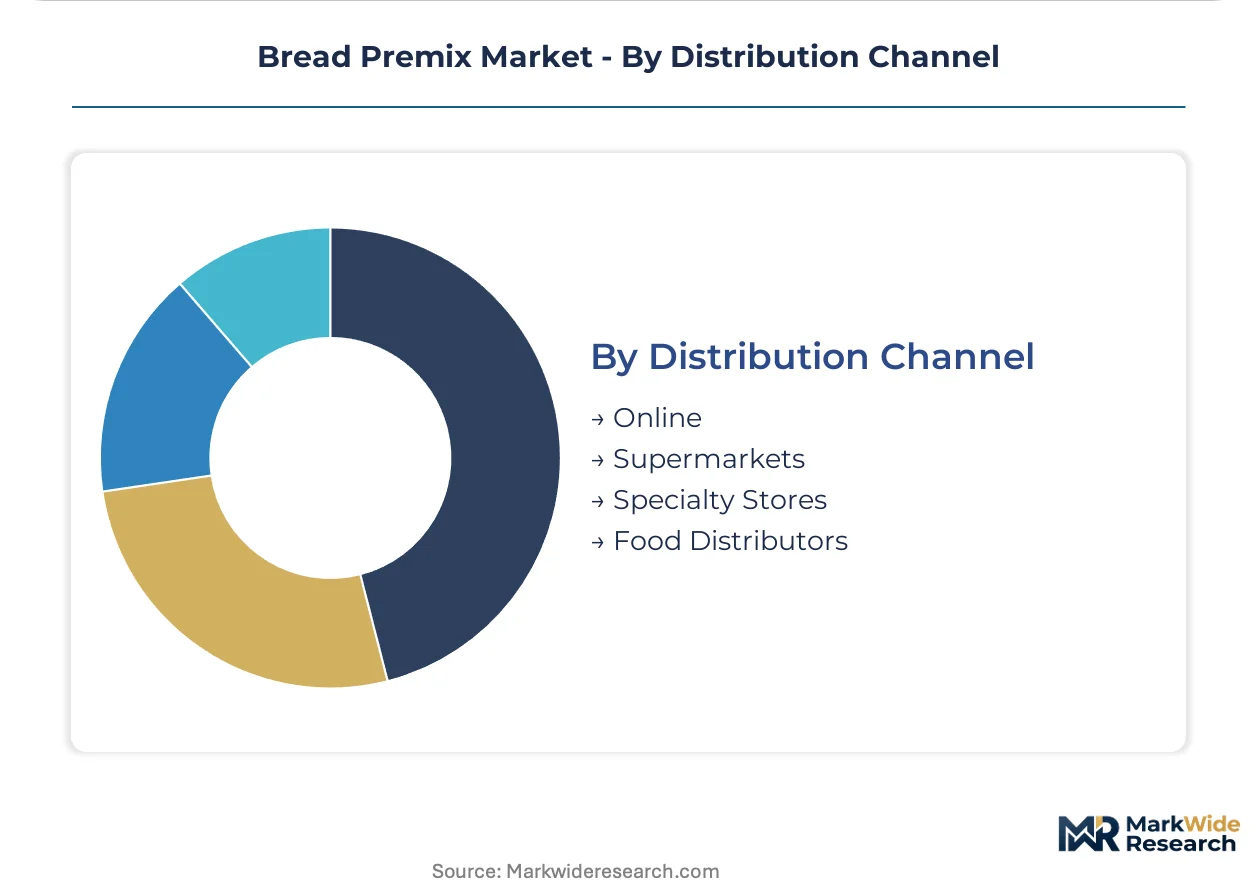
Distribution Channel:
Supply concentration in milling partnerships shapes channel control, with direct manufacturer relationships displacing regional distributors.
- Food Distributors:Consolidated procurement by multi-site bakery chains compresses negotiation cycles and unbundles technical service. French and Italian cooperative purchasing organizations centralize volume allocation through direct manufacturer contracts.
- Supermarkets:Retail shelf placement requires clean-label certification compliance under EU Green Deal and FDA guidance frameworks.
- Specialty Stores:Artisan-focused channels emphasize provenance labeling and small-batch positioning.
- Online:Direct-to-baker platforms emerge for specialty formulations with technical documentation requirements.
Food Distributors move the highest volume tonnage. Online channels are expanding most quickly for niche enzyme-enhanced variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a pronounced trade surplus in European premix formulations, while Asian markets absorb inbound enzyme technologies and North American operations balance domestic milling capacity against specialty ingredient imports.
Germany
Industrial baking clusters in Lower Saxony and Bavaria sustain premium premix procurement volumes. REACH chemical authorization restrictions under the EU Green Deal compel rapid reformulation away from propionate preservatives toward enzyme-based alternatives. The Munich-Stuttgart corridor concentrates sourdough competency centers that supply artisan bakery networks across Central Europe.
United States
Multi-site commercial baking networks standardize output through centralized premix specifications serving retail and food service channels. FDA guidance on whole-grain health claims shapes how manufacturers position multigrain portfolios for supermarket placement. Chicago and Minneapolis milling hubs anchor domestic supply chains while coastal facilities import specialty enzyme systems from European biotechnology clusters.
India
Commercial baking expansion in Maharashtra and Gujarat drives procurement of micronutrient-enhanced blends. BIS fortification mandates create compliance-driven demand for vitamin-mineral premix formulations in institutional bread production. The Mumbai-Pune industrial corridor concentrates mid-sized bakeries adopting asset-light equipment leasing to enter premix categories without capital-intensive facility investment.
France
Artisan bakery traditions sustain demand for extended-fermentation and sourdough premix variants with premium positioning. EU Green Deal clean-label regulations accelerate displacement of synthetic preservatives in formulations bound for retail channels. The Lyon and Paris basin regions host cooperative purchasing organizations that centralize volume allocation through direct manufacturer contracts, compressing regional distributor margins.
Netherlands
Food service and quick-service bakery channels in the Randstad metropolitan cluster favor ready-to-use liquid premix formats where labor minimization overrides freight cost considerations. ECHA frameworks under REACH restrict specific preservative chemistries, compelling reformulation toward enzyme-based shelf-life extension. Rotterdam and Amsterdam distribution hubs facilitate re-export of compliant formulations to neighboring EU member states facing accelerated compliance timelines.
Bread Premix Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in enzyme and fermentation technology. The vendor base organizes around three tiers: multinational ingredient conglomerates with integrated milling and biotechnology capabilities, regional premix formulators serving protected geographic markets, and niche enzyme suppliers licensing shelf-life extension technologies. Consolidation pressures intensify as cooperative purchasing organizations centralize procurement authority. Dominant competitive moves include direct manufacturer relationships displacing regional distributors and fermentation technology licensing agreements that transfer biocatalytic capabilities to industrial baking networks.
Among European biotechnology-anchored players, Corbion N.V., Puratos Group, and Kerry Group plc exemplify distinct competitive archetypes. Corbion occupies a position representing fermentation-derived enzyme specialization with applications in clean-label preservation. Puratos sits within the sourdough competency and regional milling partnership tier, anchoring supply security for artisan-oriented formulations. Kerry Group represents taste-modulation technology integration, occupying a position where sodium reduction capabilities intersect with crust development performance requirements.
| Leading Market Players |
|---|
| Bakels Group |
| Corbion N.V. |
| Puratos Group |
| Oy Karl Fazer AB |
| Kerry Group plc |
| Cargill, Incorporated |
| Lesaffre |
| Nisshin Seifun Group Inc. |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
The Munich-Stuttgart industrial corridor anchors European enzyme supply capacity, where fermentation-derived shelf-life extenders concentrate manufacturing. This geographic clustering grants incumbent biotechnology suppliers substantial leverage over pricing negotiations with commercial baking networks reformulating under REACH chemical restrictions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize input costs against wheat futures volatility. Pricing stratifies across enzyme-enhanced premium tiers, commodity flour-based standard tiers, and private-label economy tiers, with certification grade under EU Green Deal frameworks driving tier separation. Cost compression in standard flour-based formulations is intensifying because grain price hedging costs have escalated. Mid-sized bakeries leasing asset-light mixing equipment exhibit highest price sensitivity, while multi-site industrial networks with centralized procurement demonstrate lowest sensitivity due to volume scale advantages.
Supply Chain Analysis
Export-control regimes under REACH chemical authorization restrictions limit propionate and sorbate preservative flows into EU-member bakery applications, forcing supply chain reconfiguration. Manufacturing concentrates in Germany, the Netherlands, and Belgium, where fermentation biotechnology clusters feed enzyme production. Raw material dependencies center on wheat futures, specialized fermentation substrates, and hydrocolloid stabilizers. Single-source vulnerability pervades the enzyme supplier tier, where Western European biotechnology clusters control shelf-life extension technology. Distribution runs through cooperative purchasing organizations in France and Italy that centralize volume allocation through direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory fragmentation across EU Green Deal, FDA guidance, and BIS fortification mandates creates niche formulation opportunities for specialized premix suppliers. This demand-side shift rewards agility over scale.
For Market Incumbents: Insulate margin position through captive supply of fermentation-derived enzyme technologies and backward integration into regional milling partnerships. The enzyme supply concentration threat from Western European biotechnology clusters demands securing alternative biocatalytic sourcing channels. Capacity addition in India's Maharashtra-Gujarat corridor addresses BIS fortification compliance-driven demand growth. For New Entrants and Emerging Players: Mid-market commercial bakeries in India's Mumbai-Pune corridor represent the most penetrable entry point, where asset-light equipment leasing adoption outpaces technical service infrastructure. Liquid-format food service channels in metropolitan France offer secondary white-space, as labor-minimization purchasing criteria favor ready-to-use wet premixes. A technical documentation and fermentation optimization support go-to-market angle differentiates against commodity flour blend competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzyme formulation specialists with proven clean-label shelf-life extension capabilities. Long-term viability across the projection horizon hinges on regulatory compliance adaptability rather than scale economies. Acquisition targets should demonstrate established supplier qualification with cooperative purchasing organizations. The signal to monitor is REACH chemical authorization expansion beyond current propionate and sorbate restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Milling | Secures wheat supply continuity for German industrial baking clusters facing input volatility. |
| Enzyme Technology Licensing Agreement | Transfers Corbion fermentation capabilities to mid-sized bakeries lacking in-house biochemists. |
| Direct Manufacturer Contract Establishment | Bypasses French and Italian regional distributors compressed by cooperative purchasing centralization. |
| Liquid Format Manufacturing Scale-Up | Captures food service labor-minimization demand in Randstad metropolitan corridors. |
| Micronutrient Fortification Certification Investment | Unlocks BIS compliance-driven procurement in Maharashtra institutional bread production. |
Study Parameters
Operator-level perspectives from plant managers at commercial baking networks, procurement leads at multi-site bakery chains, technical R&D directors at enzyme suppliers, and distribution channel partners anchored the qualitative base. Secondary validation drew from ECHA REACH authorization databases, EU Green Deal regulatory filings, BIS fortification mandate documentation, and customs trade data for wheat and enzyme flows. Bottom-up volume estimates from facility-level capacity assessments triangulated against top-down demand projections from end-use consumption patterns.
Scenario-bracketing around regulatory compliance timelines and grain price volatility bands structured the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, application channel, moisture specification format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to normalized baseline values, with enzyme adoption rates and clean-label reformulation pace serving as industry-specific forecast inputs.
Practitioners should monitor REACH chemical authorization expansion scope and wheat futures volatility spikes for early signals of forecast deviation. Forecasts reflect assumptions regarding regulatory enforcement consistency and fermentation technology scale economies. Material shifts in EU Green Deal clean-label definition evolution or enzyme supplier consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Premix Bread Flour Market
Bakery Products
No-Fat Cake Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Pie Shells Market
Bakery Products
Matcha Cookie Market
Bakery Products
Bakery Flavors Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Baked Foods Market
Bakery Products
Teaseed Cake Market
Bakery Products
Pastry Margarine Market