
 Clean Label Flour Market | 2026-2036
Clean Label Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Flour Market Analysis
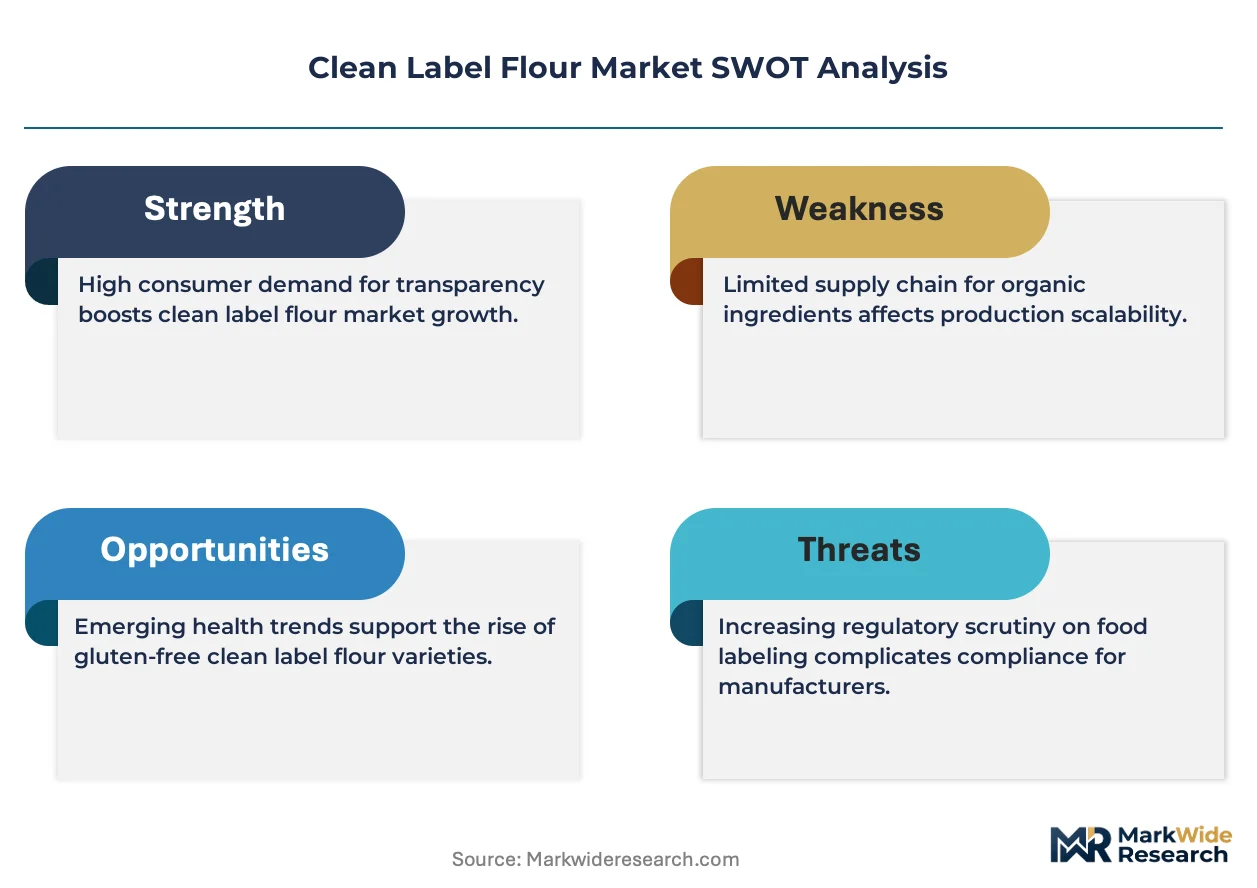
A capital-intensity divergence between integrated millers and specialty ingredient suppliers is rotating competitive advantage toward upstream grain control. Ardent Mills leverages its direct farmer relationships and vertical elevator networks to secure identity-preserved wheat streams. Ingredion Incorporated differentiates through modified clean-label starch-flour hybrids that serve gluten-free and reduced-additive formulations. King Arthur Baking Company anchors premium positioning through certified organic milling and transparent supply chain storytelling that commands shelf price premiums.
Clean label flour denotes milled grain products free from bleaching agents, artificial preservatives, and chemical additives, typically retaining bran and germ fractions or specified ash content ranges that signal minimal processing. The primary commercial purpose is enabling food manufacturers and retail bakers to meet consumer demand for recognizable ingredient statements while maintaining functional performance in dough systems. Whole wheat flour and organic flour occupy the fastest-expanding margin pools as health food stores and specialty grocers expand shelf space for certified offerings. Gluten-free flour competes through ingredient innovation in snack and ready-to-eat meal applications where allergen compliance drives reformulation mandates. Baking applications sustain the largest volume absorption among end-user segments, though food manufacturers are shifting procurement specifications toward clean label inputs for branded retail products.
FDA food labeling requirements and USDA organic certification standards shape product definitions and market access thresholds for domestic suppliers, while EU REACH and EFSA food additive evaluations constrain permissible processing aids in European milling operations. The EU Green Deal's farm-to-fork targets are tightening traceability mandates that favor mills with certified grain origination systems. Stakeholders must monitor evolving regulatory definitions of natural and clean label claims across jurisdictions to avoid enforcement actions that could force packaging revisions or distribution halts.
Market Dynamics
EU Green Deal farm-to-fork traceability mandates are compressing certification timelines and forcing mills to rebuild grain origination systems around identity-preserved supply chains rather than commodity pooling.
Growth Catalysts
- EU Green Deal traceability mandates:Tightening farm-to-fork targets in Europe are accelerating demand for certified clean label flours with verified grain origination documentation.
- Artisan bakery procurement expansion:Specialty bakers across Germany and France are specifying unbleached, minimally processed flours to meet consumer label transparency expectations.
- Stone milling revival:Traditional low-temperature milling techniques are returning to preserve bran integrity and germ fractions that signal minimal processing to health-conscious buyers.
Market Restraints
- Organic wheat input cost volatility:Premium grain premiums fluctuate with weather-driven harvest variability, compressing margin predictability for certified clean label suppliers.
- Regional mill concentration:Specialty clean label capacity clusters in Germany and France, creating supply vulnerability for buyers in peripheral European markets.
- Functional performance gaps:Unbleached flours lacking chemical conditioners deliver shorter shelf stability, limiting adoption in mass retail distribution channels.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania lack established clean label flour infrastructure, creating first-mover positioning for certified suppliers building regional elevator networks.
- Gluten-free formulation convergence:Clean label starch-flour hybrids are opening reformulation pathways in snack and ready-to-eat meal applications where allergen compliance drives ingredient switches.
- Direct-to-bakery distribution platforms:Digital procurement portals are disintermediating traditional ingredient distributors, enabling mills to capture margin through subscription supply contracts.
Industry Challenges
- Certification timeline compression:EU organic and farm-to-fork audits now require 18-24 month grain chain documentation, straining mill administrative capacity.
- Legacy equipment retrofit requirements:Converting conventional mills to identity-preserved handling demands separator upgrades and dedicated storage silos that tie up capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Flour Market |
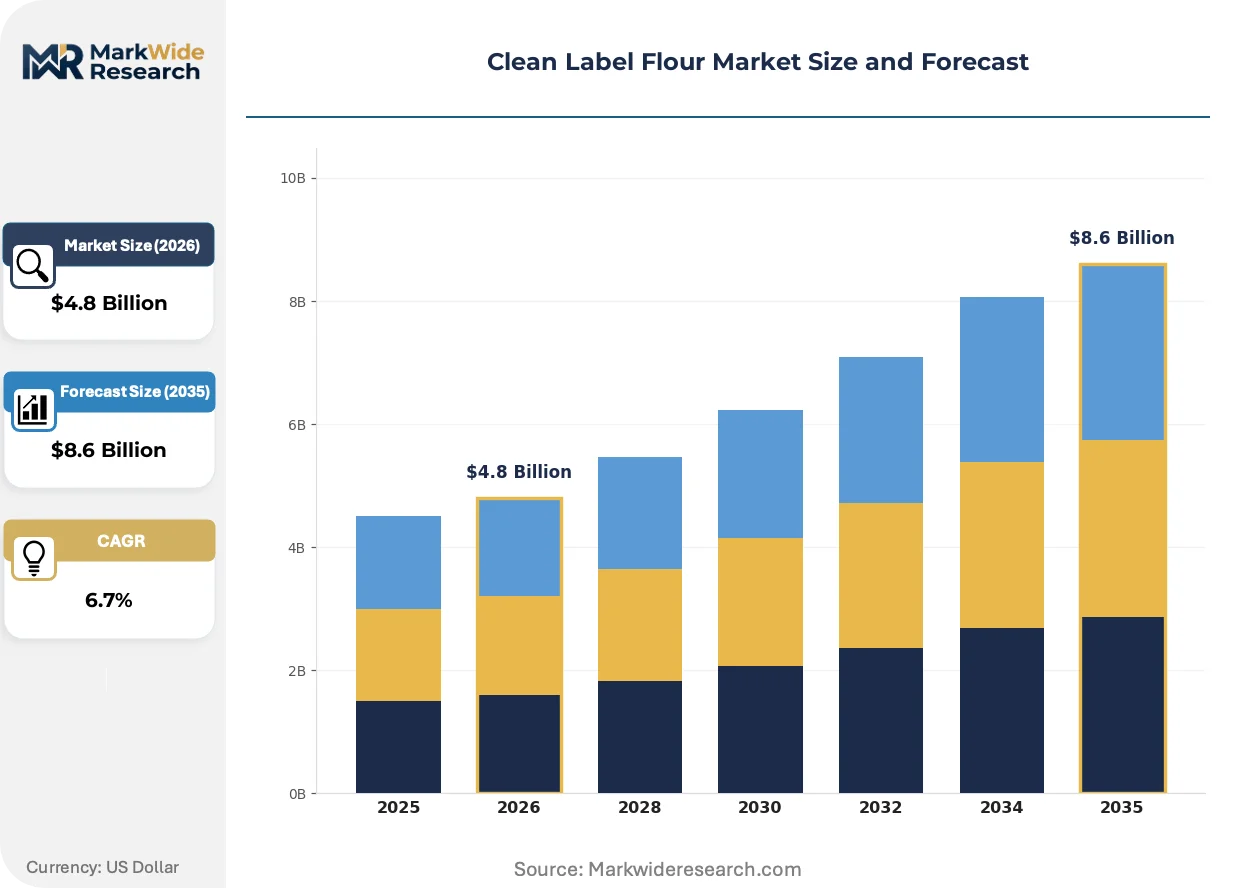
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Flour, Whole Wheat Flour, Gluten-Free Flour, Organic Flour Application: Baking, Cooking, Snacks, Ready-to-Eat Meals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Ardent Mills, Ingredion Incorporated, Cargill Incorporated, Arrowhead Mills, Groupe Limagrain, Codrico Rotterdam B.V., Siemer Specialty Ingredients, Grain Craft Inc., King Arthur Baking Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Flour Market Emerging Trajectories
Clean label flour production is pivoting from additive substitution toward process transparency, with mills investing in blockchain-enabled grain tracking and low-impact milling technologies that preserve nutritional fractions.
Near-infrared spectroscopy coupled with blockchain grain tracking is supplanting paper-based certification in European milling operations. Large artisan bakery chains in Germany and France are mandating real-time origination data for contract flour purchases. This convergence is compressing audit costs while raising barriers for mills lacking digitized supply chain infrastructure.
EU REACH evaluations of food processing aids are tightening permissible additive lists for European milling operations. EFSA assessments of bleaching agents and dough conditioners are accelerating reformulation timelines. Organic and stone-milled flour categories are capturing displaced volume from conventional chemically treated alternatives.
Buyer specification sheets now demand ash content ranges and germ retention percentages rather than generic clean label claims. Food manufacturers are unbundling flour procurement from bundled ingredient distributor contracts to secure direct mill relationships with transparent processing documentation. This shift is most pronounced in Germany where retail label transparency laws create liability exposure for vague ingredient statements.
Clean Label Flour Market Segmentation
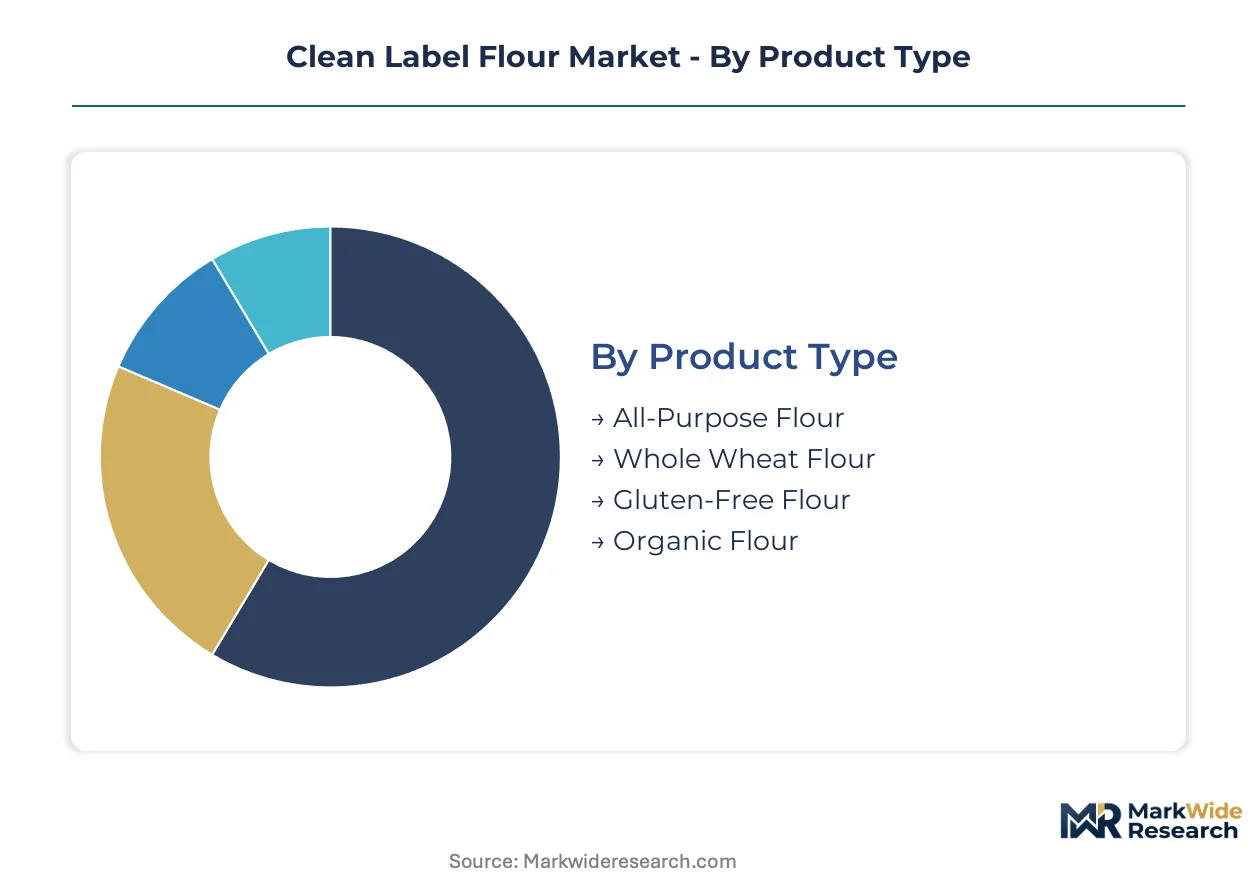
Clean label flour procurement patterns diverge sharply across product specifications and end-use requirements. Manufacturers and distributors must align milling capabilities, certification documentation, and logistics infrastructure against distinct buyer expectations within each segment cluster.
Product Type:
Whole wheat flour and organic flour face intensifying substitution pressure from stone-milled heritage grain alternatives that command premium positioning through narrative differentiation rather than functional superiority.
- All-Purpose Flour:Milled to moderate protein content with bran and germ partially removed, this specification dominates mass retail baking applications. Demand concentrates in North American supermarkets where home bakers prioritize versatility over specialized performance.
- Whole Wheat Flour:Retains complete bran and germ fractions with elevated fiber and mineral content. German artisan bakeries specify certified organic whole wheat for regional bread traditions, driven by EU farm-to-fork traceability mandates that reward documented grain origination.
- Gluten-Free Flour:Formulated from rice, tapioca, or legume starches with binding hydrocolloids. Snack manufacturers in France reformulate allergen-compliant product lines.
- Organic Flour:Certified under USDA or EU organic standards with prohibited synthetic inputs. Health food stores in California and New York expand shelf space.
All-purpose flour anchors the volume base while whole wheat flour gains share at the steepest rate.
Application:
Cost tier stratification separates artisan baking specifications from commodity food manufacturing inputs, with premium formulations absorbing certification and traceability overhead.
- Baking:Encompasses bread, pastry, and confectionery production requiring specific protein content and ash specifications. North American artisan bakeries and industrial bread operations constitute the largest demand pool, with procurement shifting toward unbleached alternatives as FDA labeling scrutiny intensifies.
- Cooking:Includes roux, coating, and thickening applications where functional performance tolerates wider specification variance. Restaurant chains in Italy and Spain specify clean label thickeners for menu transparency compliance.
- Snacks:Crackers, chips, and extruded products demanding precise moisture control and shelf stability. Clean label reformulation accelerates in German snack manufacturing.
- Ready-to-Eat Meals:Frozen and chilled prepared foods requiring extended shelf life without chemical preservatives. French meal kit suppliers specify certified organic flours.
Baking commands the dominant volume position while ready-to-eat meals demonstrate the most rapid specification upgrade trajectory.
Distribution Channel:
Supply concentration in specialty retail creates margin compression for conventional supermarket suppliers lacking differentiated certification portfolios.
- Online Retail:Direct-to-consumer platforms enabling subscription flour deliveries and bulk purchasing. King Arthur Baking Company and regional German mills leverage digital channels to capture margin through transparent supply chain storytelling.
- Supermarkets:Mass retail chains with private label programs and national brand shelf space. US and UK retailers expand clean label flour assortments.
- Health Food Stores:Specialty retailers emphasizing certified organic and non-GMO verification. German Reformhaus chains and US natural grocers drive premium positioning.
- Specialty Stores:Independent bakeries, restaurant supply depots, and ethnic food retailers. Italian and French regional mills dominate through direct relationships.
Supermarkets maintain the foundational volume position while online retail captures the most rapid channel expansion.
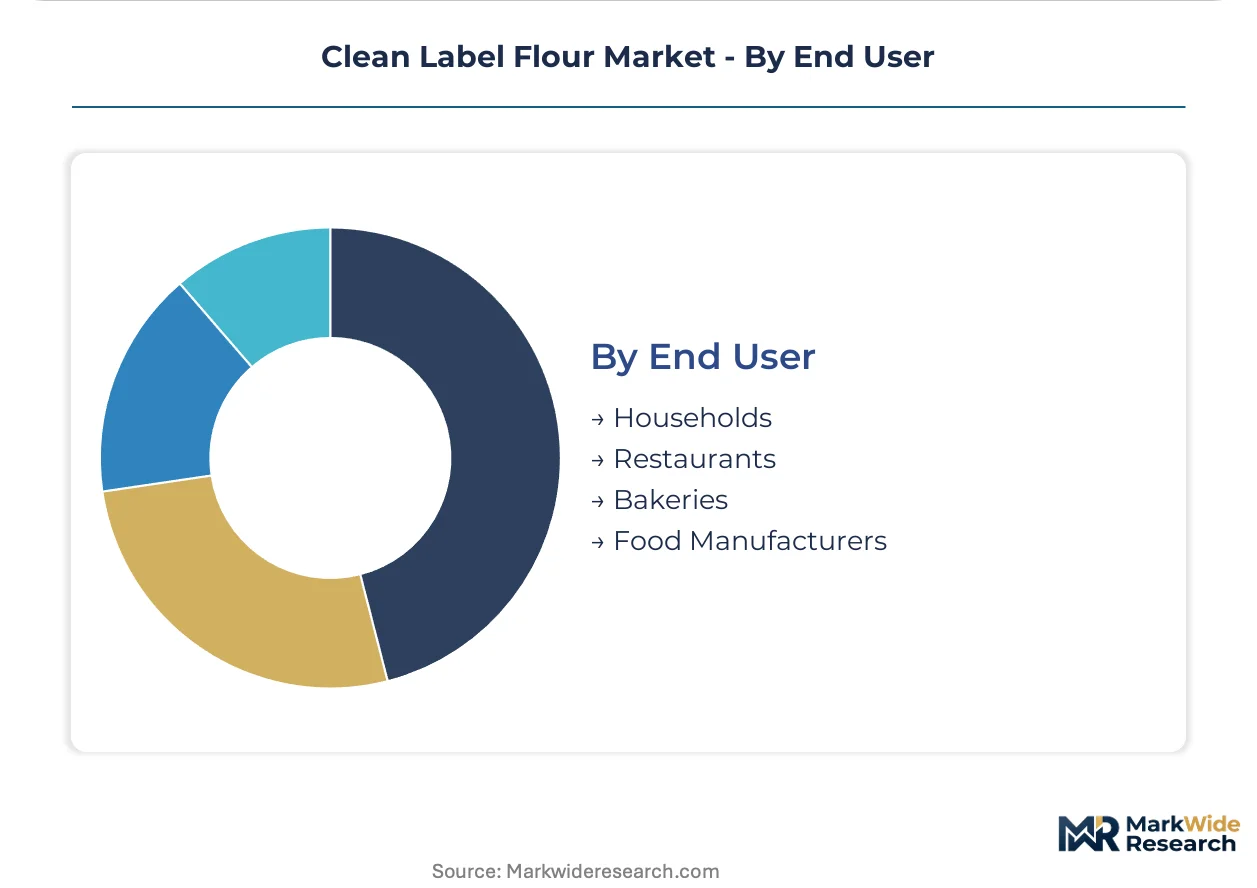
End User:
Customer type determines specification complexity, with food manufacturers demanding batch documentation and bakeries prioritizing consistent performance characteristics.
- Households:Individual consumers purchasing retail-packaged flour for home baking. German and US markets show strongest clean label adoption.
- Restaurants:Foodservice operations specifying flour for in-house bread and dessert programs. Farm-to-table establishments in California and Nordic countries mandate transparent sourcing.
- Bakeries:Artisan and industrial bread producers requiring consistent protein content and fermentation performance. French and German artisan chains specify identity-preserved grain streams.
- Food Manufacturers:Branded packaged goods companies reformulating retail products for clean label positioning. EU manufacturers face compressed timelines from EFSA additive evaluations.
Food manufacturers anchor procurement volume while artisan bakeries drive the steepest specification upgrade adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in clean label flour tilt toward European surplus and North American deficit positions, with specialty mills in Germany and France shipping identity-preserved grain streams to US artisan bakeries while sourcing organic wheat from Black Sea origins.
Germany
Artisan bakery chains in Berlin and Munich specify unbleached stone-milled flours with documented grain origination. The EU Green Deal farm-to-fork targets compress certification timelines to 18-24 months. Regional mills in Bavaria and Baden-Württemberg invest in blockchain-enabled tracking systems to meet traceability mandates.
United States
California and New York health food stores expand certified organic flour shelf space as FDA labeling scrutiny intensifies. USDA organic certification standards shape product definitions and market access thresholds. King Arthur Baking Company anchors premium positioning through Vermont-based transparent supply chain storytelling.
France
Parisian meal kit suppliers and Lyon-based snack manufacturers drive reformulation toward clean label starch-flour hybrids. EFSA evaluations of bleaching agents accelerate additive displacement. Traditional mills in Provence-Alpes-Côte d'Azur revive heritage grain varieties for narrative differentiation.
United Kingdom
London artisan bakeries and Manchester food manufacturers specify unbleached alternatives as retail label transparency expectations rise. UK organic regulations align with EU farm-to-fork traceability protocols. Specialty distributors in the Southeast build direct-to-bakery digital procurement platforms.
Poland
Warsaw-based industrial bakeries and Krakow specialty grocers absorb rising clean label flour volumes from German suppliers. The country lacks established domestic clean label milling infrastructure. Poznan and Wroclaw logistics hubs attract first-mover elevator network investments from certified suppliers.
Clean Label Flour Market Vendor Landscape
Concentration sits with integrated grain handlers and specialty ingredient suppliers rather than commodity millers, creating a tiered structure where upstream elevator control and certification documentation capabilities determine pricing power. The vendor base splits between multinational agribusinesses with farmer-direct origination networks and regional artisan mills leveraging heritage processing narratives. Three archetypes dominate: vertically integrated grain handlers, certified organic specialists, and modified starch-flour hybrid innovators. Competitive moves center on identity-preserved supply chain acquisitions and blockchain traceability platform deployments.
Within the integrated handler archetype, Ardent Mills and Cargill Incorporated occupy positions defined by elevator network scale and direct farmer contracting relationships. King Arthur Baking Company exemplifies the certified organic specialist tier through transparent supply chain storytelling. Ingredion Incorporated represents the hybrid innovation vector, anchoring reformulation capabilities for gluten-free and reduced-additive applications.
| Leading Market Players |
|---|
| Ardent Mills |
| Ingredion Incorporated |
| Cargill Incorporated |
| Arrowhead Mills |
| Groupe Limagrain |
| Codrico Rotterdam B.V. |
| Siemer Specialty Ingredients |
| Grain Craft Inc. |
| King Arthur Baking Company |
| Others |
Supply Flow & Price Mechanics
Stone-milled heritage grain substitution for conventional whole wheat is redrawing procurement geography toward Bavarian and Baden-Württemberg mills while inflating premium tier spreads against commodity all-purpose benchmarks.
Pricing Analysis
Industrial food manufacturers anchor contract-based long-term offtake structures that stabilize input costs against organic wheat spot volatility. Price differentiation separates certified organic tiers with 18-24 month farm-to-fork documentation from unbleached conventional grades and economy commodity pools. Cost compression in the standard tier is intensifying because German Reformhaus chains are consolidating supplier lists around transparent origination storytelling. Artisan bakeries demonstrate lowest price sensitivity while mass retail private-label buyers squeeze margin through volume concentration.
Supply Chain Analysis
Just-in-time flour delivery dominates artisan bakery procurement, though strategic grain stockpiling is returning among integrated millers buffering against Black Sea organic wheat harvest variability. Supply concentrates in Germany, France, and the United States, with Polish and Romanian markets drawing from German elevator networks. Raw material flows hinge on identity-preserved wheat streams, certified organic acreage, and heritage grain seed stocks. Single-source vulnerability runs through concentrated Bavarian milling capacity. Distribution runs through direct-to-bakery digital portals and specialty ingredient distributors serving food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal regulatory entrenchment creates defensive moats around mills with certified grain origination systems, as 18-24 month documentation timelines lock out opportunistic entrants lacking administrative infrastructure.
For Market Incumbents: Consolidate identity-preserved elevator networks in Poland and Romania before certification mandates spread eastward. Acquire blockchain-enabled traceability platforms to compress audit costs against administrative capacity constraints. Backward integration into heritage grain seed programs secures narrative differentiation as stone-milled alternatives displace conventional whole wheat.
For New Entrants and Emerging Players: Differentiate on direct-to-bakery subscription supply contracts that disintermediate traditional distributors. Target Warsaw and Krakow industrial bakeries lacking domestic clean label milling infrastructure. Lead with transparent processing documentation and real-time origination data portals that German artisan chains now mandate.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated grain handlers with farmer-direct origination networks. Long-term viability rests on upstream elevator control and certification documentation capabilities rather than commodity milling scale. Watch EFSA additive evaluation timelines as inflection indicators accelerating reformulation-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Identity-Preserved Elevator Network Expansion | Secures certified grain streams that EU Green Deal traceability mandates now require. |
| Blockchain Traceability Platform Deployment | Compresses 18-24 month audit timelines while raising barriers for undigitized competitors. |
| Heritage Grain Seed Program Investment | Captures premium positioning as stone-milled alternatives command narrative differentiation. |
| Direct-to-Bakery Digital Procurement Launch | Disintermediates distributors and captures margin through subscription supply contracts. |
| Organic Certification Capacity Buildout | Meets compressed farm-to-fork timelines that strain mill administrative capacity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across milling executives, artisan bakery procurement heads, food manufacturer R&D directors, and specialty ingredient distributors. Secondary validation drew from EU organic certification registries, USDA National Organic Program filings, EFSA food additive evaluation dockets, and German Federal Office of Consumer Protection traceability disclosures. Bottom-up volume triangulation against top-down value estimates anchored segmentation outputs.
Across the projection horizon, the analytical framework modeled product type specifications, application performance requirements, distribution channel economics, and end-user procurement sophistication. CAGRs were derived from segment-level growth trajectory synthesis. Forecast inputs incorporated organic wheat acreage expansion rates, EU farm-to-fork implementation timelines, and stone-milling capacity utilization trends.
Material uncertainties — regulatory redefinition of natural claims, weather-driven organic harvest volatility, and EFSA processing aid prohibitions — sit outside the modeled envelope. Forecasts reflect documented assumptions that could require revision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mulberry Leaf Extract Market
Ingredients
Global Amaranth Oil Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Millet Protein Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Calcium Caseinate Market
Ingredients
Casein and Caseinates Market
Ingredients
PHO Oils Market
Ingredients
Modified Flour Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Truffle Oil Market
Ingredients
South America Fruit and Vegetable Ingredients Market