
 Mineral Premix Market | 2026-2036
Mineral Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Premix Market Foresight
Pharmaceutical-grade mineral formulation expertise is reorganizing competitive dynamics in the premix sector as compounders face shortages of nutritionists trained in bioavailability optimization. DSM-Firmenich leverages its integrated vitamin-mineral platform to supply precision premixes for high-performance livestock systems. Cargill anchors North American supply through captive distribution networks serving integrated pork and poultry producers. BASF SE competes on chelated mineral technology, sustaining premium positioning in ruminant applications where absorption efficiency determines herd productivity outcomes.
Mineral premix denotes a homogeneous blend of trace elements including zinc, manganese, copper, iron, selenium, and iodine formulated at concentrations between 0.1% and 10% inclusion rates for incorporation into complete feeds or nutritional supplements. Manufacturers employ sequential dilution mixing with carriers such as limestone or rice hulls to prevent segregation and ensure uniform micronutrient delivery across batch volumes. Poultry premix dominates value generation due to short production cycles and intensive mineral supplementation protocols in broiler and layer operations. Aquaculture premix represents the fastest-expanding category as shrimp and salmon producers adopt mineral-fortified extruded feeds to address skeletal development and immune function in high-density systems. Powder form occupies the largest share of manufacturing output, though liquid premix gains traction in automated dosing systems at commercial feed mills seeking reduced dust exposure and improved handling precision.
FDA's Center for Veterinary Medicine enforces current Good Manufacturing Practice regulations for medicated feed and premix facilities operating in the United States, while the EU Feed Hygiene Regulation mandates HACCP-based hazard control across all premix production stages. India's FSSAI and BIS standards govern mineral fortification limits in nutritional supplements, creating compliance complexity for exporters serving multiple regulatory jurisdictions. Stakeholders must monitor evolving maximum permitted levels for copper and zinc in livestock diets as environmental accumulation concerns prompt regulatory tightening across major producing regions.
Market Dynamics
Bioavailability optimization expertise is concentrating manufacturing capacity among compounders employing chelation technology and pharmaceutical-grade formulation protocols, squeezing regional blenders dependent on basic mineral sulfates.
Growth Catalysts
- EU Feed Hygiene Regulation traceability mandates:Enforcement of HACCP-based hazard control across premix production stages compels facility upgrades that favor scaled manufacturers with integrated quality systems.
- Shrimp aquaculture intensification:High-density systems in Southeast Asia require mineral-fortified extruded feeds addressing skeletal development and immune function, expanding premix inclusion rates.
- Precision livestock farming adoption:Sensor-enabled individual animal monitoring in North American dairy operations creates demand for customized mineral blends matched to real-time metabolic data.
Market Restraints
- Copper and zinc input cost volatility:Price swings in base metal markets squeeze margin predictability for standard premix formulations using inorganic sulfate sources.
- Pharmaceutical-grade mineral supplier concentration:Limited qualified sources for chelated forms create single-source vulnerability in high-performance ruminant premix supply chains.
- Environmental accumulation limits:Tightening maximum permitted levels for copper and zinc in livestock diets across Brazil and EU jurisdictions force formula reformulation and compliance costs.
Strategic Opportunities
- Automated liquid dosing systems:Commercial feed mills in Germany and Netherlands are retrofitting powder handling infrastructure to capture reduced dust exposure and improved handling precision benefits.
- India nutritional supplement export corridor:FSSAI and BIS standards alignment creates compliance infrastructure for mineral premixes entering human nutrition applications.
- Carbon-accounting feed certification:EU Green Deal farm-to-fork requirements position low-carbon mineral sourcing as a procurement differentiator for integrated poultry operations.
Industry Challenges
- Nutritionist bioavailability specialization gap:Shortage of trained formulators capable of optimizing absorption efficiency in ruminant applications limits premium premix development velocity.
- Sequential dilution mixing capex requirements:Prevention of mineral segregation in high-volume batch production demands precision equipment investments that strain mid-tier compounders.
- Multi-jurisdiction certification complexity:Exporters serving US FDA, EU EFSA, and India FSSAI markets face divergent maximum fortification limits and documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Premix Market |
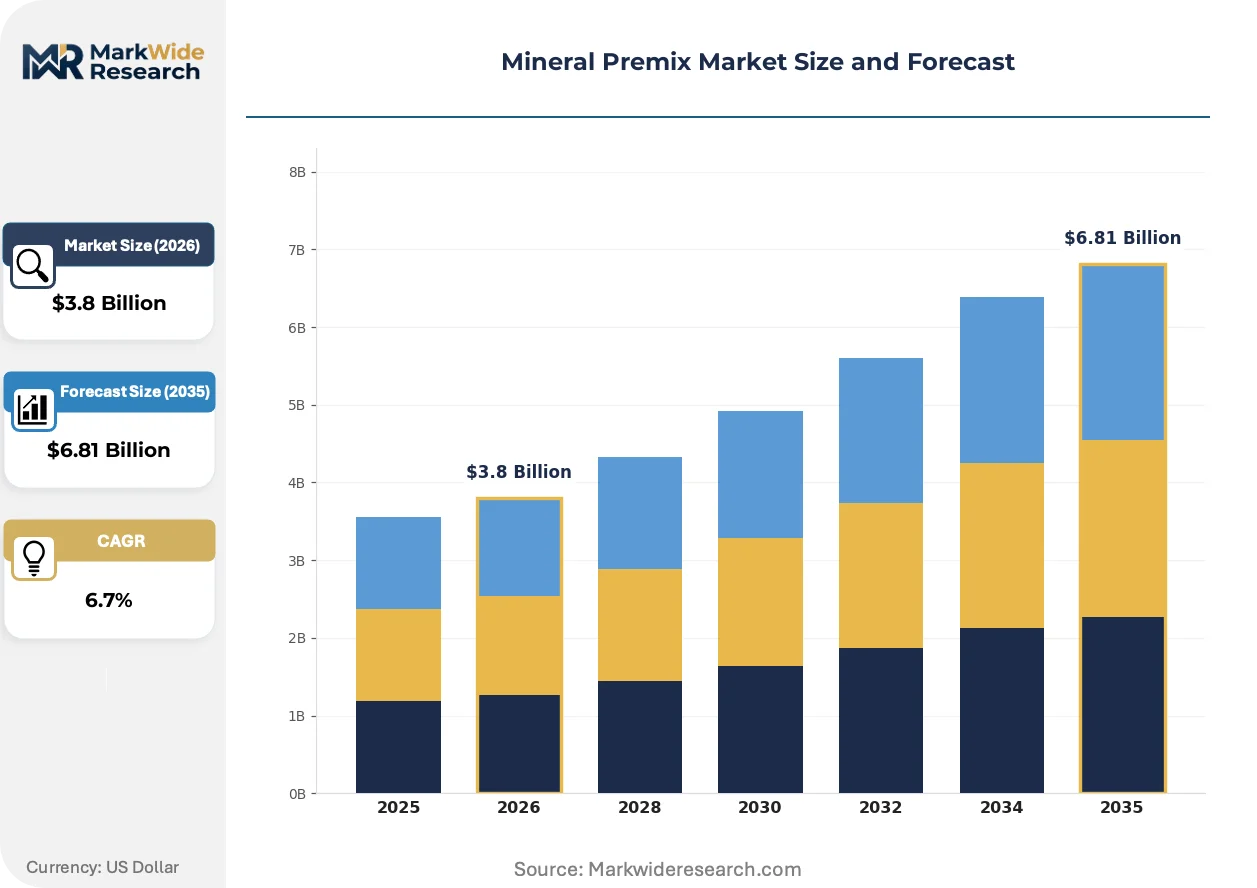
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Premix, Swine Premix, Ruminant Premix, Aquaculture Premix Form: Powder, Granular, Liquid, Tablet End User: Farmers, Feed Manufacturers, Nutritionists, Veterinarians Application: Animal Feed, Nutritional Supplements, Fortification, Premix Export |
| Companies Covered | Archer Daniels Midland Company (ADM), DSM-Firmenich, Glanbia PLC, Cargill, Nutreco, BASF SE, Corbion, Barentz, SternVitamin GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Premix Market Shifts & Advancements
Chelated mineral technology is displacing inorganic sulfate formulations as the default specification in performance-sensitive livestock segments, compressing the addressable market for basic premix suppliers.
Organic trace mineral complexes incorporating glycinate and methionine hydroxy analogue chelates are displacing zinc oxide and copper sulfate in swine and poultry premixes. Integrated operations in Denmark and the Netherlands specify these forms for improved feed conversion metrics. The technology is displacing commodity mineral suppliers from premium contract negotiations with top-ten protein producers.
REACH authorization requirements for zinc oxide veterinary medicinal uses are forcing reformulation toward feed-grade mineral premix alternatives in EU member states. The regulation redirects demand toward chelated zinc sources with established feed additive registrations. Poultry premix manufacturers serving German and French markets are accelerating dossier preparation for novel mineral forms.
Direct-to-farm premix procurement is consolidating previously fragmented distributor relationships as Brazilian and US cattle finishing operations centralize nutrition decisions at headquarters level. Traditional independent feed dealer networks lose volume to captive supply agreements with integrated protein companies. This concentration is most visible in Mato Grosso feedlot clusters and Iowa-Minnesota pork production belts.
Mineral Premix Market Segmentation
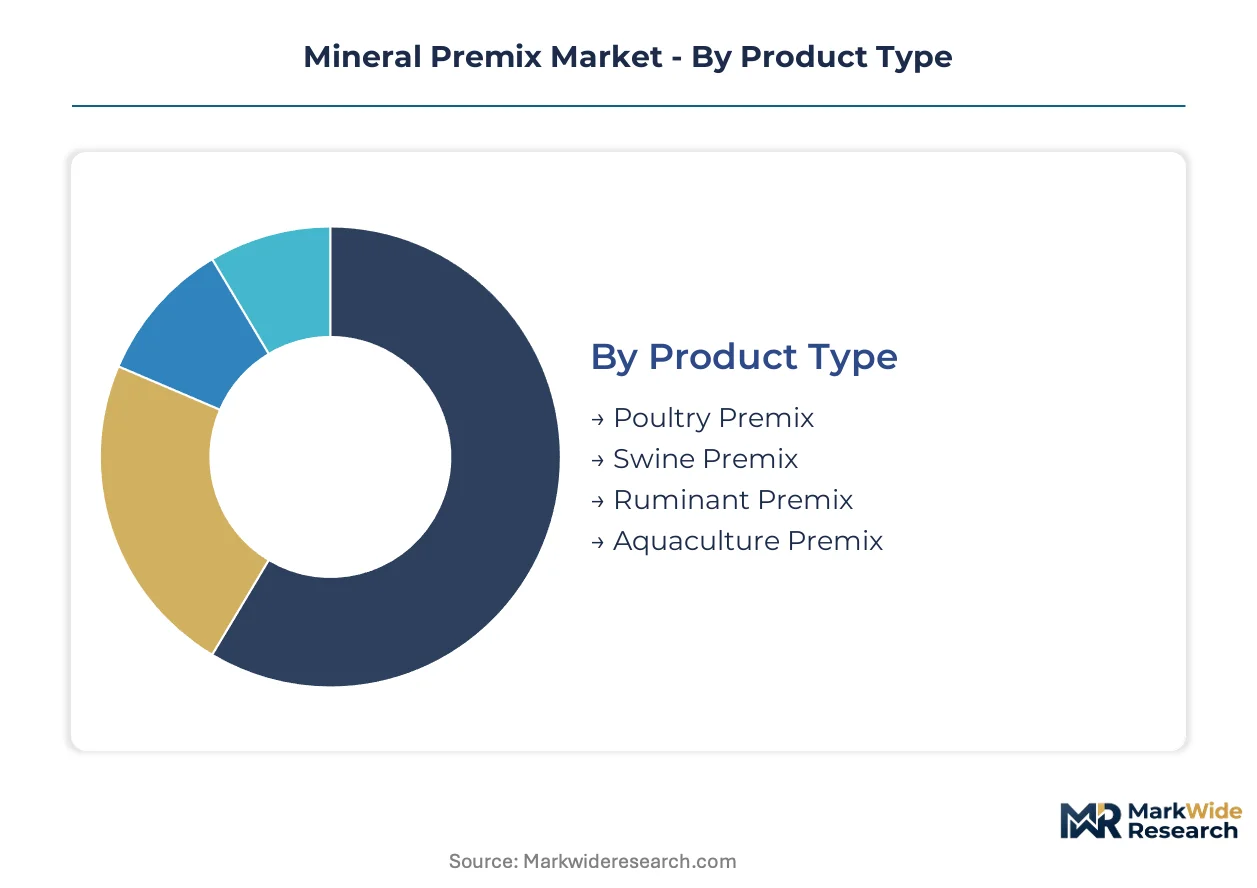
Mineral premix segmentation reflects divergent bioavailability requirements across livestock species and operational scales. Formulation complexity intensifies where precision dosing meets automated handling systems. End-user sophistication determines whether premixes flow through integrated supply chains or fragmented dealer networks.
Product Type:
Substitution pressure from organic trace mineral complexes reshapes value capture across species-specific formulations, with inorganic sulfate premixes facing margin compression in performance-sensitive segments.
- Poultry Premix:Intensive zinc, manganese, and selenium blends formulated for rapid-turn broiler and layer operations. Demand clusters in China's Shandong and Guangdong provinces where integrated poultry operations drive bulk procurement of customized mineral blends. Short production cycles amplify mineral supplementation frequency.
- Aquaculture Premix:Mineral-fortified extruded feeds addressing skeletal development and immune function in high-density shrimp and salmon systems. Southeast Asian producers in Vietnam and Indonesia are expanding inclusion rates as stocking densities intensify. This category climbs the fastest as marine and brackish-water operations professionalize nutrition protocols.
- Swine Premix:Copper and zinc-optimized formulations for nursery and finishing phases, increasingly specifying glycinate chelates over sulfates.
- Ruminant Premix:Cobalt, selenium, and iodine blends for cattle and sheep, with absorption efficiency determining herd productivity outcomes in Brazilian finishing operations.
Poultry premix retains volume leadership; aquaculture premix holds the steepest expansion curve.
Form:
Cost tier stratification separates commodity powder production from precision-engineered liquid systems, with mid-tier granulation capturing price-sensitive automation upgrades.
- Powder:Sequential dilution mixing with limestone or rice hull carriers produces homogeneous blends at 0.1% to 10% inclusion rates. This form dominates manufacturing output across Indian and Brazilian feed mill infrastructure where capital constraints limit liquid system adoption.
- Liquid:Automated dosing systems at commercial feed mills in Germany and Netherlands capture reduced dust exposure and improved handling precision. Retrofit investments favor scaled compounders with integrated quality infrastructure.
- Granular:Anti-caking formulations for humid climates and extended storage, prevalent in Southeast Asian distribution networks.
- Tablet:Precision-dosed mineral supplements for smallholder and veterinary channel distribution, particularly in African and South Asian markets with limited mixing equipment.
Powder form commands installed base dominance; liquid systems gain share fastest in automated mill retrofits.
End User:
Customer type fragmentation concentrates procurement authority at headquarters level for integrated operations while fragmenting demand across independent dealer networks serving dispersed producers.
- Feed Manufacturers:High-volume compounders sourcing mineral premixes for integration into complete feeds, with captive supply agreements replacing traditional distributor relationships in North American pork and poultry belts.
- Farmers:Direct-to-farm procurement consolidating previously fragmented relationships as Brazilian and US cattle finishing operations centralize nutrition decisions.
- Nutritionists:Specialized formulators demanding pharmaceutical-grade mineral expertise and bioavailability optimization protocols, particularly for high-performance dairy systems.
- Veterinarians:Therapeutic mineral supplementation channels, constrained by REACH authorization requirements for zinc oxide medicinal uses in EU member states.
Feed manufacturers anchor volume throughput; nutritionist-directed procurement expands most quickly in precision livestock systems.
Application:
Application maturity varies from commoditized animal feed fortification to emerging carbon-accounting certification requirements reshaping procurement specifications.
- Animal Feed:Core incorporation into complete feeds and nutritional supplements, governed by FDA current Good Manufacturing Practice regulations in the United States and EU Feed Hygiene Regulation traceability mandates.
- Fortification:Human nutrition applications subject to India's FSSAI and BIS standards, creating compliance infrastructure for mineral premix export corridors.
- Nutritional Supplements:Standalone mineral products for deficiency correction, with multi-jurisdiction certification complexity facing exporters serving US, EU, and Indian markets simultaneously.
- Premix Export:Cross-border trade requiring alignment of maximum fortification limits and documentation standards across divergent regulatory jurisdictions.
Animal feed absorbs the majority of volume; fortification applications for human nutrition gain share fastest through standards harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Center for Veterinary Medicine enforces current Good Manufacturing Practice regulations for medicated feed and premix facilities operating in the United States. Brazil's ANVISA and Ministry of Agriculture govern mineral fortification standards for livestock nutrition. China's SAMR and GB standards oversee feed additive quality across provincial manufacturing zones.
United States
Integrated pork and poultry producers in Iowa-Minnesota belts drive bulk procurement of customized mineral blends through captive supply agreements. FDA's cGMP regulations mandate traceability infrastructure that favors scaled compounders with integrated quality systems. Commercial feed mills in the Corn Belt retrofit powder handling infrastructure to capture automated liquid dosing precision benefits.
Brazil
Cattle finishing operations in Mato Grosso feedlot clusters expand mineral premix usage to improve feed conversion efficiency in intensive systems. ANVISA and MAPA regulations govern maximum permitted levels for copper and zinc as environmental accumulation concerns prompt compliance investments. São Paulo and Paraná states anchor distribution networks serving integrated protein companies centralizing nutrition decisions at headquarters level.
China
Integrated poultry operations in Shandong and Guangdong provinces drive bulk procurement of customized mineral blends for rapid-turn broiler and layer systems. SAMR's GB standards and feed additive quality protocols create compliance infrastructure for domestic and export-oriented manufacturers. Yangtze River Delta feed mill clusters professionalize nutrition protocols as stocking densities intensify mineral supplementation frequency.
Germany
Commercial feed mills in Lower Saxony and Bavaria retrofit powder handling infrastructure to capture reduced dust exposure and improved handling precision from automated liquid dosing systems. EU Feed Hygiene Regulation mandates HACCP-based hazard control across premix production stages, compelling facility upgrades. REACH authorization requirements for zinc oxide veterinary medicinal uses force reformulation toward feed-grade mineral premix alternatives.
India
Nutritional supplement exporters align FSSAI and BIS standards to create compliance infrastructure for mineral premixes entering human nutrition applications. Maharashtra and Gujarat pharmaceutical-grade mineral formulators serve domestic livestock operations and export corridors simultaneously. The country's national feed regulator governs maximum fortification limits that diverge from US and EU jurisdictions, creating multi-certification complexity.
Mineral Premix Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in mineral premix supply. Pharmaceutical-grade formulation expertise and chelation technology capabilities concentrate manufacturing capacity among compounders with bioavailability optimization protocols. Three archetypes define competitive positioning: integrated nutrition platforms with captive distribution, pharmaceutical-grade mineral specialists, and regional blenders dependent on basic sulfate sources. Consolidation pressures favor backward integration into mineral sourcing and technology licensing partnerships for novel chelate forms.
Within the integrated nutrition platform tier, DSM-Firmenich and Cargill exemplify archetypes combining vitamin-mineral integration with scaled distribution infrastructure. BASF SE occupies a position representing pharmaceutical-grade mineral technology and chelated form development. These three anchors demonstrate how formulation sophistication and supply chain control separate premium positioning from commodity blending operations.
| Leading Market Players |
|---|
| Archer Daniels Midland Company (ADM) |
| DSM-Firmenich |
| Glanbia PLC |
| Cargill |
| Nutreco |
| BASF SE |
| Corbion |
| Barentz |
| SternVitamin GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
EU Feed Hygiene Regulation traceability mandates gate both supplier qualification and price differentiation simultaneously, as HACCP-compliant facilities command premium positioning while non-compliant regional blenders face exclusion from integrated procurement channels. Pharmaceutical-grade mineral certification creates a parallel pricing tier where chelated formulators capture margin premiums over commodity sulfate suppliers.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated protein companies and scaled compounders, locking in volume commitments that insulate premium suppliers from base metal spot volatility. Price differentiation stems from chelation technology certification and volume scale, with glycinate-complex premixes commanding substantial premiums over inorganic sulfates. Cost compression in standard formulations is intensifying because copper and zinc input volatility squeezes margin predictability for regional blenders. Independent feed dealers show highest price sensitivity, while nutritionist-directed dairy operations demonstrate lowest sensitivity due to performance-linked ROI justification.
Supply Chain Analysis
Pharmaceutical-grade mineral feedstock qualification serves as the critical chokepoint constraining premix manufacturing expansion, with limited qualified sources for chelated zinc and copper glycinates creating single-source vulnerability. Supply concentrates in China for mineral sulfate refining, Germany for chelation technology, and India for pharmaceutical-grade formulation infrastructure. Raw material dependencies include zinc oxide, copper sulfate, and organic ligand precursors such as methionine hydroxy analogue. Tariff exposure on Chinese mineral inputs threatens cost structures for European compounders. Distribution runs through captive supply agreements with integrated pork and poultry producers, displacing traditional independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision livestock farming sensor integration is accelerating mineral premix market disruption, as real-time metabolic data demands trigger reformulation velocity that outpaces legacy compounder R&D cycles.
For Market Incumbents: Consolidate backward integration into chelated mineral sourcing to secure supply continuity against pharmaceutical-grade feedstock concentration. Acquire nutritionist bioavailability specialization capabilities through targeted hiring or technology licensing, defending against precision-formulation entrants. Expand HACCP-compliant manufacturing footprint in Mato Grosso and Iowa-Minnesota belts to capture direct-to-farm procurement consolidation.
For New Entrants and Emerging Players: Automated liquid dosing system retrofit services represent a service-layer gap where incumbents under-serve mid-tier German and Dutch feed mills seeking dust-reduction compliance. Target aquaculture premix formulation for Southeast Asian shrimp producers, the fastest-expanding category with lower incumbent saturation than poultry. Pursue regulatory dossier preparation partnerships with established EU compounders as a go-to-market angle for novel mineral form market entry.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated liquid dosing infrastructure, favoring scaled platform acquisitions over greenfield capacity builds. Mid-tier compounders with captive nutritionist talent and regional regulatory certifications present viable acquisition targets for platform consolidation. Monitor REACH authorization timelines for zinc oxide veterinary uses as a signal for feed-grade mineral premix demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelated Mineral Sourcing | Secures supply continuity against pharmaceutical-grade feedstock concentration in Germany and China. |
| HACCP Facility Certification Investment | Unlocks EU Feed Hygiene Regulation compliance for integrated poultry procurement contracts. |
| Aquaculture Premix Formulation Development | Captures fastest-expanding segment as Vietnam and Indonesia intensify shrimp stocking densities. |
| Automated Liquid Dosing System Deployment | Addresses German and Dutch feed mill retrofit demand for dust exposure reduction. |
| Nutritionist Bioavailability Specialization Hiring | Closes formulation capability gaps constraining premium ruminant premix development velocity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with feed mill procurement directors, livestock nutritionists, pharmaceutical-grade mineral suppliers, and regulatory compliance officers at scaled compounders. Secondary validation drew from FDA Center for Veterinary Medicine cGMP guidance documents, EU Feed Hygiene Regulation implementation reports, EFSA feed additive safety assessments, and ANVISA mineral fortification standards. Bottom-up volume modeling across species-specific premix formulations triangulated with top-down value estimates from integrated protein company supply chain disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including livestock species, mineral form technology, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from trend extrapolation of premix inclusion rate intensification, species production cycle dynamics, and automated dosing system adoption curves. Forecast inputs incorporated shrimp aquaculture stocking density trajectories and precision livestock farming sensor penetration rates in North American dairy operations.
Forecasts assume regulatory continuity in FDA cGMP, EU Feed Hygiene Regulation, and REACH authorization regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include tightening maximum permitted copper and zinc levels in livestock diets and disruption to pharmaceutical-grade mineral supplier concentration. Practitioners should keep alternative scenarios live as environmental accumulation concerns and chelation technology substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Wheat Malt Market
Ingredients
Australia Soy Protein Market
Ingredients
North America Soybean Oil Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Konjac Flour Market
Ingredients
Ice Cream Ingredients Market
Ingredients
North America Gelatin Market
Ingredients
Hen Egg White Protein Market
Ingredients
Virgin Coconut Oil Market
Ingredients
South America Lipid Market
Ingredients
Asparagus Extract Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
US Ingredients Market
Ingredients
Chickpea Fiber Market