
 Beverage Ingredients Market | 2026-2036
Beverage Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Ingredients Market Analysis
Asset-light contract manufacturing and third-party tolling arrangements is reconfiguring capital deployment across the beverage ingredients value chain, enabling mid-scale entrants to access industrial fermentation and extraction capacity without balance-sheet intensity. Kerry Group plc leverages its integrated taste and nutrition platform to anchor global supply relationships with major beverage producers. Symrise AG specializes in natural flavor extraction, sustaining premium positioning through botanical sourcing networks. Archer-Daniels-Midland Company dominates agricultural input streams, extending its origination advantage into refined sweetener and acid portfolios.
Beverage ingredients encompass functional additives, flavoring systems, acidulants, and texturizing agents formulated to deliver taste, stability, shelf-life extension, and nutritional enhancement in liquid consumables, with specifications typically requiring solubility thresholds above 95 percent and microbial counts below 10^3 CFU per gram for powdered formats. These inputs serve industrial beverage producers, food manufacturers, and foodservice operators seeking consistent batch-to-batch performance at production scale. Sweeteners and flavors command the largest value pools within ingredient type segmentation, though acid and starch modifiers are gaining traction in reduced-sugar reformulations. Functional beverages and soft drinks represent the fastest-growing application channels, while alcoholic beverages remain a mature, volume-stable segment where premiumization drives ingredient upgrading rather than unit expansion.
FDA food additive regulations and GRAS self-affirmation pathways shape product approval timelines and market access for novel ingredients in the United States, while EFSA novel food assessments and EU flavoring regulation (EC) No 1334/2008 govern commercialization across European markets. China's NMPA and national food safety standards (GB series) impose additional testing and registration requirements for imported functional ingredients. Stakeholders must monitor evolving clean-label definitions and sugar reduction mandates across these jurisdictions to anticipate reformulation demand and preempt compliance-driven supply disruptions.
Market Dynamics
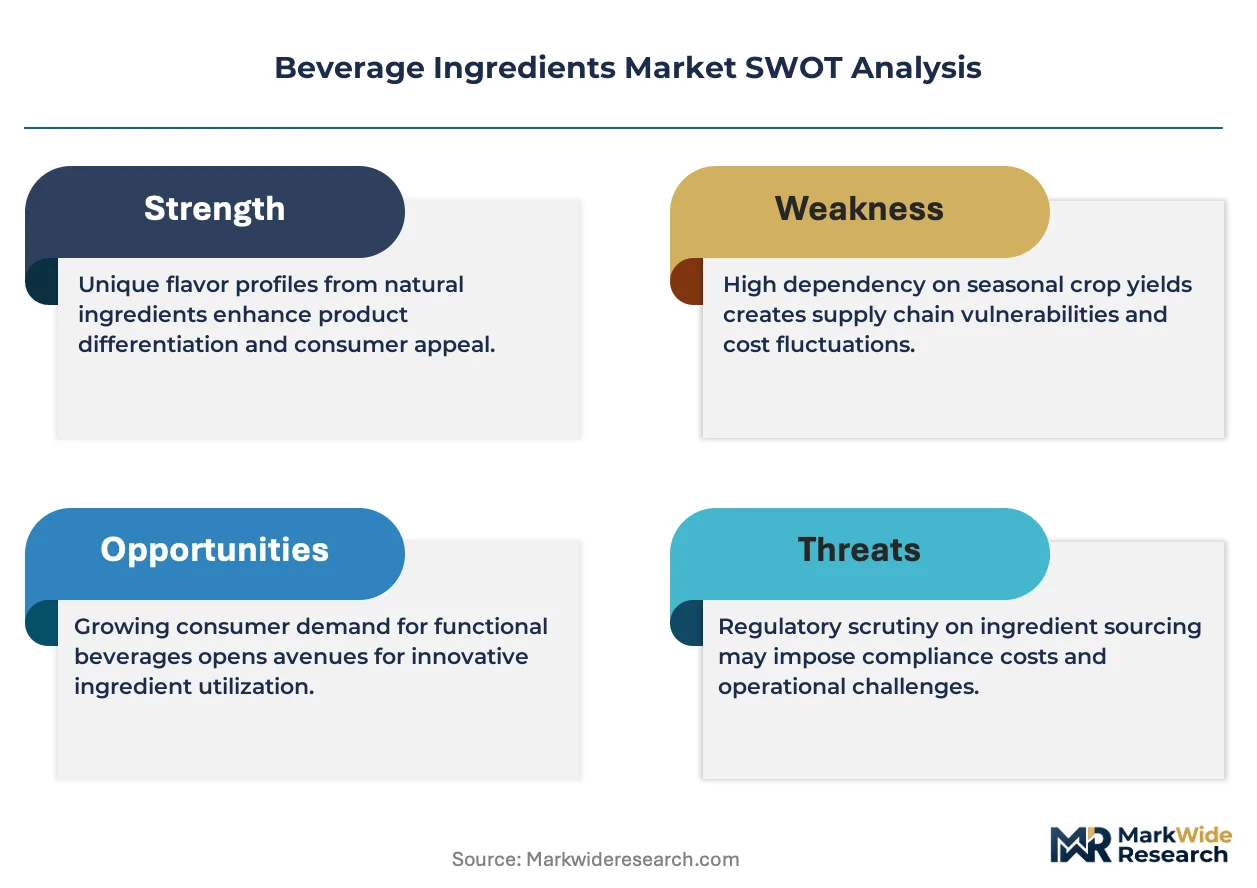
Clean-label mandates under EU flavoring regulation (EC) No 1334/2008 are compressing synthetic additive demand while redirecting R&D capital toward botanical extraction and fermentation-derived alternatives. This regulatory pivot is forcing reformulation cycles across functional beverage portfolios and respecifying solubility and microbial thresholds for natural substitutes.
Growth Catalysts
- Functional beverage expansion:Sports nutrition and cognitive health positioning are pulling novel nootropic and adaptogenic ingredients into mainstream soft drink applications, expanding addressable ingredient categories beyond traditional flavor and sweetener pools.
- EU clean-label enforcement:EFSA novel food assessments and tightening additive approval timelines are accelerating substitution demand for plant-derived colorants and natural preservation systems in European formulation facilities.
- Fermentation capacity scaling:Precision fermentation infrastructure in the United States and Germany is enabling cost-competitive production of rare botanical actives and bio-identical flavor molecules previously constrained by agricultural supply volatility.
Market Restraints
- Natural extract input volatility:Climate-sensitive botanical sourcing from Madagascar, Indonesia, and India generates price instability for vanilla, citrus, and spice-derived flavor precursors, compressing margin predictability for natural-positioned portfolios.
- Regulatory fragmentation:Divergent GRAS self-affirmation pathways in the United States versus EFSA novel food requirements in Europe versus NMPA registration in China force redundant safety dossier preparation, extending commercialization timelines.
- Technical solubility ceilings:Natural colorants and oil-based flavor systems face solubility thresholds below 85 percent in high-acid beverage matrices, limiting direct substitution rates for synthetic alternatives without emulsifier co-formulation.
Strategic Opportunities
- Precision fermentation scale-up:Bio-identical compound production via microbial hosts is converging with AI-guided strain optimization, opening supply security for rare terpenes and alkaloids in premium positioning.
- Sugar reduction mandates:Front-of-pack labeling regulations in the United Kingdom and pending state-level soda taxes in California are creating formulation service demand for bitter-masking and mouthfeel-rebuilding ingredient systems.
- Direct-to-brand ingredient supply:Mid-scale beverage producers are bypassing traditional distributor tiers through B2B platform procurement, creating margin capture opportunities for specialty extract houses with digital specification tools.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemistry expertise spanning food science, regulatory affairs, and sensory evaluation remains concentrated at legacy ingredient houses, constraining mid-tier competitor technical service bandwidth.
- Clean-label certification backlog:Third-party non-GMO, organic, and carbon-neutral verification timelines have extended to 14-18 months, delaying product launches and freezing working capital in pre-qualified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Ingredients Market |
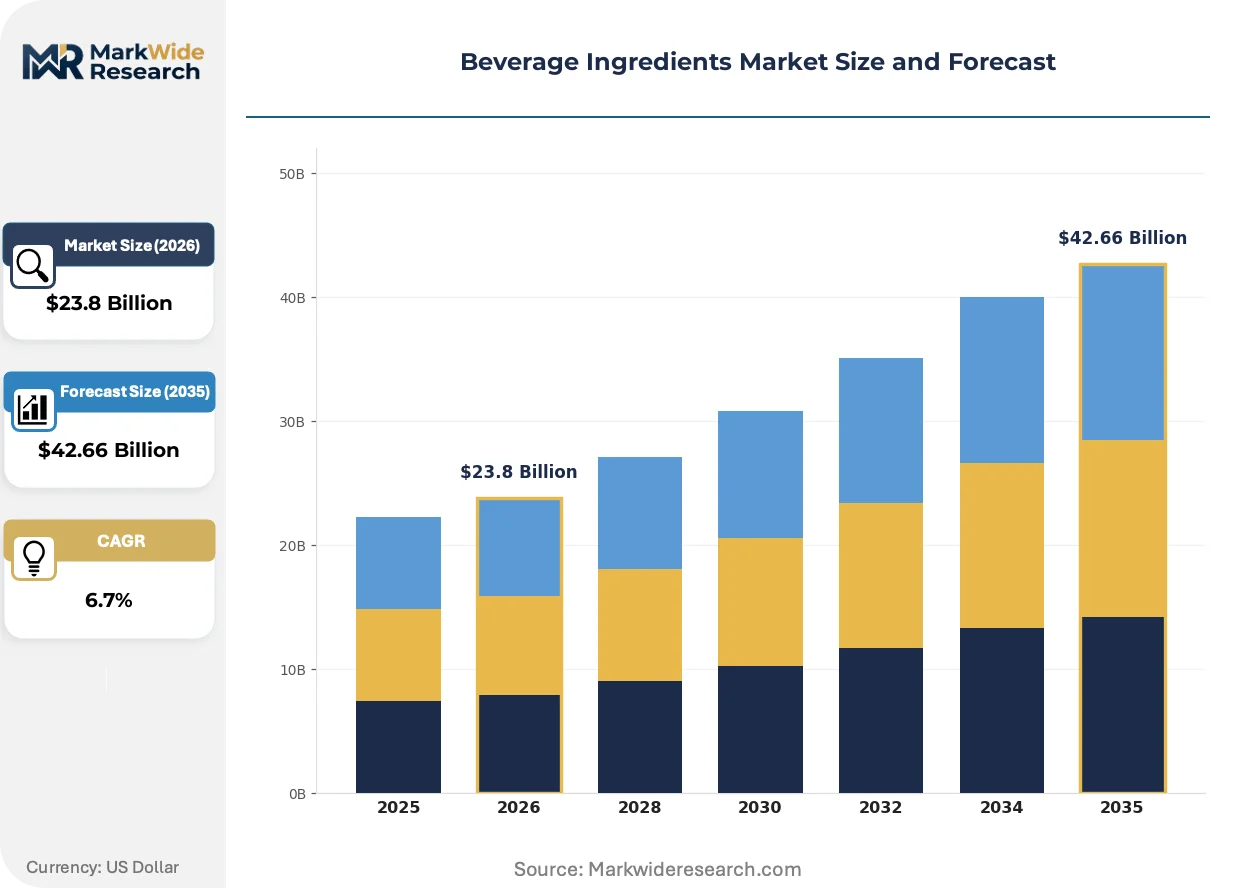
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Sweeteners, Flavors, Acids, Starches Application: Soft Drinks, Functional Beverages, Alcoholic Beverages, Dairy Beverages Form: Powder, Liquid, Concentrate, Extract End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers |
| Companies Covered | Kerry Group plc, Symrise AG, Archer-Daniels-Midland Company, Döhler Group, Tate & Lyle PLC, Cargill, Incorporated, Givaudan SA, Sensient Technologies Corporation, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Ingredients Market Emerging Trajectories
Digital specification platforms and AI-driven formulation tools are compressing development cycles while fragmenting traditional buyer-supplier relationships. These shifts are enabling smaller ingredient houses to compete on technical service parity with integrated multinationals.
AI-assisted sensory mapping is digitizing flavor formulation workflows by predicting cross-modal taste interactions from molecular structure databases. Mid-scale beverage producers in Germany and the United States are adopting these tools at 18-month replacement cycles for traditional panel-based development. The technology is digitizing historically tacit formulation expertise, compressing the competitive advantage of legacy taste houses built on decades of empirical archives.
EFSA's 2023-2025 systematic re-evaluation of food additives is accelerating titanium dioxide and synthetic dye phase-outs across European beverage portfolios. Industrial consequence includes urgent reformulation demand for calcium carbonate alternatives and plant-derived opacity agents. Reduced-sugar carbonated soft drinks in France and Germany are most affected, with producers accelerating partnerships with natural colorant specialists to preempt 2025 labeling restrictions.
Consolidated procurement through beverage co-manufacturing networks is compressing supplier rosters and extending quality audit requirements to tier-2 extractors. Major contract packers in China and Mexico are displacing direct ingredient purchasing by brand owners, centralizing specification power with manufacturing intermediaries. This concentration is most visible in functional beverage production, where co-manufacturers now dictate acidulant and texturizer sourcing to secure batch-to-batch stability guarantees across multi-brand production lines.
Beverage Ingredients Market Segmentation
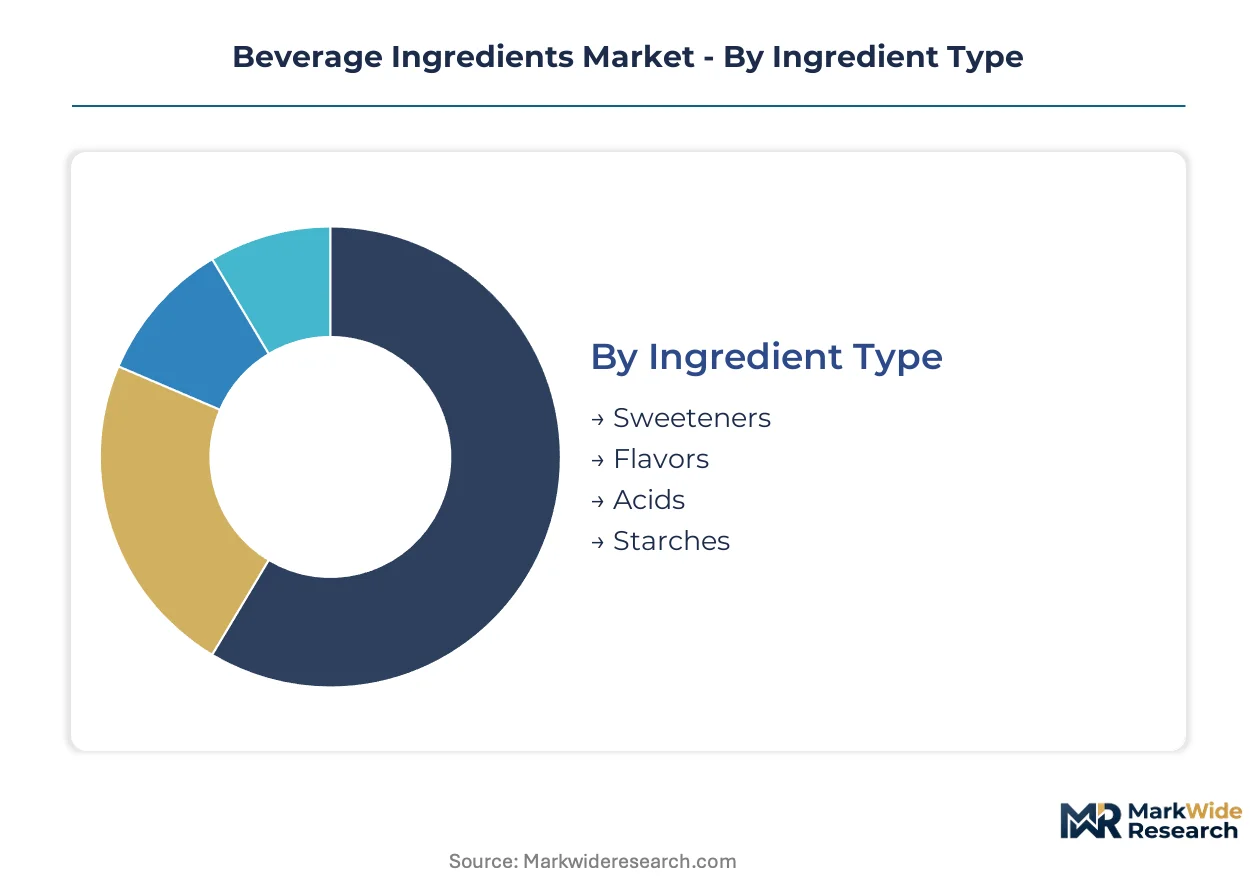
Ingredient categorization in beverage formulation directly determines procurement strategy, regulatory pathway selection, and margin structure. Each segmentation axis reveals distinct competitive dynamics, from commodity-scale sweetener sourcing to precision-extracted flavor positioning.
Ingredient Type:
Formulation teams select inputs based on solubility thresholds, microbial specifications, and clean-label compliance requirements across target markets.
- Sweeteners:Refined sugar, high-fructose corn syrup, and stevia-based systems dominate volume, with producers in the United States and Germany accelerating reformulation around reduced-sugar mandates. Solubility above 95 percent and clean-label positioning now determine supplier selection.
- Flavors:Natural extracts and fermentation-derived molecules command premium positioning, with botanical sourcing networks from Madagascar and Indonesia creating supply volatility. EFSA novel food assessments and EU flavoring regulation are accelerating synthetic-to-natural substitution cycles.
- Acids:Citric, malic, and phosphoric acidulants stabilize pH and extend shelf life, serving carbonated soft drink and functional beverage producers seeking batch-to-batch consistency.
- Starches:Modified and native starch systems provide mouthfeel reconstruction in reduced-sugar applications, with texturizing specifications tightening as beverage matrices grow more complex.
The dominant share belongs to Sweeteners, while Flavors is closing the gap fastest through premium natural positioning.
Application:
End-use channels differ sharply in volume scale, reformulation frequency, and ingredient upgrading intensity.
- Soft Drinks:Carbonated and still beverage producers in France and Germany drive acidulant and sweetener demand, with sugar reduction mandates forcing rapid reformulation cycles.
- Functional Beverages:Sports nutrition and cognitive health positioning pull novel nootropic and adaptogenic ingredients into mainstream applications, expanding addressable categories beyond traditional flavor pools.
- Alcoholic Beverages:Mature volume-stable segment where premiumization drives ingredient upgrading rather than unit expansion, with craft distillers and brewers demanding specialized flavor systems.
- Dairy Beverages:Plant-based milk alternatives and protein-fortified drinks require stabilizer and emulsifier co-formulation, with microbial specifications below 10^3 CFU per gram for powdered formats.
Functional Beverages is expanding most quickly through health-positioning innovation, while Soft Drinks retains volume leadership despite reformulation headwinds.
Form:
Physical state determines logistics economics, shelf stability, and manufacturing integration complexity.
- Powder:Spray-dried and agglomerated formats dominate industrial-scale production, requiring solubility thresholds above 95 percent and microbial counts below 10^3 CFU per gram.
- Liquid:Ready-to-use syrups and solutions reduce manufacturing step count, with beverage co-manufacturers in China and Mexico centralizing procurement through tolling arrangements.
- Concentrate:High-potency flavor and color systems enable freight cost reduction, with dilution ratios specified for precise batch control.
- Extract:Botanical and fermentation-derived actives serve premium positioning, with Madagascar vanilla and Indonesian spice networks creating input volatility.
Powder commands the largest volume share, though Liquid is gaining ground fastest through co-manufacturing network consolidation.
End User:
Customer type shapes specification authority, technical service requirements, and procurement channel selection.
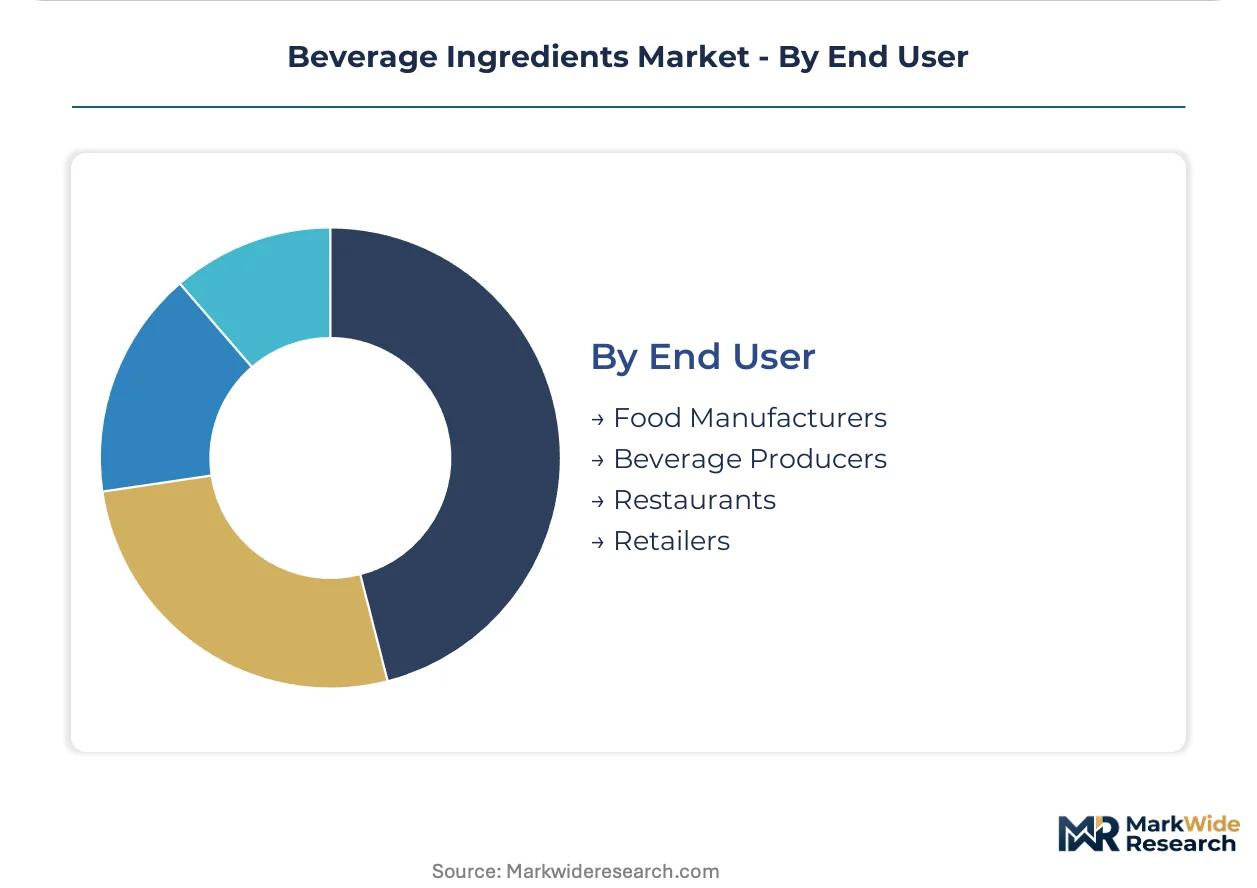
- Food Manufacturers:Diversified producers with cross-category formulation expertise, demanding consistent batch-to-batch performance across liquid consumable portfolios.
- Beverage Producers:Dedicated soft drink and functional beverage companies with specialized R&D teams, driving clean-label and sugar-reduction innovation cycles.
- Restaurants:Foodservice operators seeking fountain syrup concentrates and dispensed beverage systems, with procurement centralized through distribution intermediaries.
- Retailers:Private-label brand owners leveraging co-manufacturing networks, displacing direct ingredient purchasing and extending quality audit requirements to tier-2 extractors.
Beverage Producers hold the dominant procurement position, while Retailers is climbing fastest through private-label expansion and co-manufacturing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU flavoring regulation (EC) No 1334/2008 and front-of-pack labeling mandates are redirecting formulation investment toward natural extract technologies across major beverage production clusters.
United States
Precision fermentation infrastructure in California and North Carolina is scaling bio-identical flavor molecule production. FDA GRAS self-affirmation pathways accelerate novel ingredient timelines relative to European counterparts. Beverage co-manufacturers in Texas and Georgia now centralize procurement decisions for acidulants and texturizers.
Germany
EFSA's systematic additive re-evaluation is forcing titanium dioxide phase-outs across carbonated soft drink portfolios. Bavarian extraction facilities are expanding botanical processing capacity to supply reformulation demand. The Rhine-Ruhr industrial corridor hosts concentrated flavor house technical service operations.
China
NMPA registration requirements for imported functional ingredients are extending commercialization timelines for foreign suppliers. Yangtze River Delta beverage producers are scaling premium functional beverage lines. Shanghai-based co-manufacturers now dictate starch and emulsifier sourcing specifications.
India
FSSAI enforcement of microbial specifications below 10^3 CFU per gram is respecifying powder format imports. Maharashtra and Karnataka beverage clusters are expanding contract manufacturing capacity. Mumbai-based procurement platforms are displacing traditional distributor tiers for mid-scale producers.
Brazil
ANVISA's alignment with international food additive standards is streamlining import pathways for natural preservation systems. São Paulo state beverage producers are accelerating reduced-sugar reformulations. The Campinas research corridor anchors sensory evaluation and formulation service capabilities.
Beverage Ingredients Market Vendor Landscape
On the supply side, the industry is consolidating around integrated taste-nutrition platforms and specialized extraction houses. Tier-1 players leverage global origination networks for agricultural inputs, while mid-scale specialists compete on botanical sourcing relationships and digital specification tools. Three archetypes dominate: agricultural conglomerates with downstream refining capabilities, integrated flavor houses with fermentation technology, and regional extract specialists with direct-to-brand digital channels. Competitive intensity centers on M&A for fermentation capacity and strategic partnerships with beverage co-manufacturers.
Among Ireland- and Germany-based integrated platforms, Kerry Group plc and Symrise AG exemplify the taste-nutrition convergence archetype. Archer-Daniels-Midland Company anchors the agricultural origination tier. These three occupy positions spanning commodity-scale input security through premium natural extraction, with each representing distinct capital deployment strategies across the ingredient value chain.
| Leading Market Players |
|---|
| Kerry Group plc |
| Symrise AG |
| Archer-Daniels-Midland Company |
| Döhler Group |
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Givaudan SA |
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta fermentation cluster anchors global capacity for bio-identical flavor molecules, and its utilization rates directly transmit into premium-tier pricing power for natural extract substitutes. Downward pressure on synthetic additive margins accelerates as beverage co-manufacturers consolidate procurement authority and force specification standardization across multi-brand production lines.
Pricing Analysis
Certification level (FDA-grade versus EU organic) creates the primary spread between premium and commodity ingredient tiers. Contract-based long-term offtake dominates volume transactions, while spot purchasing persists for climate-sensitive botanical inputs like Madagascar vanilla. Price differentiation hinges on clean-label verification timelines and solubility performance guarantees. Cost compression in mid-tier natural colorants is intensifying because EFSA additive phase-outs are flooding reformulation demand toward limited qualified suppliers. Private-label beverage producers exhibit highest price sensitivity; premium functional beverage brands show lowest.
Supply Chain Analysis
Beverage co-manufacturers in Texas, Georgia, and Shanghai now hold decisive capacity allocation power across acidulant and texturizer procurement. Supply concentrates in the United States, Germany, and China for precision fermentation infrastructure, while botanical sourcing draws from Madagascar, Indonesia, and India. Raw material dependencies include citrus oil precursors, vanilla orchid biomass, and fermentation feedstock sugars. Single-source vulnerability runs through Indonesian spice networks disrupted by climate volatility. Distribution runs through tolling arrangements that displace direct brand-owner purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise spanning food science, regulatory affairs, and sensory evaluation remains trapped at legacy houses, creating acute bottlenecks for mid-tier competitors attempting technical service scale. This capability scarcity rewards targeted capability acquisition over organic buildout.
For Market Incumbents: Build captive fermentation capacity moats through backward integration into precision infrastructure in North Carolina and Bavaria. Defend against emerging AI-driven formulation platforms by accelerating digital specification tool deployment. Secure multi-year tolling partnerships with Yangtze River Delta co-manufacturers to lock acidulant allocation ahead of capacity constraints. For New Entrants and Emerging Players: Pursue direct-to-brand digital channels serving mid-scale functional beverage producers bypassing traditional distributor tiers. Target white-space in bitter-masking ingredient systems for UK sugar-reduction mandates. Enter through B2B procurement platforms offering rapid specification matching against EFSA compliance requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated taste-nutrition platforms with fermentation assets over pure-play extract houses. Long-term viability rests on supply security for rare terpenes and alkaloids as agricultural volatility intensifies. The signal to watch is co-manufacturer consolidation velocity in China and Mexico as procurement centralization indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Secures bio-identical supply for rare botanical actives previously constrained by Madagascar and Indonesian sourcing volatility. |
| Backward Integration into Extraction | Captures margin from botanical processing through Bavarian and Californian facility expansion. |
| Digital Specification Platform Launch | Compresses development cycles for mid-scale beverage producers adopting AI-assisted sensory mapping. |
| Clean-Label Certification Investment | Preempts EFSA novel food assessment delays that currently extend verification timelines to 14-18 months. |
| Co-Manufacturer Partnership | Locks acidulant and texturizer allocation as Texas and Georgia tolling networks consolidate procurement authority. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA GRAS filings, EFSA novel food registers, customs trade data, and beverage producer SEC disclosures. Primary inputs include formulation chemists at integrated flavor houses, procurement directors at contract manufacturing networks, regulatory affairs leads navigating EU flavoring regulation, and technical service managers at starch and acidulant suppliers. Bottom-up demand modeling triangulates against top-down value chain analysis across ingredient type and application segments.
Forecast inputs span solubility specification evolution, clean-label mandate enforcement intensity, and fermentation capacity utilization across the analysis window. Segmentation dimensions include ingredient type, application channel, physical form, and end-user procurement authority. CAGRs derive from elasticity-adjusted volume projections and price trajectory assumptions for natural versus synthetic substitute dynamics. Industry-specific inputs incorporate EFSA additive re-evaluation timelines and NMPA registration pathway durations.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices and energy costs for fermentation operations would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement consistency and climate pattern stability for botanical sourcing regions. Quarterly review of co-manufacturer procurement centralization indicators and EFSA assessment backlog data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Palm Mid-Fraction Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Liquid Feed Market
Ingredients
Brewer's Yeast Market
Ingredients
Hops Derivative Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
North America Dairy Protein Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Ground-Nut Oil Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Malted Wheat Flour Market
Ingredients
Peanut Ingredients Market
Ingredients
Global Dietary Fibers Market