
 Multivitamin and Mineral Supplements Market | 2026-2036
Multivitamin and Mineral Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Multivitamin and Mineral Supplements Market Analysis
Multi-source ingredient procurement is restructuring supply economics across the multivitamin and mineral supplements industry. Pfizer's Centrum unit leverages captive manufacturing networks to secure vitamin precursor supply chains. Pharmavite's Nature Made brand anchors its position through USP-verified purity programs that command retail shelf priority. Amway's Nutrilite operation differentiates via vertically controlled botanical extraction facilities in Washington and California.
Multivitamin and mineral supplements combine essential micronutrients—typically vitamins A through K, iron, zinc, magnesium, and calcium—into single-dose delivery systems manufactured through direct compression or wet granulation tableting, designed to address documented nutritional gaps in populations with restricted dietary diversity. Tablet formulations occupy the mature volume core of the market, while gummy delivery systems capture disproportionate margin pools through pediatric and senior palatability premiums. The organic formulation segment sustains price premiums three to five tiers above synthetic baselines, though whole-food sourcing creates batch-to-batch potency variance that complicates label claim compliance.
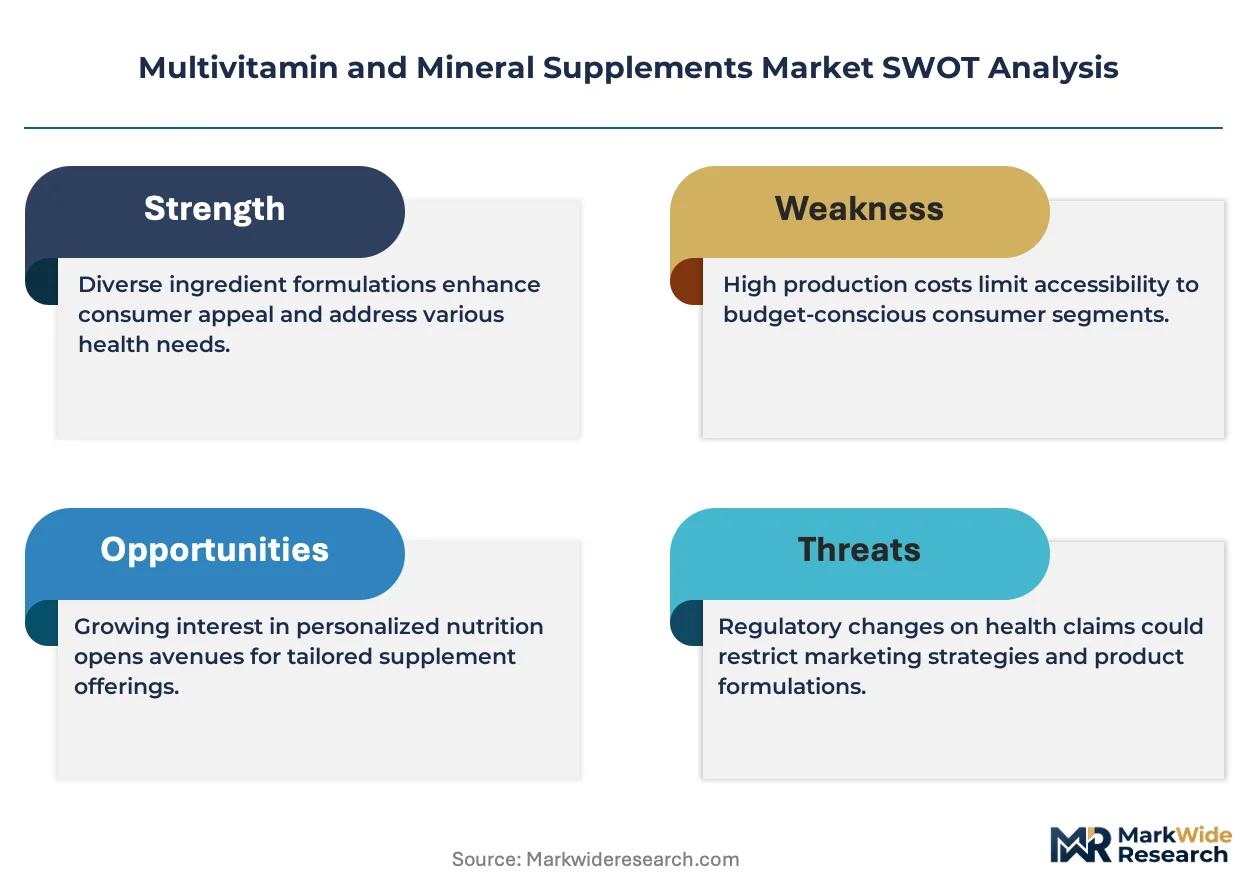
FDA's Current Good Manufacturing Practices for dietary supplements, coupled with USP verification protocols and NSF International certification standards, collectively elevate barrier costs for new market entrants while rewarding incumbent documentation infrastructure. The Federal Trade Commission actively pursues unsubstantiated health claim enforcement, particularly targeting immune and cognitive benefit assertions that lack randomized trial backing. Stakeholders must monitor evolving state-level age-restriction legislation for gummy formats and prepare contingency labeling for potential FDA mandatory product listing requirements.
Market Dynamics
FDA's updated dietary supplement labeling requirements are forcing incumbent manufacturers to rebuild documentation infrastructure while creating asymmetric compliance costs that favor established verification programs over new entrants.
Growth Catalysts
- USP Verification Protocols:Third-party purity certification programs now command retail shelf priority in United States pharmacy channels, locking in volume for compliant suppliers.
- Geriatric Institutional Demand:Long-term care facilities in Japan and Germany are standardizing multivitamin protocols for resident populations with documented micronutrient deficiencies.
- Tablet-to-Gummy Format Migration:Wet granulation advances enable mineral stability in chewable matrices, opening pediatric and senior palatability premiums previously captured by synthetic candy alternatives.
Market Restraints
- Botanical Input Volatility:Whole-food sourced vitamins face batch-to-batch potency variance from Washington and California extraction facilities, complicating label claim compliance.
- Chinese Precursor Concentration:Vitamin B and C precursor synthesis concentrates in Zhejiang and Shandong provinces, creating geographic supply risk absent captive manufacturing networks.
- FTC Health Claim Enforcement:The Federal Trade Commission's randomized trial requirements for immune and cognitive benefit assertions eliminate marketing differentiation for non-clinical formulations.
Strategic Opportunities
- Indian Preventive Health Expansion:FSSAI's functional food classification pathway enables pharmacy-direct positioning for multivitamin formats previously restricted to general wellness shelves.
- Personalized Nutrition Convergence:At-home micronutrient testing kits are converging with subscription multivitamin services, creating stickier consumer relationships than mass-market SKUs.
- Clean Label Certification:NSF International's Certified for Sport program opens institutional procurement channels for collegiate and professional athletic facilities with zero-tolerance contamination policies.
Industry Challenges
- Analytical Chemistry Talent Scarcity:USP verification requires specialized chromatography expertise that outpaces university program output, extending hiring timelines for quality control functions.
- Legacy ERP Integration:Batch record systems designed for pharmaceutical GMP struggle to accommodate dietary supplement ingredient variability, forcing middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multivitamin and Mineral Supplements Market |
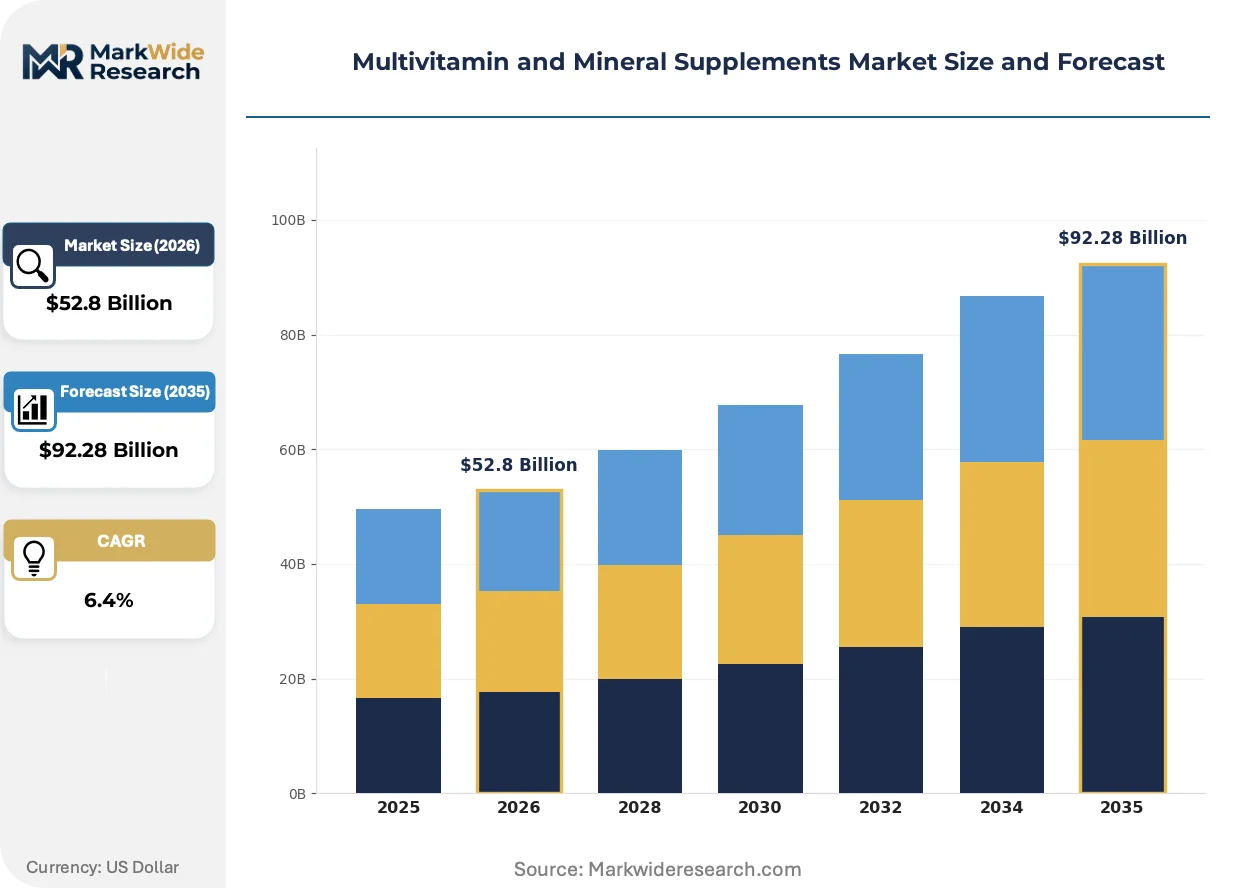
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Gummies, Powders, Capsules End User: Children, Adults, Seniors, Pregnant Women Formulation: Organic, Synthetic, Whole Food, Fortified Distribution Channel: Online, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Pfizer (Centrum), Nature Made (Pharmavite), Amway (Nutrilite), Garden of Life, NOW Foods, GNC, Bayer AG (One A Day), Thorne, Nature's Bounty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multivitamin and Mineral Supplements Market Emerging Trajectories
Direct compression tableting is converging with precision coating technologies to reshape manufacturing economics, while regulatory transparency mandates and channel fragmentation are rewriting go-to-market architectures.
Liposomal encapsulation technology is converging with mineral chelation processes to enhance bioavailability for magnesium and zinc formulations. Geriatric consumers in German and Japanese institutional settings are adopting these advanced delivery systems at twice the rate of standard tablets. This convergence is compressing margin pools for conventional tablet manufacturers while rewarding specialized contract development organizations with pharmaceutical-grade coating capabilities.
The FDA's mandatory product listing requirement, currently under regulatory review, would force all domestic and imported supplement labels into a centralized federal database. This policy shift would eliminate gray-market diversion by exposing unregistered foreign manufacturers to immediate enforcement action. United States direct-to-consumer brands with existing documentation infrastructure are pre-positioning compliance teams, while smaller importers face existential registration cost burdens.
Subscription-based replenishment models are displacing pharmacy-impulse purchasing among millennial and Generation X households with documented micronutrient deficiencies. United States telehealth platforms are integrating these auto-ship programs into post-consultation workflows, capturing patient adherence data that retail channels cannot access. This behavioral shift concentrates lifetime value in vertically integrated wellness platforms while eroding traditional retail pharmacy foot traffic for multivitamin categories.
Multivitamin and Mineral Supplements Market Segmentation
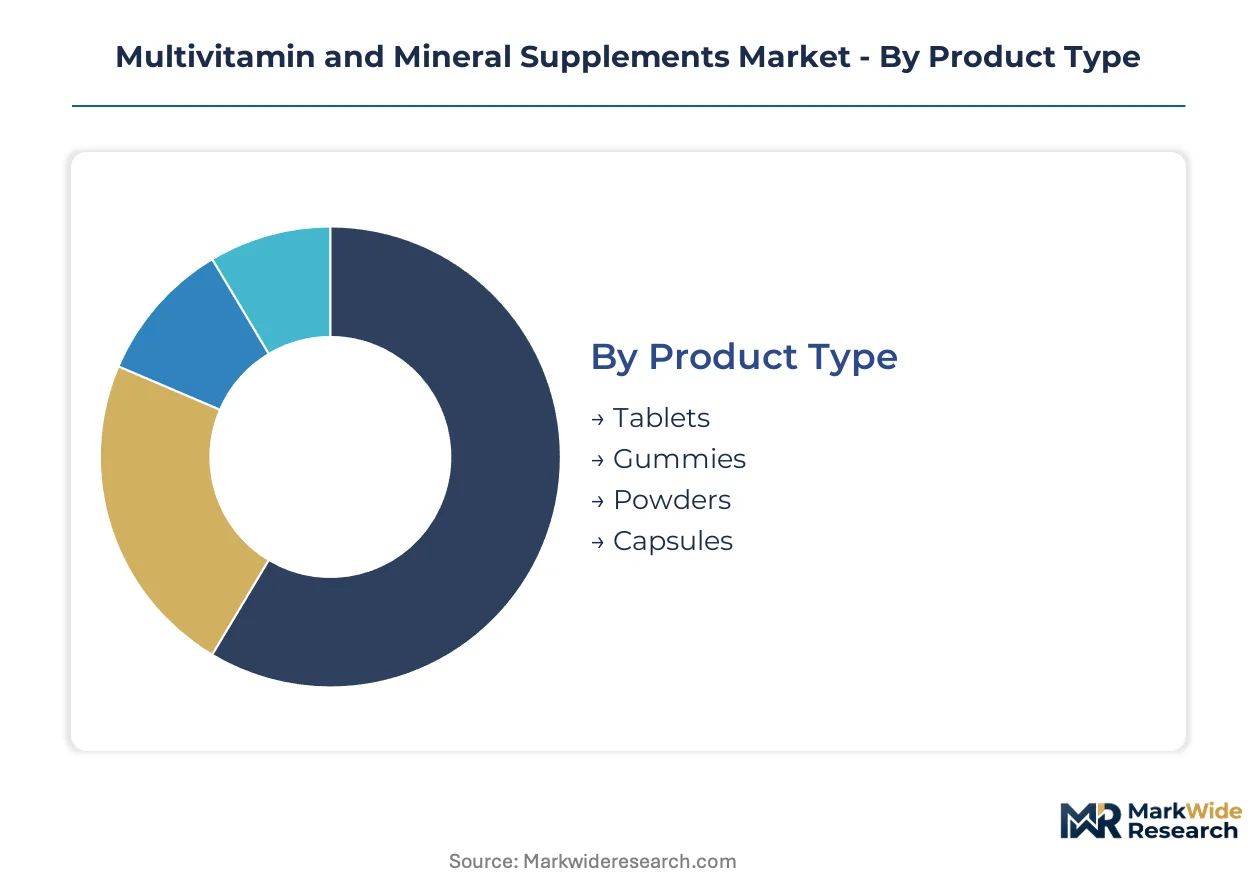
Multivitamin manufacturers deploy distinct capital profiles across delivery formats and purity tiers. Segment-level investment requirements determine which players capture pharmacy shelf priority versus direct-to-consumer volume.
Product Type:
Tablet manufacturing demands the heaviest upfront capital—compression tooling, coating lines, and dissolution testing infrastructure—while gummy production requires specialized starch molding and humidity-controlled curing environments.
- Tablets:Direct compression and wet granulation systems produce standardized doses with extended stability profiles. United States pharmacy-direct channels concentrate demand here, driven by USP verification protocols that reward documented dissolution consistency.
- Gummies:Wet granulation advances now stabilize mineral content in chewable matrices, unlocking pediatric and senior palatability premiums. Japanese long-term care facilities are standardizing gummy protocols for residents with swallowing difficulties.
- Powders:Bulk blending operations serve fitness and clinical nutrition segments with flexible dosing scalability.
- Capsules:Two-piece gelatin and vegetarian shell formats target consumers seeking rapid disintegration without tablet binders.
Most installed capacity flows through Tablets. Expansion is steepest in Gummies.
End User:
Customer acquisition costs diverge sharply across life-stage segments, with institutional procurement channels offering volume certainty that retail impulse purchases cannot match.
- Seniors:German and Japanese institutional care settings drive standardized multivitamin protocols for populations with documented micronutrient deficiencies. Long-term care contracts provide predictable offtake absent retail promotional cycles.
- Adults:Subscription-based replenishment models displace pharmacy-impulse purchasing among millennial and Generation X households with confirmed deficiencies. United States telehealth platforms integrate auto-ship programs into post-consultation workflows.
- Children:Palatability premiums concentrate demand in gummy formats with sugar-reduced positioning.
- Pregnant Women:Folate and iron specifications require prenatal-specific formulations with teratogenic screening protocols.
Institutional procurement concentrates in Seniors. Direct-to-consumer subscription growth is climbing fastest among Adults.
Formulation:
Input sourcing strategies separate cost structures, with whole-food extraction requiring vertical botanical control that synthetic precursor synthesis avoids.
- Synthetic:Vitamin B and C precursor synthesis concentrates in Zhejiang and Shandong provinces, enabling scale economies through chemical conversion efficiencies.
- Organic:Third-party certification sustains price premiums three to five tiers above synthetic baselines. Washington and California extraction facilities supply vertically controlled botanical inputs.
- Whole Food:Batch-to-batch potency variance from agricultural sourcing complicates label claim compliance.
- Fortified:Beverage and food matrix integration expands addressable occasions beyond supplement occasions.
Volume concentration sits with Synthetic. Premium positioning is expanding most quickly in Organic.
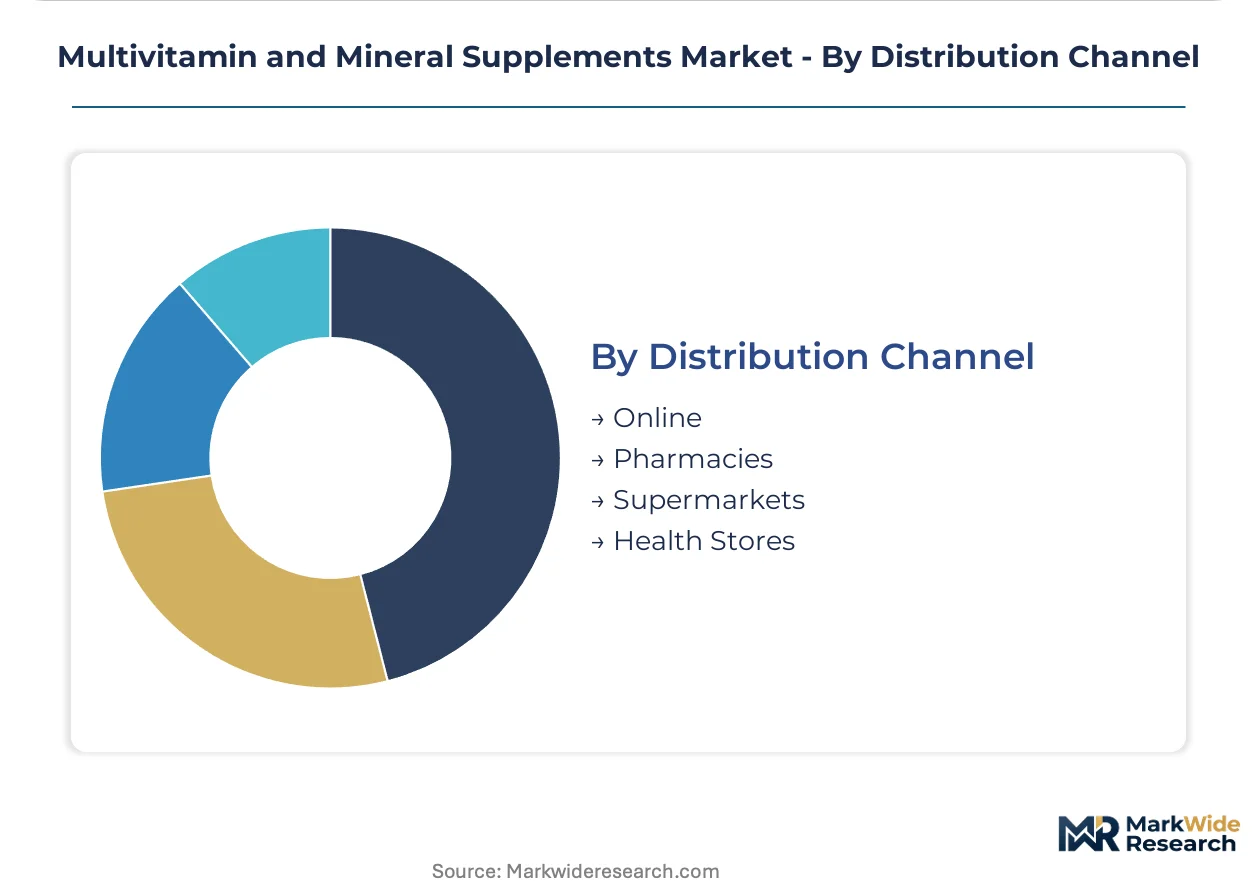
Distribution Channel:
Channel selection determines margin retention, with pharmacy-direct surrendering shelf slotting fees that online pure-plays avoid.
- Pharmacies:USP-verified products command retail shelf priority in United States pharmacy-direct channels. Pharmacist recommendation drives trial among first-time purchasers.
- Online:Subscription models capture lifetime value through auto-ship adherence data that retail channels cannot access. Telehealth integration deepens consumer relationships.
- Supermarkets:Impulse placement captures occasional purchasers with lower brand loyalty.
- Health Stores:Staff expertise supports premium and specialty format trial.
Transaction volume flows predominantly through Pharmacies. Customer lifetime value expansion is steepest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production investment toward jurisdictions with streamlined dietary supplement frameworks. Compliance cost differentials between FDA-registered and emerging-market facilities exceed 40 percent for USP verification protocols, reshaping where multivitamin manufacturers build captive precursor synthesis.
United States
Pharmacy-direct channels concentrate volume for USP-verified tablet formats, with pharmacist recommendation driving trial among first-time purchasers. FDA's updated dietary supplement labeling requirements and mandatory product listing proposals are forcing documentation infrastructure rebuilds. Washington and California host vertically controlled botanical extraction facilities supplying organic formulation inputs.
Germany
Long-term care facilities are standardizing multivitamin protocols for geriatric populations with documented micronutrient deficiencies. EFSA's health claim authorization process creates asymmetric compliance costs favoring established verification programs over new entrants. Bavaria and North Rhine-Westphalia anchor institutional procurement contracts with predictable offtake absent retail promotional cycles.
Japan
Metropolitan institutional care settings adopt gummy delivery systems at twice the rate of standard tablets for residents with swallowing difficulties. PMDA's functional food classification pathway enables pharmacy-direct positioning for formats previously restricted to general wellness shelves. Kanto and Kansai regions concentrate demand from standardized long-term care protocols.
India
FSSAI's functional food classification pathway is opening pharmacy-direct positioning for multivitamin formats previously restricted to general wellness shelves. Preventive health expansion among middle-income households is accelerating subscription-based replenishment models. Maharashtra and Gujarat host contract manufacturing clusters serving domestic and export markets with cost-optimized synthetic precursor processing.
China
Vitamin B and C precursor synthesis concentrates in Zhejiang and Shandong provinces, creating geographic supply risk absent captive manufacturing networks. NMPA's dietary supplement registration requirements are elevating barrier costs for imported brands. Yangtze River Delta and Pearl River Delta clusters dominate chemical conversion efficiencies for synthetic vitamin production.
Multivitamin and Mineral Supplements Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue personalized nutrition and clean-label certification vectors. The market structures around three tiers: pharmaceutical-captive manufacturers with vertical precursor control, third-party verified brands commanding retail shelf priority, and direct-to-consumer pure-plays capturing subscription lifetime value. Strategic archetypes include USP verification specialists, botanical extraction integrators, and telehealth-integrated wellness platforms. Dominant competitive moves center on backward integration into vitamin precursor supply and certification program enrollment that locks pharmacy channel access.
Within the pharmaceutical-captive tier, Pfizer's Centrum unit and Bayer AG's One A Day exemplify scale-driven manufacturers with documented dissolution consistency. Among third-party verified specialists, Pharmavite's Nature Made brand occupies a position anchored by USP-verified purity programs. Amway's Nutrilite operation represents vertically controlled botanical extraction, with Washington and California facilities supplying organic formulation inputs. These three anchors illustrate how compliance infrastructure and supply chain configuration separate sustainable positioning from commodity pressure.
| Leading Market Players |
|---|
| Pfizer (Centrum) |
| Nature Made (Pharmavite) |
| Amway (Nutrilite) |
| Garden of Life |
| NOW Foods |
| GNC |
| Bayer AG (One A Day) |
| Thorne |
| Nature's Bounty |
| Others |
Supply Flow & Price Mechanics
Captive precursor synthesis networks anchor both supply security and pricing power for multivitamin manufacturers with in-house vitamin B and C conversion capabilities. Pfizer's Centrum unit and Bayer AG's One A Day leverage vertically controlled production to buffer against Zhejiang and Shandong supply shocks while commanding pharmacy shelf premiums through USP-verified dissolution consistency.
Pricing Analysis
Retailer markup layers in United States pharmacy channels compress margins for non-verified brands while rewarding USP-certified suppliers with priority placement. Three-tier pricing structure across premium organic, standard synthetic, and economy private-label levels separates Amway's Nutrilite botanical extraction from commodity tablet producers. Cost compression in synthetic vitamin tiers is intensifying because Chinese precursor oversupply is eroding chemical conversion margins. Institutional procurement contracts for German and Japanese long-term care facilities exhibit lowest price sensitivity, while supermarket impulse purchasers demonstrate highest elasticity.
Supply Chain Analysis
Ocean freight cost volatility from Asia-Pacific to North American ports is reshaping inventory carrying strategies for mineral and botanical inputs. Vitamin precursor synthesis concentrates in China's Zhejiang and Shandong provinces, while whole-food extraction feeds from Washington and California botanical facilities. Single-source vulnerability in Chinese B-vitamin intermediate production creates geographic concentration risk absent captive manufacturing networks. Distribution runs through pharmacy-direct channels for verified tablet formats, with subscription auto-ship models capturing direct-to-consumer volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in multivitamin categories rests on gummy format premiums and organic certification tiering, with wet granulation advances enabling mineral stability that justifies palatability markups.
For Market Incumbents: Lock in pharmacy channel access through USP verification program enrollment before FDA mandatory product listing requirements elevate compliance costs for new entrants. Secure captive precursor synthesis in Zhejiang or Shandong provinces to isolate supply shocks from Chinese vitamin B and C concentration. Expand gummy production capacity to capture Japanese institutional demand for residents with swallowing difficulties. For New Entrants and Emerging Players: FSSAI's functional food classification pathway in India opens a window for pharmacy-direct positioning previously restricted to general wellness shelves. Target subscription-based replenishment models among United States millennial households with documented micronutrient deficiencies, leveraging telehealth platform integration for patient adherence data capture. Pursue NSF International Certified for Sport positioning to access collegiate and professional athletic procurement channels with zero-tolerance contamination policies. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemistry talent scarcity extends quality control hiring timelines beyond production scaling needs. Prioritize contract development organizations with pharmaceutical-grade coating capabilities and existing USP documentation infrastructure over commodity tablet manufacturers facing margin compression. Watch for FDA mandatory product listing implementation as inflection indicator that eliminates gray-market importers and concentrates volume in compliant domestic players.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Program Enrollment | Locks pharmacy shelf priority in United States channels against non-compliant competitors. |
| Backward Integration into Precursor Synthesis | Isolates supply risk from Chinese vitamin B and C geographic concentration. |
| Gummy Format Manufacturing Scale-Up | Captures pediatric and senior palatability premiums in Japanese institutional care. |
| Telehealth Platform Partnership | Integrates subscription auto-ship into post-consultation workflows for adherence data. |
| NSF Certified for Sport Positioning | Opens institutional procurement channels for collegiate athletic facilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmacy category managers, dietary supplement quality control directors, long-term care facility procurement officers, and botanical extraction facility operators with secondary validation. FDA dietary supplement labeling guidance, USP verification protocols, FSSAI functional food classifications, and PMDA registration databases anchored regulatory trajectory assessment. Bottom-up tablet and gummy volume estimates triangulated against top-down market sizing from channel shipment data.
Segment-weighting approaches distributed value across synthetic, organic, and whole-food formulation tiers while modeling tablet, gummy, powder, and capsule delivery format trajectories. CAGRs derived from regression analysis of historical pharmacy-direct and online subscription channel growth patterns, with geriatric institutional demand curves and personalized nutrition convergence timelines as industry-specific inputs across the projection horizon.
Revisions become necessary when FDA mandatory product listing implementation timelines shift, Chinese precursor export restrictions materialize, or EFSA health claim authorization processes extend beyond baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Nutritional Oil Powder Market