
 Sunflower Lecithin Market | 2026-2036
Sunflower Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Sunflower Lecithin Market Analytics
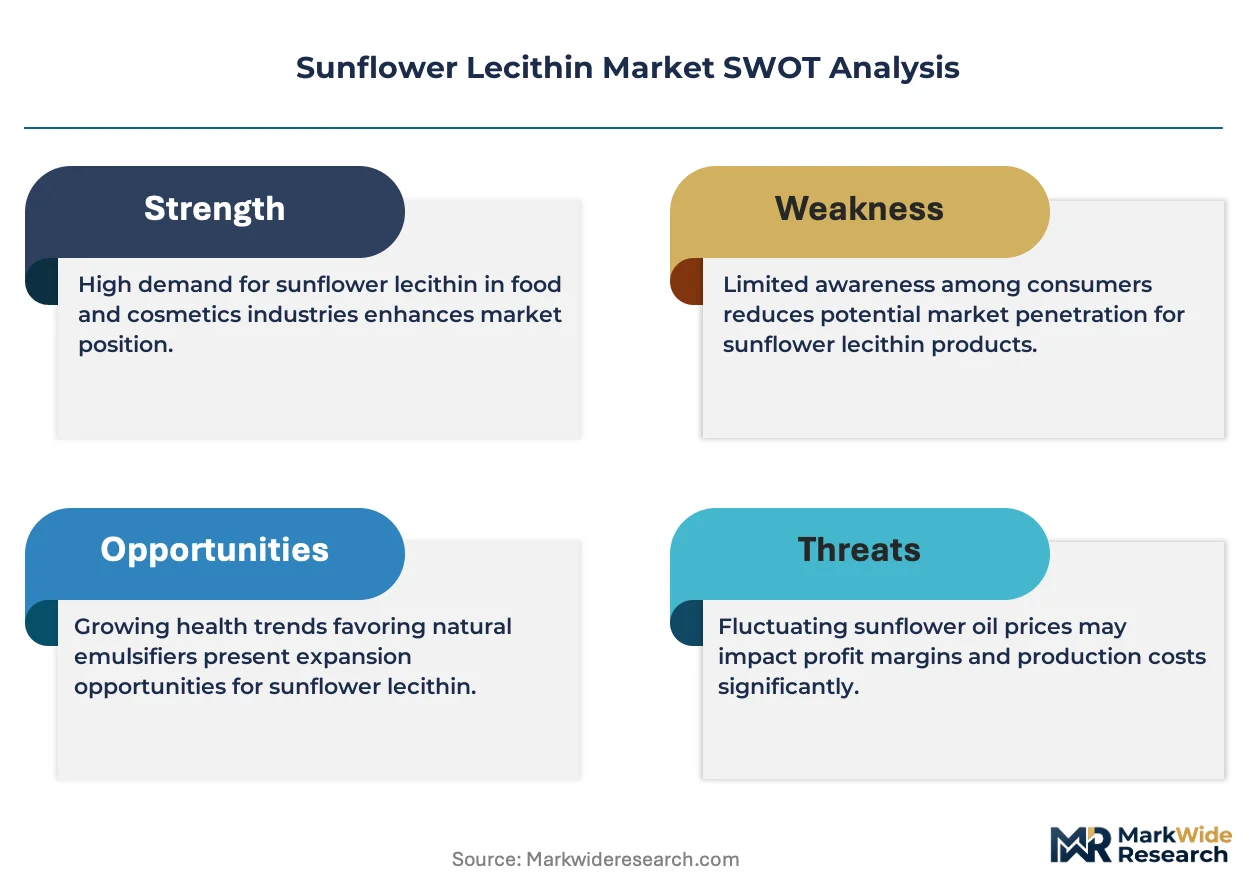
Clean-label emulsification is tilting formulation chemistry away from soy and egg phospholipids toward sunflower-derived alternatives with superior allergen profiles. Ciranda, Inc. leverages its organic supply chain to anchor premium positioning in North American natural foods. Sonic Biochem competes on enzymatic refining scale, while Fismer Lecithin Corporation specializes in high-PC (phosphatidylcholine) pharmaceutical grades.
Sunflower lecithin comprises a mixture of phospholipids—primarily phosphatidylcholine, phosphatidylethanolamine, and phosphatidylinositol—extracted via cold-pressing and degumming of sunflower seed oil, functioning as a natural emulsifier, wetting agent, and dispersant across food, pharmaceutical, and nutraceutical systems. Liquid sunflower lecithin dominates volume due to its direct incorporation into chocolate and bakery streams, while powder and granule forms capture margin in dietary supplements where dosing precision and shelf stability matter. Pharmaceutical-grade material commands premium positioning as manufacturers seek non-GMO, allergen-free excipients for lipid-based drug delivery systems.
FDA food additive regulations and USDA organic certification standards shape product purity thresholds and label claims in the United States, while EFSA and EU REACH frameworks govern phospholipid specifications and environmental compliance across European markets. India's FSSAI and CDSCO are tightening emulsifier quality benchmarks for domestic food and pharmaceutical applications, redirecting import flows toward certified suppliers. Stakeholders must monitor evolving allergen-labeling mandates and phospholipid concentration standards as procurement criteria harden across regulated end-use sectors.
Market Dynamics
Clean-label procurement mandates from food and beverage manufacturers are systematically displacing soy and egg phospholipids, with allergen-free certification now functioning as a non-negotiable gating criterion across contract negotiations.
Growth Catalysts
- EU REACH compliance:Registration, Evaluation, Authorisation and Restriction of Chemicals frameworks mandate detailed substance safety documentation, tilting European emulsifier procurement toward sunflower-derived alternatives with transparent supply chains.
- Chocolate and confectionery wetting:Liquid sunflower lecithin integrates directly into high-throughput tempering lines, eliminating hydration steps required by powder alternatives and reducing process energy.
- India nutraceutical expansion:CDSCO tightening of excipient quality benchmarks for lipid-based drug delivery systems redirects import flows toward certified non-GMO suppliers.
Market Restraints
- Sunflower seed oil price volatility:Crude oil commodity swings transmit directly to lecithin raw material costs, compressing processor margins during drought cycles in Black Sea production zones.
- Enzymatic refining capex:Pharmaceutical-grade phosphatidylcholine concentration requires specialized membrane filtration infrastructure, creating capital barriers for mid-scale processors.
- Soy lecithin substitution inertia:Established soy supply contracts with volume-based pricing tiers delay conversion timelines even where allergen labeling favors sunflower alternatives.
Strategic Opportunities
- Pharmaceutical lipid nanoparticles:mRNA drug delivery platforms require high-purity phospholipid excipients, opening premium positioning for processors with enzymatic fractionation capabilities.
- USDA organic certification arbitrage:Certified organic lecithin commands 40-60% price premiums in North American natural foods channels where clean-label claims drive shelf placement.
- Powder form dosing precision:Dietary supplement manufacturers seek granule and powder formats with defined particle size distributions for tablet compression and capsule filling automation.
Industry Challenges
- Phospholipid assay standardization:Variable analytical methods across ISO, AOCS, and pharmacopeial standards create specification mismatches between suppliers and pharmaceutical buyers.
- Cold-chain degumming logistics:Temperature-controlled transport from crushing facilities to refining plants adds cost layers that erode competitiveness against ambient-stable soy alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunflower Lecithin Market |
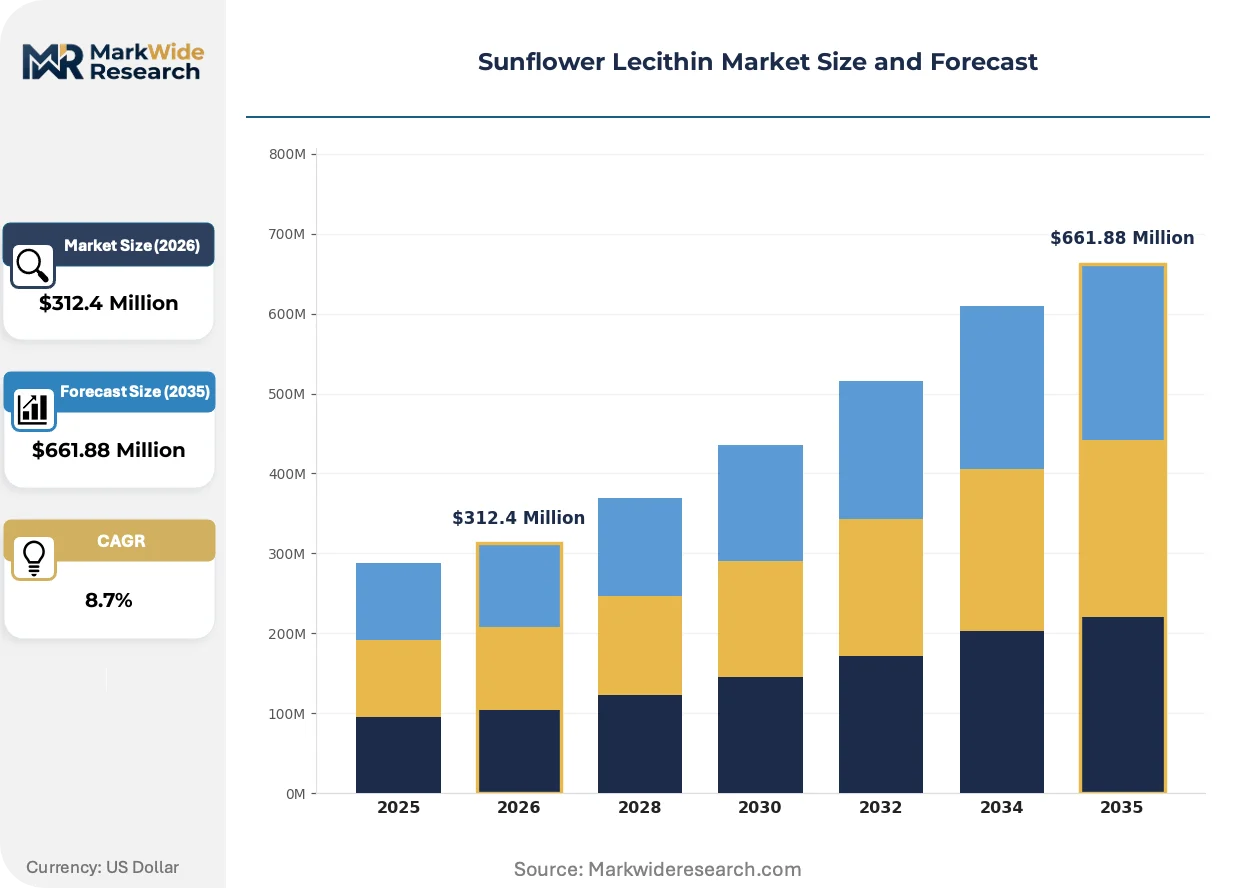
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granules, Powder, Capsules Application: Food & Beverage, Dietary Supplements, Pharmaceuticals, Animal Feed End User: Manufacturers, Retailers, Wholesalers, Distributors Distribution Channel: Online, Offline, Direct Sales, Specialty Stores |
| Companies Covered | Ciranda, Inc., Sonic Biochem, Lecilite, ConnOils LLC, GIIAVA, Fismer Lecithin Corporation, MITUSHI BIO PHARMA, Sun Nutrafoods, Process Agrochem Industries Pvt Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunflower Lecithin Market Evolving Landscape
Enzymatic modification and membrane filtration technologies are reshaping product grade stratification, enabling processors to isolate specific phospholipid fractions for pharmaceutical and nutraceutical applications previously served by synthetic alternatives.
Enzymatic phospholipid modification is hybridizing traditional solvent extraction with targeted hydrolysis, enabling processors to tailor acyl chain profiles for specific emulsification performance. Nutraceutical contract manufacturers in Germany and the United States are adopting these grades for liposomal vitamin encapsulation. The technology is compressing the historical separation between food-grade commodity lecithin and pharmaceutical-grade phospholipid excipients.
EFSA novel food ingredient evaluations and EU REACH substance volume thresholds are tightening purity documentation requirements for imported lecithin. Processors must now maintain batch-level traceability from seed origin through final fractionation. Pharmaceutical and infant nutrition segments are responding by consolidating supplier bases to vertically integrated crushers with captive analytical laboratories.
Buyer concentration among multinational food manufacturers is compressing contracting cycles and unbundling technical service from base ingredient supply. Direct procurement teams at chocolate and bakery conglomerates are establishing approved supplier lists with dedicated quality auditors. This pattern is most visible in Germany and Switzerland, where formulation hubs source lecithin through centralized commodity desks rather than regional distributors.
Sunflower Lecithin Market Segmentation
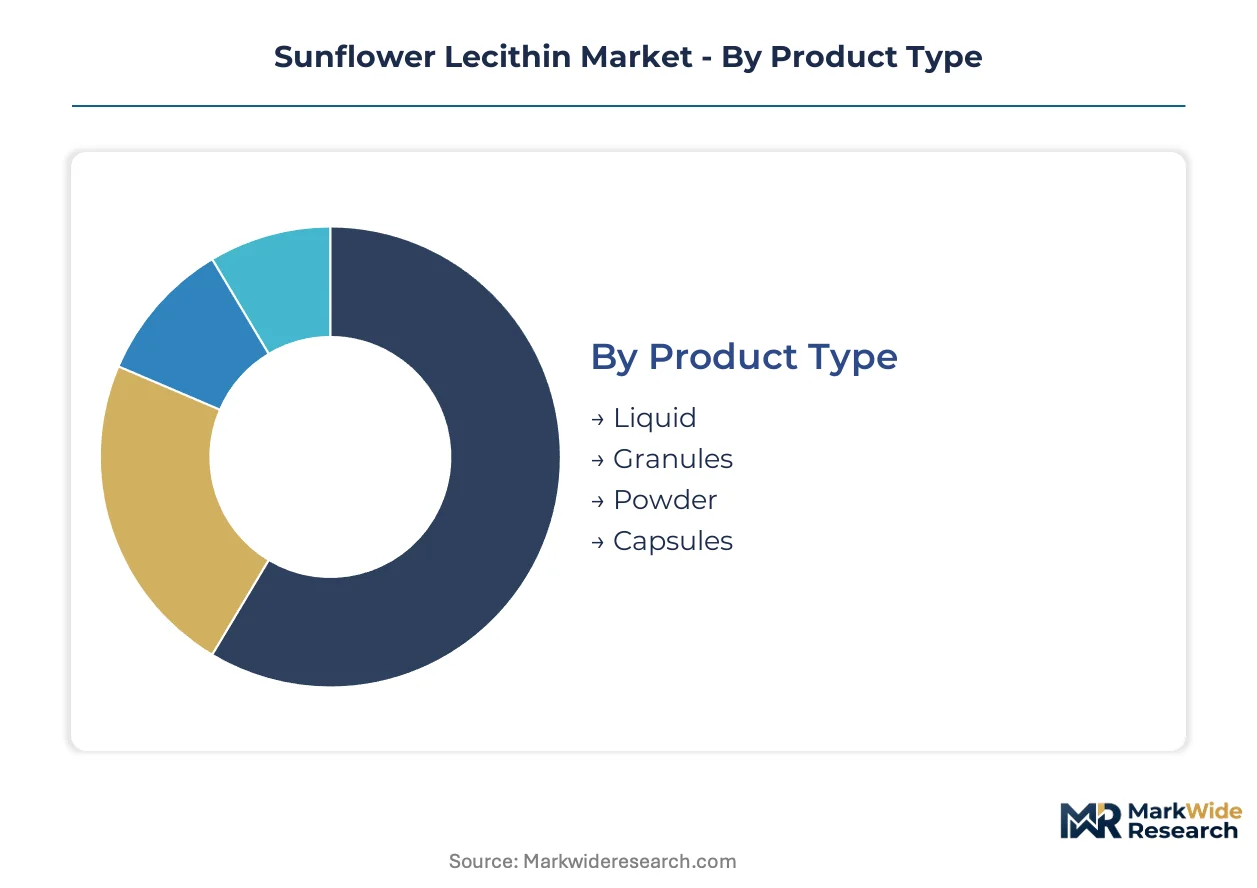
Sunflower lecithin processors differentiate offerings across physical form, regulatory grade, and supply chain configuration. Each segment carries distinct margin profiles and certification requirements that reshape procurement patterns across food, pharmaceutical, and nutraceutical channels.
Product Type:
Physical form determines handling protocols, shelf stability, and integration compatibility across manufacturing environments.
- Liquid:Unrefined or partially refined fluid lecithin extracted directly from degumming operations retains natural phospholipid ratios. Chocolate manufacturers in Germany and Switzerland favor liquid grades for direct injection into tempering lines, bypassing hydration steps and reducing energy consumption. FDA food additive compliance and kosher certification anchor procurement specifications.
- Powder:Spray-dried or acetone-precipitated powders achieve defined particle size distributions for tablet compression and capsule filling automation. Dietary supplement contract manufacturers in the United States specify powder grades with phosphatidylcholine concentrations above 20% for liposomal vitamin encapsulation. Cold-chain stability requirements during transport add cost layers that compress margins against liquid alternatives.
- Granules:Agglomerated forms balance flowability with reduced dust generation during handling.
- Capsules:Pre-encapsulated formats target direct-to-consumer nutraceutical channels with dosing precision.
Established volume favors liquid; emerging adoption favors powder.
Application:
Regulatory intensity and performance specifications stratify demand across end-use sectors.
- Food & Beverage:Bakery, confectionery, and dairy applications exploit sunflower lecithin's emulsification and anti-staling properties. Clean-label procurement mandates from multinational manufacturers in Germany and the United States are systematically displacing soy alternatives. EFSA food additive specifications and EU organic certification standards govern label claims.
- Pharmaceuticals:High-purity phospholipid excipients serve lipid-based drug delivery systems including mRNA nanoparticle formulations. CDSCO tightening of excipient quality benchmarks in India redirects import flows toward certified non-GMO suppliers. Enzymatic fractionation capabilities separate pharmaceutical-grade processors from commodity suppliers.
- Dietary Supplements:Liposomal encapsulation and cognitive health positioning drive premium positioning.
- Animal Feed:Pellet binding and nutritional fortification applications favor cost-optimized liquid grades.
Food & beverage commands current volume; pharmaceuticals are climbing the fastest.
End User:
Procurement scale and technical service requirements differentiate customer relationships.
- Manufacturers:Direct formulation integration demands batch-level traceability and customized phospholipid profiles.
- Retailers:Private-label supplement brands require turnkey capsule and powder packaging.
- Wholesalers:Inventory consolidation across multiple grades serves regional food processors.
- Distributors:Technical service bundling separates value-added resellers from commodity traders.
Manufacturer direct procurement is gaining share fastest; distributor intermediation faces compression.
Distribution Channel:
Channel selection reflects order scale, certification documentation needs, and geographic proximity to crushing infrastructure.
- Direct Sales:Volume commitments from multinational food manufacturers enable dedicated quality auditor programs and approved supplier list status. Swiss chocolate conglomerates and German bakery groups source through centralized commodity desks rather than regional intermediaries.
- Online:E-commerce platforms serve small-batch nutraceutical startups and specialty food producers with minimum order quantities below traditional distributor thresholds.
- Offline:Established distributor networks maintain refrigerated warehousing for liquid inventory.
- Specialty Stores:Organic and natural foods channels command USDA certification premiums.
Direct sales anchor large-account relationships; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukrainian and Russian crushing facilities supply refined lecithin to German chocolate manufacturers and Indian nutraceutical formulators, creating a trade corridor sensitive to Black Sea agricultural volatility.
Germany
Chocolate conglomerates in Cologne and Hamburg drive liquid lecithin procurement for tempering-line integration. EFSA food additive specifications and EU REACH substance documentation requirements filter supplier eligibility toward vertically integrated crushers with captive laboratories. The Rhine-Ruhr industrial corridor hosts formulation hubs that source directly through centralized commodity desks.
United States
Natural foods manufacturers in Minneapolis and Chicago demand USDA organic certification for clean-label emulsifier claims. FDA food additive regulations and kosher certification standards anchor procurement specifications. Ciranda, Inc. leverages its organic supply chain to anchor premium positioning in these channels.
India
Nutraceutical contract manufacturers in Mumbai and Hyderabad seek high-purity phospholipid excipients for liposomal vitamin encapsulation. CDSCO tightening of excipient quality benchmarks redirects import flows toward certified non-GMO suppliers. FSSAI emulsifier standards are hardening domestic quality expectations.
Switzerland
Swiss chocolate manufacturers in Vevey and Zurich specify liquid grades for direct injection into high-throughput production lines. Swissmedic pharmaceutical regulations and EU REACH alignment create dual compliance frameworks for excipient-grade material. The Lake Geneva cluster concentrates premium formulation expertise.
China
Domestic crushers in Shandong and Heilongjiang are expanding enzymatic refining capacity to serve local pharmaceutical and food sectors. SAMR food additive standards and GB quality benchmarks govern label claims and import substitution strategies. The Yangtze River Delta hosts downstream emulsifier formulation facilities.
Sunflower Lecithin Market Competitive Landscape
On the supply side, the industry is bifurcated between commodity liquid processors and specialized fractionators serving pharmaceutical-grade phospholipid demand. The vendor base spans vertically integrated oilseed crushers with captive lecithin streams and independent refiners purchasing crude gum from multiple origins. Three archetypes dominate: organic-certified specialists, enzymatic refining scale operators, and pharmaceutical-grade fractionators. Competitive moves center on backward integration into crushing assets and technology licensing for membrane filtration capabilities.
Among North American organic specialists, Ciranda, Inc. exemplifies the certified-supply-chain archetype, while Fismer Lecithin Corporation occupies a position within the pharmaceutical-grade tier. Sonic Biochem represents the enzymatic refining scale segment. These three anchors illustrate how procurement criteria are hardening around certification depth and phospholipid concentration capabilities.
| Leading Market Players |
|---|
| Ciranda, Inc. |
| Sonic Biochem |
| Lecilite |
| ConnOils LLC |
| GIIAVA |
| Fismer Lecithin Corporation |
| MITUSHI BIO PHARMA |
| Sun Nutrafoods |
| Process Agrochem Industries Pvt Ltd. |
| Others |
Value Network & Pricing Analysis
Black Sea agricultural volatility determines both pricing tier spreads and supply chain shape, compressing margins for liquid-grade processors during drought cycles while pharmaceutical-grade fractionators capture insulation through enzymatic refining premiums.
Pricing Analysis
Commodity-extraction versus enzymatic-fractionation pricing gaps separate three distinct technology generations in sunflower lecithin procurement. Three-tier pricing structure across pharmaceutical-grade, food-grade certified organic, and commodity liquid levels anchors the market, with differentiation resting on phosphatidylcholine concentration thresholds and non-GMO certification depth. Cost compression in commodity liquid tiers is intensifying because Ukrainian seed oil price swings transmit directly to processor margins. Dietary supplement contract manufacturers show least price sensitivity due to liposomal encapsulation performance requirements, while animal feed compounders operate at highest price elasticity.
Supply Chain Analysis
EU REACH substance documentation requirements function as de facto export controls limiting crude gum flows from non-compliant origins. Supply concentrates in Ukraine, Russia, and Argentina as crushing hubs, with downstream refining drawing from Black Sea seed oil, acetone for powder precipitation, and membrane filtration equipment. Single-source vulnerability runs through Ukrainian crushing assets exposed to geopolitical disruption. Distribution runs through vertically integrated processors with captive analytical laboratories serving pharmaceutical buyers, while commodity liquid flows through regional distributor networks with refrigerated warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sunflower lecithin incumbents face a substitution defense against synthetic phospholipid alternatives and enzymatically modified soy fractions that threaten premium positioning in liposomal drug delivery applications.
For Market Incumbents: Harden analytical certification depth to meet EFSA novel food ingredient documentation and CDSCO excipient quality benchmarks, closing the aperture for synthetic substitute penetration. Deepen backward integration into Black Sea crushing assets to secure seed origin traceability and buffer commodity price volatility. Prioritize enzymatic fractionation capacity additions in Germany and India to defend pharmaceutical-grade margin premiums against soy lecithin enzymatic modification advances.
For New Entrants and Emerging Players: Establish a beachhead in USDA organic certified powder grades for North American natural foods channels, where Ciranda's supply chain concentration creates service gaps for mid-scale dietary supplement manufacturers. Target liposomal vitamin contract manufacturers in Hyderabad and Mumbai seeking non-GMO phospholipid excipients with defined particle size distributions. Lead with batch-level seed-to-finished-product traceability as the go-to-market wedge against commodity traders lacking documentation depth.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated crushers with captive pharmaceutical-grade fractionation capabilities over independent refiners exposed to raw material cost volatility. Long-term viability across the analysis window hinges on enzymatic refining technology access and regulatory certification infrastructure rather than commodity scale. Watch CDSCO and FSSAI alignment on phospholipid assay standardization as the signal indicating which processor archetypes will capture nutraceutical contract manufacturing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Fractionation Capacity Expansion | Separates pharmaceutical-grade processors from commodity liquid suppliers in mRNA excipient procurement. |
| Backward Integration into Black Sea Crushing | Secures seed origin traceability required for EU REACH substance documentation and organic certification claims. |
| USDA Organic Certification Investment | Unlocks 40-60% price premiums in North American natural foods channels where clean-label claims drive shelf placement. |
| Long-term Supply Agreement with Nutraceutical Formulators | Locks in volume commitments from Mumbai and Hyderabad liposomal encapsulation specialists facing CDSCO quality benchmark tightening. |
| Joint Venture for Membrane Filtration Technology Licensing | Accelerates pharmaceutical-grade phosphatidylcholine concentration capabilities without full proprietary R&D burden. |
Research Methodology
Operator-level perspectives from sunflower seed crushers, lecithin refinery plant managers, procurement leads at chocolate and bakery conglomerates, and regulatory affairs directors at nutraceutical contract manufacturers anchored the qualitative base. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through EFSA food additive specifications, CDSCO excipient quality circulars, FSSAI emulsifier standards, USDA organic certification databases, and EU REACH substance volume threshold documentation. Bottom-up volume modeling across liquid, powder, granule, and capsule physical forms triangulated against top-down demand estimates from food, pharmaceutical, dietary supplement, and animal feed end-use sectors.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning physical form, regulatory grade tier, application intensity, and geographic production hub concentration. CAGRs emerged from fitted growth curves applied to historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated sunflower seed oil commodity price volatility assumptions and regulatory compliance cost escalators for phospholipid assay standardization.
Macroeconomic conditions sit as an overlay; deviation in Black Sea agricultural output, EU-Asia trade route stability, or pharmaceutical excipient regulatory alignment would shift the trajectory. Forecasts reflect documented assumptions regarding enzymatic refining technology diffusion rates and certification infrastructure investment patterns. Material shifts in CDSCO-FSSAI regulatory harmonization or synthetic phospholipid substitute performance breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Malted Wheat Flour Market
Ingredients
Africa Fats and Oil Market
Ingredients
US Vegetable Oil Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Europe Feed Yeast Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Seaweed Derivatives Market
Ingredients
Gymnema Extract Market
Ingredients
Textural Food Ingredients Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Canada Soy Protein Market
Ingredients
North America Corn Starch Market
Ingredients
Konjac Root Fiber Market