
 Bean Flour Market | 2026-2036
Bean Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Bean Flour Market Intelligence
The shift from bulk sacks to smaller, resealable stand-up pouches for retail channels is recalibrating consumer purchasing decisions for specialty bean flours. Large-scale suppliers like Cargill, Incorporated leverage extensive global distribution networks to serve industrial clients. Archer Daniels Midland Company competes on processing efficiency and ingredient blending capabilities. In contrast, Bob's Red Mill Natural Foods specializes in the premium, consumer-packaged segment with a focus on certified organic and gluten-free products.
Bean flour is a powdered ingredient produced by milling dried beans, such as chickpeas, lentils, or fava beans, into a fine consistency. It serves as a high-protein, high-fiber, and gluten-free alternative to traditional wheat flours in various food applications. Chickpea flour leads the market due to its versatility in both savory and sweet gluten-free baking. The meat substitutes segment, which uses flours from fava and mung beans for their binding properties, shows the highest growth rate.
Food safety and labeling standards, including the FDA's regulations on gluten-free claims in the United States and the EFSA's allergen directives in Europe, govern market access. In India, the FSSAI's fortification guidelines are creating new opportunities for nutrient-enriched bean flours. Stakeholders must now decide whether to invest in specialized processing for high-protein isolates or focus on cost-effective milling for bulk commodity markets.
Market Dynamics
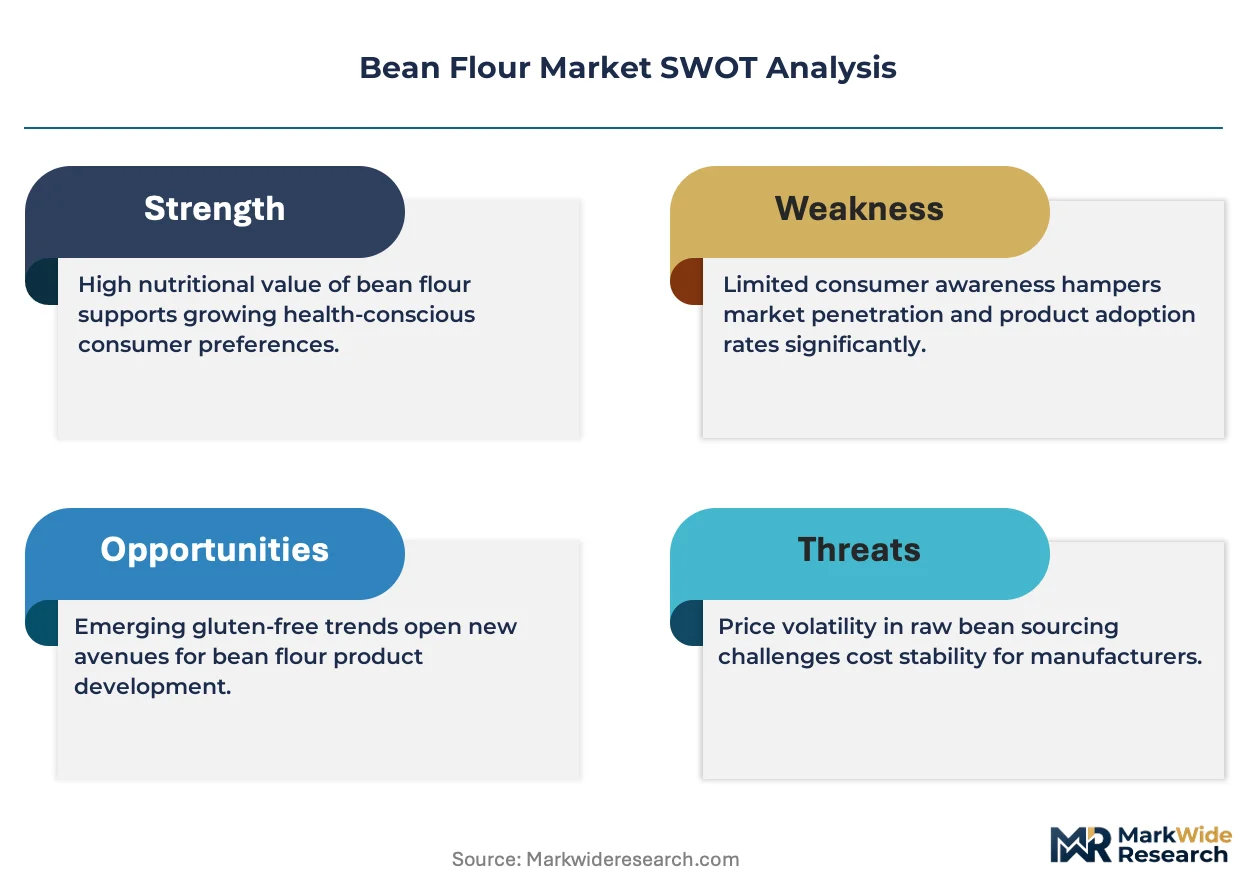
The primary structural force shaping the market is the dual pressure from consumers demanding plant-based, gluten-free foods and regulators enforcing stricter allergen labeling. This combination compels food manufacturers to reformulate products, creating a direct pull for alternative flours.
Growth Catalysts
- Gluten-Free Baking Sector:Rising diagnoses of celiac disease and gluten sensitivity in North America and Europe are driving the substitution of wheat flour in bakery products.
- Plant-Based Diets:The consumer shift towards veganism and flexitarianism increases the use of bean flours as a protein source in meat substitutes and fortified snacks.
- Allergen Labeling Regulations:Mandates from the FDA and EFSA force manufacturers to declare common allergens, pushing them towards inherently allergen-free ingredients like bean flour.
Market Restraints
- Inherent Flavor Profiles:The distinct taste of certain bean flours, particularly from fava or soy beans, requires masking agents or complex formulation, limiting direct substitution in flavor-sensitive products.
- Agricultural Supply Volatility:Bean crop yields are vulnerable to climate events, causing price fluctuations for raw materials and impacting miller profit margins.
- Technical Processing Barriers:Achieving fine, consistent particle sizes and desirable functional properties necessitates specialized milling equipment, presenting a high capital barrier for entry.
Strategic Opportunities
- Nutrient Fortification Programs:India's FSSAI fortification guidelines open a pathway for nutrient-enriched bean flours in government-supported food programs and retail products.
- Extruded Product Innovation:The application of lentil and chickpea flours in high-protein, gluten-free extruded snacks and pastas represents a significant new product category.
- High-Protein Isolates:Developing processing capabilities for bean protein isolates targets the high-value sports nutrition and infant formula segments seeking clean-label ingredients.
Industry Challenges
- Certification Complexity:Maintaining and documenting supply chain integrity for certifications like non-GMO and organic is a costly and resource-intensive operational burden for suppliers.
- Formulation Skill Scarcity:A shortage of food scientists with expertise in reformulating products using bean flours slows the innovation cycle for food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bean Flour Market |
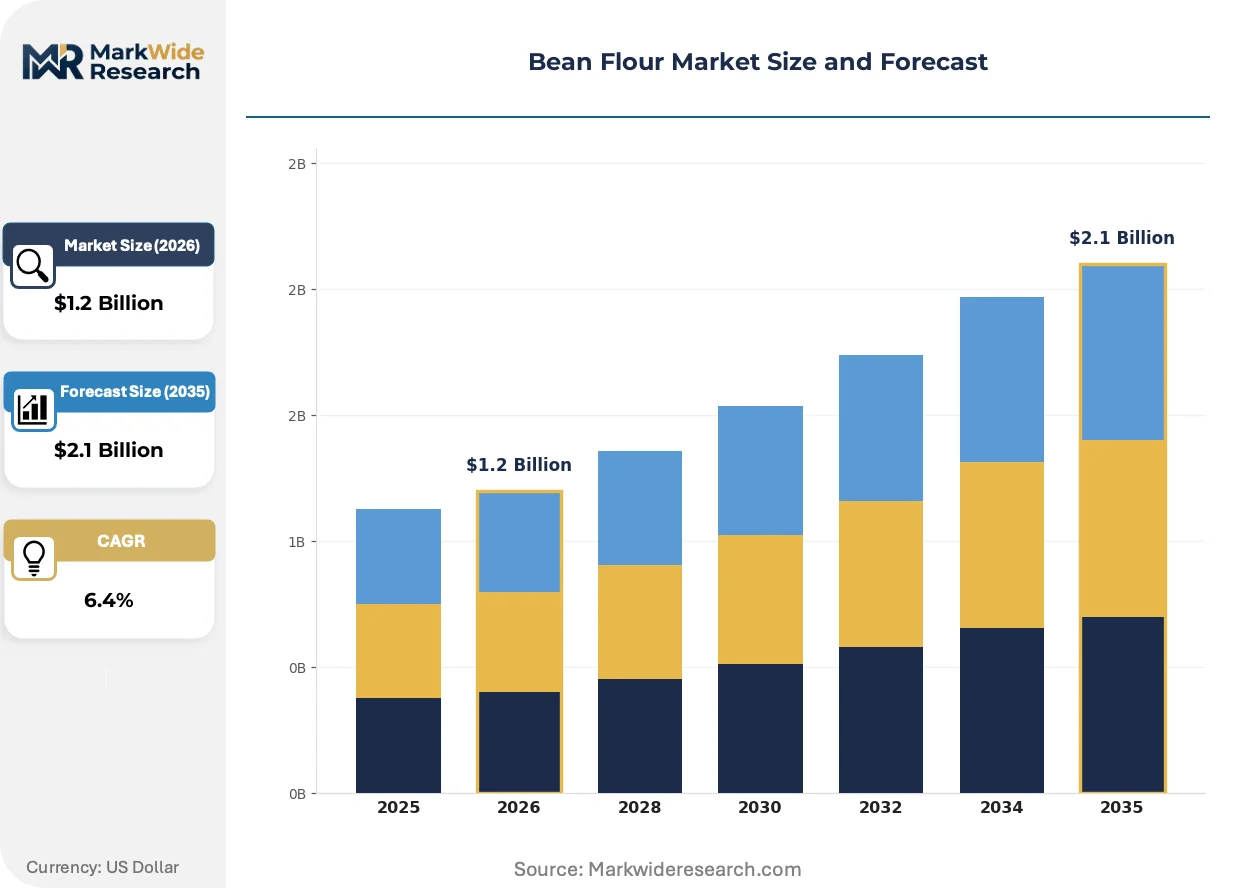
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chickpea Flour, Lentil Flour, Mung Bean Flour, Fava Bean Flour, Navy Bean Flour Application: Gluten-Free Baking, Meat Substitutes, Thickening Agent, Infant Food, Nutritional Supplements End User: Bakery Manufacturers, Foodservice Providers, Dietary Supplement Companies, Infant Nutrition Firms, Vegan Product Developers Packaging Type: Vacuum Sealed Bags, Stand-up Pouches, Bulk Sacks, Paper Bags, Plastic Containers |
| Companies Covered | Cargill, Incorporated, Ottogi Co., Ltd., Archer Daniels Midland Company, SunOpta Inc., Tate & Lyle PLC, Ingredion Incorporated, Bob's Red Mill Natural Foods, Olam International Limited, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bean Flour Market Strategic Shifts & Innovations
Technological advancements in milling and fractionation are bifurcating the market. This creates a clear distinction between high-value, functional ingredients for specialized applications and cost-effective flours for bulk commodity use, reshaping competitive positioning.
Dry fractionation and air classification technologies separate dried beans into concentrated protein and starch streams without using water or chemicals. Ingredient manufacturers targeting the meat substitute and sports nutrition sectors are rapidly adopting this process. This advancement is electrifying the ingredient landscape by unlocking higher-value functional components from the same raw bean input.
The European Food Safety Authority (EFSA) provides scientific advice that underpins the EU's stringent allergen labeling laws, including for gluten. This regulatory framework requires food producers to clearly identify potential allergens, creating a compliance-driven need for alternatives to wheat. The European bakery sector is most impacted, accelerating its switch to certified gluten-free flours.
Consumer-facing packaging formats are shifting from bulk sacks to smaller, resealable stand-up pouches, particularly for specialty flours. This change disrupts the traditional bulk distribution model and favors brands with strong retail channel access. The trend is most visible in the health-conscious consumer segment in North America and Germany.
Bean Flour Market Segmentation
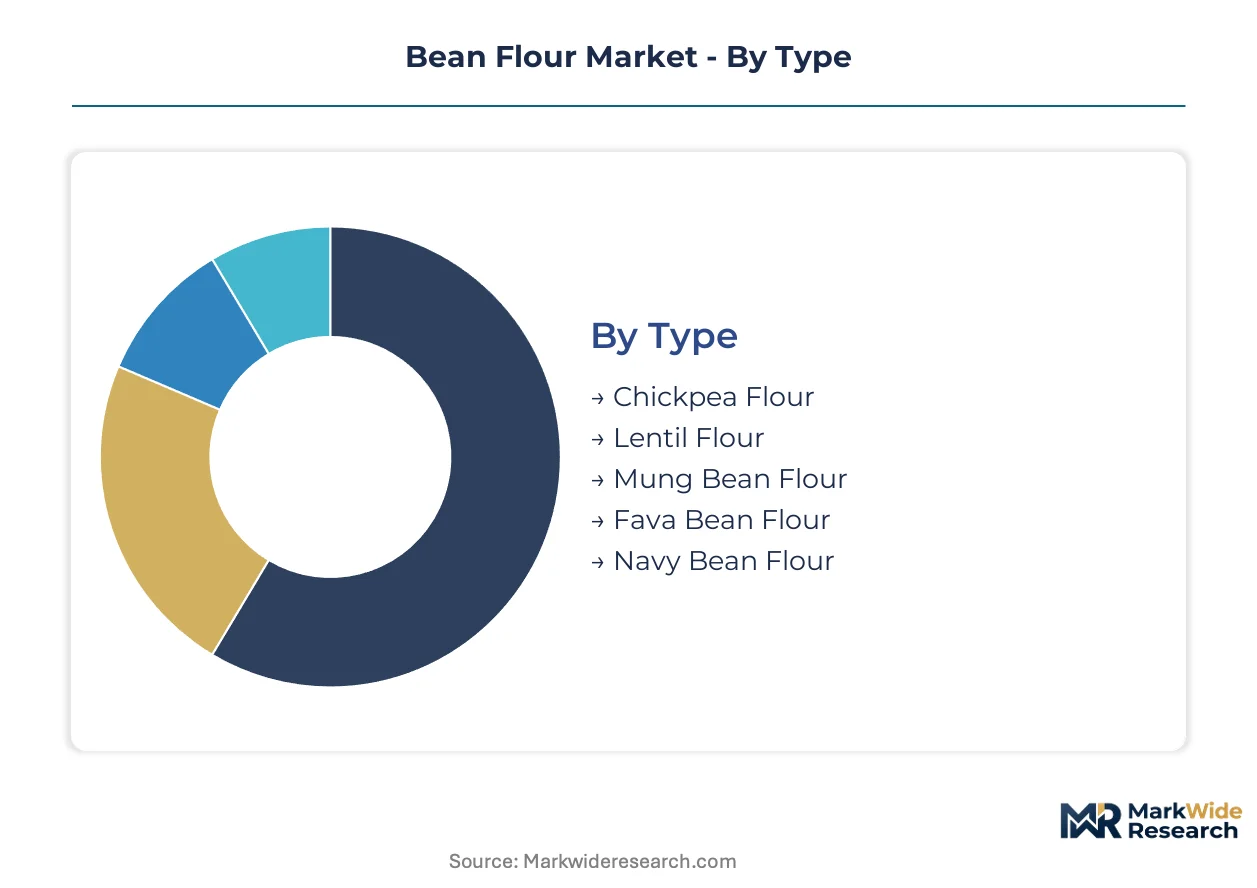
The bean flour market segments across diverse product types, applications, end users, and packaging formats. Understanding these distinctions is crucial for stakeholders to identify specific demand pockets and optimize product development strategies. Each segment reflects unique processing requirements or consumer preferences that influence market dynamics.
Type:
The market for bean flour differentiates based on the specific bean variety and its inherent processing characteristics.
- Chickpea Flour:This versatile flour is produced from ground chickpeas, offering a neutral flavor profile and excellent binding properties for gluten-free applications. Demand concentrates in the gluten-free baking sector across North America and Europe due to its wide acceptance and functional benefits.
- Lentil Flour:Milled from dried lentils, this flour provides a high-protein, fiber-rich ingredient for various food formulations. Lentil flour is increasingly used in extruded products like pastas and snacks, especially in regions prioritizing plant-based nutrition.
- Mung Bean Flour:Derived from mung beans, this type of flour is valued for its light texture and nutritional content. It finds application in Asian cuisine and is gaining traction in meat substitute formulations for its binding capabilities.
- Fava Bean Flour:Ground from fava beans, this flour offers a robust protein source and strong binding characteristics, making it suitable for meat alternative products. Demand for fava bean flour is expanding in the meat substitutes segment, particularly in Europe, driven by plant-based dietary shifts.
- Navy Bean Flour:Produced from navy beans, this flour is used for its thickening properties and nutritional value. It often serves as an ingredient in soups, sauces, and gluten-free mixes.
Mature deployment sits with Chickpea Flour. Newer deployment is concentrated in Fava Bean Flour.
Application:
Market application segments highlight the diverse functional uses of bean flours across the food industry.
- Gluten-Free Baking:Bean flours serve as primary alternatives to wheat flour in bakery products, catering to consumers with celiac disease or gluten sensitivities. This application sees significant demand in Germany and the United States, driven by health trends and allergen labeling regulations.
- Meat Substitutes:Formulations for plant-based meat alternatives extensively utilize bean flours for their protein content and binding properties, mimicking the texture of conventional meat products. The meat substitutes segment exhibits the steepest expansion trajectory, fueled by global vegan and flexitarian movements.
- Thickening Agent:Certain bean flours, like navy bean flour, function as effective natural thickening agents in sauces, gravies, and soups. Food manufacturers use these flours to improve product consistency and mouthfeel.
- Infant Food:Nutrient-dense bean flours are incorporated into infant formula and baby food for their protein, fiber, and mineral content. Manufacturers focus on highly processed, easily digestible forms for this sensitive application.
- Nutritional Supplements:Bean protein isolates and flours are used in protein powders, bars, and other dietary supplements for athletes and health-conscious consumers. These products often target the sports nutrition market with clean-label ingredients.
Gluten-Free Baking remains a foundational application. Meat Substitutes are currently gaining share fastest.
End User:
The end-user segmentation reflects the primary industries and businesses that incorporate bean flours into their products or services.
- Bakery Manufacturers:These companies utilize bean flours to produce a wide array of gluten-free breads, pastries, and other baked goods. European bakery manufacturers are actively reformulating products to meet stricter allergen guidelines.
- Foodservice Providers:Restaurants, cafes, and institutional kitchens use bean flours in their culinary preparations, particularly for gluten-free and plant-based menu options. This segment responds to evolving consumer dietary preferences in dining.
- Dietary Supplement Companies:Manufacturers of protein powders, nutrition bars, and health supplements source bean flours and isolates for their high protein and fiber content. These firms target consumers seeking functional food ingredients.
- Infant Nutrition Firms:Companies specializing in baby food and infant formula integrate bean flours for their nutritional value and hypoallergenic properties. Product development focuses on digestibility and nutrient profiles for early childhood.
- Vegan Product Developers:Innovators in the plant-based food industry extensively use bean flours as foundational ingredients for meat alternatives, dairy-free products, and vegan snacks. This group drives innovation in new product categories.
Bakery Manufacturers represent a mature market segment. Vegan Product Developers demonstrate strategic focus on emerging trends.
Packaging Type:
Packaging type segmentation illustrates the various formats in which bean flours are distributed, catering to different distribution channels and consumer needs.
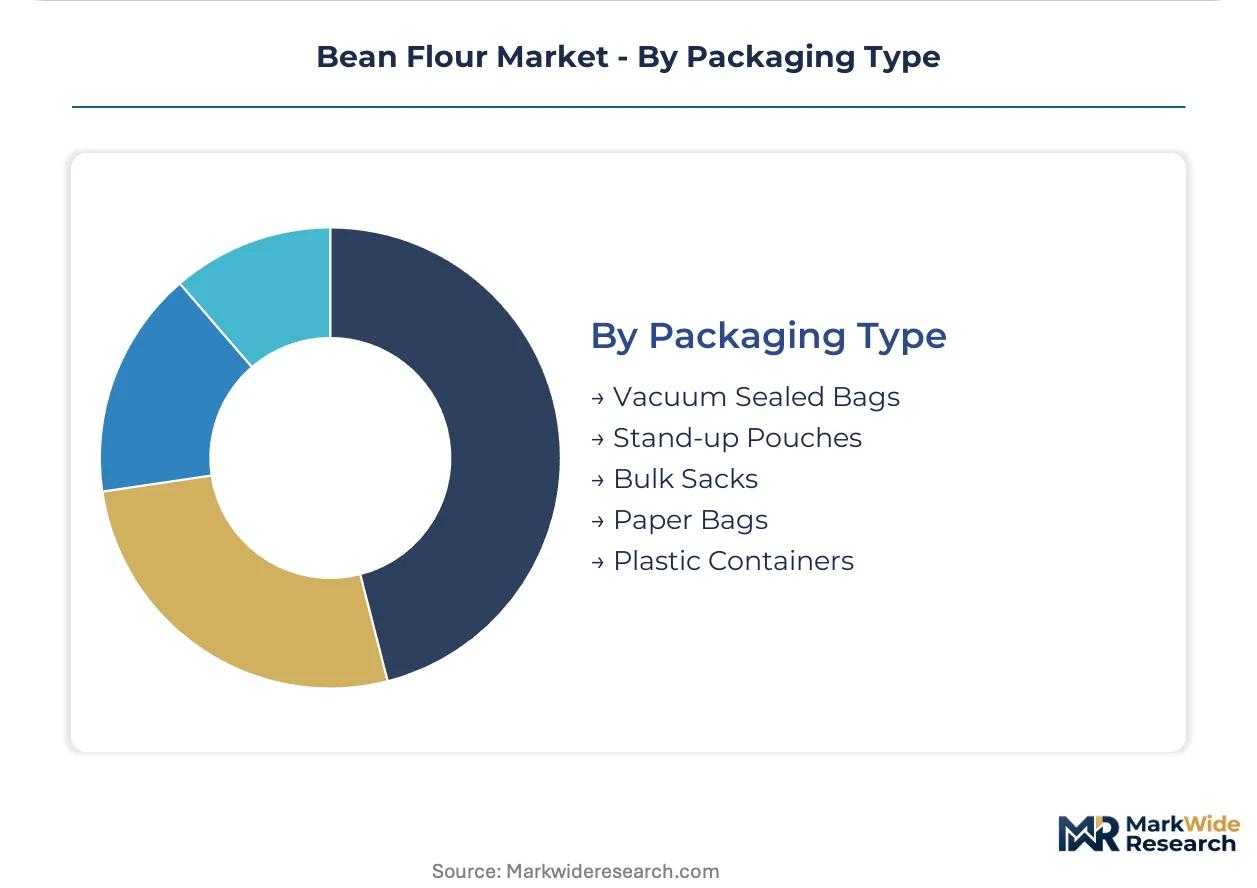
- Vacuum Sealed Bags:This packaging extends shelf life and protects bean flour from moisture and oxidation, typically for bulk or specialty applications. These bags are common for preserving ingredient quality in industrial settings.
- Stand-up Pouches:Smaller, resealable stand-up pouches are gaining popularity in retail channels for specialty and consumer-packaged bean flours. This format appeals to health-conscious consumers in North America and Germany seeking convenience.
- Bulk Sacks:Large bulk sacks are the primary packaging for industrial clients, including major food manufacturers and ingredient suppliers. Cargill, Incorporated leverages this format for its extensive global distribution network.
- Paper Bags:Traditional paper bags offer a cost-effective and breathable packaging solution for various bean flours, particularly in commodity markets. This format remains prevalent for general purpose flour distribution.
- Plastic Containers:Rigid plastic containers provide durability and reusability, often used for premium or organic bean flour brands in retail. These containers offer enhanced protection during transport and storage.
Bulk Sacks dominate industrial distribution. Stand-up Pouches are recalibrating consumer purchasing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bean flour market exhibits a clear divide between major agricultural production hubs and high-demand consumption centers. Regions with extensive bean cultivation often serve as primary raw material suppliers, while developed economies drive consumption through evolving dietary preferences. This dynamic influences both supply chain configurations and product innovation across geographies.
United States
United States demand for bean flour stems from rising celiac disease diagnoses and the expanding gluten-free baking sector. FDA regulations on gluten-free claims compel food manufacturers to reformulate products with alternative flours. California's food innovation hubs actively drive new product development utilizing diverse bean flour types.
Germany
Germany demonstrates strong consumer preference for plant-based and allergen-free ingredients, boosting bean flour adoption in the European bakery sector. EFSA's stringent allergen directives require clear labeling, accelerating the switch to certified gluten-free flours. Berlin's vibrant food tech startups are integrating bean flours into novel, health-conscious product lines.
India
India's market presents significant opportunities due to nutrient fortification programs and a large consumer base seeking healthy alternatives. FSSAI's fortification guidelines encourage the development of nutrient-enriched bean flours for public health initiatives. Maharashtra's food processing zones are becoming centers for fortified bean flour product manufacturing.
Brazil
Brazil, a major agricultural producer, sees increasing domestic demand for plant-based proteins and gluten-free options. ANVISA food safety standards guide local processing and ingredient quality for bean flour production. São Paulo's expansive food industry explores bean flour applications in various packaged goods and meat substitutes.
China
China's large and health-conscious consumer market drives demand for nutritious and plant-based food ingredients like bean flour. SAMR food safety regulations ensure quality control and market access for bean flour products. Shanghai's food manufacturing sector actively adopts bean flours for new product lines, particularly in snacks and meat alternatives.
Bean Flour Market Key Industry Players
The competitive structure tilts toward a tiered system, balancing large-scale commodity suppliers with specialized premium ingredient providers. Strategic archetypes include global agricultural conglomerates, which control vast supply chains and serve industrial clients, alongside regional processing specialists optimizing for ingredient blending and efficiency. A third archetype comprises niche consumer-focused brands emphasizing certified organic and gluten-free products. Dominant competitive moves involve significant capacity expansion for bulk production and strategic portfolio diversification to capture high-value specialty market segments, often through new product development.
At the scale-driven end, Cargill, Incorporated leverages extensive global distribution networks to serve industrial clients with bulk bean flour products. Archer Daniels Midland Company occupies a position focused on processing efficiency and ingredient blending capabilities for a broad range of food manufacturers. Bob's Red Mill Natural Foods exemplifies the premium, consumer-packaged segment, specializing in certified organic and gluten-free bean flour offerings.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ottogi Co., Ltd. |
| Archer Daniels Midland Company |
| SunOpta Inc. |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Bob's Red Mill Natural Foods |
| Olam International Limited |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in the bean flour sector often prioritize long-term supply relationships, influencing contract-based pricing stability over spot market volatility. This ownership pattern fosters resilience against short-term price fluctuations for raw materials.
Pricing Analysis
Margin tightening in commodity bean flours traces to agricultural supply volatility and intense competition among bulk suppliers. The dominant pricing structure is contract-based long-term offtake for industrial clients, while retail specialty flours use value-based pricing. Price differentiation stems from certified organic status and fine particle size. Industrial buyers are highly price-sensitive, whereas premium consumer segments prioritize quality and certifications.
Supply Chain Analysis
Reverse logistics for bean flour primarily involves managing product returns due to quality issues or expired shelf life, with minimal remanufacturing potential. Geographic supply concentrates in Brazil and India, which are major bean producers, alongside processing hubs in the United States. Raw material dependencies include dried chickpeas, lentils, and fava beans. Commodity price volatility represents a significant structural risk. Downstream distribution predominantly runs through industrial bulk channels and specialty retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bean flour market is becoming a consolidation play, with stricter food safety and labeling mandates forcing smaller, less compliant producers out of the supply chain.
For Market Incumbents: Hedge against emerging competition by investing in advanced fractionation technologies to extract high-protein isolates, targeting the sports nutrition segment. Strengthen control over certified organic bean sourcing to mitigate supply chain certification complexity. Cargill, Incorporated could leverage its global distribution network for new specialty product lines, addressing the threat of niche players.
For New Entrants and Emerging Players: India's FSSAI fortification guidelines in India open a window for specialized manufacturers to introduce nutrient-enriched bean flours for public health programs. Focus on developing high-protein extruded snacks using lentil and chickpea flours, targeting the rapidly expanding plant-based consumer segment in Europe. A direct-to-consumer online sales model offers a penetrable go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap processors in the United States, particularly those with specialized milling capabilities for allergen-free production. Long-term viability hinges on capturing growing demand for plant-based proteins and gluten-free alternatives. The signal to watch is the adoption rate of dry fractionation technologies by smaller players, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Fractionation | Enables production of high-value protein isolates for sports nutrition. |
| Certification Investment (Organic/Gluten-Free) | Secures access to premium consumer segments in North America. |
| Partnerships with Vegan Product Developers | Accelerates innovation in the fast-growing meat substitutes application. |
| Geographic Expansion into Fortification Programs | Captures opportunities within nutrient-enriched markets like India. |
| Advanced Packaging Development | Differentiates retail offerings with resealable stand-up pouches for consumers. |
Research Approach
FDA reports, EFSA directives, and FSSAI guidelines formed the secondary backbone, supplemented by agricultural statistics from USDA and FAO. Primary interviews with food scientists, procurement managers at bakery manufacturers, regulatory affairs experts, and mill operators provided granular insights. This approach facilitated bottom-up market sizing and top-down validation.
A bottom-up analytical lens informed volume and value projections across the analysis window. Segmentation dimensions modeled included product type, application, end user, packaging format, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected demand drivers. Key forecast inputs included celiac disease diagnosis rates and plant-based diet adoption trends.
The model assumes a particular technology adoption path; alternative pathways for dry fractionation would alter the outlook. Forecasts reflect assumptions regarding agricultural supply stability and consumer preference shifts. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Marine Collagen Ingredients Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Yeast Autolysates Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Global Gelatin Market
Ingredients
Bovine Gelatin Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Asia-Pacific Protein Market
Ingredients
North America Milk Protein Market
Ingredients
Hops Derivative Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Virginiamycin Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Plant Based Ingredients Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market