
 Calendula Oil Market | 2026-2036
Calendula Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Calendula Oil Market Outlook
ISO 16128 natural origin certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Weleda AG leverages its biodynamic cultivation network to secure premium shelf placement in European pharmacies. Mountain Rose Herbs anchors its position through direct relationships with certified organic farms across the Pacific Northwest. AOS Products competes on volume scale, supplying refined calendula oil to mid-tier cosmetics manufacturers in South Asia.
Calendula oil is a fixed oil extracted from Calendula officinalis flower heads, typically yielding 20-25% lipids rich in faradiol esters and triterpenoids through cold-press or solvent extraction methods, primarily serving anti-inflammatory and skin-repair functions in topical formulations. Organic product type commands the dominant margin pool as clean-label cosmetics manufacturers absorb premium feedstock costs to maintain certification claims. Pharmaceutical application represents the fastest-expanding segment, driven by wound-healing and dermatitis treatment protocols that require standardized flavonoid content. Essential and extract grades occupy distinct technical niches, with the former serving aromatherapy diffusion and the latter concentrated actives for clinical cosmeceuticals.
EMA guidelines on herbal medicinal products and EU REACH registration requirements for botanical extracts collectively raise the compliance threshold for market entry, filtering out uncertified suppliers. USDA Organic and ISO 9001 quality management standards further segment export eligibility, particularly for North American and Asian market access. Stakeholders must monitor evolving pharmacopeial monographs and adapt extraction protocols to meet tightening heavy metal and pesticide residue limits.
Market Dynamics
EU REACH registration requirements for botanical extracts are filtering supplier bases as certification costs rise, concentrating procurement among qualified organic processors while marginalizing uncertified regional producers.
Growth Catalysts
- Clean-label cosmetics procurement:Formulators in certified organic skincare lines absorb premium feedstock costs to maintain ISO 16128 natural origin claims.
- EMA herbal medicinal product guidelines:Standardized wound-healing protocols requiring documented flavonoid content expand pharmaceutical-grade demand.
- Biodynamic cultivation networks:Pacific Northwest and Central European farming clusters secure pharmacy channel placement through direct farm-to-formulator relationships.
Market Restraints
- Input cost volatility:Organic Calendula officinalis flower head prices fluctuate with weather-dependent yields in Ukraine and Poland growing regions.
- Regulatory friction:USDA Organic and EU Organic equivalence disputes create dual-certification burdens for cross-Atlantic exporters.
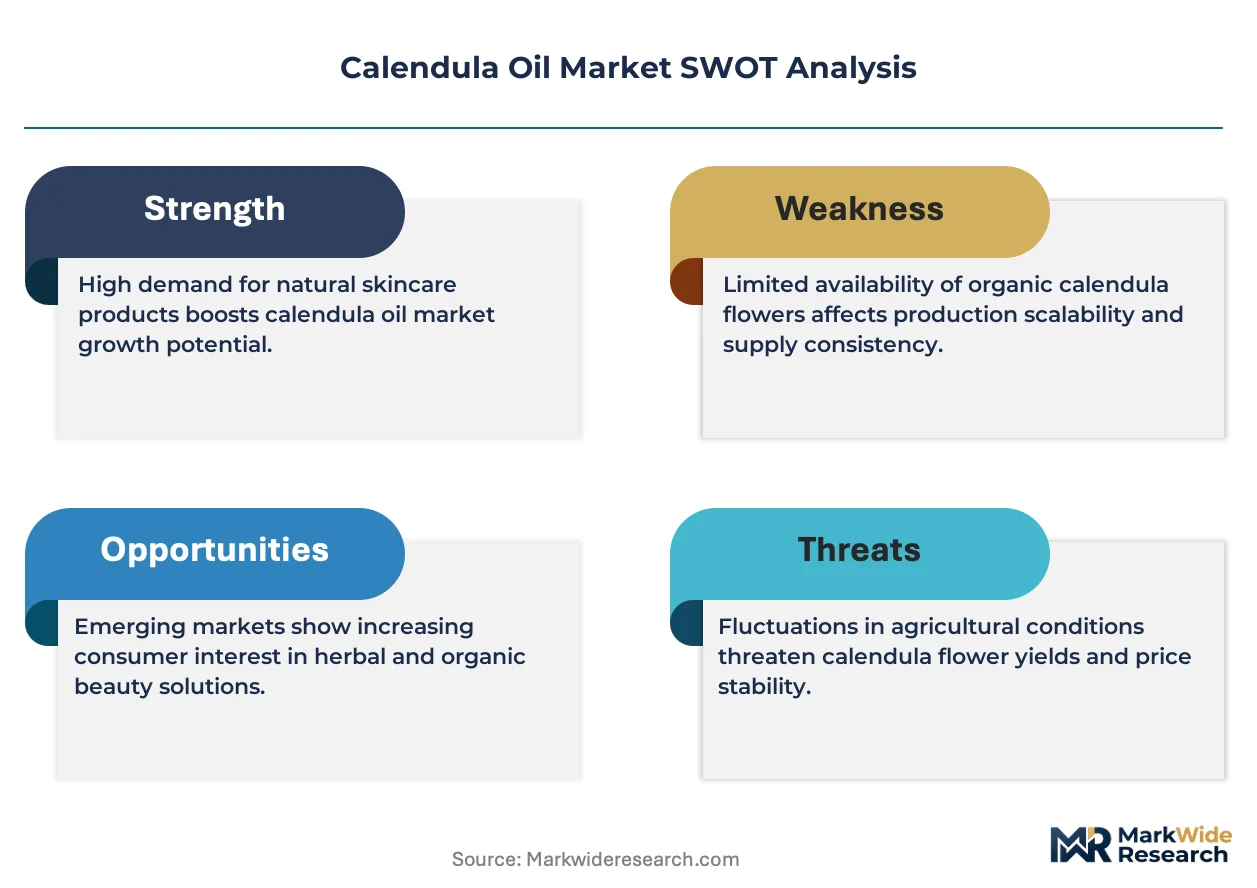
- Substitution threat:Synthetic faradiol esters from pharmaceutical chemical suppliers undercut natural extract pricing in cost-sensitive cosmeceutical segments.
Strategic Opportunities
- Clinical dermatology protocols:Hospital-based dermatitis treatment programs in Germany and France require standardized calendula oil with heavy metal documentation.
- Direct-to-practitioner channels:Aromatherapy supply houses bypass traditional distributor markups by sourcing essential-grade oil from certified organic distillers.
- EU Green Deal bioeconomy incentives:Circular extraction technologies using supercritical CO2 qualify for sustainability-linked procurement preferences.
Industry Challenges
- Analytical chemistry skill gaps:Triterpenoid quantification and pesticide residue testing require trained chromatography technicians that rural processing facilities struggle to retain.
- Pharmacopeial monograph alignment:European Pharmacopoeia and United States Pharmacopeia diverging standards on calendula extract specifications force dual validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calendula Oil Market |
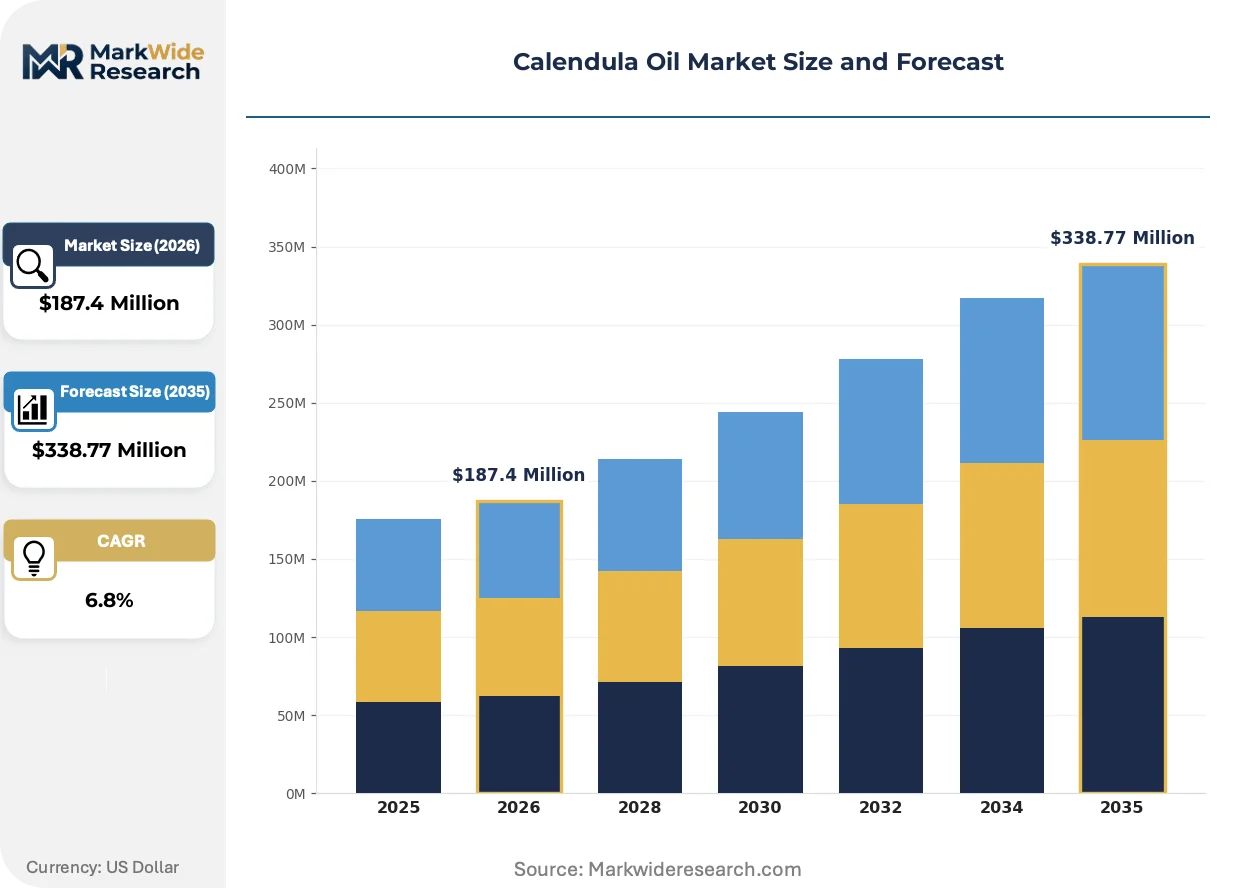
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Synthetic, Essential, Extract Application: Cosmetics, Pharmaceuticals, Food Industry, Aromatherapy End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Offline, Specialty Stores, Health Stores |
| Companies Covered | Starwest Botanicals, Kiehl’s Since 1851, Mountain Rose Herbs, AOS Products, Telia Oils, Weleda AG, NOW Health Group, Aadhunik Ayurveda, Herb Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calendula Oil Market Strategic Shifts
Supercritical CO2 extraction and pharmacopeial standardization are compressing traditional solvent-based processing margins while elevating analytical capability requirements across supplier tiers.
Supercritical CO2 extraction systems are displacing hexane solvent methods in premium-grade production. German and Swiss cosmetics manufacturers specify CO2-extracted oil for certified organic lines. This technology is displacing batch-process solvent operators unable to finance capital upgrades.
REACH Annex XVII restrictions on botanical heavy metal thresholds tighten testing protocols. ECHA guidance documents now require ICP-MS documentation for cadmium and lead in flower head sourcing. Extract-grade suppliers serving pharmaceutical applications face the steepest compliance cost escalation.
Certification-driven preference shifts concentrate buyer power among ISO 9001 and organic-certified processors. French pharmacy chains now require batch-specific heavy metal certificates. This pattern appears most pronounced in German-speaking Central European markets where pharmacist consultation drives product selection.
Calendula Oil Market Segmentation
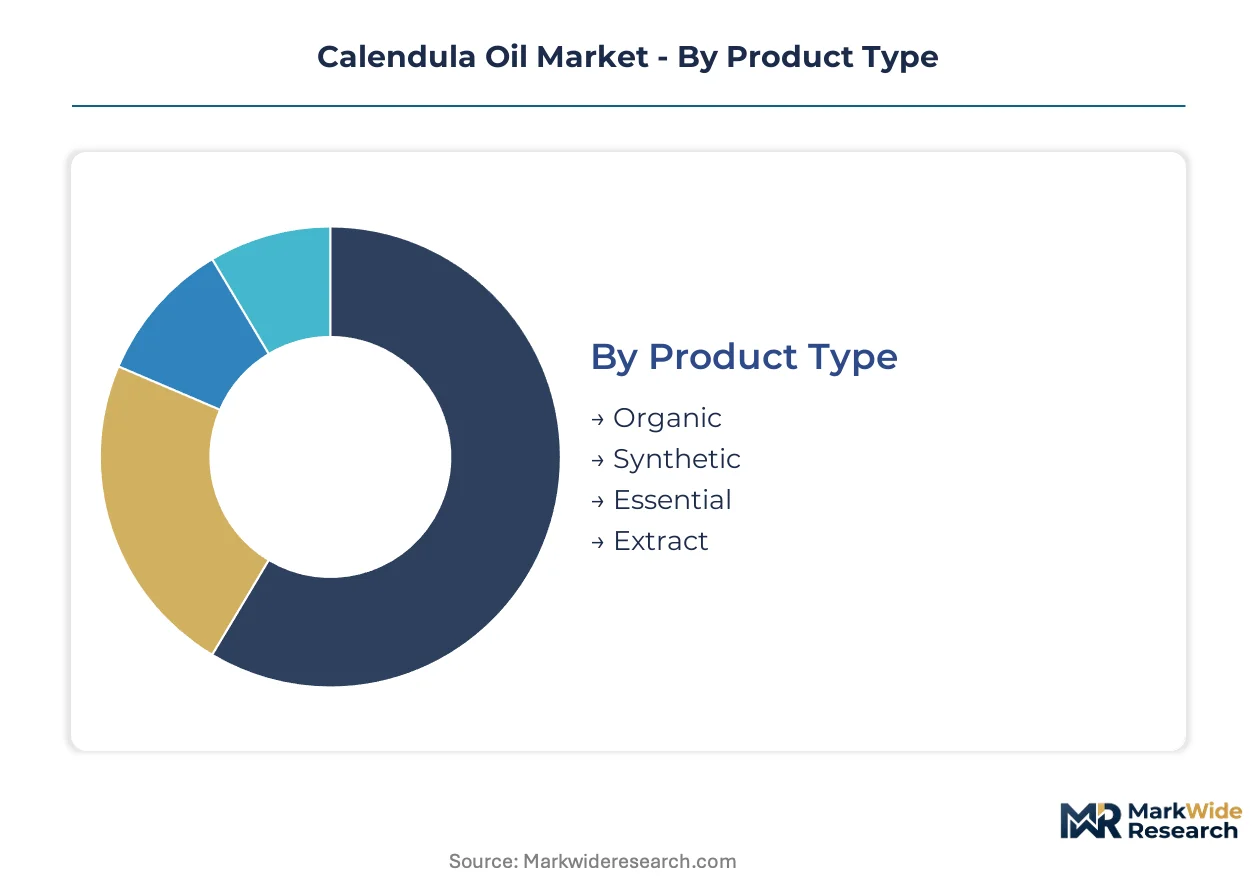
Channel configuration determines margin capture in calendula oil procurement. Pharmacy chains, direct-to-practitioner networks, and certified organic distributors each filter for distinct product specifications and documentation standards.
Product Type:
Organic and essential grades flow through pharmacy and specialty retail channels commanding premium shelf placement. Synthetic and extract variants serve cost-sensitive manufacturers through bulk industrial distributors.
- Organic:Cold-pressed from certified Calendula officinalis cultivation meeting EU Organic and USDA standards. German and French pharmacy chains absorb 40-60% feedstock premiums to maintain ISO 16128 natural origin claims on skincare packaging.
- Essential:Steam-distilled volatile fraction containing sesquiterpenes and monoterpenes for aromatherapy diffusion. Direct-to-practitioner channels in Switzerland and Austria bypass traditional distributor markups by sourcing from certified organic distillers.
- Synthetic:Laboratory-derived faradiol esters replicating natural triterpenoid profiles. South Asian cosmeceutical manufacturers substitute this grade when natural extract pricing exceeds formulation budgets.
- Extract:Standardized flavonoid concentrates produced via supercritical CO2 or ethanol extraction. Pharmaceutical applications in German hospital dermatology protocols require heavy metal documentation per EMA herbal medicinal product guidelines.
Organic dominates installed base. Extract is where expansion concentrates.
Application:
Cost tier stratification separates clinical-grade pharmaceutical demand from mass-market cosmetic volume.
- Cosmetics:Formulations leverage calendula oil for anti-inflammatory and skin-barrier repair claims. Clean-label manufacturers in France and Germany prioritize certified organic feedstock to secure pharmacy channel placement.
- Pharmaceuticals:Wound-healing and dermatitis treatment protocols require standardized triterpenoid content with batch-specific analytical certificates. EMA guidelines on herbal medicinal products drive documentation rigor for hospital procurement.
- Food Industry:Limited application as natural colorant and flavoring agent. Regulatory approval constraints in EU and North American markets restrict volume expansion.
- Aromatherapy:Essential-grade oil for diffusion and topical dilution. Swiss and Austrian supply houses source directly from biodynamic cultivation networks.
Cosmetics commands volume leadership. Pharmaceuticals shows steepest expansion trajectory.
End User:
Customer type dictates procurement scale and specification complexity across the value chain.
- Manufacturers:Cosmetics and pharmaceutical formulators purchasing feedstock in drum or tanker quantities. EU REACH registration requirements filter supplier bases toward certified organic processors.
- Retailers:Pharmacy chains and natural products stores requiring batch-specific documentation. French pharmacy networks now mandate heavy metal certificates for every calendula oil SKU.
- Distributors:Industrial chemical and botanical extract wholesalers serving mid-tier manufacturers. Margin compression from certification cost escalation pressures traditional trading operations.
- Consumers:Direct purchase of small-format therapeutic and cosmetic products. Online channels expand access to certified organic SKUs previously confined to specialty retail.
Manufacturers anchor procurement volume. Retailers concentrate margin capture.
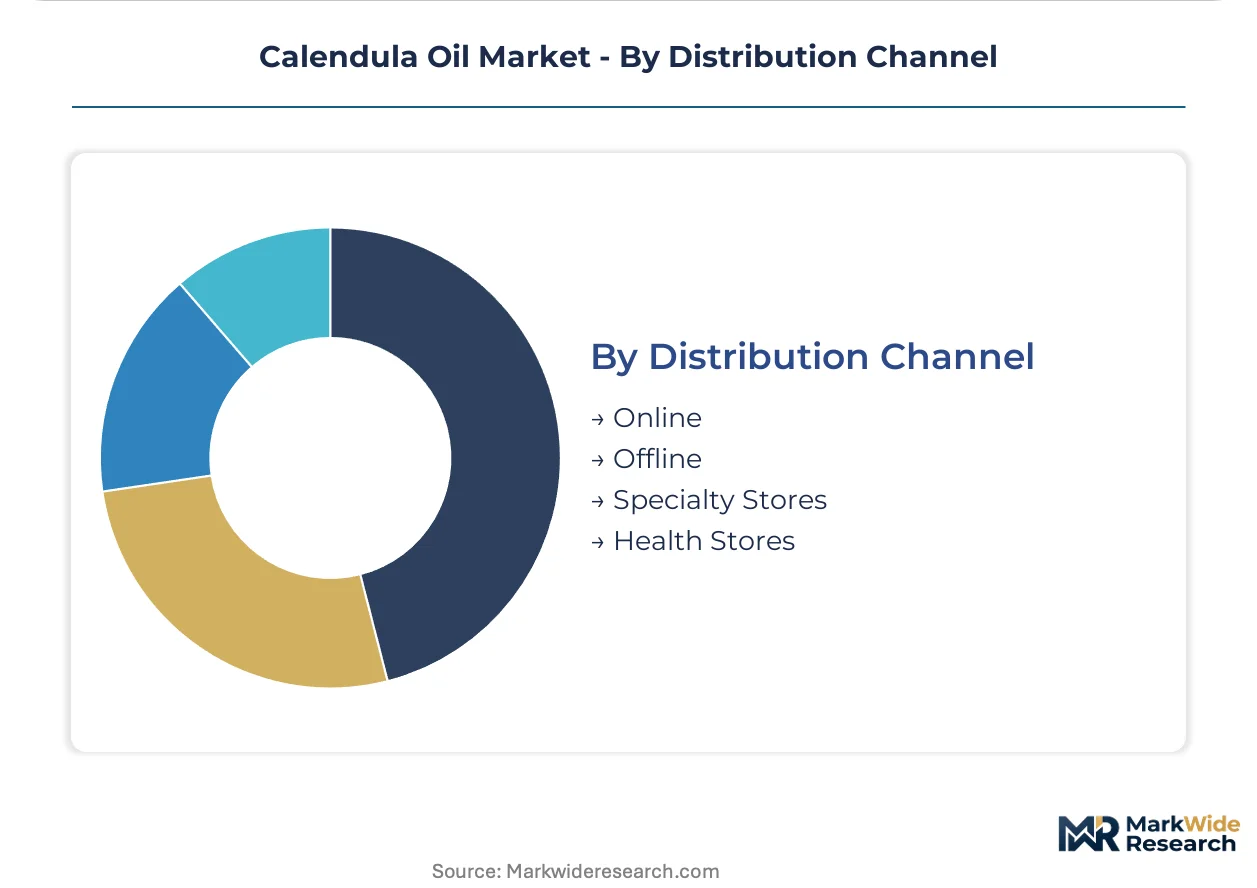
Distribution Channel:
Supply concentration varies by channel maturity and certification requirements.
- Online:E-commerce platforms and direct-to-consumer brand sites. German and French consumers purchase certified organic skincare through pharmacy-affiliated digital channels.
- Offline:Traditional wholesale and retail networks. Brick-and-mortar pharmacy chains maintain preference for suppliers with established biodynamic cultivation relationships.
- Specialty Stores:Natural products retailers and aromatherapy supply houses. Swiss and Austrian practitioners source essential-grade oil through these channels.
- Health Stores:Dedicated wellness and supplement retailers. USDA Organic and EU Organic certification claims drive product selection in North American and European markets.
Offline retains volume dominance. Online gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy chains and certified organic cosmetics manufacturers in Germany and France concentrate procurement power, while biodynamic cultivation networks in the Pacific Northwest and Central Europe secure premium channel placement through direct farm-to-formulator relationships.
Germany
Hospital-based dermatitis treatment programs in Bavaria and North Rhine-Westphalia drive pharmaceutical-grade demand with documented flavonoid requirements. EMA herbal medicinal product guidelines mandate batch-specific analytical certificates for wound-healing protocols. The Baden-Württemberg cosmetics cluster absorbs 40-60% feedstock premiums to maintain ISO 16128 natural origin claims.
France
French pharmacy chains now require heavy metal certificates for every calendula oil SKU, filtering supplier bases toward certified organic processors. ANSM oversight of botanical extract purity standards tightens testing protocols for cadmium and lead documentation. The Provence-Alpes-Côte d'Azur region anchors biodynamic cultivation networks supplying direct-to-practitioner aromatherapy channels.
United States
USDA Organic certification drives product selection in Pacific Northwest health stores and natural products retailers. FDA oversight of cosmetic ingredient labeling interacts with state-level organic standards to create dual-compliance burdens for cross-Atlantic exporters. Oregon and Washington farming clusters supply Mountain Rose Herbs and other certified organic distributors.
Switzerland
Swissmedic regulation of herbal medicinal products elevates documentation requirements for pharmacy channel placement. Swiss and Austrian practitioners source essential-grade oil directly from certified organic distillers, bypassing traditional distributor markups. The Basel-Zurich corridor concentrates aromatherapy supply houses serving German-speaking Central European markets.
India
AOS Products competes on volume scale, supplying refined calendula oil to mid-tier cosmetics manufacturers in South Asia. CDSCO oversight of botanical extract standards creates export eligibility filters for North American and European market access. Maharashtra and Gujarat processing facilities face analytical chemistry skill gaps in triterpenoid quantification and pesticide residue testing.
Calendula Oil Market Competitive Environment
Player mix skews toward certified organic specialists and volume-scale refiners, with biodynamic cultivation networks securing premium shelf placement against solvent-based processors facing margin compression from supercritical CO2 technology upgrades. Three archetypes dominate: biodynamic farm-to-formulator integrators, certified organic mid-tier suppliers, and volume-driven refiners serving cost-sensitive manufacturers. Competitive moves concentrate on backward integration into cultivation assets and pharmacopeial standardization investments to meet EMA and USP diverging specifications.
Among certified organic specialists, Mountain Rose Herbs and Weleda AG exemplify the biodynamic cultivation network archetype, while AOS Products occupies a position within the volume-scale refiner tier. These three companies represent the strategic spectrum from premium pharmacy channel placement to mid-tier cosmetics manufacturing supply, with each anchoring distinct competitive positioning based on certification depth and customer segment focus.
| Leading Market Players |
|---|
| Starwest Botanicals |
| Kiehl's Since 1851 |
| Mountain Rose Herbs |
| AOS Products |
| Telia Oils |
| Weleda AG |
| NOW Health Group |
| Aadhunik Ayurveda |
| Herb Pharm |
| Others |
Value Chain & Pricing Dynamics
EU REACH registration requirements for botanical extracts simultaneously gate supplier qualification and compress price differentiation between certified and uncertified tiers. This regulatory filter concentrates procurement power among organic-certified processors while marginalizing regional producers unable to absorb compliance costs.
Pricing Analysis
Cost-plus contracts with organic Calendula officinalis flower head indexation dominate procurement between German cosmetics manufacturers and Pacific Northwest cultivation networks. Price differentiation rests on ISO 16128 certification depth and batch-specific heavy metal documentation tiers. Cost compression in synthetic faradiol ester substitutes is intensifying because South Asian cosmeceutical manufacturers prioritize formulation budget adherence over natural origin claims. Mid-tier cosmetics formulators exhibit highest price sensitivity, while German pharmacy chains absorb premium feedstock costs with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of certified organic flower heads prevails among German and French pharmacy chains facing weather-dependent yield volatility in Ukraine and Poland growing regions. Geographic supply concentrates in India, Germany, and the Pacific Northwest United States. Raw material dependencies include organic Calendula officinalis cultivation, supercritical CO2 extraction equipment, and chromatography-grade solvents for triterpenoid quantification. Single-source vulnerability runs through Ukrainian organic flower head supplies exposed to climate volatility. Distribution feeds from biodynamic cultivation networks through direct farm-to-formulator relationships into pharmacy and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification interoperability between USDA Organic and EU Organic standards is creating platform-economics dynamics where multi-certified suppliers capture disproportionate margin pools. This ecosystem shift rewards backward integration into controlled cultivation assets.
For Market Incumbents: Secure biodynamic cultivation network exclusivity in Central European and Pacific Northwest farming clusters to defend against synthetic faradiol ester substitution in cost-sensitive cosmeceutical segments. Deepen pharmacopeial standardization investments to meet diverging European Pharmacopoeia and United States Pharmacopeia specifications, locking in hospital procurement relationships through batch-specific analytical certificate capabilities. For New Entrants and Emerging Players: Direct-to-practitioner aromatherapy supply in Swiss and Austrian markets represents an under-served service layer where incumbents rely on traditional distributor markups. Target essential-grade oil procurement for certified organic distillers, leveraging bypass channel economics. Pursue EU Green Deal bioeconomy incentive qualification through circular supercritical CO2 extraction technology adoption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure, favoring scaled processors over batch solvent operators. Long-term viability centers on acquisition targets with captive organic cultivation assets and established pharmacy channel relationships. Watch for ICP-MS analytical capability deployment rates as the inflection signal indicating supplier tier consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodynamic Cultivation | Captures ISO 16128 certification control and secures pharmacy channel placement against feedstock volatility. |
| Supercritical CO2 Extraction Scale-Up | Qualifies for EU Green Deal procurement preferences while displacing hexane-based solvent competitors. |
| Pharmacopeial Standardization Investment | Enables dual European Pharmacopoeia and United States Pharmacopeia compliance for hospital dermatology protocols. |
| Direct-to-Practitioner Channel Development | Bypasses traditional distributor markups in Swiss and Austrian aromatherapy supply networks. |
| ICP-MS Analytical Capability Deployment | Satisfies ECHA heavy metal documentation requirements for French pharmacy chain SKU approval. |
Study Parameters
Initial hypotheses were tested against primary input from cosmetics formulators, pharmaceutical procurement managers, organic cultivation network operators, and botanical extract distributors, then refined through secondary validation. Primary interviews captured procurement scale, certification cost structures, and channel placement dynamics. Secondary sources included EMA herbal medicinal product guideline documents, EU REACH registration databases, USDA Organic certification records, and pharmacopeial monograph specifications. Bottom-up cultivation yield models and top-down cosmetics industry demand estimates were triangulated to anchor volume projections.
Variance decomposition across product type, application, end user, and distribution channel dimensions structured the analytical framework. CAGRs were derived from segmented demand elasticity modeling and input cost trajectory assumptions. Forecast inputs incorporated organic flower head yield volatility patterns, supercritical CO2 extraction capacity buildout timelines, and pharmacy chain certification requirement evolution.
Forecasts assume regulatory continuity in EU REACH, EMA herbal medicinal product oversight, and USDA Organic equivalence arrangements; material policy shifts would require re-modeling. Specific risks include pharmacopeial monograph divergence acceleration, synthetic substitute pricing breakthroughs, and climate-induced organic cultivation yield collapse. Revision becomes warranted when ICP-MS analytical certificate adoption rates among French pharmacy chains cross threshold penetration levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Industrial Sugar Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Durian Powder Market
Ingredients
Corn Peptide Market
Ingredients
Lipids Market
Ingredients
Rose Hips Extract Market
Ingredients
Torula Yeast Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Europe Amino Acid Market
Ingredients
Farnesene Market
Ingredients
Dry Malt Products Market
Ingredients
Food Amino Acids Market
Ingredients
Omega Ingredients Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Pepsin Market