
 Europe Fermented Ingredients Market | 2026-2036
Europe Fermented Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fermented Ingredients Market Foresight
Modular ingredient bundling is expanding as buyers seek customizable starter cultures and enzyme blends rather than single-species formulations. Chr. Hansen leverages its strain collection to dominate specialty dairy cultures across Nordic and Central European plants. DSM-Firmenich sustains broad portfolio coverage spanning enzymes, probiotics, and nutritional lipids for multiple end users. Lesaffre anchors European yeast supply through vertically integrated fermentation capacity from raw material sourcing to finished dry products.
Fermented ingredients comprise metabolically active or inactivated biomass, organic acids, enzymes, and flavor compounds produced through controlled microbial cultivation in bioreactors or solid-state systems, typically operating at precise temperature, pH, and dissolved oxygen parameters to ensure batch consistency and regulatory-grade purity. These inputs serve as leavening agents, flavor modulators, shelf-life extenders, and functional health ingredients across formulated consumer goods. Yeast occupies the largest volume position in the European market, reflecting entrenched demand from industrial bakeries and alcoholic beverage producers, while probiotics generates the fastest value growth as nutraceutical companies and dairy processors fortify positioned health claims. Enzyme applications in plant-based dairy alternatives and snack texturization represent emerging margin pools where technical differentiation commands pricing premiums.
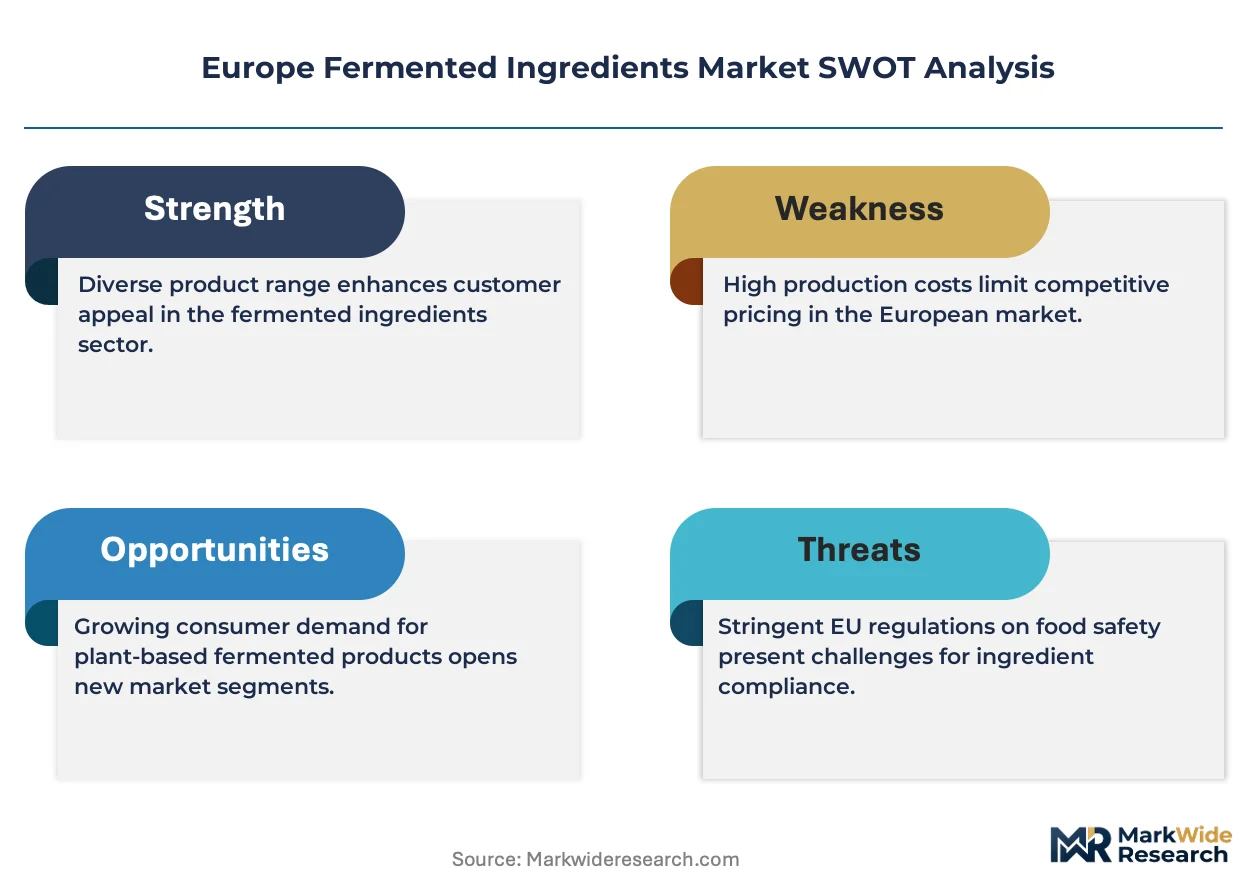
The European Food Safety Authority screens novel microbial strains through qualified presumption of safety assessments, constraining speed-to-market for new probiotic entrants while elevating barriers against unvalidated suppliers. REACH and the EU Green Deal impose decarbonization and chemical disclosure obligations on fermentation feedstock sourcing and downstream processing, redirecting capital toward renewable energy-integrated biorefineries. Stakeholders must monitor evolving strain patent landscapes and carbon border adjustment mechanisms to secure compliant supply positions.
Market Dynamics
Modular starter culture bundling is reshaping procurement relationships across European dairy and bakery value chains. Buyers now demand customizable enzyme-yeast-probiotic combinations rather than single-species inputs. This shift compresses supplier margins while elevating technical service requirements.
Growth Catalysts
- EU Green Deal decarbonization mandates:Industrial biorefineries face binding emissions reduction targets. Fermentation facilities with renewable energy integration capture preferential sourcing contracts from multinational food manufacturers.
- Clean-label bakery expansion:Industrial bakeries across Germany and France replace chemical preservatives with cultured wheat and fermented flour. Extended shelf-life claims without E-number additives drive volume pull.
- Precision fermentation scale-up:Novel lipid and protein platforms reach commercial viability. Biotech-derived dairy alternatives and egg replacers attract capital from ingredient distributors seeking portfolio diversification.
Market Restraints
- Molasses and sugar beet feedstock volatility:Yeast production depends on concentrated sucrose streams. Agricultural commodity price swings transmit directly to fermentation input costs without hedging mechanisms for mid-scale producers.
- Strain patent thickets:Probiotic intellectual property concentrates among legacy culture collections. New entrants face licensing barriers or costly freedom-to-operate analyses for human microbiome-targeted formulations.
- EFSA qualified presumption of safety timelines:Novel microbial strain approvals average 18-24 months. Accelerated market entry for next-generation probiotics remains structurally constrained regardless of clinical evidence quality.
Strategic Opportunities
- Eastern European manufacturing footprint gaps:Poland and Romania lack domestic starter culture production at scale. Joint venture structures with local dairy cooperatives unlock captive supply relationships for pan-European ingredient distributors.
- F-Gas Regulation refrigerant transition:Cold-chain fermentation facilities must replace hydrofluorocarbon cooling systems. Engineering partnerships for ammonia or CO2-based refrigeration create service revenue layers beyond ingredient sales.
- Plant-based dairy enzyme suites:Lipase and protease blends tailored to oat and pea protein bases command technical premiums. Specialty enzyme houses capture margin pools unavailable in commodity bakery applications.
Industry Challenges
- Industrial microbiology talent scarcity:Strain development and bioprocess engineering skills concentrate in Danish and Dutch academic clusters. Recruitment for production-scale facilities in peripheral regions requires compensation premiums or remote R&D structures.
- Legacy ERP integration with batch traceability systems:Fermentation record-keeping for REACH compliance conflicts with existing manufacturing execution software. Custom middleware development extends digital transformation timelines.
- Carbon border adjustment mechanism documentation:Imported fermentation feedstocks require embedded emissions certification. Supplier audit burdens multiply for traders sourcing Ukrainian or Brazilian sugar derivatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fermented Ingredients Market |
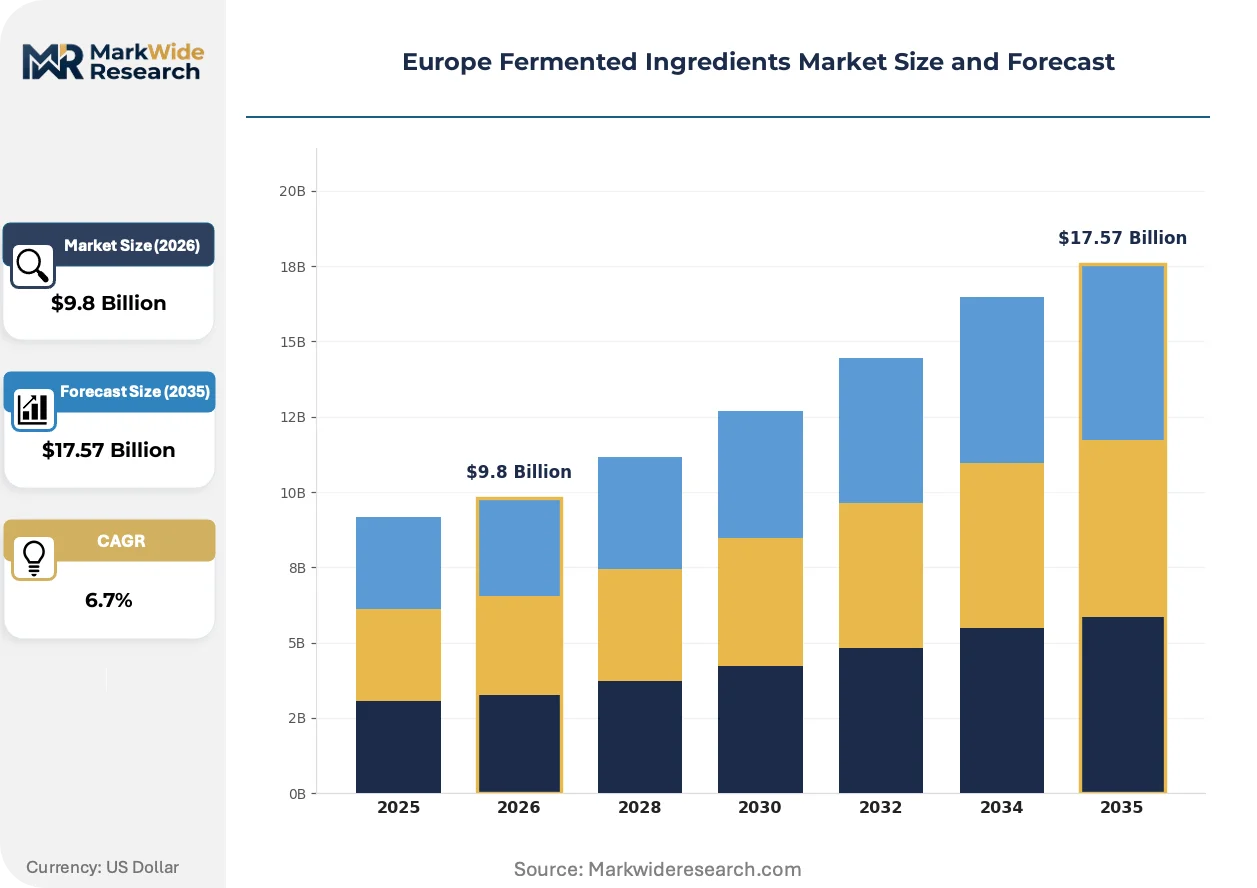
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Lactic Acid Bacteria, Enzymes, Probiotics Application: Beverages, Bakery Products, Dairy Products, Snacks End User: Food Industry, Beverage Manufacturers, Nutraceutical Companies, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Döhler GmbH, DuPont, BASF SE, DSM-Firmenich, Chr. Hansen, Lesaffre, Corbion, Evonik, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fermented Ingredients Market Shifts & Advancements
Bioprocess intensification and regulatory disclosure requirements are simultaneously compressing production economics and elevating transparency standards. Technical differentiation now hinges on energy efficiency and strain performance rather than commodity scale alone.
Continuous fermentation systems with real-time metabolite monitoring are converging with machine learning process control. Specialty enzyme manufacturers in the Netherlands adopt these platforms to reduce batch-to-batch variability. The technology is converging with pharmaceutical-grade production discipline, enabling food-grade manufacturers to serve dual-use nutraceutical contracts with minimal capital reconfiguration.
REACH chemical registration obligations now extend to fermentation-derived metabolites and processing aids. ECHA substance evaluation workflows capture novel organic acids and flavor compounds previously exempt from full dossier requirements. Small and mid-scale producers in Southern Europe face disproportionate compliance burdens, accelerating consolidation toward integrated analytical laboratories.
Direct procurement relationships between dairy processors and culture suppliers are displacing traditional distributor intermediaries. Large German and French cooperatives negotiate multi-year strain exclusivity agreements with guaranteed volume commitments. This pattern concentrates most visibly in Nordic organic dairy chains, where identity preservation requirements favor transparent supply structures over opaque trading networks.
Europe Fermented Ingredients Market Segmentation
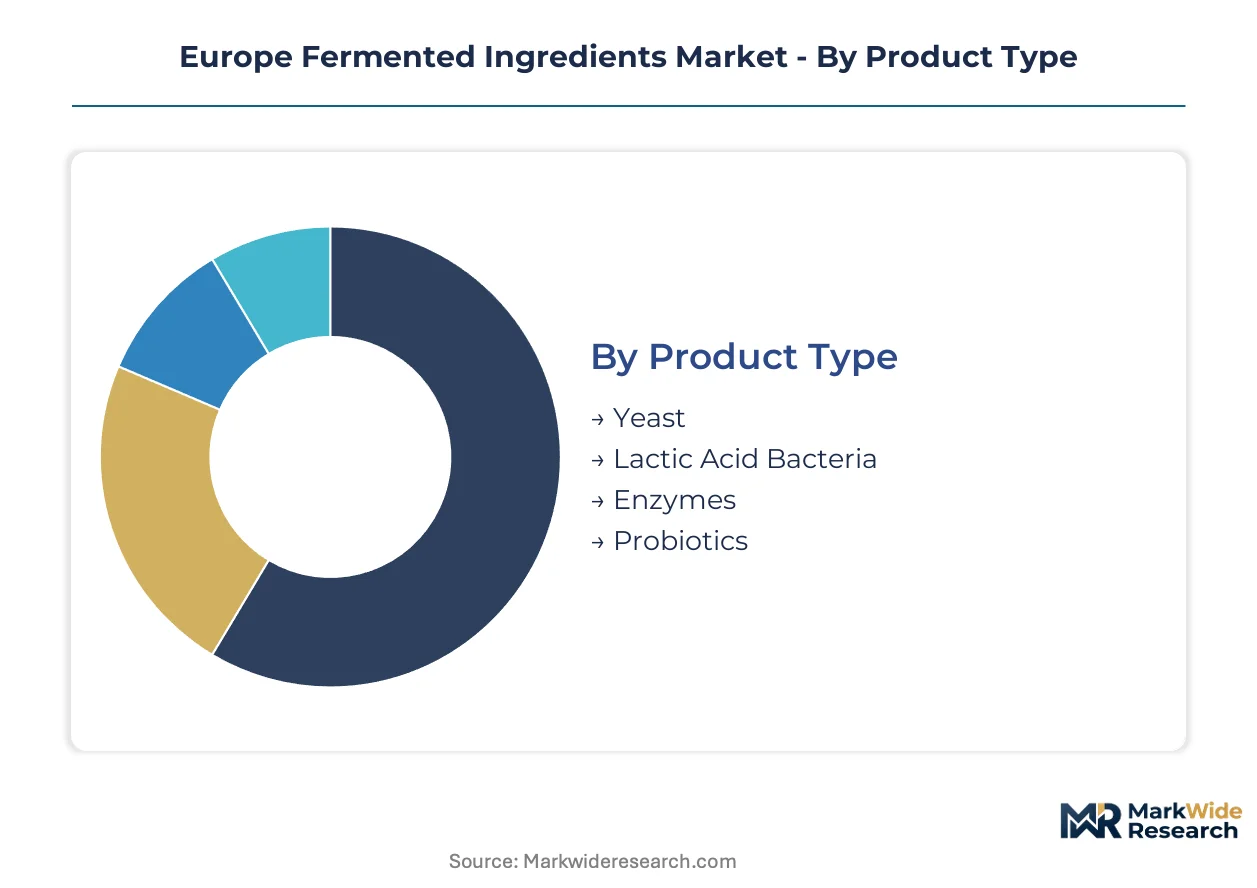
Segmentation in the European fermented ingredients market reveals how procurement power concentrates around industrial scale buyers while specialty applications fragment across niche channels. Understanding these divides exposes where margin pools shift and where supplier consolidation will accelerate.
Product Type:
Supply concentration clusters heavily around yeast and enzyme platforms, where capital-intensive fermentation infrastructure creates natural oligopoly structures.
- Yeast:Active and inactive dried biomass dominates industrial bakery and alcoholic beverage formulations across Germany and France. German malting cooperatives and French industrial bakeries anchor continental demand through multi-year supply contracts with vertically integrated producers.
- Lactic Acid Bacteria:Starter cultures for dairy fermentation command technical premiums through strain-specific performance guarantees. Danish and Dutch culture houses concentrate R&D capacity, leaving Southern European processors dependent on imported live cultures.
- Enzymes:Protease, lipase, and amylase blends serve texturization and shelf-life extension in plant-based dairy alternatives.
- Probiotics:Live microbial strains for health-positioned foods and supplements face EFSA qualified presumption of safety bottlenecks.
Today's leader: Yeast. Tomorrow's challenger: Probiotics.
Application:
Volume distribution tracks the maturity of industrial food processing clusters, with beverages and bakery commanding raw tonnage while dairy and snacks drive value-added formulation.
- Beverages:Alcoholic fermentation consumes the largest yeast volumes, with Czech and German brewing traditions sustaining concentrated demand. Craft beer revival across Poland and Spain creates spot-market opportunities for specialty strain suppliers.
- Bakery Products:Industrial pan bread and frozen dough applications standardize on commodity baker's yeast. French and Italian artisan segments increasingly specify long-fermentation cultures for clean-label positioning.
- Dairy Products:Yogurt and cheese fermentation requires thermophilic and mesophilic starter combinations tailored to regional taste profiles.
- Snacks:Fermented flavor bases and texturizing enzymes penetrate extruded and baked snack categories.
Beverages and bakery together absorb the majority of commodity fermentation output, while dairy applications generate the steepest expansion trajectory for premium cultures.
End User:
Procurement sophistication varies sharply across buyer categories, with multinational food manufacturers demanding technical service integration that mid-scale nutraceutical firms cannot replicate.
- Food Industry:Industrial bakeries, dairy cooperatives, and prepared meal manufacturers consolidate purchasing through pan-European ingredient distributors. German and French buyers lead in specifying custom starter culture blends.
- Beverage Manufacturers:Brewing and winemaking operations range from multinational groups with captive yeast propagation to regional producers sourcing active dry preparations.
- Nutraceutical Companies:Probiotic fortification demands clinical substantiation and strain documentation beyond standard food-grade requirements.
- Cosmetics:Fermented extracts for skincare represent an emerging specification channel with distinct purity and preservation standards.
Food and beverage manufacturers currently dominate volume procurement, though nutraceutical buyers are gaining share fastest through premium-priced strain applications.
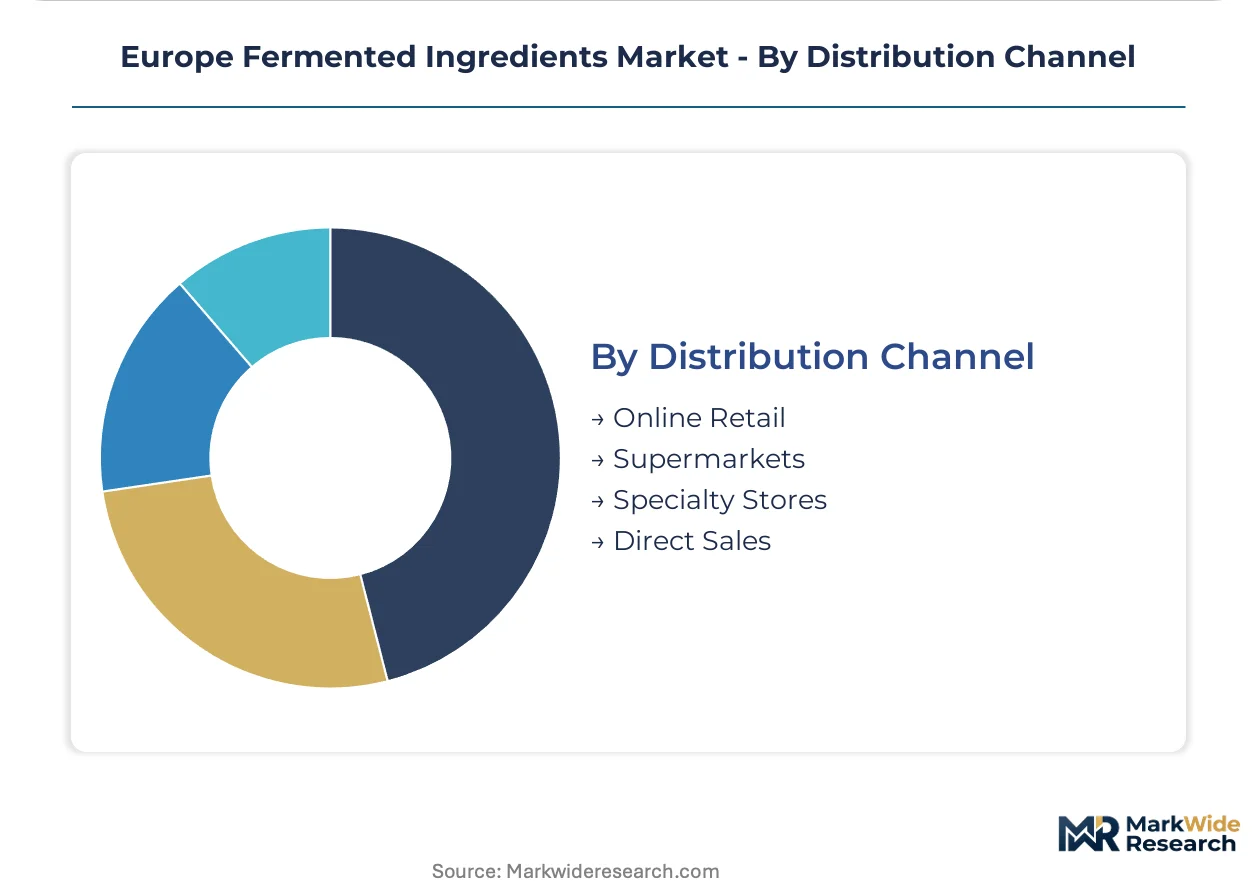
Distribution Channel:
Channel structure reflects the tension between technical service requirements and cost minimization, with direct relationships displacing intermediaries for high-volume accounts.
- Direct Sales:Large dairy cooperatives and multinational food groups negotiate multi-year exclusivity agreements with culture suppliers. This channel captures the majority of probiotic and specialty enzyme value.
- Online Retail:E-commerce platforms serve small-scale artisan producers and research institutions requiring limited quantities of specialized strains.
- Supermarkets:Mass-market retail channels distribute consumer-facing probiotic supplements and home fermentation kits.
- Specialty Stores:Professional ingredient suppliers and regional distributors maintain inventory for mid-scale processors lacking direct supplier relationships.
Direct sales anchor supplier profitability today, while online retail is climbing the fastest as digital procurement penetrates smaller account tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial fermentation in Europe traces its modern lineage to Danish dairy science institutions and German brewing academies that pioneered pure culture isolation in the late nineteenth century. These foundational research clusters established the continent's dominance in starter culture development and yeast propagation. Today, regional demand patterns reflect this heritage while adapting to decarbonization mandates and clean-label procurement pressures.
Germany
Industrial bakeries and malting cooperatives anchor continental yeast consumption through multi-year supply contracts. The EU Green Deal's binding emissions targets are redirecting capital toward renewable energy-integrated biorefineries in North Rhine-Westphalia. Düsseldorf and Cologne host concentrated fermentation capacity serving pan-European distribution networks.
France
Artisan bread traditions and industrial dairy processing sustain dual demand tracks for long-fermentation cultures and thermophilic starter combinations. REACH chemical registration obligations now extend to fermentation-derived metabolites, elevating compliance burdens for smaller producers. The Auvergne-Rhône-Alpes cluster concentrates specialty enzyme manufacturing for plant-based dairy alternatives.
Netherlands
Precision fermentation scale-up attracts venture capital toward novel lipid and protein platforms in the Randstad corridor. ECHA substance evaluation workflows capture organic acids previously exempt from full dossier requirements. Wageningen University anchors academic-industrial partnerships in bioprocess intensification.
Denmark
Danish culture houses concentrate R&D capacity for probiotic strain development and dairy fermentation science. EFSA qualified presumption of safety assessments constrain speed-to-market for novel microbial entrants. Copenhagen's industrial microbiology talent pool supplies technical expertise to Nordic and Central European plants.
Poland
Craft beer revival and dairy cooperative expansion create spot-market opportunities for specialty strain suppliers. Domestic starter culture production at scale remains underdeveloped, exposing processors to imported supply dependencies. Warsaw and Łódź are emerging as distribution hubs for Eastern European fermentation inputs.
Europe Fermented Ingredients Market Competitive Landscape
The competitive structure tilts toward vertically integrated multinational suppliers with captive strain collections and renewable energy-integrated production assets. Danish and Dutch heritage companies dominate specialty culture development, while French and German players anchor commodity yeast supply through backward integration into agricultural feedstock sourcing. Two strategic archetypes prevail: diversified life-science conglomerates spanning enzymes, probiotics, and nutritional lipids; and focused fermentation specialists concentrating on single-platform excellence. Capacity expansion and direct procurement relationship-building with large dairy cooperatives represent the dominant competitive moves reshaping channel structures.
Among heritage European specialists, Chr. Hansen, Lesaffre, and DSM-Firmenich exemplify contrasting strategic positions within the supplier base. Chr. Hansen represents the focused culture collection archetype, leveraging decades of strain banking to serve dairy fermentation requirements. Lesaffre occupies a position emphasizing vertical control from agricultural raw materials through finished dry yeast products. DSM-Firmenich sits within the diversified life-science tier, spanning multiple fermentation-derived ingredient categories beyond single-platform dependence. These three anchors illustrate how procurement power concentrates around technical service integration and renewable energy compliance rather than commodity scale alone.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Döhler GmbH |
| DuPont |
| BASF SE |
| DSM-Firmenich |
| Chr. Hansen |
| Lesaffre |
| Corbion |
| Evonik |
| Others |
Supply & Pricing Matrix
Strain certification grade bifurcation separates premium probiotic cultures from commodity baker's yeast across European procurement channels, with EFSA-qualified strains commanding technical service premiums while standard yeast flows through volume-contracted distributor networks. This tier divergence concentrates margin capture among Danish and Dutch culture houses while compressing returns for undifferentiated biomass suppliers dependent on molasses feedstock economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs European fermented ingredient transactions, with EFSA-qualified probiotic strains and specialty enzymes occupying the premium tier, commodity baker's yeast and standard dairy cultures anchoring the mid-market, and bulk inactive biomass serving economy formulations. Price differentiation hinges on strain documentation depth and renewable energy integration certification, with EU Green Deal compliance emerging as a threshold qualifier for multinational food manufacturer contracts. Pricing pressure stems from molasses and sugar beet feedstock volatility transmitting directly to yeast production costs without effective hedging instruments for mid-scale producers. Industrial bakeries exhibit the highest price sensitivity due to standardized product specifications and limited switching costs, while nutraceutical companies tolerate premium positioning for clinically substantiated probiotic strains.
Supply Chain Analysis
Dual-sourcing requirements now mandate that large German and French dairy cooperatives qualify at least two culture suppliers for each starter blend specification, reducing single-source dependency while elevating supplier audit burdens. Geographic supply concentration clusters in Germany, Denmark, and the Netherlands, where academic-industrial fermentation clusters anchor strain development and bioprocess engineering capacity. Raw material dependencies center on Ukrainian and Brazilian sugar derivatives for yeast propagation, Danish and Dutch culture collections for proprietary strains, and renewable energy-integrated biorefineries for compliance-grade production. Supply chain risk crystallizes around carbon border adjustment mechanism documentation requirements, where embedded emissions certification for imported feedstocks multiplies supplier audit complexity. Distribution runs through direct sales relationships for high-volume dairy and bakery accounts, with specialty stores and online retail serving fragmented artisan and research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's fermented ingredients market functions as a stable compounder, with EU Green Deal decarbonization mandates and clean-label procurement trends generating durable demand growth for compliant suppliers across the projection horizon.
For Market Incumbents: Hedge against feedstock volatility through backward integration into agricultural raw material sourcing or long-term offtake agreements with beet sugar cooperatives in France and Germany. Prioritize renewable energy certification for biorefinery assets to capture preferential sourcing contracts from multinational food manufacturers facing binding emissions targets. Defensive consolidation of analytical laboratory capabilities will accelerate as REACH disclosure obligations extend to fermentation-derived metabolites, disproportionately burdening smaller Southern European competitors lacking in-house compliance infrastructure. For New Entrants and Emerging Players: E-commerce platforms serving artisan dairy processors and craft brewers represent the most penetrable channel for specialty strain suppliers lacking direct sales scale. Target Poland and Romania, where domestic starter culture production remains underdeveloped and dairy cooperative expansion creates captive supply opportunities through joint venture structures with local processors. Precision fermentation-derived dairy alternatives and egg replacers offer white-space positioning, with enzyme suites tailored to oat and pea protein bases commanding technical premiums unavailable in commodity applications. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance burdens and carbon border documentation requirements exceed the analytical capabilities of mid-scale Southern European producers. The market supports long-term viability for vertically integrated specialists with captive strain collections and renewable energy-integrated production assets, particularly those serving dual-use nutraceutical and food-grade contracts. Watch for inflection signals in EFSA qualified presumption of safety approval timelines, where acceleration or further delay would materially alter competitive positioning for next-generation probiotic entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Biorefinery Integration | EU Green Deal compliance secures preferential contracts from German and French food manufacturers. |
| Precision Fermentation Scale-Up | Novel lipid and protein platforms reach commercial viability for plant-based dairy alternatives. |
| Direct Procurement Relationship Building | Multi-year exclusivity agreements with large dairy cooperatives displace traditional distributor intermediaries. |
| EFSA Strain Qualification Investment | Regulatory-grade documentation unlocks premium positioning in health-positioned food formulations. |
| Eastern European Joint Venture Formation | Polish and Romanian dairy cooperative partnerships establish captive supply positions in underpenetrated markets. |
Research Methodology
Multiple input streams — executive interviews with fermentation technology directors, procurement leads at German and French dairy cooperatives, regulatory affairs specialists navigating EFSA and ECHA workflows, and technical R&D heads at enzyme manufacturers — were reconciled against secondary validation from EU customs trade data, EFSA qualified presumption of safety submission records, SEC filings of listed ingredient suppliers, and Cefic chemical industry reports. Bottom-up volume modeling across yeast, enzyme, and probiotic product categories was cross-checked against top-down expenditure estimates from food and beverage manufacturer procurement disclosures.
Historical capacity utilization and pricing patterns were cross-referenced against panel input from bioprocess engineering consultants and strain development specialists to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user sophistication tier, and distribution channel structure, with particular attention to renewable energy integration status as an emerging procurement qualifier. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and feedstock cost trajectory assumptions, incorporating precision fermentation technology maturation curves and carbon border adjustment mechanism implementation schedules as industry-specific forecast inputs.
The model assumes a particular technology adoption path for continuous fermentation systems with real-time metabolite monitoring; alternative pathways for batch-based traditional bioprocessing would alter the outlook for capital efficiency and batch consistency benchmarks. Deviation in EFSA approval timelines or EU Green Deal enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Cholesterol API Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Europe Pea Starch Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Feed Premix Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Self-Rising Flour Market
Ingredients
Omega 9 Market