
 North America Dairy Protein Ingredients Market | 2026-2036
North America Dairy Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Protein Ingredients Market Analytics
Grass-fed and organic certification tiers is reorganizing procurement priorities across the North America dairy protein landscape. Glanbia leverages its Irish-American supply architecture to secure year-round grass-fed whey streams. Hilmar Cheese Company anchors California's Central Valley with integrated cheese-and-ingredient production. Leprino Foods dominates mozzarella-derived whey streams, locking in captive protein supplies from its pizza-cheese scale.
North America dairy protein ingredients encompass fractionated milk proteins—whey isolates exceeding 90% protein by dry weight, casein micelles, and hydrolyzed peptides produced via enzymatic or acid precipitation—serving as functional nutrition substrates across food, beverage, and supplement matrices. Whey protein concentrates and isolates lead volume due to superior leucine bioavailability and rapid gastric emptying, while hydrolyzed variants command premium positioning in medical and infant nutrition where allergen reduction matters. Casein protein sustains slower amino acid release profiles that sports nutrition and clinical weight-management formulators exploit for overnight recovery applications.
FDA nutrition labeling standards and USDA organic certification govern protein quality claims and clean-label positioning across the United States, while Health Canada and the Canadian Food Inspection Agency enforce parallel compositional rules that cross-border suppliers must harmonize. The FDA's evolving stance on protein digestibility-corrected amino acid scores directly determines which products qualify for "excellent source" declarations. Stakeholders must monitor pending GRAS notifications for novel fractionation methods and assess how cooperative consolidation in the upper Midwest reshapes raw milk contracting terms.
Market Dynamics
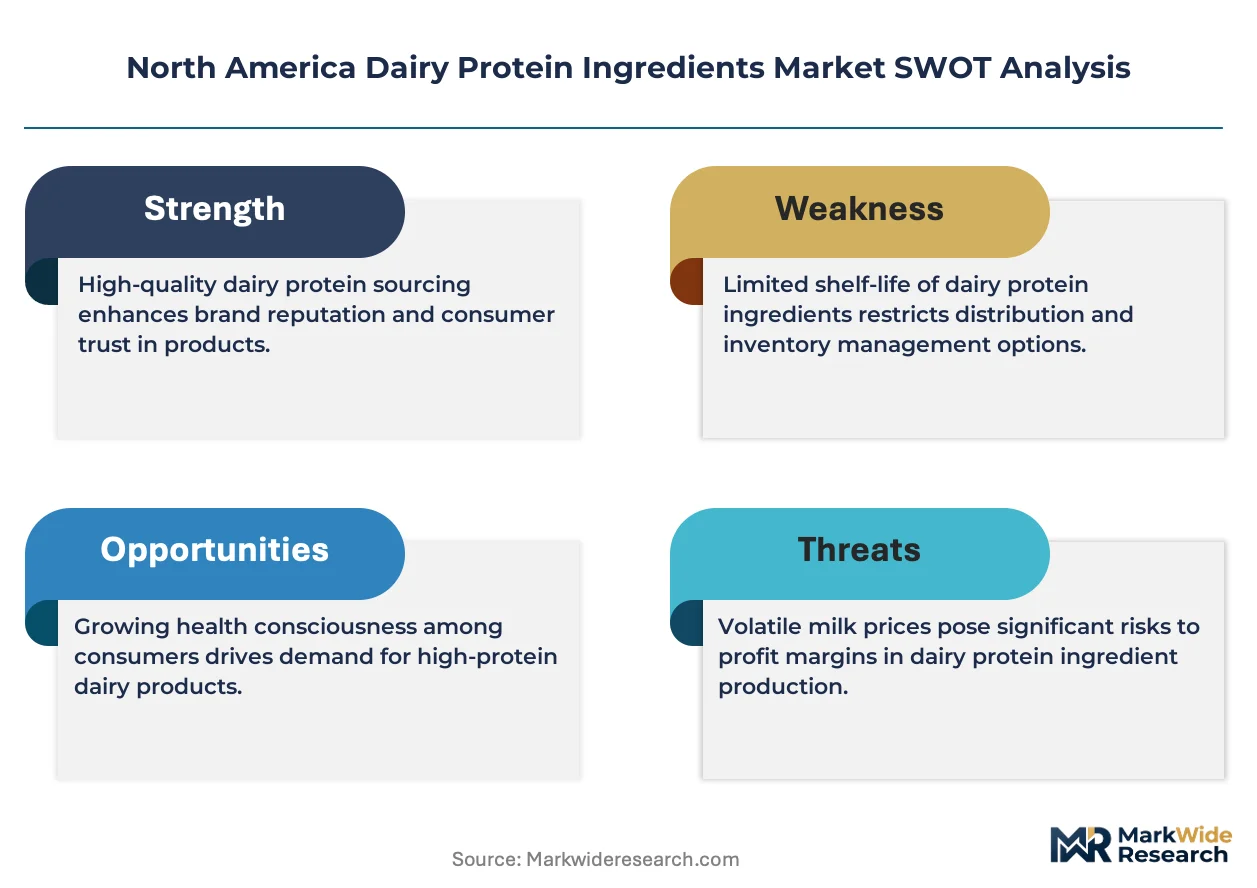
FDA's updated protein quality labeling standards are compressing formulation choices across the North American dairy protein landscape, forcing manufacturers to validate PDCAAS scores before claiming "excellent source" status on packaging.
Growth Catalysts
- Sports nutrition absorption:Athletes and fitness consumers prioritize clean-label recovery products with rapid gastric emptying profiles, pulling whey protein isolates into premium positioning.
- USDA organic certification:Grass-fed and organic tiers reorganize procurement priorities, with cooperative networks in Wisconsin and California locking in certified fluid milk streams.
- Cheese-whey integration:Pizza-cheese scale operations generate captive protein supplies, securing dedicated whey streams without spot-market exposure.
Market Restraints
- Fluid milk input volatility:Raw milk contracting terms fluctuate with cooperative consolidation in the upper Midwest dairy belt, squeezing margin predictability for fractionators.
- GRAS notification backlog:Pending FDA determinations on novel enzymatic fractionation methods delay product launches and freeze R&D pipelines.
- Plant protein substitution:Pea and rice protein isolates capture clean-label positioning in mass-market applications, pressuring dairy protein share in non-performance segments.
Strategic Opportunities
- Canadian cross-border harmonization:Health Canada and CFIA compositional rules create arbitrage potential for US suppliers with dual-certified production lines.
- Medical nutrition white space:Hydrolyzed peptides with reduced allergen profiles penetrate clinical weight-management and infant nutrition where amino acid release precision matters.
- Direct-to-practitioner channels:Sports dietitians and clinical nutritionists bypass traditional distribution, creating pull-through demand for validated protein quality claims.
Industry Challenges
- Fractionation talent scarcity:Enzymatic precipitation and membrane separation expertise concentrates in legacy dairy processing regions, limiting expansion into emerging production clusters.
- Dual-certification capex burden:Simultaneous organic and grass-fed infrastructure requires parallel cold-chain investments that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Protein Ingredients Market |
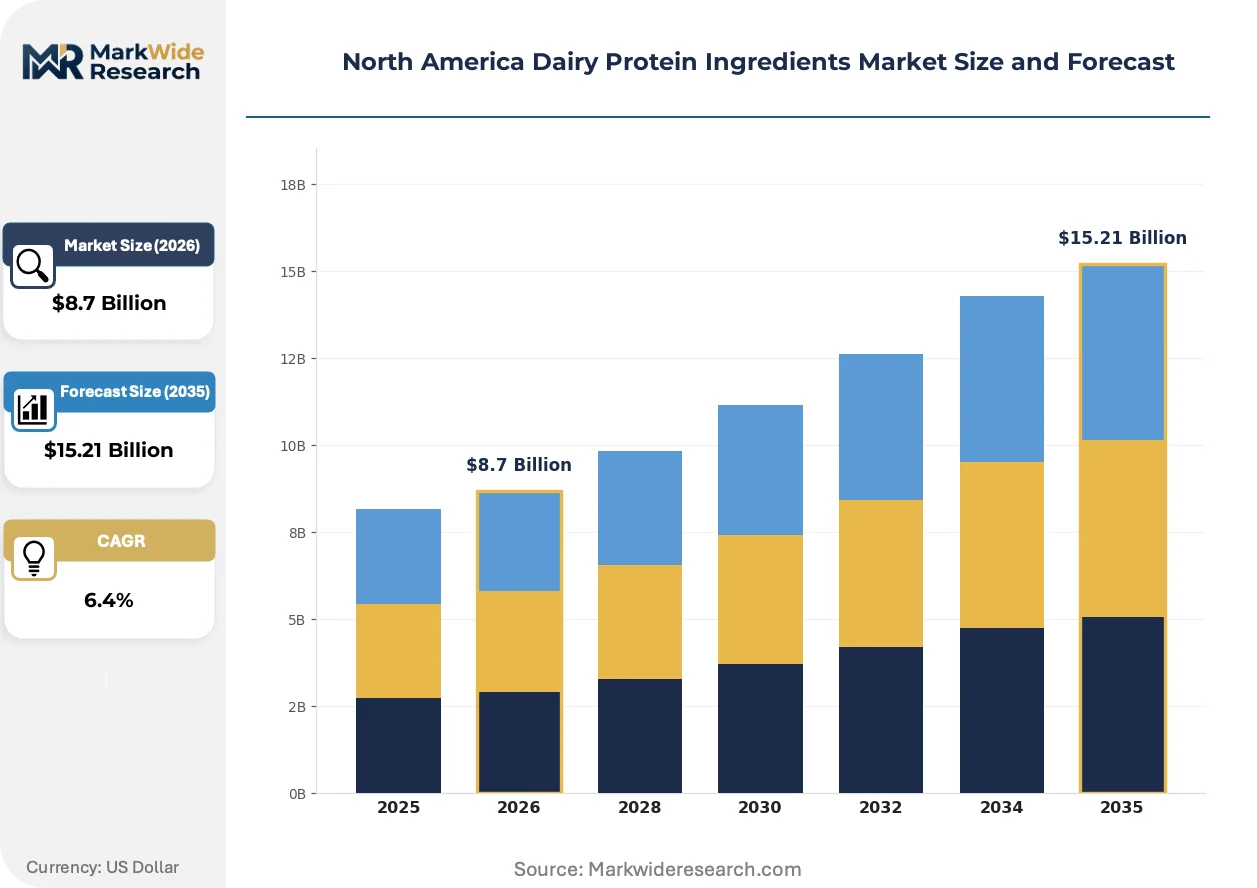
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Hydrolyzed Protein Application: Sports Nutrition, Dietary Supplements, Functional Foods, Bakery Products End User: Food Manufacturers, Beverage Companies, Nutraceutical Firms, Personal Care Brands Delivery Mode: Powder, Liquid, Ready-to-Drink, Tablets |
| Companies Covered | Dairy Farmers of America, Glanbia, Fonterra Co-operative Group, Saputo, Arla Foods Ingredients Group, Hilmar Cheese Company, AMCO Proteins, Leprino Foods, Darigold, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Protein Ingredients Market Evolving Landscape
Membrane filtration and enzymatic engineering are fragmenting traditional whey processing economics, creating divergent cost structures between commodity concentrates and precision isolates.
Cross-flow microfiltration combined with ion-exchange chromatography is bifurcating the whey protein landscape. Sports nutrition formulators adopt 90%+ isolate grades for leucine-bioavailability claims, while medical nutrition buyers demand hydrolyzed fractions with documented digestibility curves. This technical split compresses mid-tier concentrate margins and rewards capital-intensive purification investments.
The FDA's evolving PDCAAS validation framework directly determines which products qualify for protein quality declarations. Manufacturers reformulating to meet "excellent source" thresholds face reformulation costs and analytical verification burdens. Sports nutrition and clinical segments absorb these compliance investments fastest, while commodity food applications lag in certification adoption.
Buyer concentration among fitness-focused direct-to-consumer brands rotates procurement toward contract manufacturers with in-house analytical capabilities. Traditional ingredient distributors lose share to vertically integrated co-packers offering finished-product validation. California and Wisconsin processing clusters capture this channel shift through integrated testing laboratories co-located with fractionation lines.
North America Dairy Protein Ingredients Market Segmentation
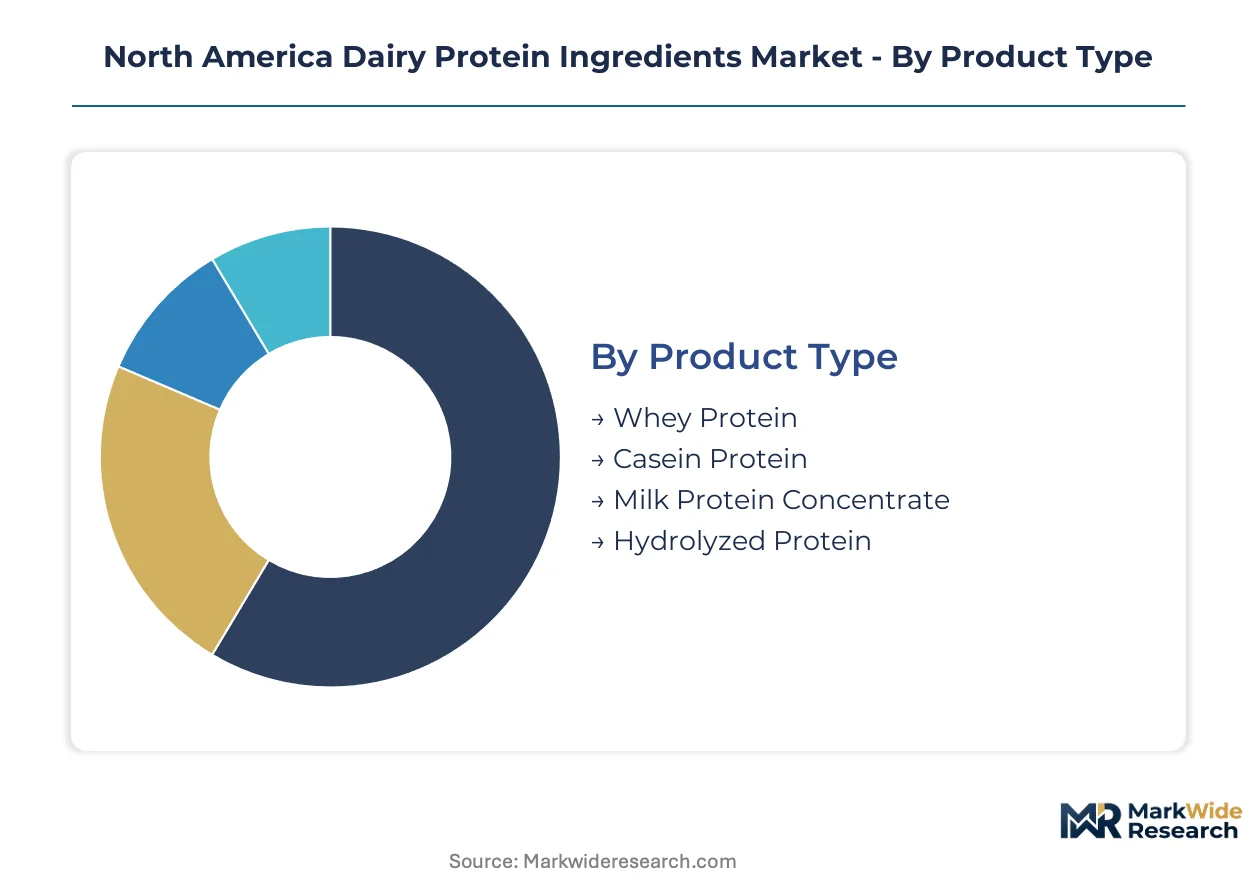
Segmentation in dairy protein ingredients reveals how technical specifications and delivery formats command divergent margin structures. Manufacturers allocate fractionation capacity based on end-use validation requirements rather than volume alone.
Product Type:
Margin pools concentrate in high-purity isolates and hydrolyzed fractions where enzymatic processing creates defendable differentiation.
- Whey Protein:Fractionated into concentrates and isolates exceeding 90% protein by dry weight. Sports nutrition brands in the upper Midwest dairy belt absorb isolates for leucine-bioavailability claims, while concentrates serve mass-market fortification where cost sensitivity dominates.
- Casein Protein:Micellar structures enable sustained amino acid release profiles. Overnight recovery formulations and clinical weight-management applications exploit this kinetic property, anchoring demand in medical nutrition and premium sports segments.
- Milk Protein Concentrate:Blended casein-whey ratios suit processed cheese and functional food matrices requiring emulsion stability.
- Hydrolyzed Protein:Pre-digested peptides reduce allergen potential for infant and medical nutrition.
Whey Protein holds installed capacity. Hydrolyzed Protein is rotating up the share rankings.
Application:
Application segmentation tracks how formulation complexity and regulatory scrutiny reshape procurement priorities across end-use verticals.
- Sports Nutrition:Clean-label recovery products with rapid gastric emptying profiles absorb premium whey isolates. Athletes and fitness consumers validate PDCAAS scores before purchase, compressing formulation choices toward FDA-compliant declarations.
- Dietary Supplements:Capsule and tablet formats prioritize shelf-stable concentrates with documented protein quality claims. Direct-to-consumer brands bypass traditional distribution, pulling procurement toward contract manufacturers with in-house analytical capabilities.
- Functional Foods:Protein fortification in bars and dairy alternatives demands flavor-neutral concentrates with heat stability.
- Bakery Products:Dough conditioning and moisture retention utilize milk protein concentrates for structural functionality.
Sports Nutrition commands premium positioning. Dietary Supplements is gaining share fastest through channel fragmentation.
End User:
Customer-type segmentation exposes how vertical integration and certification requirements fragment supplier relationships.
- Food Manufacturers:Pizza-cheese scale operations generate captive whey streams through integrated cheese-and-ingredient production, eliminating spot-market exposure.
- Beverage Companies:Ready-to-drink formats require cold-chain-stable isolates with solubility across pH ranges.
- Nutraceutical Firms:Medical and infant nutrition buyers demand hydrolyzed fractions with documented digestibility curves and reduced allergen profiles.
- Personal Care Brands:Collagen-adjacent positioning in topical applications absorbs trace volumes of dairy-derived peptides.
Food Manufacturers lock in captive supply. Nutraceutical Firms is climbing the fastest on clinical validation premiums.
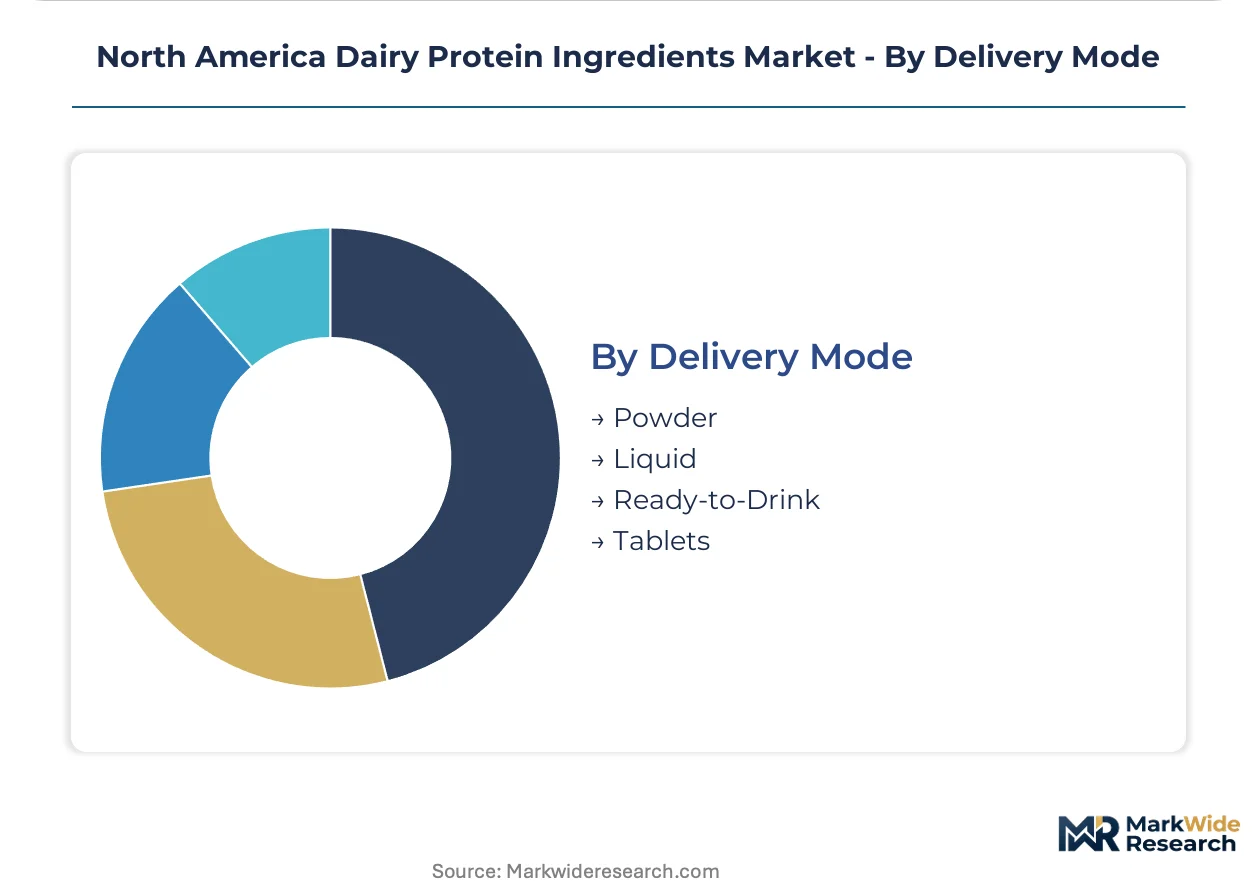
Delivery Mode:
Format segmentation determines cold-chain investment and shelf-life engineering requirements across distribution channels.
- Powder:Bulk concentrates and isolates dominate B2B procurement for reconstitution into finished goods.
- Liquid:Aseptic processing of protein slurries serves industrial food manufacturing with JIT delivery requirements.
- Ready-to-Drink:UHT-stabilized beverages with 12-18 month shelf life capture convenience-oriented fitness consumers.
- Tablets:Compression-formulated concentrates target supplement retail with portability positioning.
Powder retains volume leadership. Ready-to-Drink is expanding most quickly on convenience-driven channel shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows across North America reveal the United States as a net exporter of fractionated whey streams while Canada and Mexico absorb cross-border ingredient volumes for finished food manufacturing. Import dependency for specialized hydrolyzed peptides concentrates in Canadian nutraceutical corridors. Mexican beverage bottlers source U.S.-origin isolates for ready-to-drink fortification.
United States
Wisconsin and California processing clusters anchor domestic fractionation capacity through cooperative-sourced fluid milk networks. FDA PDCAAS validation requirements compress formulation choices toward documented protein quality claims. The upper Midwest dairy belt concentrates enzymatic precipitation expertise in legacy cheese-making regions.
Canada
Health Canada and CFIA compositional rules create dual-certification arbitrage for U.S. suppliers with cross-border production lines. Sports nutrition brands in Ontario and British Columbia absorb premium isolates for leucine-bioavailability positioning. Quebec's dairy cooperative infrastructure locks in grass-fed certification tiers for export-oriented ingredient streams.
Mexico
Beverage manufacturers in the Bajío Region and Mexico City Metro import U.S.-origin whey isolates for ready-to-drink protein fortification. Mexican federal food safety standards harmonize with FDA frameworks for cross-border dairy trade. Monterrey industrial corridors concentrate dairy processing joint ventures serving Central American export markets.
North America Dairy Protein Ingredients Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and captive supply architectures. The vendor base stratifies between scale-driven cheese-whey integrators and precision-isolate purifiers. Three archetypes dominate: cooperative-backed fractionators with raw milk lock-in, Irish-American supply architects with year-round grass-fed sourcing, and mozzarella-specialized operators with captive protein streams. Competitive moves concentrate on backward integration into fluid milk contracting and dual-certification infrastructure deployment.
Within the cooperative-backed tier, Dairy Farmers of America exemplifies raw milk aggregation at scale. Glanbia occupies a position as an Irish-American supply architect securing transatlantic grass-fed certification. Hilmar Cheese Company represents California Central Valley integration between cheese production and ingredient fractionation. These anchors illustrate how geographic clustering and supply architecture differentiation create defendable positioning.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Glanbia |
| Fonterra Co-operative Group |
| Saputo |
| Arla Foods Ingredients Group |
| Hilmar Cheese Company |
| AMCO Proteins |
| Leprino Foods |
| Darigold |
| Others |
Value Network & Pricing Analysis
USDA organic certification and FDA PDCAAS validation requirements simultaneously gate supply qualification and enable price stratification across the North American dairy protein landscape. Buyers lacking dual-certified sourcing capabilities face exclusion from premium tier procurement, while suppliers with integrated testing laboratories capture margin premiums through validated quality claims.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize input costs against fluid milk volatility. Three-tier pricing structure across premium grass-fed isolates, standard organic concentrates, and economy conventional grades reflects certification investment and leucine-bioavailability documentation. Cost compression in mid-tier concentrates intensifies as membrane filtration technology democratizes 90% isolate production. Mass-market food manufacturers exhibit highest price sensitivity, while sports nutrition brands absorb premiums for PDCAAS-validated declarations.
Supply Chain Analysis
Inventory cycles compress during Q2-Q3 peak milk production, extending lead times for hydrolyzed peptide fractions where enzymatic capacity concentrates in Wisconsin and California. Raw milk sourcing draws from cooperative networks in the upper Midwest dairy belt and California Central Valley processing clusters. Single-source vulnerability emerges from cheese-whey integration dominance among mozzarella-specialized operators. Distribution runs through vertically integrated co-packers with co-located analytical laboratories, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractionation expertise scarcity concentrates in legacy dairy processing regions, constraining expansion into emerging production clusters and amplifying returns for incumbent capability holders. Membrane separation and enzymatic precipitation skill gaps limit mid-scale processor competitiveness.
For Market Incumbents: Consolidate backward integration into fluid milk contracting through cooperative equity stakes, locking in certified supply streams before procurement competition intensifies. Expand dual-certification infrastructure in Wisconsin and California clusters to defend margin position against plant protein substitution in mass-market applications. For New Entrants and Emerging Players: Differentiate on hydrolyzed peptide specialization for medical nutrition white space where allergen reduction commands clinical validation premiums. Target Canadian cross-border harmonization opportunities through Health Canada and CFIA dual-certified production lines, leveraging arbitrage potential in Ontario and British Columbia sports nutrition corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from cooperative-backed fractionators seeking capital for organic infrastructure deployment. Long-term viability hinges on captive whey stream security through cheese-whey integration or transatlantic grass-fed sourcing architectures. Monitor FDA GRAS notification resolution velocity as inflection indicator for novel fractionation method commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Milk Contracting | Cooperative equity stakes in Wisconsin and California secure certified raw material streams against spot-market volatility. |
| Dual-Certification Infrastructure Deployment | Parallel organic and grass-fed cold-chain investments unlock premium tier pricing in sports nutrition channels. |
| Cross-Border Production Line Harmonization | Health Canada and CFIA dual certification enables arbitrage positioning in Ontario and British Columbia markets. |
| Hydrolyzed Peptide Capability Buildout | Enzymatic precipitation expertise addresses medical nutrition demand for documented digestibility curves. |
| Integrated Analytical Laboratory Investment | In-house PDCAAS validation capabilities capture procurement shift toward contract manufacturers with finished-product testing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with sports nutrition formulators, clinical nutrition procurement managers, dairy cooperative supply planners, and membrane filtration equipment specialists. Secondary validation drew from FDA GRAS notification databases, USDA organic certification records, Health Canada compositional guidance, and cooperative financial disclosures. Bottom-up capacity modeling and top-down consumption estimates were triangulated to reconcile production cluster outputs with end-use absorption patterns.
Across the analysis window, value projections reflect segment-level CAGRs derived from protein quality claim adoption curves and certification tier penetration rates. Segmentation dimensions modeled include product type purity grades, application formulation complexity, end-user vertical integration levels, and delivery mode cold-chain requirements. Forecast inputs incorporate fluid milk supply elasticity in the upper Midwest dairy belt and enzymatic fractionation capacity expansion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA PDCAAS framework stability and cooperative network consolidation continuity; material deviation in GRAS notification velocity or grass-fed certification adoption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Gelatin Market
Ingredients
Zea Mays Starch Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Olive Oil Market
Ingredients
Grape Seed Extracts Market
Ingredients
United Kingdom Protein Market
Ingredients
Citrus Pectin Market
Ingredients
Green Gram Powder Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
United States Avocado Oil Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Soy Hydrolysates Market
Ingredients
Bovine Gelatin Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Sunflower Lecithin Market