
 Brazil Starch Derivatives Market | 2026-2036
Brazil Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Starch Derivatives Market Outlook
ANVISA's food additive registration requirements is bifurcating the competitive landscape between qualified multinationals and local processors lacking certification bandwidth. Cargill Incorporated leverages its integrated corn-milling infrastructure across Mato Grosso to secure raw material cost advantages. Ingredion Incorporated differentiates through specialty modified starch portfolios tailored to Brazilian bakery and dairy applications. Tate & Lyle anchors its position via distribution partnerships with regional food compounders in the Southeast.
Starch derivatives encompass chemically, physically, or enzymatically altered starch polymers that exhibit modified viscosity, gelatinization temperature, or film-forming properties beyond native starch granules. These functional carbohydrates serve primarily as texture modifiers, binders, and controlled-release matrices across industrial formulations. Modified starch commands the dominant value share due to premium pricing for cross-linked and acetylated variants used in processed foods and pharmaceutical excipients. Maltodextrin represents the fastest-expanding product category, fueled by sports nutrition and infant formula applications requiring rapid dispersibility and clean flavor profiles. The sweetener application segment concentrates margin pools where high-purity dextrose supplies pharmaceutical-grade specifications.
ANVISA governs food additive safety assessments and maximum usage limits, while the Ministry of Agriculture (MAPA) oversees starch derivative labeling under processed food standards. BIS-equivalent conformity requirements for imported modified starches create compliance barriers that favor domestic production investments. The national bioeconomy framework under MCTI promotes cassava-derived alternatives, diversifying feedstock sources beyond corn. Stakeholders must monitor ANVISA's pending novel food consultations and MAPA's traceability mandates to anticipate reformulation costs and supply chain reconfiguration needs.
Market Dynamics
ANVISA's bifurcated food additive registration pathway concentrates competitive advantage among processors with dedicated regulatory compliance infrastructure, forcing domestic manufacturers to choose between certification investment and contract manufacturing dependence.
Growth Catalysts
- Clean-label reformulation mandates:São Paulo-based food compounders demand modified starches that replace synthetic stabilizers in dairy and bakery applications, creating pull for acetylated and cross-linked variants.
- ANVISA's updated additive framework:The regulator's streamlined consultation process for novel starch derivatives accelerates product registration timelines for qualified applicants.
- Cassava feedstock diversification:MCTI's national bioeconomy incentives promote root crop processing clusters in Minas Gerais as alternatives to corn-dependent supply chains.
Market Restraints
- Corn price volatility:Mato Grosso harvest fluctuations transmit directly into modified starch input costs, compressing margin stability for non-integrated processors.
- Import conformity barriers:BIS-equivalent certification requirements for foreign modified starches limit supplier diversification and protect domestic incumbents.
- Enzymatic conversion yield ceilings:Current maltodextrin production protocols face technical boundaries that cap throughput efficiency at Brazilian humidity and temperature conditions.
Strategic Opportunities
- Northeast region penetration:Pernambuco and Bahia food manufacturing corridors remain underserved by specialty starch distribution networks, offering first-mover positioning.
- Pharmaceutical excipient grade expansion:High-purity dextrose specifications for injectable formulations command premium positioning above standard food-grade pricing tiers.
- MAPA traceability mandate preparation:Early compliance with pending processed food ingredient tracking requirements creates differentiation against laggard competitors.
Industry Challenges
- Specialized enzymology talent scarcity:Brazilian universities produce insufficient starch biochemistry specialists to staff expanding R&D and process engineering functions.
- ANVISA registration timeline compression:Novel food additive consultations require 18-24 month documentation cycles that delay revenue realization for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Starch Derivatives Market |
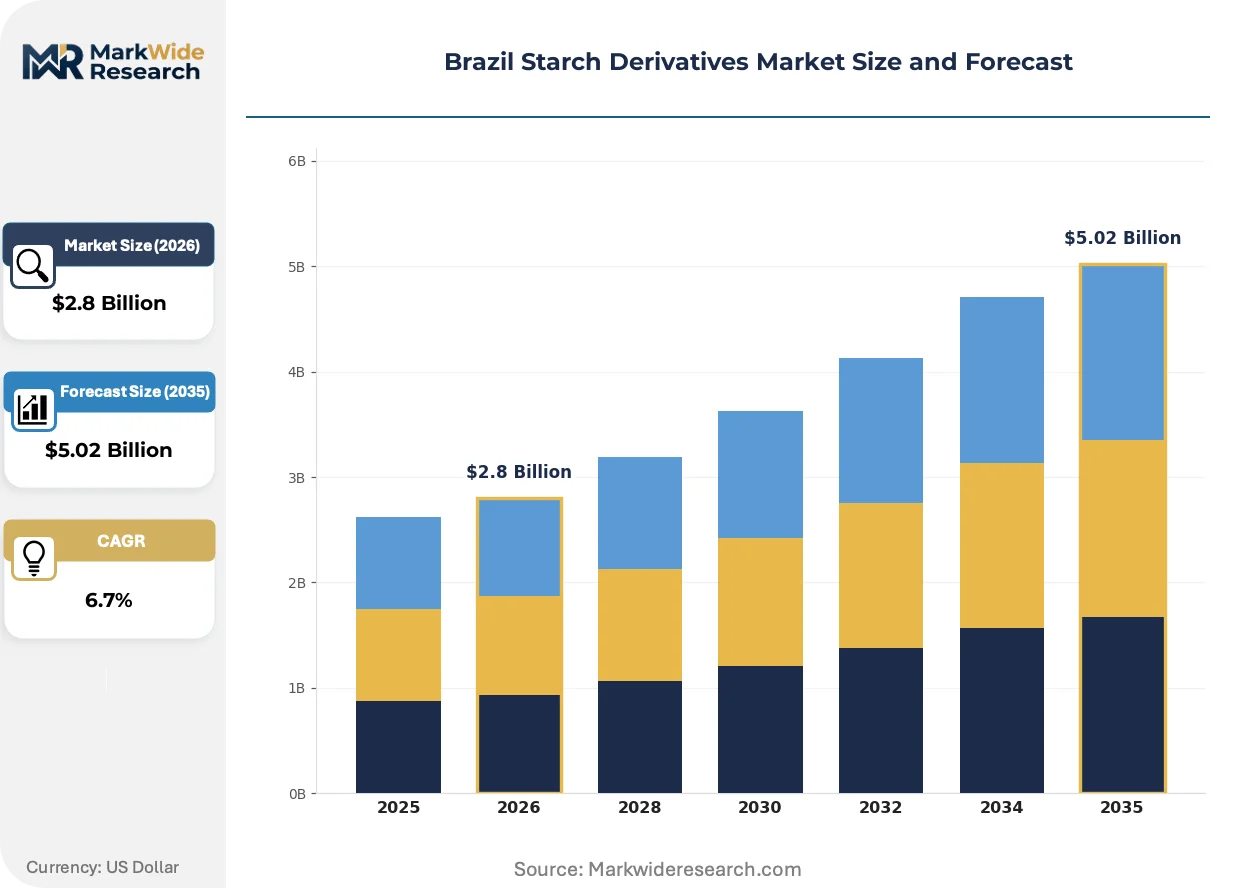
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Dextrose, Maltodextrin End User: Food & Beverages, Pharmaceuticals, Paper & Packaging, Personal Care Application: Thickening Agent, Stabilizer, Sweetener, Film Former Form: Powder, Granule, Liquid, Gel |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Agrana Group, Tate & Lyle, Roquette Frères, Tereos SA, Avebe, Grain Processing Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Starch Derivatives Market Strategic Shifts
Enzymatic modification techniques and clean-label formulation requirements are restructuring how Brazilian processors develop and commercialize functional starch ingredients across food, pharmaceutical, and industrial channels.
Enzymatically produced resistant starches is fragmenting traditional modified starch categories by enabling dietary fiber claims in bakery and pasta applications without compromising texture. Campinas-area mills adopt these biocatalytic processes to supply health-positioned food brands. The technology is fragmenting established product hierarchies by collapsing the distinction between functional fiber additives and conventional texturizers.
MAPA's pending processed food traceability mandates require lot-level ingredient documentation from starch derivative suppliers through finished goods distribution. This regulatory pressure forces compounders to requalify suppliers based on documentation capabilities rather than price alone. Southeast region dairy and meat processors face the steepest compliance preparation costs as they reconfigure procurement systems.
Bakery and confectionery manufacturers in São Paulo state consolidate supplier relationships around full-service starch portfolios that include technical formulation support. Regional food compounders now bundle modified starches with emulsifier and hydrocolloid recommendations, displacing standalone ingredient procurement. This consolidation pattern concentrates volume with integrated suppliers capable of application laboratory services.
Brazil Starch Derivatives Market Segmentation
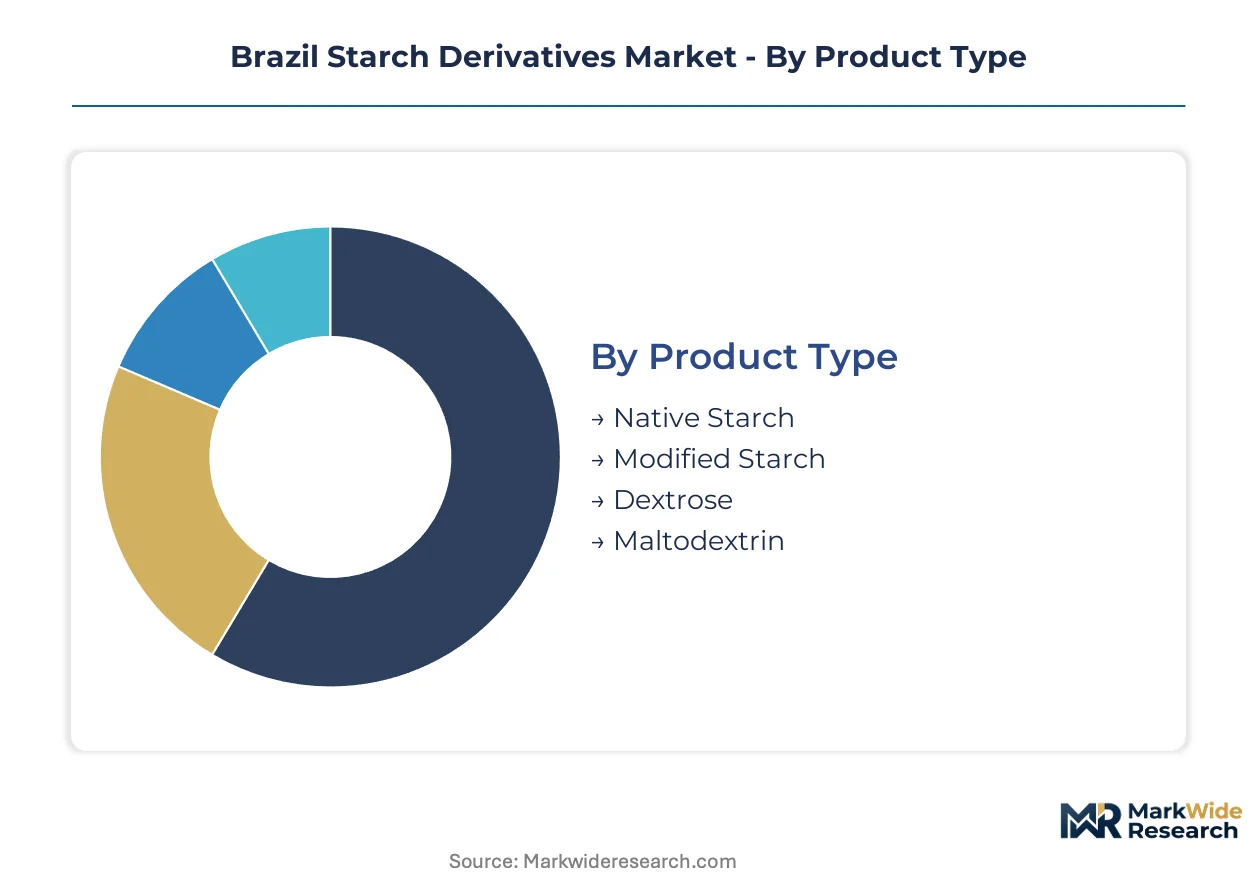
Segmentation in Brazil's starch derivatives market reveals how functional specifications and regulatory pathways fragment procurement decisions across end-use industries. Buyers in São Paulo's food manufacturing corridor prioritize modified starches with ANVISA-compliant documentation, while pharmaceutical compounders in Campinas demand excipient-grade dextrose with traceability certification.
Product Type:
Margin pools concentrate in chemically altered variants where cross-linking and acetylation command premium positioning over commodity native grades.
- Modified Starch:Cross-linked and acetylated polymers deliver controlled viscosity under thermal and shear stress. São Paulo dairy processors specify these variants for clean-label yogurt and dessert applications where synthetic stabilizer replacement drives specification premiums. ANVISA's additive registration requirements favor suppliers with dedicated compliance infrastructure.
- Maltodextrin:Enzymatically hydrolyzed starch polymers with dextrose equivalence below 20 provide rapid dispersibility and clean flavor carriers. Sports nutrition formulators in Minas Gerais and infant formula manufacturers in Campinas anchor demand for low-hygroscopicity grades. Humidity-adjusted production protocols remain a technical constraint at Brazilian temperature conditions.
- Native Starch:Unmodified corn and cassava granules serve cost-sensitive industrial binders and paper sizing applications.
- Dextrose:High-purity crystalline glucose supplies pharmaceutical injectable specifications and fermentation feedstocks.
Modified Starch holds installed capacity. Maltodextrin is rotating up the share rankings.
End User:
Volume concentration tracks food manufacturing geography, with Southeast region compounders consuming disproportionate share of texturizer and stabilizer grades.
- Food & Beverages:Bakery, dairy, and processed meat manufacturers in São Paulo state specify modified starches for texture control and moisture management. Clean-label reformulation mandates from major retail chains are displacing synthetic hydrocolloids with acetylated distarch phosphate and similar variants.
- Pharmaceuticals:Injectable-grade dextrose and tablet disintegrants require USP-equivalent certification that limits qualified supplier pools. Campinas-area pharmaceutical clusters source high-purity excipients through validated distribution channels with lot-level documentation.
- Paper & Packaging:Surface sizing and adhesive applications consume native starch for cost efficiency in corrugated board manufacturing.
- Personal Care:Film-forming and absorbent properties drive modest volume in cosmetic and hygiene product formulations.
Food & Beverages dominates procurement tonnage. Pharmaceuticals is climbing the fastest on value-per-kilogram metrics.
Application:
Functional role determines pricing tier, with controlled-release and pharmaceutical-grade specifications capturing premium positioning above commodity texturizers.
- Thickening Agent:Viscosity-building properties in sauces, soups, and dairy systems represent the foundational demand driver. Cross-linked starches maintain texture stability through freeze-thaw cycles and high-temperature processing.
- Stabilizer:Emulsion maintenance and syneresis prevention in processed foods.
- Sweetener:Dextrose and maltodextrin provide fermentable carbohydrates and bulk sweetness.
- Film Former:Edible coatings and pharmaceutical tablet barriers.
Thickening Agent holds formulation ubiquity. Stabilizer is gaining share fastest as clean-label dairy expansion accelerates.
Form:
Physical state selection reflects handling economics and dissolution kinetics, with powder dominance giving way to liquid concentrates in high-throughput beverage operations.
- Powder:Spray-dried and drum-dried variants offer extended shelf stability and precise dosing for dry blend applications. Southeast region food compounders specify powder grades for inventory efficiency and transport cost optimization.
- Liquid:Pre-hydrated starch solutions eliminate dissolution steps in continuous beverage processing.
- Granule:Intermediate particle size for controlled hydration rates.
- Gel:Pre-gelatinized preparations for instant applications.
Powder commands existing infrastructure investment. Liquid is expanding most quickly in carbonated and still beverage manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MCTI's national bioeconomy framework channels investment toward cassava processing clusters, diversifying feedstock geography beyond traditional corn dependence. State-level industrial policies in Minas Gerais and São Paulo accelerate modified starch capacity expansion. Regional procurement patterns track food manufacturing corridor density.
São Paulo
São Paulo state concentrates Brazil's food compounder demand for clean-label modified starches in dairy and bakery applications. ANVISA's additive registration requirements favor suppliers with dedicated compliance infrastructure located near Campinas processing clusters. The Campinas-Ribeirão Preto corridor hosts integrated starch derivative mills serving multinational food manufacturers.
Minas Gerais
Minas Gerais leverages MCTI bioeconomy incentives to develop cassava-derived starch alternatives to corn-based supply chains. State agricultural extension programs promote root crop processing infrastructure in Triângulo Mineiro. Uberlândia-area mills experiment with enzymatic conversion protocols adapted to regional humidity conditions.
Rio Grande do Sul
Rio Grande do Sul anchors southern region demand for native starch in paper sizing and corrugated board manufacturing. State environmental regulations on industrial effluent shape wet-milling facility location decisions. Porto Alegre metropolitan area food processors source modified starches through distributors with ANVISA-certified documentation systems.
Bahia
Bahia represents an underserved corridor where food manufacturing growth outpaces specialty starch distribution network penetration. Northeast regional development funds under BNDES support agroindustrial processing investments. Feira de Santana logistics hubs offer first-mover positioning for suppliers establishing direct distribution to Salvador-area compounders.
Paraná
Paraná integrates corn production density with wet-milling infrastructure serving both domestic and export markets. State agricultural research institutions collaborate with processors on enzymatic yield optimization for maltodextrin production. Londrina and Maringá industrial zones concentrate starch derivative capacity with rail connectivity to Santos port terminals.
Brazil Starch Derivatives Market Competitive Environment
Player mix skews toward integrated agribusiness conglomerates with captive corn supply and dedicated regulatory compliance infrastructure. Market structure concentrates advantage among processors with ANVISA certification bandwidth and backward integration into raw material sourcing. Three archetypes dominate: multinational integrated processors, regional specialists with formulation laboratory capabilities, and contract manufacturers dependent on qualified partners for product registration. Competitive dynamics center on capacity expansion in Southeast processing corridors and portfolio diversification into pharmaceutical-grade specifications.
Within the multinational integrated tier, Cargill Incorporated and Ingredion Incorporated exemplify players leveraging upstream corn-milling infrastructure to secure input cost advantages. Tate & Lyle occupies a position anchored through distribution partnerships with regional food compounders. These companies represent the archetype of processors combining regulatory compliance depth with application technical service capabilities.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Agrana Group |
| Tate & Lyle |
| Roquette Frères |
| Tereos SA |
| Avebe |
| Grain Processing Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles at Southeast region compounders concentrate procurement leverage among ANVISA-certified suppliers, translating documentation bandwidth into pricing power over non-integrated domestic processors. This lead-time compression rewards backward-integrated multinationals with captive corn supply while squeezing margin stability at contract-dependent manufacturers.
Pricing Analysis
Certification level under ANVISA's additive framework creates the primary spread between pharmaceutical-grade dextrose and commodity native starch tiers. Three-tier pricing structure across premium excipient, standard food-grade, and economy industrial levels reflects documentation depth and traceability investment. Pricing pressure stems from Mato Grosso harvest volatility transmitting directly into modified starch input costs. Pharmaceutical compounders in Campinas demonstrate lowest price sensitivity due to USP-equivalent specification requirements, while paper sizing buyers in Rio Grande do Sul anchor the economy tier with volume-driven procurement.
Supply Chain Analysis
Mato Grosso corn belt concentration anchors upstream raw material flows, creating single-source vulnerability during harvest fluctuations. Brazilian wet-milling infrastructure draws from corn and cassava feedstocks, with enzymatic conversion enzymes sourced from specialized biocatalyst suppliers. Distribution runs through Campinas-Ribeirão Preto processing clusters serving Southeast food manufacturing corridors, with BNDES-funded Northeast expansion threatening incumbent logistics advantages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among São Paulo-based food compounders consolidating supplier relationships around full-service starch portfolios with technical formulation support. This procurement consolidation fragments volume access for standalone ingredient vendors lacking application laboratory capabilities.
For Market Incumbents: Secure ANVISA registration bandwidth expansion ahead of pending novel food consultations to preempt competitor certification delays. Anchor backward integration into Triângulo Mineiro cassava processing clusters under MCTI bioeconomy incentives, displacing corn-dependent supply risk. Lock long-term offtake agreements with pharmaceutical compounders before MAPA traceability mandates requalify supplier pools on documentation capabilities rather than price. For New Entrants and Emerging Players: ANVISA's streamlined consultation fast-track enables 18-24 month registration acceleration for qualified applicants with dedicated regulatory infrastructure. Target Bahia's underserved food manufacturing corridor where Northeast regional development funds support agroindustrial processing investments. Differentiate through enzymatic resistant starch production serving health-positioned bakery brands with dietary fiber claims. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across maltodextrin production as enzymatic yield optimization reduces unit capital requirements. Acquire regional specialists with formulation laboratory capabilities and existing ANVISA certification infrastructure. Monitor ANVISA novel food consultation queue depth as inflection signal for registration timeline compression and revenue realization delays.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Registration bandwidth separates qualified suppliers from contract manufacturing dependence under bifurcated additive pathways. |
| Cassava Feedstock Diversification | MCTI bioeconomy incentives root alternative supply chains in Minas Gerais processing clusters beyond corn dependence. |
| Pharmaceutical-Grade Capacity Expansion | USP-equivalent dextrose specifications command premium positioning above standard food-grade pricing tiers in Campinas clusters. |
| Application Laboratory Buildout | Technical formulation support consolidates supplier relationships as São Paulo compounders bundle starch with emulsifier recommendations. |
| Northeast Distribution Network Establishment | First-mover positioning in Pernambuco and Bahia corridors captures food manufacturing growth ahead of incumbent network expansion. |
Study Parameters
A spread of perspectives from plant managers at wet-milling facilities, procurement leads at downstream food compounders, distribution channel partners, and ANVISA regulatory affairs specialists converged on the working assumptions. Primary interview intelligence combined with customs/trade data, MAPA processed food standards documentation, SEC 10-K filings of listed processors, and MCTI bioeconomy framework publications. Bottom-up capacity utilization estimates triangulated against top-down consumption modeling across end-use industries.
Segmentation dimensions modeled include product type hierarchy, end-user industry concentration, functional application role, and physical form state across the projection horizon. CAGRs derived from regression analysis of historical pricing and volume trajectories, adjusted for ANVISA regulatory timeline assumptions and cassava feedstock penetration scenarios. Forecast inputs incorporated Mato Grosso corn yield volatility bands and pharmaceutical excipient certification queue projections.
The analysis sits within stated boundaries; outcomes outside ANVISA consultation timeline assumptions or MCTI incentive continuity would require recalibration. Forecasts reflect documented assumptions on enzymatic conversion yield ceilings and humidity-adjusted production protocols. Practitioners should keep alternative scenarios live as MAPA traceability mandate implementation schedules and Northeast regional development fund disbursement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Vitamin Ingredients Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Thinned Starch Market
Ingredients
African Brewing Enzymes Market
Ingredients
North America Potato Protein Market
Ingredients
North America Feed Yeast Market
Ingredients
Hen Egg White Protein Market
Ingredients
Coconut Cream Powder Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Commercial Flour Market
Ingredients
Bouillon Market
Ingredients
Kairomones Market
Ingredients
Cocoa Liquor Market
Ingredients
Non Meat Ingredients Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Spray-Dried Isolate Market