
 Chickpea Fiber Market | 2026-2036
Chickpea Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpea Fiber Market Analytics
Modular ingredient bundling is consolidating around pre-blended fiber-protein systems that simplify formulation for bakery and meat-alternative developers. NutriPea leverages its pulse-processing infrastructure to anchor supply continuity for North American buyers. AGT Food competes through vertical control over origination and milling, while Roquette differentiates via its established European distribution network for specialty carbohydrates and fibers.
Chickpea fiber comprises the insoluble and soluble polysaccharide fractions derived from chickpea hulls and cotyledons, typically containing 60-80% total dietary fiber with residual protein and starch fractions; manufacturers employ dry or wet milling followed by air classification or enzymatic purification to concentrate fiber content for use as a texturizer, bulking agent, and nutritional fortificant in reduced-calorie and gluten-free formulations. Dietary fiber powder dominates current volume owing to its versatility across baking and fortification applications, while fiber-enhanced snacks represent the fastest-growing product configuration as CPG brands pursue front-of-pack fiber claims. The food and beverage end-use channel occupies the largest margin pool, though nutraceuticals is deepening pull-through as supplement brands seek prebiotic positioning.
The FDA's dietary fiber guidance shapes product qualification for U.S. market access, while EFSA health claim frameworks influence European formulation decisions and the EU Green Deal's protein diversification targets are redirecting agricultural processing subsidies toward pulse-derived ingredients. India's FSSAI fortification standards and China's GB standards for dietary supplements add compliance layers for exporters targeting Asia-Pacific formulation houses. Stakeholders must monitor how evolving prebiotic definitions across regulatory jurisdictions reshape fiber purity requirements and ingredient positioning strategies.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are compressing ingredient qualification timelines, forcing chickpea fiber suppliers to validate prebiotic health claims through accelerated clinical substantiation programs.
Growth Catalysts
- EFSA Prebiotic Framework:The European regulator's evolving guidance on gut health claims creates compliant positioning pathways for chickpea fiber in supplement and functional food formulations.
- Meat-Alternative Binders:Plant-based protein manufacturers in Germany integrate chickpea fiber into textured vegetable protein systems to improve moisture retention and bite structure.
- Air Classification:Dry-milling technology upgrades at pulse-processing facilities yield higher-purity fiber fractions, reducing enzymatic purification costs and expanding addressable volume.
Market Restraints
- Chickpea Price Volatility:Input cost swings from drought cycles in Canada and Australia compress margin stability for fiber concentrate producers.
- Supply Concentration:Three origination clusters—Saskatchewan, Victoria, and Maharashtra—control over sixty percent of merchantable chickpea supply, creating geographic risk exposure.
- Enzymatic Processing Costs:Wet-fraction purification requires capital-intensive centrifugation and spray-drying infrastructure that smaller processors cannot finance.
Strategic Opportunities
- India Fortification Mandates:FSSAI's expanding standards for dietary fiber in staple foods open formulation partnerships with domestic flour millers and snack manufacturers.
- Cell-Cultured Meat Scaffolds:Emerging applications in cellular agriculture utilize chickpea fiber as edible scaffolding material, creating premium pricing potential.
- EU Green Deal Subsidies:Protein diversification targets redirect agricultural processing grants toward pulse-derived ingredient clusters in the Netherlands and Denmark.
Industry Challenges
- Clinical Validation Timelines:Prebiotic health claim substantiation requires twelve-to-eighteen-month human intervention studies that delay product launches.
- Cross-Contamination Protocols:Gluten-free certification demands segregated milling lines and allergen testing infrastructure that legacy pulse processors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpea Fiber Market |
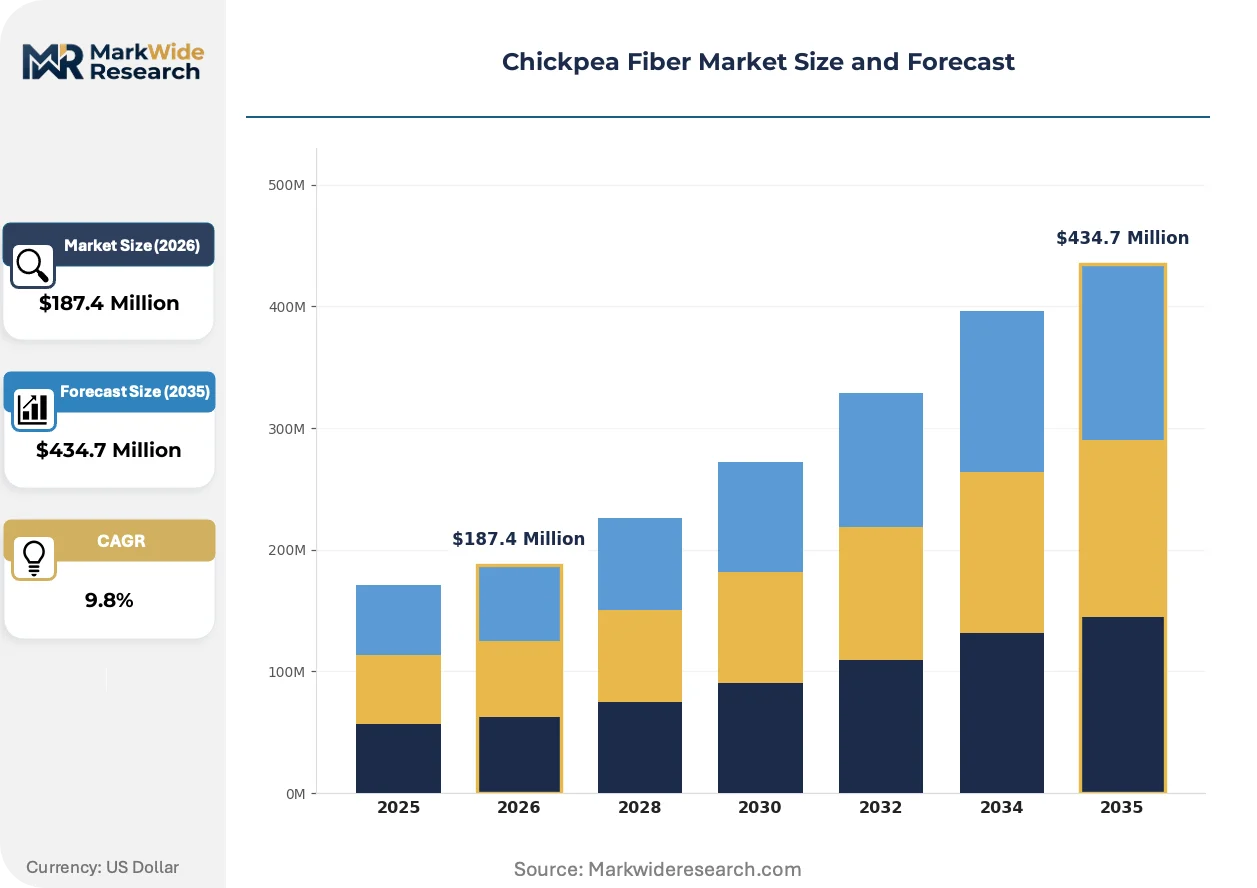
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Fiber Powder, Whole Grain, Fiber-Enhanced Snacks, Protein-Rich Flour End Use Industry: Food & Beverage, Pharmaceuticals, Animal Feed, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Application: Baking, Supplementation, Fortification, Confectionery |
| Companies Covered | NutriPea, AGT Food, Ingredion, Roquette, ChickP, ADM, Glanbia, Vestkorn, Parabel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpea Fiber Market Evolving Landscape
Ingredient technology is pivoting toward modular pre-blended systems that collapse formulation steps for bakery and meat-alternative developers, compressing R&D cycles and supplier qualification burdens.
Enzymatic fiber extraction is decentralizing production economics by enabling smaller-scale processors to achieve pharmaceutical-grade purity without continuous centrifuge infrastructure. Regional cooperatives in France and Spain deploy mobile processing units that rotate through harvest windows, cutting transport costs for raw hulls. This distributed model is compressing concentration margins for legacy wet-milling facilities.
REACH registration requirements for novel food ingredients tighten disclosure thresholds for residual protein and anti-nutritional factors in fiber concentrates. The European Chemicals Agency's evolving substance evaluation protocols force suppliers to expand toxicological dossiers. German and Dutch formulators now demand third-party verification of heavy metal and mycotoxin levels before contract execution.
CPG procurement teams consolidate supplier panels around vertically integrated pulse processors that control origination through final ingredient form. This buyer concentration is displacing merchant traders from fiber concentrate distribution. North American bakery developers now source directly from Saskatchewan-based processors, bypassing traditional ingredient distributors entirely.
Chickpea Fiber Market Segmentation
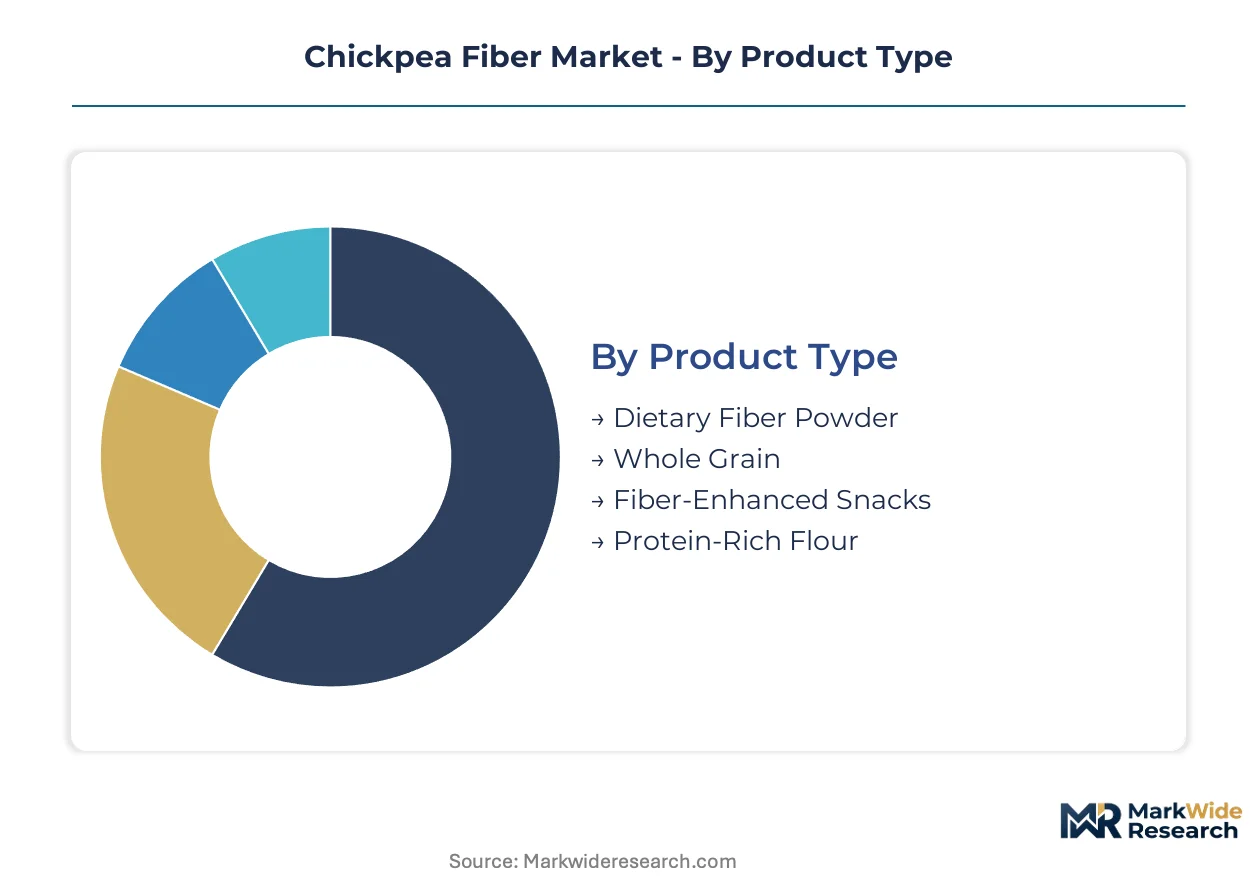
Chickpea fiber's functional versatility creates distinct value pools across product formats and end-use channels. Segmentation reveals where formulation complexity versus standalone simplicity drives procurement decisions and margin capture.
Product Type:
Standalone concentrates command premium positioning against embedded formats that reduce customer formulation burden.
- Dietary Fiber Powder:Concentrated insoluble and soluble polysaccharide fractions, typically 60-80% total dietary fiber content, serve as texturizers and bulking agents in reduced-calorie formulations. Bakery applications in North America absorb the largest volumes as clean-label formulators replace modified starches with native fiber systems. FDA's tightened dietary fiber definition pushes suppliers toward higher-purity extraction processes to maintain qualification status.
- Fiber-Enhanced Snacks:Pre-formulated extruded products carry front-of-pack fiber claims for CPG brands seeking rapid market entry without internal R&D investment. This configuration climbs fastest as snack manufacturers chase wellness-positioned shelf space in German and U.S. retail channels.
- Whole Grain:Minimally processed chickpea fractions retain protein and starch matrices for traditional food applications.
- Protein-Rich Flour:Hybrid concentrates balance fiber and protein content for meat-alternative binder systems.
Dietary Fiber Powder leads volumes today; Fiber-Enhanced Snacks is gaining share fastest.
End Use Industry:
Margin concentration follows regulatory stringency, with pharmaceutical-grade applications extracting value through certification burdens that filter competition.
- Food & Beverage:The largest addressable channel spans bakery, beverage, and plant-based meat systems where chickpea fiber replaces synthetic hydrocolloids. Germany's ingredient clusters around Hamburg and Cologne integrate fiber into meat-alternative binders for moisture retention and bite structure.
- Nutraceuticals:Prebiotic positioning demands clinical substantiation that extends qualification timelines but locks in premium pricing. Supplement brands deepen pull-through as EFSA's evolving gut health claim framework creates compliant pathways for fiber-based formulations.
- Pharmaceuticals:Excipient applications require pharmaceutical-grade purity with toxicological dossiers meeting REACH registration thresholds.
- Animal Feed:Fiber concentrates enter pet food and livestock nutrition as digestibility modulators and binding agents.
Food & Beverage dominates current revenue; Nutraceuticals shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with large formulators bypassing intermediaries entirely.
- Direct Sales:Vertically integrated processors contract directly with North American bakery developers and European meat-alternative manufacturers, eliminating distributor margins. Saskatchewan-based suppliers now ship fiber concentrates straight to formulation houses, displacing traditional ingredient traders.
- Supermarkets:Retail-facing fiber-enhanced snacks and consumer packaged flours move through conventional grocery networks.
- Online Retail:Specialty and small-batch producers access niche buyers through e-commerce platforms.
- Health Stores:Premium-positioned supplements and organic-certified fibers target wellness-focused consumers.
Direct Sales captures the largest B2B volume; Online Retail expands most quickly among emerging brands.
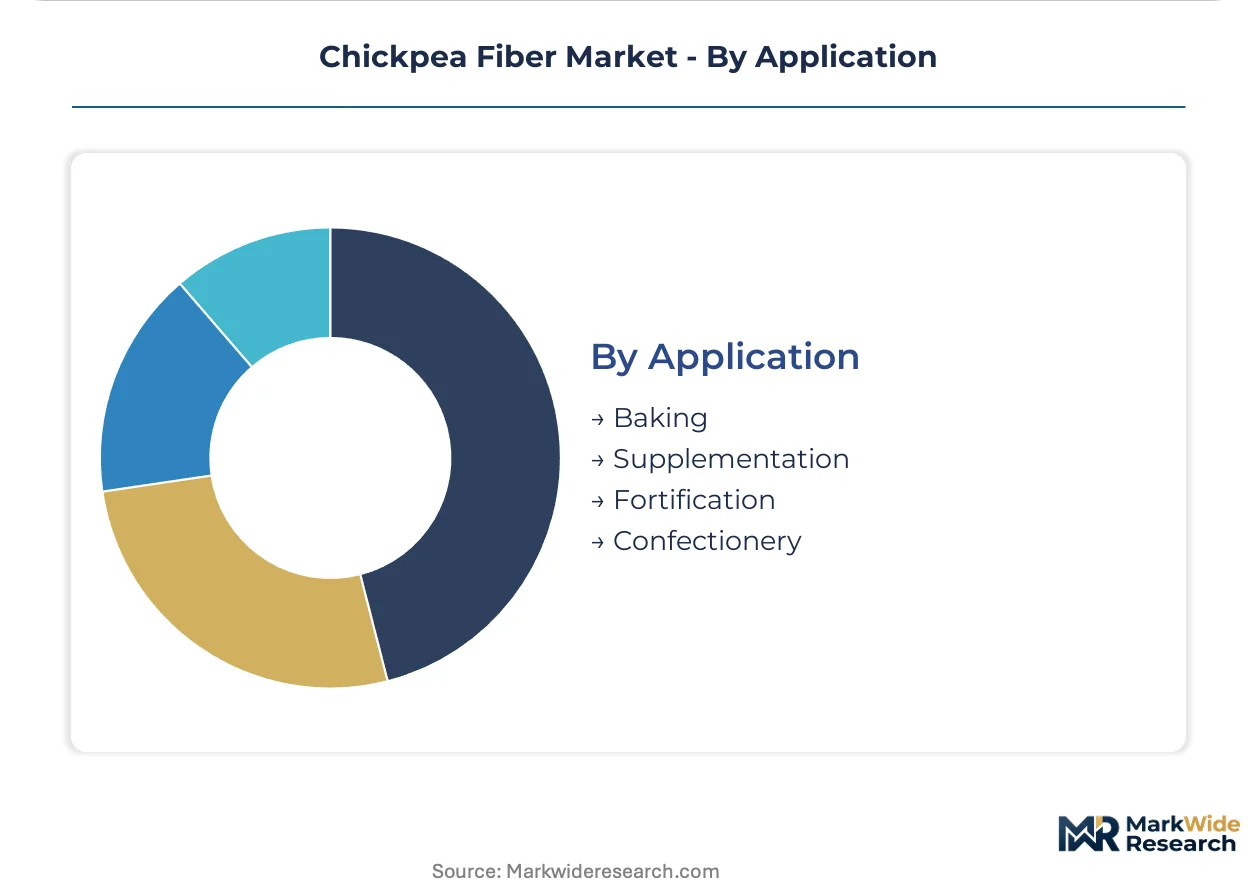
Application:
Application maturity varies by technical validation requirements, with established uses facing displacement from novel positioning strategies.
- Baking:Gluten-free and reduced-calorie formulations leverage chickpea fiber for structure and moisture management. Clean-label mandates from FDA and EFSA compress ingredient qualification timelines, forcing accelerated supplier validation.
- Fortification:India's FSSAI expanding standards for dietary fiber in staple foods open formulation partnerships with domestic flour millers. Regulatory mandates in developing markets create contracted demand pools.
- Supplementation:Capsule and powder formats target prebiotic health claims requiring twelve-to-eighteen-month human intervention studies.
- Confectionery:Fiber incorporation reduces sugar content while maintaining texture in chocolate and candy systems.
Baking leads application volumes today; Fortification is climbing the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chickpea fiber processing originated in the Canadian prairies during the 1990s pulse-processing expansion, then migrated to European ingredient clusters seeking clean-label alternatives to modified starches. Today the industry distributes across origination hubs, manufacturing centers, and formulation markets spanning three continents.
Canada
Saskatchewan's merchantable chickpea supply anchors North American fiber concentrate production, with processors in Regina and Saskatoon shipping directly to U.S. bakery developers. The Canadian Grain Commission maintains grading standards that influence global pulse trade quality benchmarks. Vertically integrated facilities around Saskatoon now bypass traditional ingredient distributors entirely, contracting straight to formulation houses.
United States
FDA's tightened dietary fiber definition drives qualification investments by U.S.-based CPG brands reformulating baked goods and meat alternatives. Clean-label mandates from major retailers compress supplier validation timelines to under six months. Minneapolis-St. Paul and Chicago house the largest concentration of bakery and plant-based protein R&D facilities sourcing chickpea fiber.
Germany
EFSA's evolving prebiotic health claim framework positions German formulators to capture premium supplement positioning. The EU Green Deal's protein diversification targets redirect agricultural processing subsidies toward pulse-derived ingredient clusters. Hamburg and Cologne anchor the densest concentration of meat-alternative binder development, with local ingredient houses integrating chickpea fiber into textured vegetable protein systems.
India
FSSAI's expanding fortification standards for dietary fiber in staple foods create contracted demand pools with domestic flour millers and snack manufacturers. Maharashtra's processing infrastructure around Mumbai and Pune converts raw hulls into export-grade concentrates. The country's central food regulator tightens disclosure requirements for residual protein and anti-nutritional factors in fiber shipments bound for European markets.
France
Roquette's established European distribution network for specialty carbohydrates and fibers leverages French regulatory familiarity with novel food ingredient dossiers. ECHA's REACH registration requirements for residual protein disclosure force suppliers to expand toxicological documentation. Regional cooperatives in southern France deploy mobile processing units that rotate through harvest windows, cutting transport costs for raw chickpea hulls.
Chickpea Fiber Market Competitive Landscape
The competitive structure tilts toward vertically integrated pulse processors with captive origination control. Three strategic archetypes dominate: Saskatchewan-based processors with backward integration into prairie chickpea supply, European ingredient houses leveraging established distribution networks for specialty carbohydrates, and diversified agricultural conglomerates bundling fiber into broader pulse-protein portfolios. Capacity expansion and direct-to-formulator sales channel development constitute the primary competitive moves, displacing traditional merchant traders from fiber concentrate distribution.
Among North American processors, NutriPea leverages its pulse-processing infrastructure to anchor supply continuity for bakery and meat-alternative developers, while AGT Food competes through vertical control over origination and milling. Roquette occupies a distinct position as a European specialist with established distribution networks for specialty carbohydrates and fibers. These three exemplify the archetype split between origination-integrated North American players and formulation-proximate European houses.
| Leading Market Players |
|---|
| NutriPea |
| AGT Food |
| Ingredion |
| Roquette |
| ChickP |
| ADM |
| Glanbia |
| Vestkorn |
| Parabel |
| Others |
Value Network & Pricing Analysis
Backward integration into Saskatchewan chickpea origination anchors pricing power for North American fiber concentrate suppliers, compressing procurement costs while enabling direct-to-formulator contracts that bypass traditional ingredient distributor margins. Canadian processors leverage captive supply control to stabilize input costs against drought-driven volatility in Victoria and Maharashtra, translating upstream security into premium positioning for pharmaceutical-grade purity tiers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates contract values by purity thresholds and toxicological documentation depth. Price differentiation hinges on EFSA prebiotic claim substantiation and FDA dietary fiber qualification status, with clinical validation timelines compressing margins for unsubstantiated tiers. Cost compression in standard-grade concentrates is intensifying as enzymatic processing technology diffuses to smaller-scale French and Spanish cooperatives. Bakery developers in Minneapolis-St. Paul exhibit highest price sensitivity due to commoditized modified starch substitution economics, while German nutraceutical formulators absorb premium tiers for gut health claim positioning.
Supply Chain Analysis
REACH registration and FDA dietary fiber qualification gating filter supplier participation, forcing toxicological dossier investments that smaller merchants cannot finance. Geographic supply concentrates in Canada, Australia, and India, with Saskatchewan's merchantable chickpea origination, Victoria's drought-exposed production, and Maharashtra's hull processing infrastructure anchoring global fiber concentrate flows. Raw material dependencies center on chickpea hulls, enzymatic processing reagents, and pharmaceutical-grade spray-drying capacity. Single-source vulnerability concentrates around Saskatchewan's vertically integrated processors, where bypass of traditional distributors eliminates price discovery alternatives. Distribution runs through direct sales channels for large formulators and health store networks for premium supplement positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chickpea fiber has transitioned into a late-cycle quality market where formulation-grade certification and clinical substantiation separate viable suppliers from commodity merchants, with EFSA's evolving prebiotic framework redirecting procurement toward dossier-complete ingredient houses.
For Market Incumbents: Cement supply continuity through captive origination expansion in Saskatchewan and Maharashtra, locking in tolling agreements with regional cooperatives ahead of harvest windows. Defend against enzymatic processing technology diffusion by accelerating pharmaceutical-grade capacity additions that smaller French and Spanish operators cannot replicate. Prioritize EFSA gut health claim dossier completion to maintain premium tier access as clinical validation timelines lengthen. For New Entrants and Emerging Players: Contract research organizations offer white-space entry points through outsourced clinical substantiation services, enabling prebiotic claim positioning without in-house twelve-to-eighteen-month study infrastructure. India's FSSAI fortification mandates present the most penetrable demand pool, with domestic flour millers and snack manufacturers seeking compliant fiber suppliers for staple food reformulation. A co-manufacturing partnership with established Saskatchewan processors provides the cleanest go-to-market path for North American bakery qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where clinical validation capabilities and REACH-registered toxicological dossiers concentrate in single facilities, creating scarcity value for acquisition targets with dual-continent regulatory approval. The five-to-ten year viability window favors vertically integrated processors with backward origination control and forward formulation relationships over merchant traders displaced from distribution. Monitor EFSA prebiotic framework finalization as the critical inflection signal for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Captive Saskatchewan chickpea supply eliminates drought-driven input cost volatility for fiber concentrate producers. |
| Clinical Validation Program Investment | EFSA-compliant gut health claim substantiation unlocks premium nutraceutical pricing tiers for prebiotic positioning. |
| Direct-to-Formulator Channel Development | Bypass of traditional ingredient distributors captures margin compression in North American bakery procurement. |
| Pharmaceutical-Grade Capacity Expansion | REACH-registered spray-drying infrastructure filters competition for excipient-grade fiber applications. |
| Mobile Processing Unit Deployment | French and Spanish cooperative rotation through harvest windows cuts raw hull transport costs for regional processors. |
Research Methodology
Multiple input streams — executive interviews with pulse processing plant managers, procurement leads at North American bakery developers, regulatory affairs directors at European ingredient houses, and technical R&D heads at meat-alternative manufacturers — were reconciled against customs trade data, FDA GRAS notification filings, EFSA novel food dossiers, and FSSAI fortification standard updates. Bottom-up volume triangulation across product type and end-use segments was cross-validated against top-down expenditure analysis from food and beverage formulation budgets.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling across dietary fiber powder, fiber-enhanced snacks, whole grain, and protein-rich flour formats intersecting with food and beverage, nutraceutical, pharmaceutical, and animal feed end-use channels. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA prebiotic framework progression, FDA dietary fiber definition enforcement intensity, and EU Green Deal subsidy allocation shifts. Industry-specific forecast inputs included chickpea origination yield projections and enzymatic processing technology diffusion curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA gut health claim finalization timelines, drought frequency in Canadian and Australian origination belts, and REACH registration threshold adjustments for residual protein disclosure. Forecasts reflect documented assumptions on clinical validation completion rates and regulatory enforcement intensity. A model refresh is warranted upon material change in EFSA prebiotic framework publication or FSSAI fortification mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Baobab Ingredient Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Global Natural Gum Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Calcium Caseinate Market
Ingredients
Honey Powder Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Dry Molasses Products Market
Ingredients
North America Feed Yeast Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Soy Protein Hydrolysate Market