
 Instant Tea Premixes Market | 2026-2036
Instant Tea Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Tea Premixes Market Foresight
Southeast Asian contract manufacturers is broadening output capacity for spray-dried tea extracts to serve regional brand owners. Nestle leverages its soluble beverage infrastructure across multiple continents to maintain cost advantages in powder formulations. Unilever sustains brand recognition in black tea segments through established distribution networks in South Asia and Africa. Tata Consumer Products anchors its position in masala tea premixes through deep retail penetration in Indian metro clusters.
Instant tea premixes comprise dehydrated tea extracts combined with sweeteners, dairy or non-dairy creamers, and flavoring agents that reconstitute in hot or cold water to produce ready-to-consume beverages. Spray-drying and freeze-drying processes preserve volatile aromatic compounds while enabling shelf stability exceeding twelve months at ambient temperatures. Powder formulations occupy the largest volume share due to lower logistics costs and extended shelf life compared to liquid concentrates. Health-conscious consumers are shifting demand toward green tea and herbal variants with reduced sugar profiles. Ready-to-drink formats command premium positioning in convenience channels though powder sachets dominate household procurement across price-sensitive markets.
FSSAI in India mandates nutritional labeling and additive disclosures for all packaged beverage premixes, pushing reformulation toward cleaner ingredient decks. The FDA enforces GRAS status for flavor compounds and creamer additives entering US commerce, while EFSA evaluates health claims on functional tea extracts within European markets. Stakeholders must track evolving sweetener regulations across major jurisdictions as sugar taxation spreads and natural alternative approvals fragment. Procurement and R&D teams should prioritize flexible formulation platforms capable of rapid adaptation to divergent national standards.
Market Dynamics
Corporate foodservice procurement of single-serve sachets across India and Southeast Asia is compressing production cycles and forcing contract manufacturers to reconfigure spray-drying capacity toward smaller batch sizes with faster turnaround times.
Growth Catalysts
- FSSAI Labeling Mandates:India's tightening nutritional disclosure requirements for packaged beverages are accelerating reformulation toward cleaner ingredient decks, opening premium positioning for compliant domestic brands.
- Green Tea Extract Technology:Cold-water-soluble green tea variants developed through modified spray-drying protocols are capturing health-conscious consumers in East Asian urban markets previously dominated by black tea formulations.
- Southeast Asian Contract Manufacturing:Regional spray-dried tea extract capacity expansion is enabling local brand owners to reduce import dependence and shorten supply chains for foodservice distribution.
Market Restraints
- Input Cost Volatility:Dairy and non-dairy creamer prices fluctuate with palm oil and milk powder commodity cycles, compressing margin predictability for powder formulation producers.
- Supply Concentration Risk:Spray-drying equipment and technical expertise cluster among a limited set of processing hubs in India and Vietnam, creating bottleneck vulnerability for regional brand expansion.
- Technical Shelf-Life Limitation:Volatile aromatic compound degradation in green tea extracts limits ambient stability to 8-10 months versus 12+ months for black tea variants, constraining distribution radius for premium products.
Strategic Opportunities
- Vietnam Foodservice Penetration:Underdeveloped corporate catering channels in Vietnamese urban centers present first-mover advantage for single-serve sachet suppliers establishing direct foodservice relationships.
- Functional Extract Convergence:Combination formulations merging tea polyphenols with adaptogenic botanicals are creating new premium segments in South Korean and Japanese convenience retail channels.
- E-Commerce Direct Distribution:Platform-native brands bypassing traditional wholesale layers are capturing household procurement in Indian tier-2 cities through subscription-based powder sachet delivery.
Industry Challenges
- Spray-Drying Technical Talent Scarcity:Specialized process engineers capable of optimizing volatile compound retention are concentrated among legacy equipment operators, constraining new facility commissioning timelines.
- Multi-Jurisdiction Sweetener Compliance:Divergent approval statuses for stevia glycosides, monk fruit extracts, and sugar alcohols across FSSAI, FDA, and EFSA jurisdictions force parallel formulation tracks and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Tea Premixes Market |
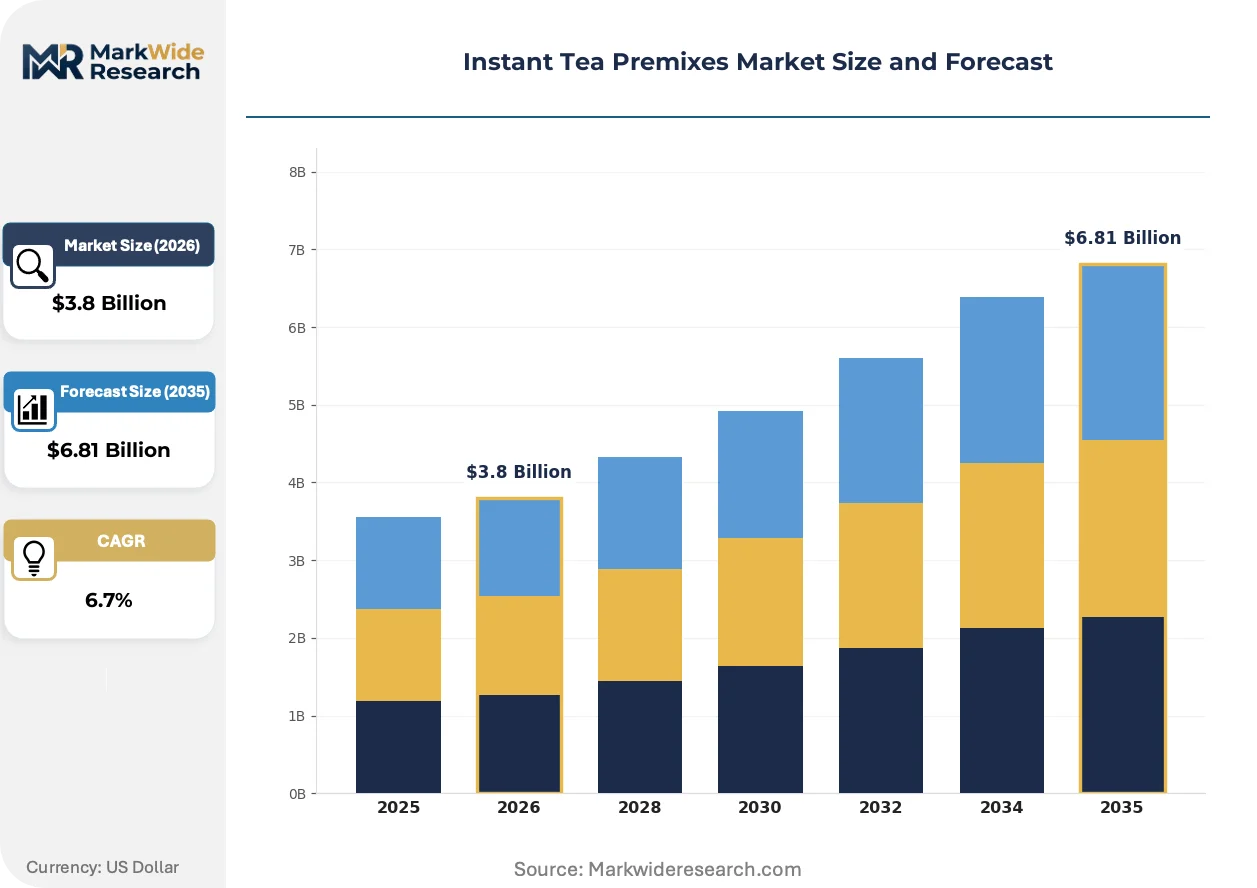
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Masala Tea Form: Powder, Liquid, Sachet, Ready-to-Drink Target Audience: Health Conscious, Convenience Seekers, Traditionalists, Millennials Flavor Profile: Citrus, Spiced, Mint, Vanilla |
| Companies Covered | Nestle, Unilever, PepsiCo, Ito En Ltd, Wagh Bakri Tea Group, Tata Consumer Products, The Coca-Cola Company, Starbucks, Keurig Green Mountain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Tea Premixes Market Shifts & Advancements
Reformulation around clean-label positioning and cold-water solubility is compressing traditional production cycles while opening new channel access for instant tea premix suppliers.
Micro-encapsulation technology for volatile aromatic preservation is expanding into premium green tea and herbal variant production. Specialty tea processors in Japan and South Korea are adopting these systems to extend ambient shelf life without synthetic stabilizers. The technology is expanding into export-oriented production lines serving European retail private-label contracts.
India's FSSAI implementation of stricter additive disclosure requirements is forcing ingredient list simplification across domestic packaged beverage premixes. Manufacturers are removing artificial flavor carriers and switching to natural spray-dried fruit extracts. Masala tea premix producers serving Indian metro retail clusters face the steepest reformulation timelines due to complex spice extract labeling.
Corporate procurement departments in Southeast Asian technology parks are consolidating beverage supplier relationships toward single-vendor contracts covering coffee, tea, and alternative premix categories. Foodservice distributors serving these campuses are unbundling equipment leasing from product supply to compete on total cost metrics. This pattern is most visible in Bangalore, Singapore, and Ho Chi Minh City commercial district catering contracts.
Instant Tea Premixes Market Segmentation
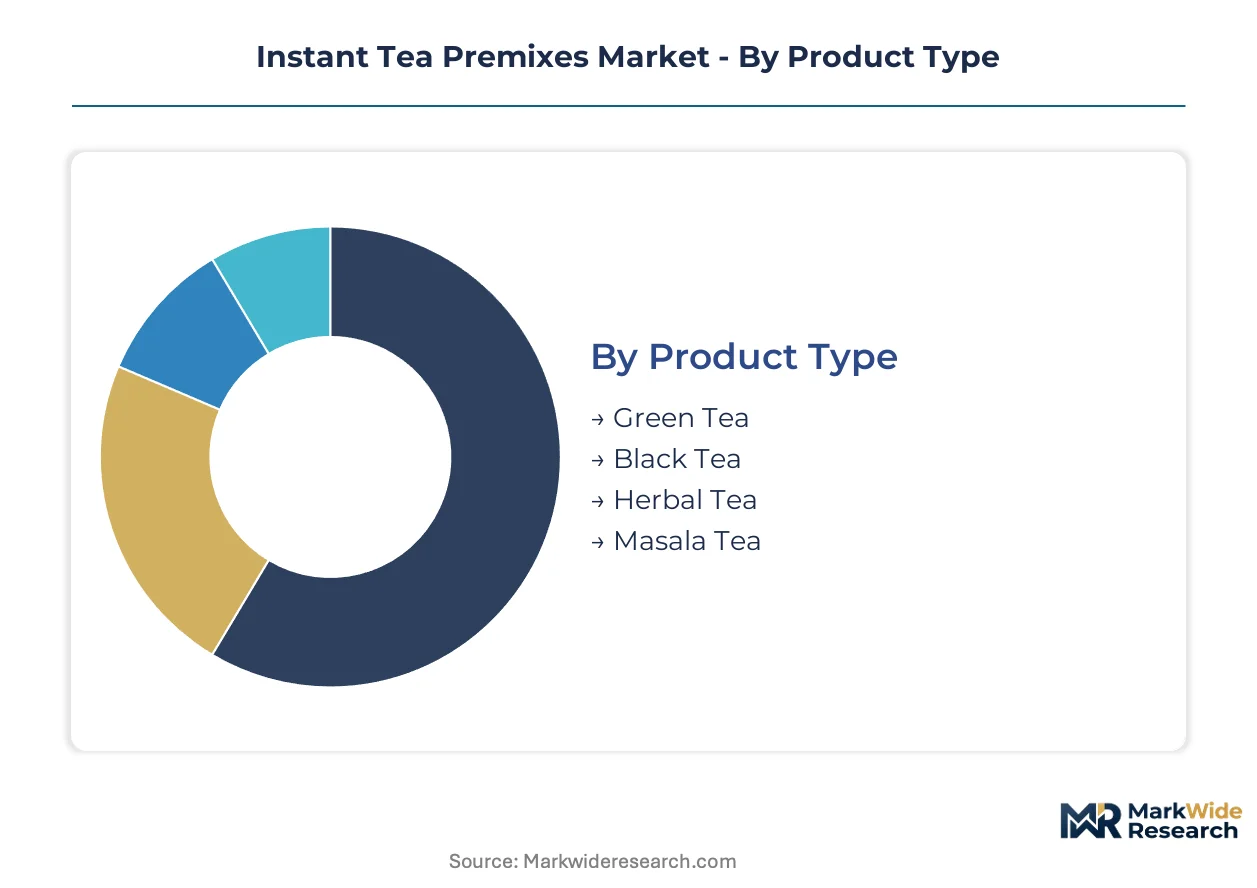
Instant tea premix segmentation reveals divergent capital requirements across production technologies and formulation complexity. Manufacturers prioritize capacity allocation based on spray-drying infrastructure utilization and shelf-stability specifications.
Product Type:
Black tea premixes demand the heaviest upfront investment in spray-drying equipment due to high-volume throughput requirements and volatile aromatic compound preservation systems.
- Black Tea:Standard spray-drying protocols achieve 12+ month ambient stability through optimized temperature profiles. Urban Indian households and Southeast Asian corporate foodservice channels absorb the majority of black tea premix volume, driven by established consumption habits and cost-sensitive procurement patterns.
- Green Tea:Modified low-temperature spray-drying or freeze-drying preserves catechin integrity and volatile aromatics. East Asian urban markets—particularly South Korean and Japanese convenience retail—concentrate green tea premix demand as health-conscious consumers shift from traditional black tea formulations.
- Herbal Tea:Botanical extract sourcing and custom drying cycles elevate per-unit processing costs. Chamomile, rooibos, and hibiscus variants target European wellness-oriented retail channels with premium positioning.
- Masala Tea:Complex spice extract integration requires specialized blending equipment and FSSAI-compliant additive disclosure systems. Indian metro retail clusters sustain masala tea premix demand through deep cultural penetration.
Black tea premixes absorb the bulk of installed capacity; green tea variants are expanding most quickly.
Form:
Cost tier differentiation separates powder formulations at economy scale from ready-to-drink liquids commanding premium positioning.
- Powder:Lowest logistics burden and extended shelf stability dominate household procurement across price-sensitive Indian and Southeast Asian markets. Bulk packaging for foodservice and single-serve sachets for retail constitute parallel production lines.
- Sachet:Single-serve powder packaging targets corporate foodservice procurement in Bangalore, Singapore, and Ho Chi Minh City technology parks. Rapid turnaround requirements compress production cycles for contract manufacturers.
- Liquid:Concentrated extracts require refrigerated distribution infrastructure and shorter shelf windows. Premium positioning in convenience channels offsets higher per-unit logistics costs.
- Ready-to-Drink:Fully reconstituted beverages command the highest price tier through immediate consumption utility. Japanese and South Korean convenience retail channels sustain ready-to-drink tea premix penetration.
Powder formulations anchor volume production; sachet configurations are climbing the fastest as foodservice procurement consolidates.
Target Audience:
Customer type segmentation aligns formulation complexity with willingness-to-pay thresholds and channel access patterns.
- Health Conscious:Zero-sugar and adaptogenic-infused variants target South Korean and Japanese consumers seeking functional beverage benefits. Polyphenol retention specifications drive premium ingredient sourcing.
- Convenience Seekers:Cold-water solubility and rapid dissolution properties prioritize speed over sensory complexity. Urban Indian professionals and Southeast Asian corporate campuses sustain this segment.
- Traditionalists:Authentic flavor profiles replicating brewed tea preparation methods dominate Indian household procurement. Masala and strong black tea formulations align with established taste preferences.
- Millennials:Experimental flavor combinations and Instagram-compatible packaging drive trial purchases in tier-2 Indian cities through e-commerce subscription models.
Traditionalists absorb the bulk of installed capacity; health-conscious consumers are gaining share fastest.
Flavor Profile:
Application-driven segmentation maps flavor innovation to regional palate preferences and seasonal consumption patterns.
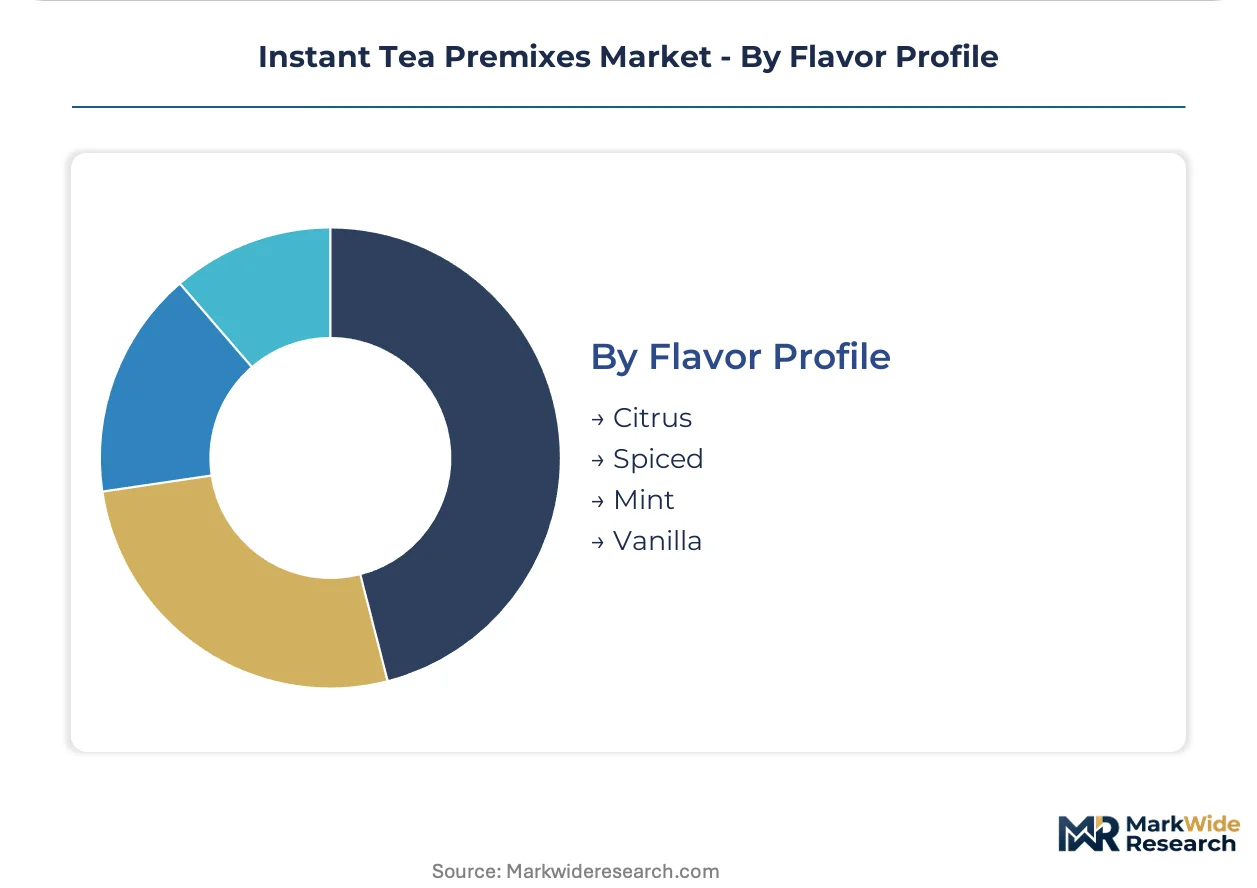
- Spiced:Cardamom, cinnamon, and ginger extracts anchor masala tea formulations for Indian retail and foodservice channels. FSSAI spice labeling mandates complicate ingredient deck simplification efforts.
- Citrus:Lemon and bergamot variants target European private-label contracts and East Asian summer consumption peaks. Natural spray-dried fruit extracts replace artificial flavor carriers under clean-label pressure.
- Mint:Refreshment-positioned variants capture Middle Eastern and North African market entry opportunities. Spearmint and peppermint extracts require specialized volatile compound stabilization.
- Vanilla:Creamy flavor profiles complement non-dairy creamer bases in premium positioning strategies. European and North American retail channels sustain vanilla-flavored premix demand.
Spiced formulations absorb the bulk of installed capacity; citrus variants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assam tea estates and Kerala spice gardens supply the raw material base that anchors South Asian premix manufacturing. Spray-dried extract processors cluster near these source regions to minimize leaf-to-powder transit times.
India
Urban households in Mumbai and Delhi drive black tea and masala premix consumption through deep retail penetration. FSSAI mandates additive disclosure and nutritional labeling for all packaged beverages, forcing ingredient deck simplification. Karnataka's Bangalore technology parks consolidate corporate foodservice procurement toward single-vendor tea and coffee contracts.
Vietnam
Corporate catering channels in Ho Chi Minh City commercial districts absorb growing single-serve sachet volumes from technology park tenants. The country's national food safety authority enforces packaged beverage standards aligned with ASEAN harmonization protocols. Contract manufacturers in Binh Duong province expand spray-drying capacity to serve regional brand owners reducing import dependence.
Japan
Convenience retail chains in Tokyo and Osaka sustain premium ready-to-drink and cold-water-soluble green tea premix demand. METI oversees functional food claims evaluation for polyphenol-forward formulations targeting health-conscious consumers. Specialty processors in Shizuoka prefecture deploy micro-encapsulation systems to preserve volatile aromatics in export-oriented production lines.
South Korea
Seoul's convenience retail channels concentrate demand for adaptogenic-infused tea formulations merging botanical extracts with green tea polyphenols. MFDS regulates health claims on functional beverages containing standardized catechin content. Busan-Ulsan industrial corridors host spray-drying facilities serving both domestic convenience chains and European private-label contracts.
Singapore
Technology park catering contracts in One-North and Changi Business Park consolidate procurement across coffee, tea, and alternative beverage categories. The Singapore Food Agency enforces strict additive approval lists for imported premix formulations. Regional distributors unbundle equipment leasing from product supply to compete on total cost metrics for corporate accounts.
Instant Tea Premixes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional extract convergence and direct-to-consumer subscription models. The vendor base spans multinational beverage conglomerates with soluble infrastructure, regional tea processors with spice integration expertise, and platform-native brands bypassing wholesale layers. Three archetypes dominate: diversified multinationals leveraging cross-category manufacturing scale, regional specialists commanding distribution depth in cultural tea markets, and digital-native formulators capturing tier-2 city households through e-commerce channels. Capacity expansion and portfolio diversification toward clean-label positioning constitute the dominant competitive moves.
Within the diversified multinational tier, Nestle and Unilever exemplify scale-driven soluble beverage infrastructure deployment across multiple continents. Tata Consumer Products occupies a position within the regional specialist archetype, anchoring masala tea premix supply through established South Asian distribution networks. Wagh Bakri Tea Group represents the heritage regional processor category with deep penetration in Indian urban retail clusters.
| Leading Market Players |
|---|
| Nestle |
| Unilever |
| PepsiCo |
| Ito En Ltd |
| Wagh Bakri Tea Group |
| Tata Consumer Products |
| The Coca-Cola Company |
| Starbucks |
| Keurig Green Mountain |
| Others |
Supply & Pricing Matrix
Palm oil futures and milk powder commodity benchmarks cascade through spray-dried tea extract production into three distinct pricing tiers, with contract manufacturers in India and Vietnam absorbing volatility while brand owners push cost compression downstream into foodservice procurement channels.
Pricing Analysis
Equipment-leasing unbundling from product supply is reshaping corporate foodservice contracts in Bangalore and Singapore technology parks. Three-tier pricing structure across premium, standard, and economy levels separates micro-encapsulated green tea extracts from conventional black tea powders and bulk masala formulations. Pricing pressure stems from FSSAI-mandated reformulation costs accelerating ingredient deck simplification. Price-sensitive household procurement in Indian tier-2 cities anchors economy-tier volume, while health-conscious consumers in Seoul and Tokyo convenience channels absorb premium positioning.
Supply Chain Analysis
India's phased domestic-content requirements for packaged beverage manufacturing are redirecting spice extract sourcing toward Kerala-based processors compliant with FSSAI additive disclosure mandates. Spray-drying equipment and technical expertise cluster in India, Vietnam, and South Korea, with Assam tea estates and Kerala spice gardens feeding regional processing hubs. Raw material dependencies center on tea leaf supply contracts, palm oil-derived non-dairy creamers, and natural sweetener alternatives. Single-source vulnerability concentrates in specialized volatile compound retention engineering. Distribution runs through foodservice distributors unbundling equipment leases and e-commerce platforms penetrating tier-2 Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI labeling mandates in India erect a compliance moat that favors established domestic brands with reformulation infrastructure, while fragmenting margin structures for import-dependent regional players lacking clean-label R&D capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into Assam tea estate sourcing and captive spray-drying capacity expansion in Binh Duong province. Threat from platform-native subscription brands bypassing wholesale layers demands channel control investment. Certification leverage in FSSAI-compliant additive disclosure systems protects metro retail shelf access against reformulation-lagged competitors. For New Entrants and Emerging Players: MFDS functional food claims evaluation in South Korea opens a window for adaptogenic-infused tea formulations merging botanical extracts with standardized catechin content. White-space concentration sits in Vietnamese corporate catering channels and European private-label micro-encapsulation contracts. Direct-to-consumer e-commerce penetration in Indian tier-2 cities offers lowest customer acquisition cost against established retail networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional spray-drying specialists with FSSAI-compliant infrastructure in Indian metro clusters over asset-light brand marketers exposed to input cost volatility. Long-term viability hinges on clean-label reformulation capability and foodservice channel lock-in. Signal to watch is consolidation velocity among Vietnamese contract manufacturers as ASEAN harmonization protocols tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSSAI-compliant ingredient deck simplification secures metro retail shelf access in Mumbai and Delhi. |
| Spray-Drying Capacity Expansion | Binh Duong province facility buildout reduces import dependence for Vietnamese brand owners. |
| Micro-Encapsulation Technology Adoption | Shizuoka prefecture processors preserve volatile aromatics for European private-label export contracts. |
| E-Commerce Direct Distribution | Platform-native subscription models bypass wholesale layers in Indian tier-2 city household procurement. |
| Functional Extract Convergence | Adaptogenic botanical integration captures premium positioning in Seoul convenience retail channels. |
Research Methodology
Multi-period observation of spray-drying capacity utilization rates and FSSAI compliance timelines anchored the trend analysis, supplemented by interviews with contract manufacturing plant managers, brand owner procurement leads, foodservice distribution channel heads, and specialty tea R&D directors. Secondary validation drew from customs trade data on spray-dried extract shipments, FSSAI packaged beverage filings, ASEAN food safety harmonization protocols, and retail audit data from Indian metro clusters. Bottom-up segment sizing triangulated against top-down category spend estimates.
Segment-weighting across product type, form configuration, target audience, and flavor profile dimensions shaped the analytical framework across the analysis window. CAGRs derived from volume trajectory modeling incorporating spray-drying batch size compression trends and cold-water-solubility technology adoption curves. Forecast inputs included corporate foodservice procurement consolidation patterns in Southeast Asian technology parks and green tea extract shelf-stability limitation constraints.
The model assumes a particular technology adoption path; alternative pathways for micro-encapsulation scale-up would alter the outlook for premium green tea variant penetration. Forecasts reflect assumptions on FSSAI enforcement consistency and ASEAN regulatory harmonization velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Smart Tea Set Market
Tea
Pyramid Tea Bags Market
Tea
Global Fruit Tea Market
Tea
Asia-Pacific Tea Market
Tea
Kombucha Tea Market
Tea
South America Tea Market
Tea
Pu-Erh Tea Market
Tea
Detox Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Matcha Market
Tea
Probiotic Tea Market
Tea
Europe Green Tea Market
Tea
Green Tea Leaves Market
Tea
Africa Tea Market
Tea
North America Tea Market
Tea
Tea Essence Market