
 Vietnam Pangasius (Basa) Market | 2026-2036
Vietnam Pangasius (Basa) Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Pangasius (Basa) Market Intelligence
Aftermarket value-added processing is rewriting margin distribution across the Vietnam pangasius value chain. Vinh Hoan Corporation leverages captive feed mills and collagen extraction facilities to capture downstream margin pools. GODACO sustains export volume leadership through BRC-certified processing lines serving EU retail private label. Anvifish Joint-Stock Company anchors Mekong Delta sourcing networks with vertically integrated hatch-to-processing operations.
Vietnam pangasius denotes a freshwater catfish species farmed intensively in the Mekong Delta, yielding white-fleshed fillets with protein content near 15% and fat below 8%, primarily supplying global whitefish demand as a cost-competitive substitute for cod and tilapia. Frozen product dominates export value given extended shelf life and containerized logistics compatibility, while processed segments including breaded and marinated portions attract premium positioning in European retail. Food service channel volumes recover fastest as Horeca operators reformulate menus around stable-cost whitefish alternatives.
Vietnam's Ministry of Agriculture and Rural Development enforces antibiotic residue limits through Circular 02/2022/TT-BNNPTNT, while EU REACH and EFSA standards govern import eligibility for frozen fillets. The country's national fisheries regulator coordinates with BIS-equivalent quality agencies to align aquaculture practices with destination market access requirements. Stakeholders must monitor evolving EU deforestation regulation traceability mandates and their application to Mekong Delta pond origin documentation.
Market Dynamics
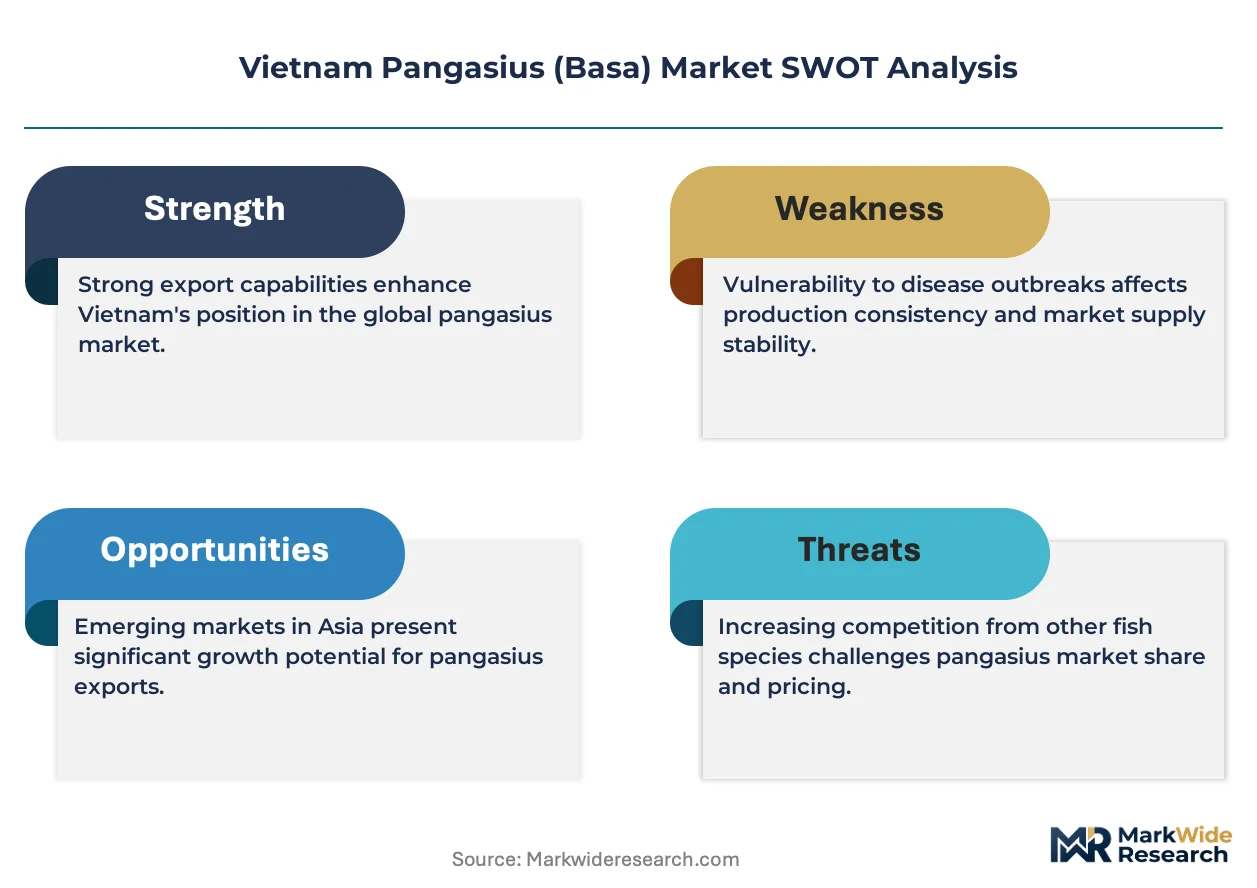
Antibiotic residue enforcement under Circular 02/2022/TT-BNNPTNT is compressing farm-gate supply while downstream IQF processing capacity expands to meet EU foodservice specifications. This regulatory tightening is redrawing competitive advantage toward vertically integrated operators with captive laboratory testing and hatchery control.
Growth Catalysts
- EU Deforestation Regulation traceability mandates:Mekong Delta pond origin documentation requirements are accelerating blockchain-based supply chain investments among export-oriented processors seeking continued market access.
- Whitefish substitution in European Horeca:Foodservice operators in Germany, Netherlands, and Belgium are reformulating menus around frozen pangasius fillets as cod supply volatility persists.
- Collagen extraction from byproducts:Downstream biotech applications in cosmetics and nutraceuticals are creating margin capture opportunities for processors with integrated rendering facilities.
Market Restraints
- Feed input cost volatility:Soybean meal and fish oil price swings compress farm-level margins and destabilize contract pricing for independent growers lacking forward procurement.
- Supply concentration in Mekong Delta:Pond farming clusters in An Giang, Dong Thap, and Vinh Long provinces face simultaneous climate and disease risks with limited geographic diversification.
- EFSA antibiotic residue thresholds:European import rejection protocols for enrofloxacin and chloramphenicol residues create non-tariff barriers that smaller exporters struggle to navigate.
Strategic Opportunities
- China tier-two city penetration:Horeca channels in Chengdu, Hangzhou, and Wuhan show underdeveloped pangasius adoption compared to saturated Shanghai and Beijing markets.
- Marinated and breaded portion innovation:Value-added retail SKUs targeting European supermarket private label are commanding price premiums over commodity frozen fillets.
- Vietnam Ministry of Agriculture quality certification incentives:VietGAP and GlobalGAP accreditation subsidies are lowering compliance costs for mid-scale farms seeking export eligibility.
Industry Challenges
- BRC and IFS certification timelines:Smaller processing facilities face 12-18 month compliance windows to secure European retail qualification, requiring capital outlays for line renovations.
- Broodstock genetic management:Hatchery operators struggle with inbreeding depression and disease resistance traits, constraining fingerling quality consistency across the Delta.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Pangasius (Basa) Market |
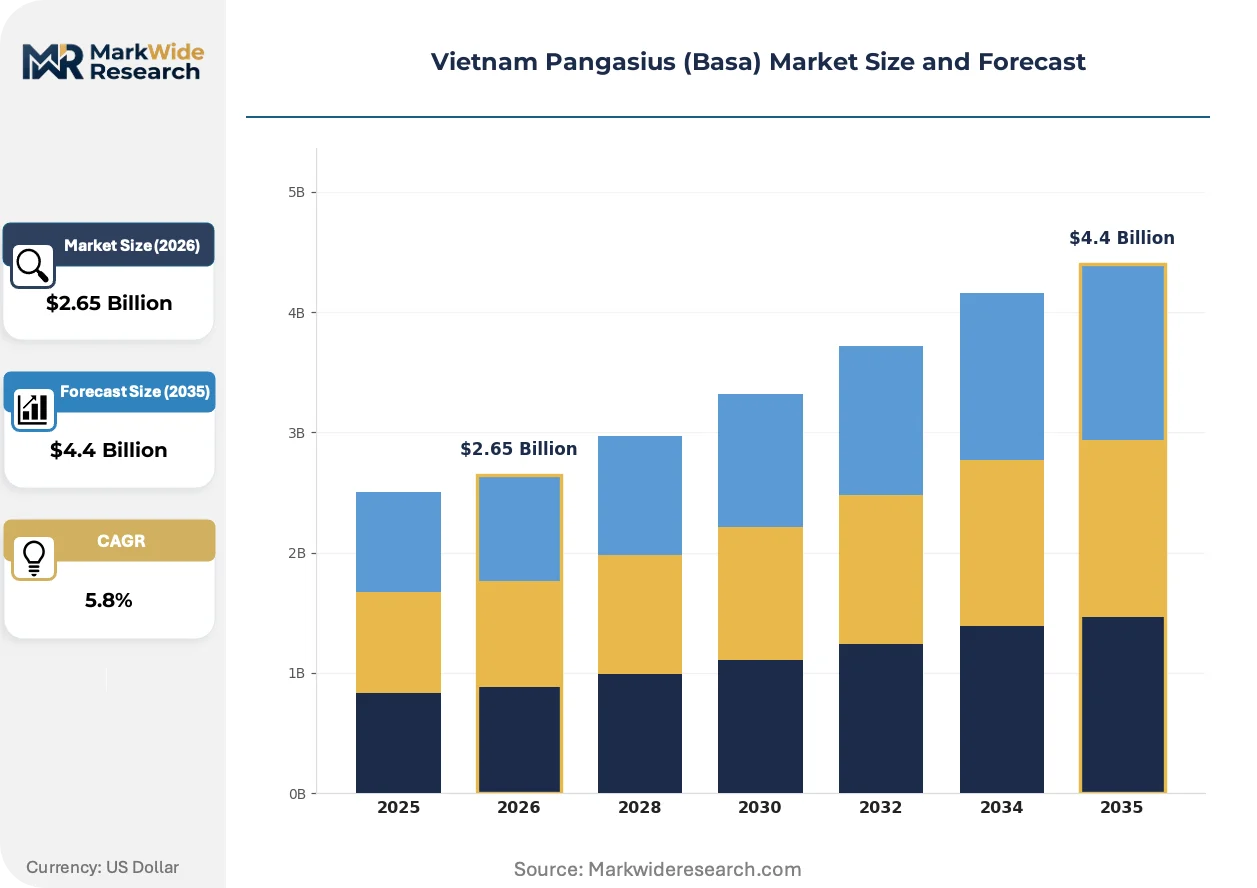
| Market Size in 2026 | $2.65 Billion |
| Market Size in 2035 | $4.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Dried, Processed Distribution Channel: Retail, Wholesale, Food Service, Export End User: Consumer, Restaurants, Supermarkets, Food Manufacturers Packaging Type: Vacuum Sealed, Canned, Bulk, Tray |
| Companies Covered | Anvifish Joint-Stock Company, Can Tho Import Export Seafood JSC, Vinh Hoan Corporation, Go Dang Joint Stock Company (GODACO), Cuu Long Seafood Import and Export JSC, Bien Dong Seafood Company Limited, Aquatex Ben Tre, Dai Thanh Seafood, Van Duc Tien Giang, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Pangasius (Basa) Market Strategic Shifts & Innovations
Processing technology and regulatory traceability systems are converging to transform how pangasius moves from Mekong Delta ponds to European retail freezers. These shifts favor capital-intensive operators while squeezing fragmented farm-gate suppliers.
Recirculating aquaculture system (RAS) pilot installations are emerging as biosecurity buffers against riverine disease pressure. Vinh Hoan and several Mekong Delta cooperatives are trialing closed-loop tank systems for broodstock and early grow-out phases. RAS adoption is migrating from experimental hatchery applications toward commercial-scale grow-out as land and water access permits tighten around traditional pond operations.
Vietnam's Ministry of Agriculture and Rural Development is tightening antibiotic residue surveillance through expanded laboratory testing protocols and farm-level inspection frequency. This enforcement is disqualifying non-compliant suppliers from export eligibility lists while concentrating procurement among certified large-scale operations. Smallholder farms in Dong Thap province are responding by forming cooperative quality assurance pools to share testing costs and traceability infrastructure.
European foodservice distributors are consolidating procurement through direct processor relationships, bypassing traditional import trading houses. German and Dutch Horeca purchasing groups now negotiate annual volume contracts with BRC-certified Vietnamese processors for IQF portion specifications. This channel compression is most visible in the Netherlands, where wholesale seafood traders have lost substantial pangasius volume to direct-import restaurant chains seeking cost transparency and supply security.
Vietnam Pangasius (Basa) Market Segmentation
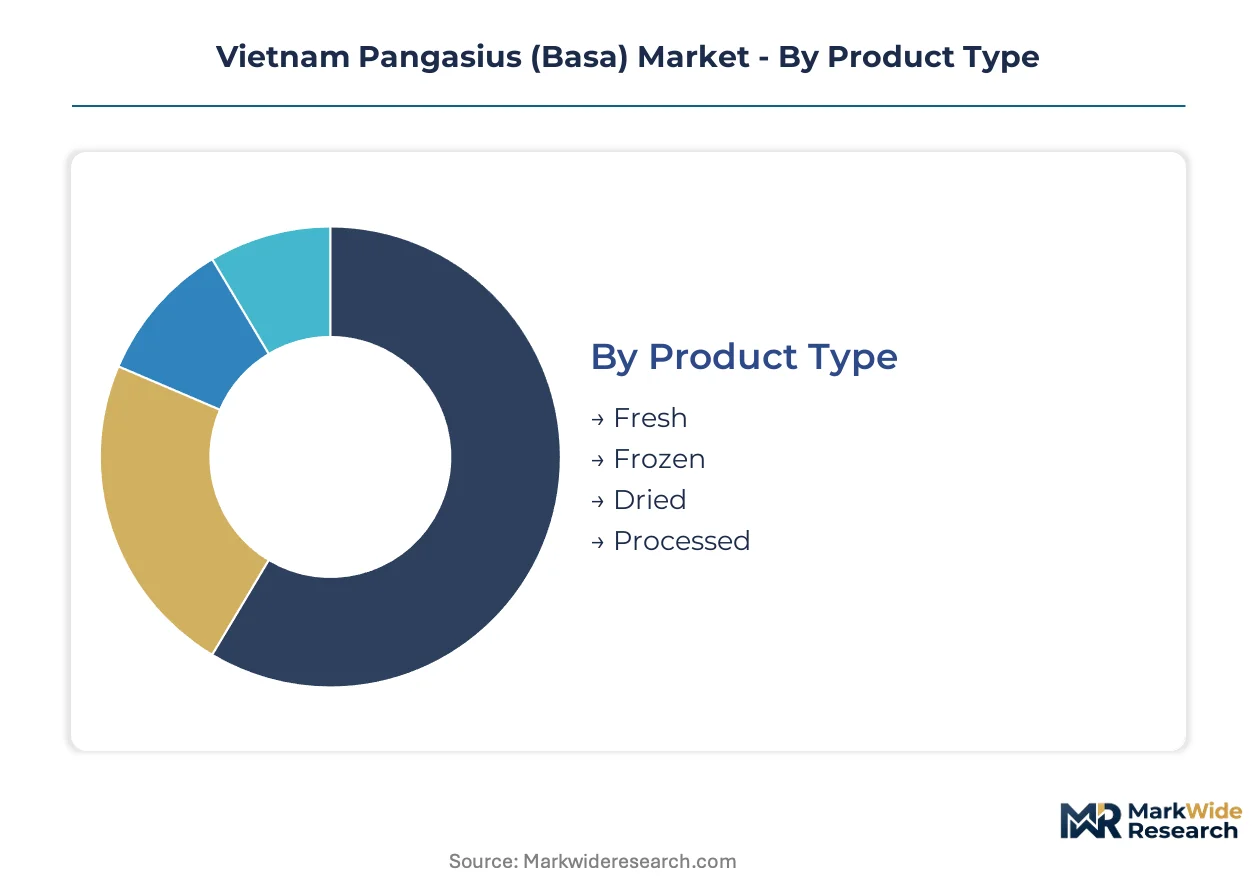
Vietnam pangasius flows through distinct product, channel, and packaging configurations that determine margin capture and regulatory exposure. Each segmentation dimension carries strategic weight for processors balancing EU foodservice specifications against Asian retail price sensitivity.
Product Type:
Fresh fillets serve premium same-day consumption in domestic Vietnamese markets and cross-border Chinese wet markets, while frozen blocks dominate export economics through extended shelf stability and containerized logistics efficiency.
- Frozen:IQF fillets and interleaved blocks constitute the export revenue backbone, with European Horeca operators specifying 170-220g portion cuts for menu standardization. German and Dutch foodservice distributors now contract directly with BRC-certified Vietnamese processors for annual volume commitments, bypassing traditional trading houses.
- Processed:Breaded, marinated, and glazed portions command retail premium positioning in European supermarket private label, with collagen extraction from byproducts creating parallel biotech revenue streams for integrated operators like Vinh Hoan.
- Fresh:Whole fish and fillets move through Mekong Delta wet markets and cross-border channels to Guangxi and Yunnan provinces, where same-day freshness determines price premiums over frozen alternatives.
- Dried:Traditional sun-dried and mechanically dehydrated products serve ethnic Vietnamese diaspora markets in North America and Australia, with limited volume growth relative to frozen export trajectories.
The dominant share belongs to Frozen, while Processed is closing the gap fastest through value-added SKU expansion in European retail.
Distribution Channel:
Channel selection dictates working capital intensity and traceability infrastructure requirements, with direct processor relationships displacing traditional importer intermediaries in European foodservice procurement.
- Export:Containerized frozen fillet shipments to EU, US, and Chinese markets require BRC, IFS, or equivalent certification for retail eligibility, with blockchain traceability investments accelerating under EU Deforestation Regulation mandates for Mekong Delta pond origin documentation.
- Food Service:Horeca operators in Germany, Netherlands, and Belgium reformulate menus around pangasius as cod supply volatility persists, with annual volume contracts replacing spot market purchasing for cost transparency.
- Retail:Supermarket chains in China's tier-one cities stock IQF portions for home preparation, while European retail demands marinated and breaded SKUs with extended ingredient deck differentiation.
- Wholesale:Traditional trading houses in Ho Chi Minh City and Can Tho aggregate farm-gate supply for domestic processors and regional re-exporters, facing margin compression as direct processor relationships expand.
Export channels absorb the largest volume, though Food Service is expanding most quickly through Horeca menu reformulation.
End User:
End-user differentiation centers on specification stringency and price elasticity, with food manufacturers imposing the most rigorous technical requirements for further processing inputs.
- Restaurants:European Horeca operators specify consistent portion weights and thaw yield rates for kitchen efficiency, with German casual dining chains leading volume procurement through direct Vietnamese processor contracts.
- Supermarkets:Retail buyers demand private label value-added products with clean-label ingredient positioning, requiring processors to maintain separate production lines for marinated and breaded SKUs.
- Food Manufacturers:Surimi and fish cake producers in Japan and South Korea import frozen pangasius mince for reprocessing, with texture and protein content specifications exceeding standard fillet grades.
- Consumer:Direct-to-consumer e-commerce channels in Vietnamese urban centers and Chinese tier-one cities are emerging for premium fresh fillet delivery, though volumes remain marginal against institutional procurement.
Restaurants command the largest procurement volume, while Food Manufacturers are gaining share fastest through Asian surimi and reprocessing demand.
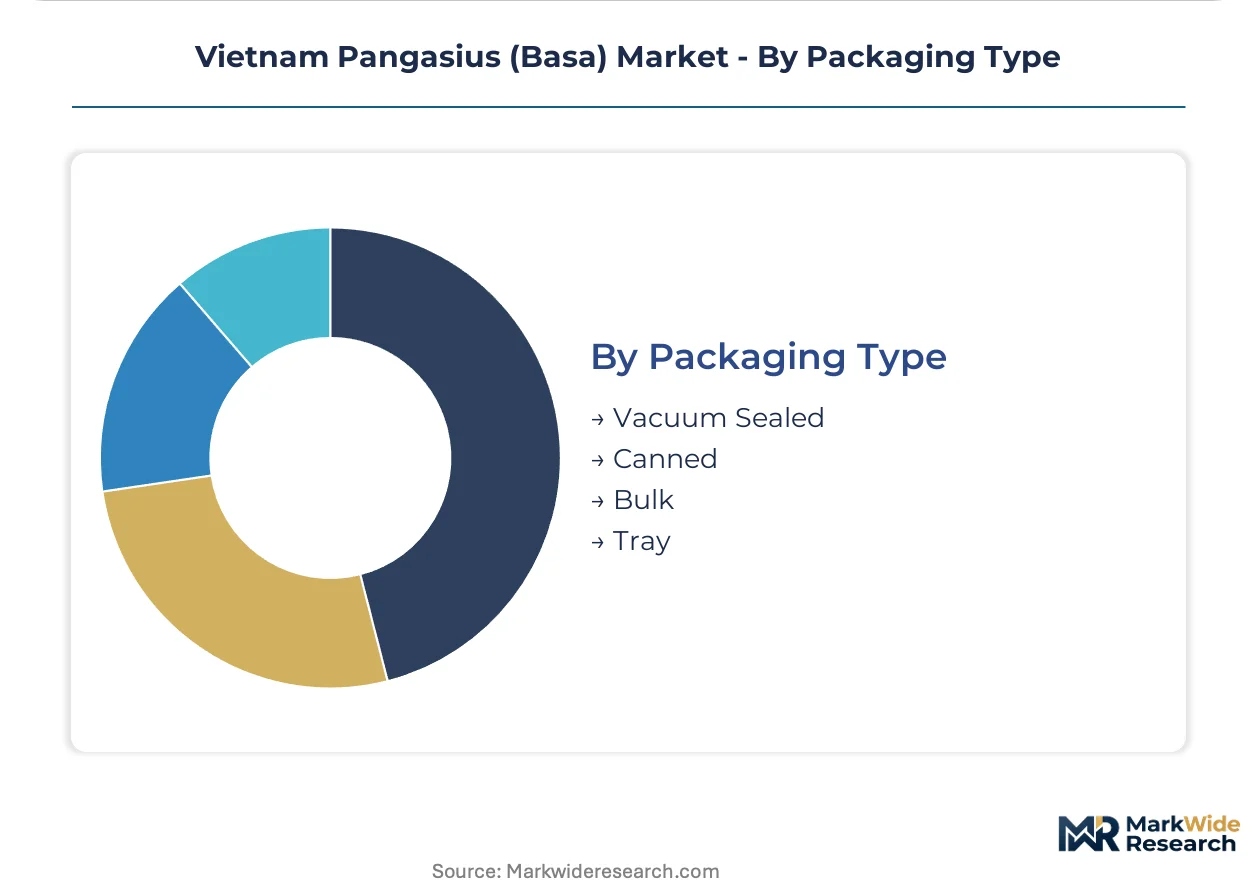
Packaging Type:
Packaging selection correlates with shelf-life requirements and retail presentation standards, with vacuum technology investments separating export-qualified processors from domestic-market suppliers.
- Vacuum Sealed:Modified atmosphere packaging extends frozen fillet shelf life to 24 months, meeting EU retail requirements for oxygen exclusion and drip loss minimization during thawing.
- Tray:Retail-ready foam or paperboard trays with overwrap film serve European supermarket fresh counters and Chinese tier-one city retail, with presentation standards driving line automation investments.
- Bulk:10kg and 20kg carton blocks supply foodservice distributors and food manufacturers for further portioning or reprocessing, with least packaging cost per kilogram but highest handling requirements.
- Canned:Heat-sterilized products in brine or sauce serve emergency food programs and specific ethnic market niches, with limited commercial significance relative to frozen export economics.
Vacuum Sealed holds the dominant position, while Tray packaging is climbing the fastest through retail-ready SKU expansion in European and Chinese markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European foodservice buyers exhibit the lowest price elasticity for pangasius fillets, accepting premium specifications for consistent supply, while Chinese wet market traders remain highly sensitive to daily price fluctuations. This demand-elasticity contrast shapes procurement patterns across destination markets.
China
Horeca operators in Shanghai and Beijing specify IQF portion cuts for menu standardization, with tier-two cities in Sichuan and Zhejiang provinces showing underdeveloped adoption. SAMR enforces food safety standards for imported aquatic products through GB standards compliance. Processing clusters in Guangxi province handle cross-border fresh fillet traffic from Mekong Delta farms.
Germany
Casual dining chains reformulate menus around pangasius as cod supply volatility persists, with direct processor contracts replacing spot market purchasing. EFSA antibiotic residue thresholds govern import eligibility, with enrofloxacin screening protocols creating non-tariff barriers. The Hamburg wholesale seafood hub faces margin compression as restaurant groups import directly from Vietnamese processors.
Netherlands
Foodservice purchasing groups negotiate annual volume contracts for cost transparency, bypassing traditional import trading houses. EU REACH and EFSA standards regulate frozen fillet specifications for Horeca channel entry. Rotterdam container terminals handle consolidated shipments from BRC-certified Mekong Delta processors serving Benelux distribution networks.
United States
Retail private label buyers demand marinated and breaded SKUs with clean-label positioning for supermarket placement. FDA enforces seafood HACCP regulations for imported pangasius fillets. Los Angeles and Seattle cold storage facilities receive containerized shipments for West Coast redistribution.
Belgium
Foodservice distributors consolidate procurement through direct Vietnamese processor relationships, seeking supply security amid whitefish substitution trends. EU Deforestation Regulation traceability mandates accelerate blockchain investments for Mekong Delta pond origin documentation. Antwerp logistics hubs coordinate cross-border distribution to French and German Horeca operators.
Vietnam Pangasius (Basa) Market Key Industry Players
Vertically integrated conglomerates and export-focused processors split the market between captive supply chain control and flexible procurement models. Three strategic archetypes dominate: integrated feed-to-fillet operators with laboratory testing capabilities, BRC-certified processors serving EU retail private label, and cooperative quality assurance pools sharing traceability infrastructure among smallholder farms. Competitive moves center on backward integration into hatchery operations and direct foodservice contract negotiation bypassing trading intermediaries.
Among Mekong Delta-integrated operators, Vinh Hoan Corporation exemplifies the feed mill and collagen extraction archetype, while Go Dang Joint Stock Company (GODACO) represents BRC-certified processing scale for European retail channels. Anvifish Joint-Stock Company anchors hatch-to-processing verticality within cooperative sourcing networks.
| Leading Market Players |
|---|
| Anvifish Joint-Stock Company |
| Can Tho Import Export Seafood JSC |
| Vinh Hoan Corporation |
| Go Dang Joint Stock Company (GODACO) |
| Cuu Long Seafood Import and Export JSC |
| Bien Dong Seafood Company Limited |
| Aquatex Ben Tre |
| Dai Thanh Seafood |
| Van Duc Tien Giang |
| Others |
Cost & Logistics Intelligence
An Giang province anchors Mekong Delta pangasius production capacity, and its pond density dynamics directly shape downstream pricing power for BRC-certified processors negotiating annual volume contracts with European Horeca operators.
Pricing Analysis
After-sales revenue from collagen extraction and byproduct rendering drives lifetime value for integrated operators like Vinh Hoan. Pricing stratifies across premium IQF portions, standard frozen blocks, and economy-grade bulk shipments based on certification tier and portion customization. Pricing pressure stems from soybean meal and fish oil input cost volatility compressing farm-gate margins. Food manufacturers in Japan and South Korea exhibit lowest price sensitivity for surimi-grade mince, while Chinese wet market traders show highest sensitivity to daily spot fluctuations.
Supply Chain Analysis
EU Deforestation Regulation traceability mandates restrict technology flows to Mekong Delta processors lacking blockchain-based pond origin documentation systems. Supply concentrates in Vietnam, with secondary processing clusters in China's Guangxi province handling cross-border fresh fillet traffic. Raw material dependencies center on imported soybean meal, fish oil, and hatchery fingerlings. Single-source vulnerability runs through Mekong Delta pond farming clusters facing simultaneous climate and disease risks. Distribution runs through direct processor relationships with European foodservice purchasing groups, bypassing traditional import trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across tier-two Chinese cities where Horeca pangasius adoption lags saturated Shanghai and Beijing markets, as Sichuan and Zhejiang provincial operators seek stable-cost whitefish alternatives.
For Market Incumbents: Insulate procurement positions by deepening backward integration into hatchery operations and captive feed mill capacity, countering the threat of antibiotic residue enforcement disqualifying non-compliant suppliers from export eligibility lists. Prioritize laboratory testing infrastructure investments to maintain EU market access under EFSA screening protocols.
For New Entrants and Emerging Players: Establish a beachhead in marinated and breaded portion innovation for European supermarket private label, where clean-label ingredient positioning commands premium pricing over commodity frozen fillets. Target cooperative quality assurance pools among Dong Thap smallholder farms to share traceability costs and secure export eligibility.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory tightening under Circular 02/2022/TT-BNNPTNT is disqualifying fragmented suppliers and concentrating procurement among certified large-scale operations. Target vertically integrated processors with captive collagen extraction facilities. Watch EU Deforestation Regulation enforcement timelines as the inflection signal for accelerated blockchain infrastructure investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Backward Integration | Captive fingerling supply secures genetic quality consistency against inbreeding depression risks. |
| Blockchain Traceability Deployment | Pond origin documentation satisfies EU Deforestation Regulation mandates for continued market access. |
| Collagen Extraction Facility Expansion | Byproduct rendering captures downstream margin pools in cosmetics and nutraceutical applications. |
| BRC Certification Line Renovation | Processing line upgrades secure European retail private label eligibility within 12-18 month windows. |
| Direct Foodservice Contract Negotiation | Annual volume commitments with German and Dutch Horeca operators bypass margin-compressed trading intermediaries. |
Research Approach
Initial hypotheses were tested against primary input from Mekong Delta farm operators, BRC-certified processing facility managers, European foodservice procurement directors, and Vietnamese Ministry of Agriculture regulatory officials, and refined through secondary validation against customs export data, EU import rejection protocols, and aquaculture trade association reports. Bottom-up volume modeling triangulated with top-down value chain analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user, and packaging configuration alongside regional regulatory cluster differentiation. CAGRs derived from historical trade flow analysis and forward procurement contract visibility. Forecast inputs incorporated feed input cost indices and EU deforestation compliance timelines.
Sensitivities concentrate around antibiotic residue enforcement intensity, feed commodity price swings, and EU traceability mandate implementation schedules. Forecasts reflect documented assumptions on regulatory stability and climate risk incidence. Material shifts in EFSA screening protocols or Mekong Delta water access permitting would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Frozen and Canned Seafood Market
Seafood
Fish Meal and Fish Oil Market
Seafood
North America Frozen Seafood Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
United States Lobster Market
Seafood
United States Salmon Market
Seafood
United States Plant-Based Seafood Market
Seafood
Japan Lobster Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
GCC Seafood Market
Seafood
Europe Salmon Market
Seafood
Canned Mackerel Market
Seafood
Fish Hydrolysate Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Latin America Salmon Market
Seafood
United Arab Emirates Seafood Market