
 United States Lobster Market | 2026-2036
United States Lobster Market Size, Share, and Industry Trends Forecast 2026-2036
United States Lobster Market Intelligence
Pre-portioned lobster tail packs and modular meal kits is broadening buyer choice beyond traditional whole-live formats. Ready Seafood leverages vertical integration from boat to box to control quality through its Maine-based operations. East Coast Seafood Company sustains geographic dominance through its Mid-Atlantic distribution network. Supreme Lobster differentiates via specialized cold-chain logistics serving white-tablecloth restaurants nationwide.
United States lobster comprises marine crustaceans of the family Nephropidae, primarily Homarus americanus, distinguished by a hard exoskeleton reaching weights up to 20 kilograms, harvested via baited traps from cold North Atlantic waters at depths of 4-200 meters, and valued for its muscular tail and claw meat in premium foodservice and retail channels. Live lobster and lobster tails command the highest margin pools due to perishability premiums and export-grade specifications, while direct-to-consumer channels represent the fastest-growing distribution vector as refrigerated e-commerce logistics mature. Homarus americanus anchors volume leadership through established Gulf of Maine stocks, though product-type diversification into frozen and processed formats is accelerating.
NOAA National Marine Fisheries Service administers the Atlantic Large Whale Take Reduction Plan, modifying trap configurations and seasonal closures to protect endangered North Atlantic right whales, directly constraining gear deployment and harvest windows for Maine and Massachusetts lobstermen. The FDA's Hazard Analysis Critical Control Point rules govern processing facility sanitation and temperature controls, elevating compliance costs for smaller shore-side operators. State-level licensing caps in Maine prevent fleet expansion, entrenching incumbent permit holders. Stakeholders must monitor pending biological opinion revisions and whale-roping mitigation mandates that could trigger additional seasonal area closures.
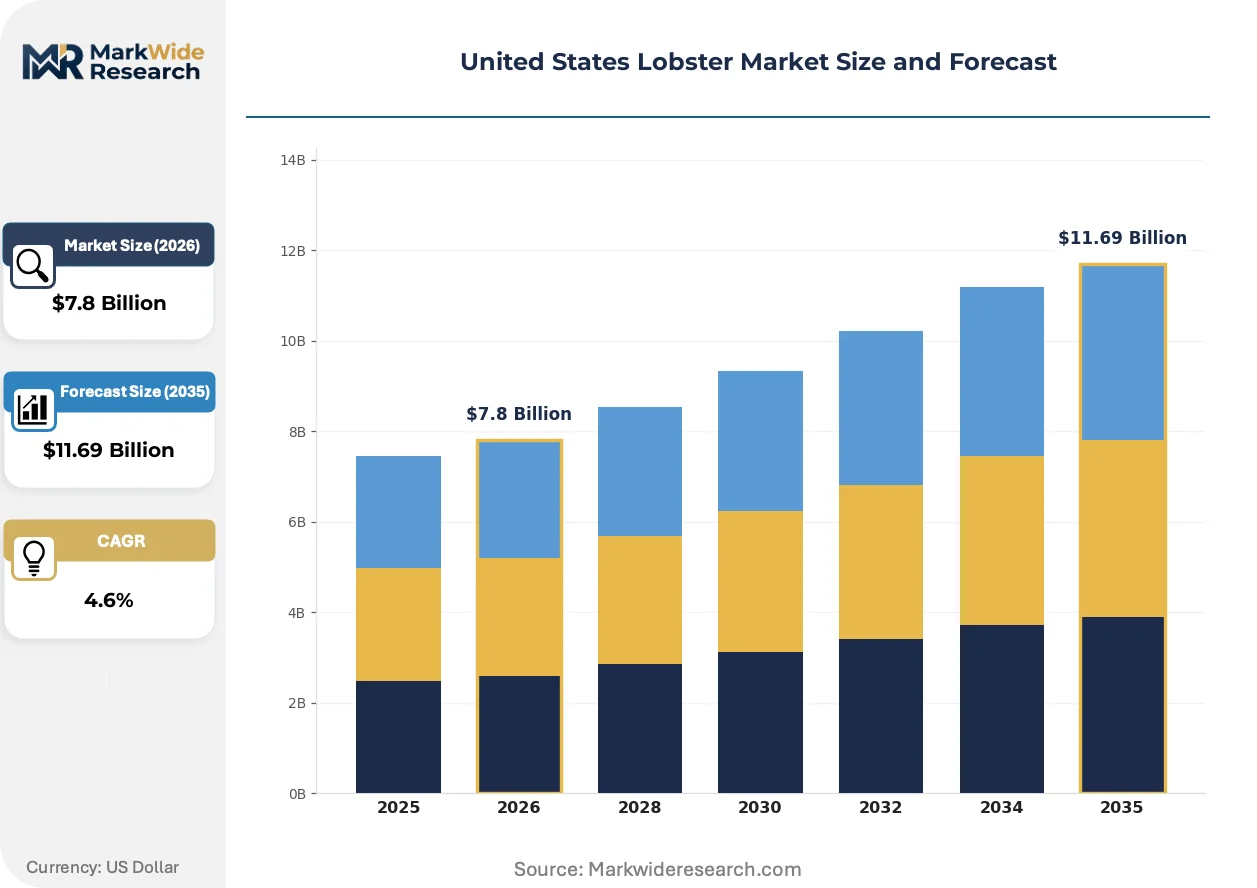
Market Dynamics
The Atlantic Large Whale Take Reduction Plan is compressing harvest windows and forcing rapid gear reconfiguration across the Maine and Massachusetts fleet, reshaping supply availability and landing patterns.
Growth Catalysts
- Live-holding infrastructure expansion:High-end metropolitan restaurants are installing visible tank systems to signal freshness, pulling volume through Portland-to-Ellsworth processing clusters.
- Refrigerated e-commerce logistics maturation:Direct-to-consumer channels are capturing premium perishability markups previously reserved for foodservice distributors.
- NOAA seasonal trap limits:Structured harvest windows are stabilizing dockside pricing volatility and enabling forward contracting by processors.
Market Restraints
- Bait cost volatility:Herring and menhaden quota restrictions in Atlantic waters are inflating trap bait expenditures for independent lobstermen.
- Gulf of Maine stock concentration:Biological productivity gradients concentrate viable harvest zones within a narrow coastal band, amplifying climate sensitivity.
- Right whale mitigation mandates:Pending biological opinion revisions threaten additional seasonal area closures without compensatory harvest efficiency gains.
Strategic Opportunities
- Pre-portioned retail formats:Modular meal kits and tail packs are opening household penetration beyond traditional whole-live occasions.
- Mid-Atlantic distribution corridors:Underdeveloped cold-chain infrastructure between New York and Baltimore offers whitespace for regional hub establishment.
- FDA HACCP compliance differentiation:Smaller operators face elevated sanitation and temperature-control costs, creating acquisition targets for scaled processors.
Industry Challenges
- Multi-generational permit transfer friction:Maine's licensing caps entrench aging permit holders while blocking new entrant recruitment.
- Ropeless gear transition timelines:On-demand retrieval systems require capital deployment and deckhand retraining without guaranteed regulatory relief.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Lobster Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homarus americanus, Homarus gammarus, Lobster Tails, Live Lobster Distribution Channel: Supermarkets, Restaurants, Direct-to-Consumer, Online Retail End User: Households, Seafood Restaurants, Catering Services, Retailers Size: Small, Medium, Large, Jumbo |
| Companies Covered | Boston Lobster Company, Cozy Harbor Seafood Inc., East Coast Seafood Company, New England Lobster Co., Ready Seafood, Southern Maine Lobster Company, Supreme Lobster, Maine Lobster Now, The Fresh Lobster Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Lobster Market Strategic Shifts & Innovations
Digital traceability platforms and alternative bait chemistries are converging with regulatory pressure to reshape harvest operations and supply chain transparency expectations.
Blockchain-enabled catch documentation is converging with wholesale buyer procurement requirements. Major distributors now mandate vessel-level provenance tracking. This convergence is compressing information asymmetry between dockside auctions and end-use pricing.
The NOAA Atlantic Large Whale Take Reduction Plan is mandating weakened rope links and seasonal gear modifications. Lobstermen face truncated deployment windows in Massachusetts waters. Processing facilities are responding by expanding live-holding capacity to buffer supply interruptions.
Restaurant procurement is consolidating toward fewer, larger distributors with captive cold-chain assets. Independent seafood houses are losing access to consistent live supply. This consolidation is most visible in Chicago and San Francisco white-tablecloth markets where tank installation costs deter self-distribution.
United States Lobster Market Segmentation
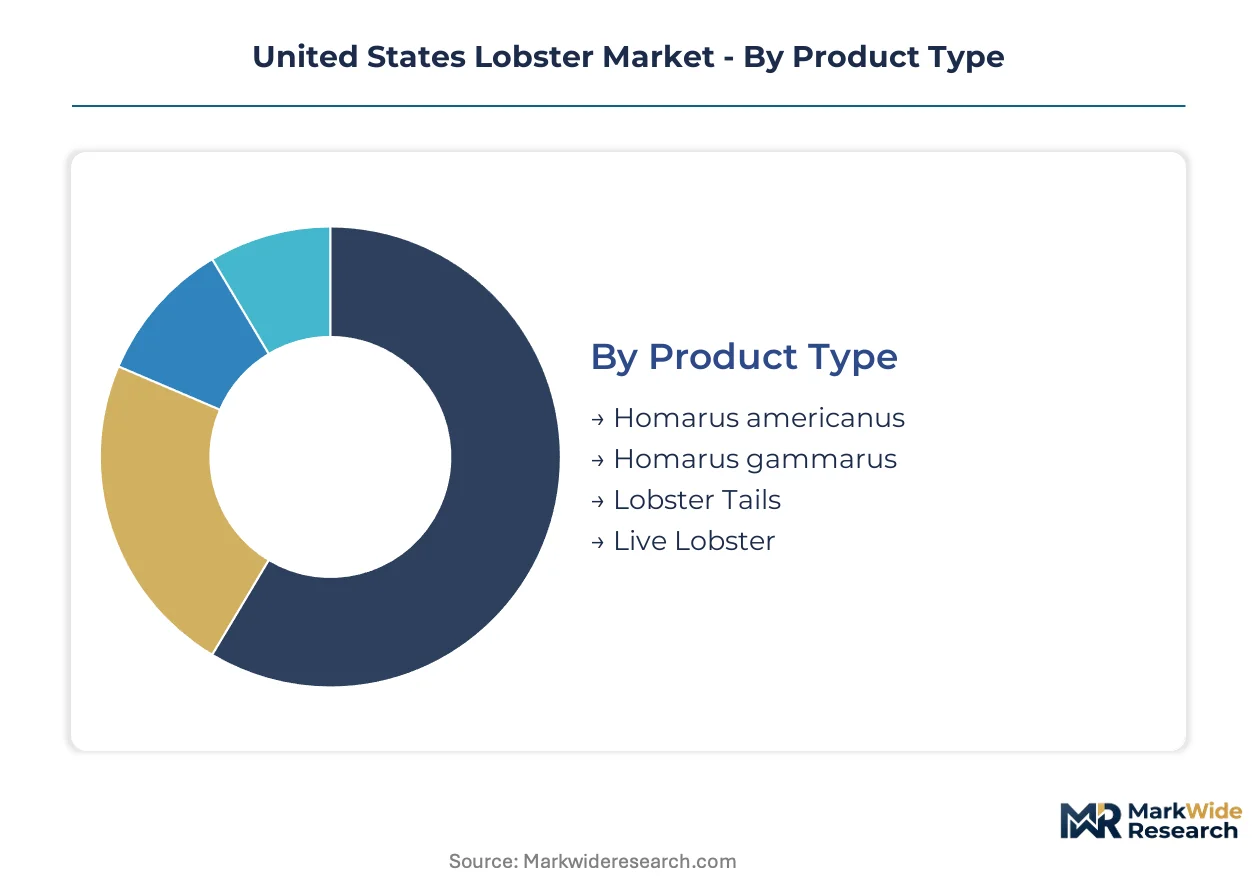
Segmentation in the United States lobster market reveals how supply chain configuration and buyer sophistication create distinct margin pools. Each dimension—species, channel, end user, and size grade—carries different handling requirements and pricing power that processors must navigate.
Product Type:
Supply concentration along the Gulf of Maine coast directly shapes which product formats dominate landed volume and export flow.
- Homarus americanus:The American lobster commands biological volume leadership through established Gulf of Maine stocks. Demand concentrates in Portland-to-Ellsworth processing corridors where live-holding infrastructure buffers seasonal trap limit interruptions.
- Homarus gammarus:European lobster imports serve niche white-tablecloth segments seeking claw-to-tail ratio differentiation. Geographic concentration in New England cold-chain hubs limits penetration against domestic supply advantages.
- Lobster Tails:Frozen tail packs anchor retail penetration beyond live occasion constraints.
- Live Lobster:Tank-to-table formats extract maximum perishability premiums from metropolitan restaurant installations.
Today's leader: Homarus americanus. Tomorrow's challenger: Lobster Tails.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain operators from asset-light digital intermediaries.
- Supermarkets:Pre-portioned retail formats require FDA HACCP-compliant processing at scale. Volume concentrates in Northeast regional chains with established seafood counter infrastructure.
- Restaurants:White-tablecloth procurement consolidates toward distributors with captive live-holding assets. Chicago and San Francisco markets exhibit the tightest supply consolidation.
- Direct-to-Consumer:Refrigerated e-commerce logistics are climbing the fastest as insulated packaging and last-mile cold protocols mature.
- Online Retail:Marketplace platforms aggregate fragmented shore-side supply for national reach.
Supermarkets dominate volume throughput. Direct-to-Consumer channels are gaining share fastest on margin expansion.
End User:
Application maturity separates established foodservice procurement from emerging household occasion creation.
- Seafood Restaurants:Visible tank installations signal freshness to diners. Demand clusters in metropolitan high-end segments from Boston to Los Angeles.
- Households:Modular meal kits and tail packs are opening penetration beyond traditional whole-live occasions. Recipe-ready formats drive trial in inland markets.
- Catering Services:Event-based procurement favors frozen processed formats for volume consistency.
- Retailers:Independent seafood houses face live supply access constraints against consolidated distributor networks.
Seafood Restaurants anchor premium pricing. Households show steepest expansion trajectory on format innovation.
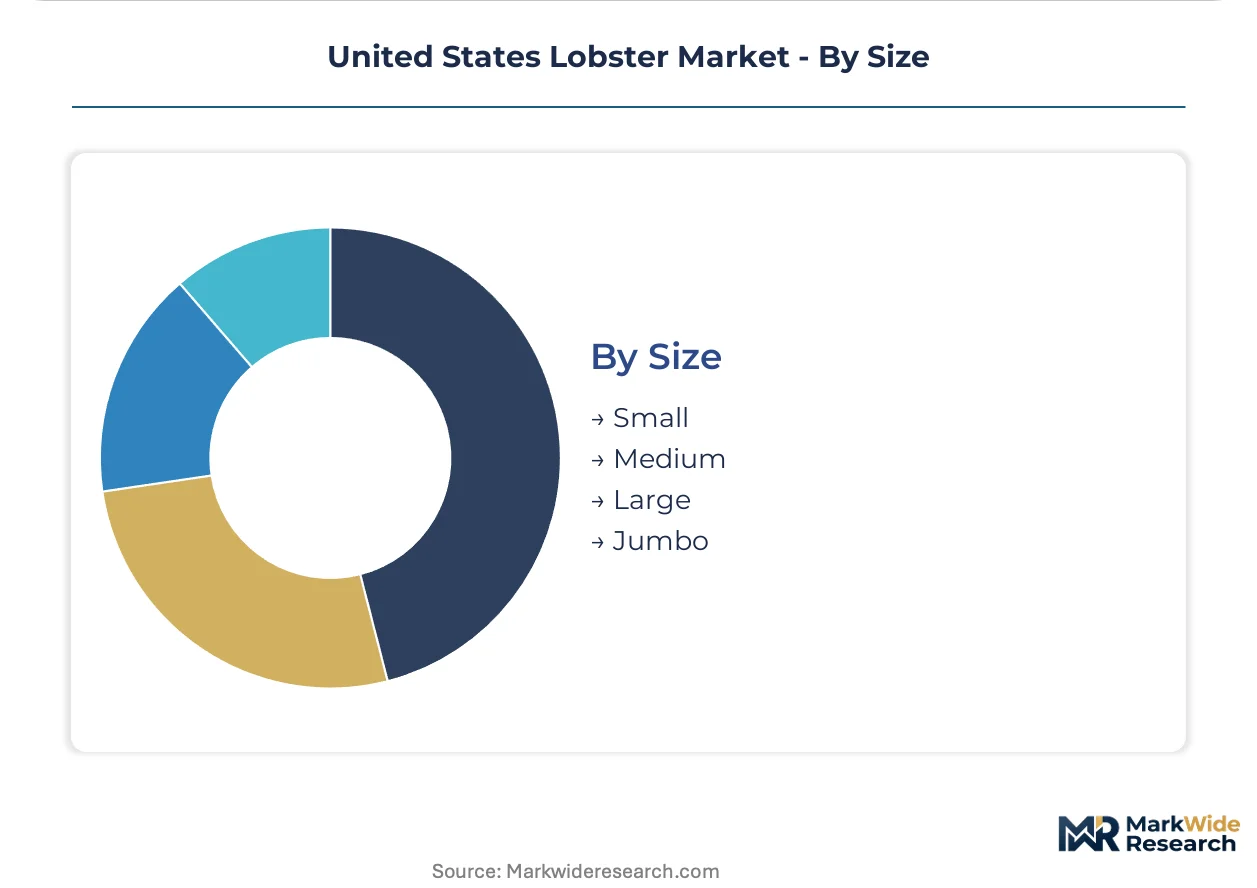
Size:
Grade differentiation creates tiered pricing architecture from commodity chix to trophy specimens.
- Large:One-and-one-half to two-pound specimens balance meat yield with cooking versatility. Demand concentrates in restaurant tank systems and direct-to-consumer gift programs.
- Jumbo:Specimens exceeding two pounds command auction premiums for special occasion positioning. Limited natural abundance restricts volume scalability.
- Small:Chix lobsters serve processing-intensive value-added applications.
- Medium:Select grade fills retail tail pack and restaurant portion control requirements.
Large sizes dominate revenue contribution. Jumbo grades face biological scarcity constraints on volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The American lobster industry traces its commercial roots to 17th-century New England, where Massachusetts Bay Colony fishermen first developed trap-based harvest methods that spread northward to Maine's more productive Gulf of Maine grounds.
Gulf of Maine
Maine's coastal processing corridor from Portland to Ellsworth anchors domestic volume, with live-holding infrastructure expanding to buffer NOAA seasonal trap limits. The Atlantic Large Whale Take Reduction Plan mandates weakened rope links and seasonal gear modifications that compress harvest windows. Ellsworth-based processors are consolidating shore-side operations to maintain supply continuity through truncated landing periods.
Southern New England
Massachusetts lobstermen face the most restrictive whale mitigation closures, with on-demand ropeless gear trials accelerating in Cape Cod Bay. State environmental regulators coordinate with federal NOAA officials on area-specific seasonal protocols. New Bedford processing facilities are diversifying into frozen tail packs to offset live supply volatility from truncated deployment windows.
Mid-Atlantic Corridor
New York and New Jersey distributors command premium positioning in metropolitan white-tablecloth markets, with tank installation costs consolidating procurement toward fewer cold-chain operators. FDA HACCP compliance requirements elevate processing standards for cross-state shipment. Brooklyn-based distributors are expanding refrigerated last-mile capacity to serve Philadelphia and Baltimore restaurant clusters.
Pacific Coast
California and Washington markets rely entirely on air-freighted East Coast supply, with San Francisco and Los Angeles restaurants absorbing the highest perishability premiums in domestic foodservice. State health departments enforce strict live animal receiving protocols at airport cargo facilities. Los Angeles-based seafood houses are losing live supply access as distributor consolidation accelerates.
Great Lakes and Inland
Chicago anchors inland demand through specialized cold-chain logistics serving white-tablecloth establishments, with direct-to-consumer channels gaining traction as refrigerated e-commerce protocols mature. Illinois and Michigan food safety inspectors coordinate interstate shipment documentation. Chicago distributors are expanding pre-portioned retail formats to capture household penetration beyond traditional restaurant supply.
United States Lobster Market Key Industry Players
The competitive structure tilts toward vertically integrated harvest-to-distribution operators with captive cold-chain assets. Processing capacity concentrates in Maine's coastal corridor where live-holding infrastructure creates defensive moats against supply interruption. Two strategic archetypes dominate: boat-to-box integrators controlling quality through upstream harvest assets, and specialized logistics operators serving dispersed metropolitan restaurant markets. Competitive moves center on regional hub expansion and FDA HACCP compliance differentiation that pressures smaller shore-side operators.
Among Maine-based integrators, Ready Seafood exemplifies the boat-to-box archetype through its captive supply chain from harvest through processing. East Coast Seafood Company anchors Mid-Atlantic distribution reach, while Supreme Lobster occupies specialized cold-chain positioning for national white-tablecloth service. These three represent distinct competitive vectors: upstream integration, geographic density, and logistics specialization.
| Leading Market Players |
|---|
| Boston Lobster Company |
| Cozy Harbor Seafood Inc. |
| East Coast Seafood Company |
| New England Lobster Co. |
| Ready Seafood |
| Southern Maine Lobster Company |
| Supreme Lobster |
| Maine Lobster Now |
| The Fresh Lobster Company |
| Others |
Cost & Logistics Intelligence
Metropolitan restaurant procurement consolidation toward captive cold-chain operators is forcing smaller distributors to absorb live-holding infrastructure costs or exit premium segments, compressing margins and accelerating price stratification across service tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by perishability handling and provenance documentation. Premium tiers extract markups from live tank-to-table formats with vessel-level traceability, while standard grades cover frozen tail packs with basic FDA HACCP compliance. Price differentiation stems from cold-chain custody documentation and seasonal availability windows. Cost compression in economy tiers is intensifying because bait expenditure inflation and trap limit restrictions squeeze independent lobstermen. Quick-service restaurant chains exhibit highest price sensitivity, while white-tablecloth establishments absorb premiums for consistent live supply.
Supply Chain Analysis
Herring and menhaden bait supply rests on Atlantic quota restrictions administered by NOAA, constraining input availability for Maine and Massachusetts trap operations. Live-holding infrastructure draws from Portland-to-Ellsworth processing clusters, while air-freight distribution feeds West Coast metropolitan markets. Raw material dependencies include bait fish stocks, rope and gear components, and insulated packaging materials. Single-source vulnerability concentrates in Gulf of Maine landings during truncated harvest windows. Distribution runs through vertically integrated boat-to-box operators and specialized cold-chain logistics providers serving national restaurant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States lobster market functions as a stable compounder anchored by inelastic demand from high-end foodservice and format innovation unlocking household penetration beyond traditional occasion constraints.
For Market Incumbents: Extend live-holding capacity in Portland-to-Ellsworth corridors to buffer NOAA seasonal trap limits and whale mitigation closures. Consolidate FDA HACCP-compliant processing assets to absorb smaller shore-side operators facing compliance cost pressure. Defensive positioning against distributor consolidation in Chicago and San Francisco white-tablecloth markets requires captive cold-chain investments or exclusive supply agreements with tank-installation restaurants. For New Entrants and Emerging Players: Capture underdeveloped refrigerated e-commerce logistics between New York and Baltimore where regional hub infrastructure remains fragmented. Penetrate inland household markets through modular meal kit formats that bypass live-handling complexity. A direct-to-consumer go-to-market angle leveraging insulated packaging partnerships with last-mile cold protocol specialists offers lowest barrier to trial. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors holding FDA HACCP certification and live-holding assets in Maine's coastal corridor. Long-term viability hinges on biological opinion outcomes and ropeless gear transition timelines rather than demand erosion. Watch pending NOAA seasonal area closure announcements as the critical inflection signal for supply availability and landing cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Holding Capacity Expansion | Buffers supply interruptions from Atlantic Large Whale Take Reduction Plan seasonal closures. |
| Backward Integration into Bait Supply | Reduces exposure to herring and menhaden quota volatility affecting trap economics. |
| Direct-to-Consumer Channel Launch | Captures premium perishability markups previously reserved for foodservice distributors. |
| Pre-Portioned Retail Format Development | Opens household penetration beyond traditional whole-live occasion constraints. |
| Cold-Chain Logistics Partnership | Secures last-mile refrigerated capacity for metropolitan restaurant tank installations. |
Research Approach
Direct dialogue with lobster harvesters, processing facility operators, restaurant procurement directors, and cold-chain logistics specialists grounded the qualitative foundation. Secondary validation drew from NOAA fisheries landings data, FDA HACCP inspection records, state-level licensing databases, and trade flow documentation. Bottom-up volume estimates from trap counts and landing reports triangulated against top-down demand aggregation across foodservice and retail channels.
Segment-level value outputs across the projection horizon reflect modeled interactions between species type, product format, distribution channel, and geographic end-use concentration. CAGRs were derived from historical landing trend analysis adjusted for regulatory constraint scenarios and format adoption curves. Forecast inputs incorporated trap limit schedules, whale mitigation closure probabilities, and refrigerated e-commerce penetration assumptions.
Biological opinion revisions, ropeless gear mandate acceleration, and bait quota restrictions are the dominant revision risks to modeled supply availability. Forecasts reflect documented assumptions about harvest window continuity and processing capacity utilization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Tuna Market
Seafood
COD Market
Seafood
Global Smoked Fish Market
Seafood
Edible Seaweed Market
Seafood
Global Seafood Market
Seafood
Halibut Market
Seafood
Fin Fish Market
Seafood
Sea Bream Market
Seafood
Rainbow Trout Market
Seafood
North America Salmon Market
Seafood
Seafood Flavors Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Milkfish Market
Seafood
Toothfish Market
Seafood
Europe Seafood Market
Seafood
Canned Sardines Market