
 United States Salmon Market | 2026-2036
United States Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
United States Salmon Market Intelligence
Premium ASC-certified and organic-grade salmon is collapsing the price gap against conventional farmed product as retailers rewrite procurement specifications. Mowi leverages its integrated feed-to-fillet operations across multiple coastal states to sustain volume leadership. Bakkafrost anchors its position through superior fish welfare metrics that differentiate shelf placement in Whole Foods and regional co-ops. Atlantic Sapphire competes via land-based recirculating aquaculture systems that promise domestic production without ocean pen exposure.
United States salmon encompasses farmed and wild-caught Oncorhynchus and Salmo species processed into fresh, frozen, smoked, and value-added formats for human consumption, with fat content, flesh color (astaxanthin saturation), and harvest method serving as primary quality differentiators in commercial grading. Farmed salmon dominates volume throughput while smoked salmon captures disproportionate margin in specialty retail channels. Online retail is accelerating fastest among distribution channels as direct-to-consumer platforms bypass traditional seafood counter intermediaries. Vacuum-sealed packaging leads innovation investment, extending shelf life from days to weeks and reducing spoilage rates in cross-country logistics.
FDA seafood HACCP mandates and NOAA fisheries management protocols govern harvest quotas, processing sanitation, and interstate commerce documentation, with USDA's Agricultural Marketing Service now auditing organic aquaculture claims. State-level environmental regulations in Washington and Maine restrict net pen density, forcing operators to adopt offshore or land-based alternatives. Stakeholders must monitor whether evolving EPA effluent standards for aquaculture facilities will require capital-intensive filtration upgrades that reshape cost structures for domestic producers.
Market Dynamics
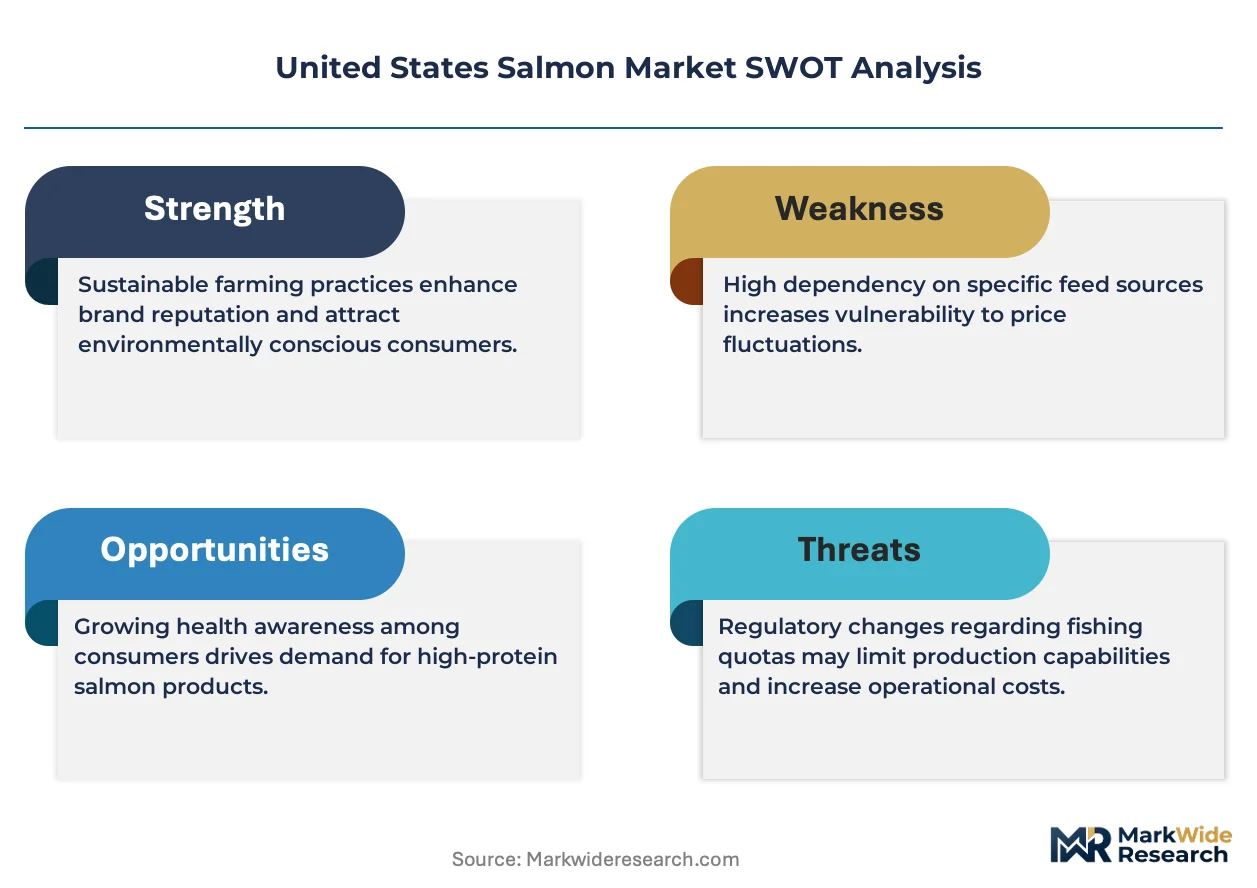
Land-based recirculating aquaculture systems are redrawing capital allocation across domestic salmon production as ocean pen operators face mounting state-level density restrictions and effluent compliance costs.
Growth Catalysts
- USDA Organic Aquaculture Audits:Retailers are expanding shelf space for certified organic fillets as federal verification protocols reduce label fraud, pulling premium-grade supply into mainstream distribution.
- Cold-chain infrastructure densification:Refrigerated logistics networks along the Pacific Northwest and Northeast corridors now enable fresh fillet delivery to restaurant chains within 24 hours of processing.
- Direct-to-consumer platforms:Online seafood retailers bypass traditional counter intermediaries, capturing margin previously absorbed by wholesale distributors and capturing household penetration in inland states.
Market Restraints
- Feed input cost volatility:Fishmeal and fish oil prices fluctuate with Peruvian anchovy harvest quotas, compressing farmed salmon margins when marine ingredient markets tighten.
- Supply concentration in Norway and Chile:Import dependence on two origin countries exposes US buyers to currency swings and foreign disease outbreaks that disrupt scheduled deliveries.
- EPA effluent standard uncertainty:Pending wastewater discharge rules for aquaculture facilities create capital planning paralysis among domestic operators considering expansion.
Strategic Opportunities
- Underpenetrated Midwest and Mountain West:Fresh salmon consumption per capita in Colorado, Utah, and Texas remains half coastal levels, presenting white space for cold-chain extension.
- Land-based RAS technology convergence:Integration of water recirculation engineering with renewable energy sourcing enables domestic production without ocean temperature or disease exposure.
- IRA clean energy incentives:Federal tax credits for renewable-powered agriculture infrastructure reduce operating cost premiums for land-based salmon farms versus conventional ocean pens.
Industry Challenges
- Biological technician shortage:Land-based RAS facilities require staff trained in both aquaculture husbandry and mechanical water system maintenance, a skill intersection with limited labor pool depth.
- ASC certification timeline compression:Aquaculture Stewardship Council audit backlogs stretch 14-18 months, delaying premium shelf placement for operators seeking certification-driven price realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Salmon Market |
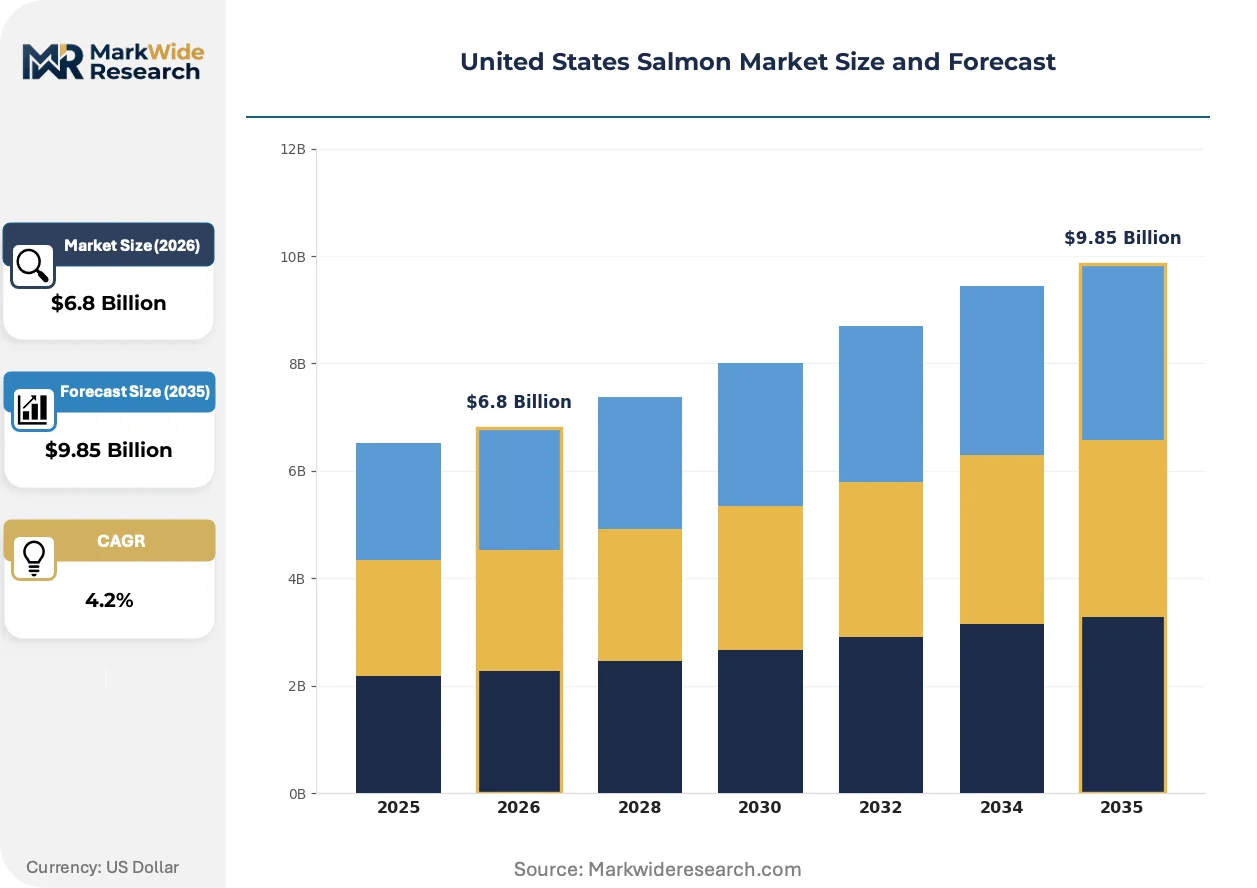
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Farmed Salmon, Wild Salmon, Smoked Salmon, Canned Salmon Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Fish Markets End User: Households, Restaurants, Food Service Providers, Grocery Stores Packaging Type: Fresh, Frozen, Vacuum-Sealed, Pre-Packaged |
| Companies Covered | SalMar ASA, Bakkafrost, Mowi, Nordlaks Produkter AS, Ideal Foods Ltd., Atlantic Sapphire, Cermaq, BluGlacier, AquaChile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Salmon Market Strategic Shifts & Innovations
Vacuum-sealed packaging formats and alternative protein feed trials are compressing spoilage windows and reshaping input cost structures simultaneously across the value chain.
Recirculating aquaculture system engineering is fragmenting production geography by enabling salmon farming in landlocked states without ocean access. Indoor facilities in Florida and Indiana now harvest Atlantic salmon year-round, insulated from seasonal temperature swings and algal bloom events that disrupt coastal operations. This distributed production model is compressing freight distances to inland population centers while raising unit capital costs.
FDA seafood HACCP mandates are tightening processing documentation requirements for interstate commerce, forcing mid-size smokers and distributors to upgrade electronic traceability systems. The agency's enhanced scrutiny of astaxanthin sourcing claims affects labeling for farmed fillets marketed as "naturally colored." Smoked salmon specialty retailers are responding by segregating supply chains for certified additive-free product lines.
Restaurant procurement is consolidating toward pre-portioned, individually quick-frozen fillets as labor costs compress back-of-house fish butchering economics. Broadline distributors are displacing traditional seafood counter relationships by offering specification-grade consistency with integrated food safety documentation. This specification-driven buying pattern is most visible in the Southeast, where casual dining chains dominate salmon menu placement.
United States Salmon Market Segmentation
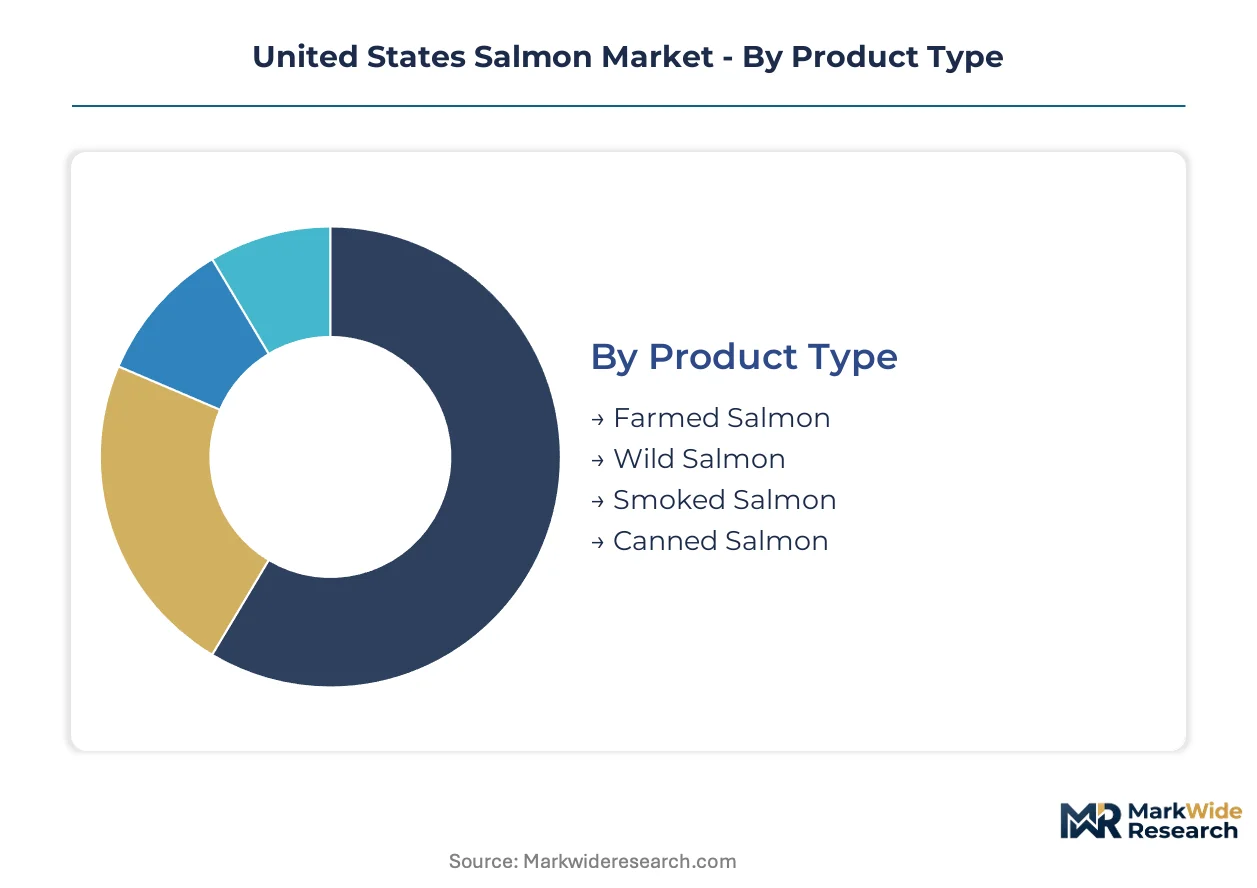
Segmentation in the United States salmon market reveals how margin pools concentrate around freshness preservation and certification premiums. Distribution channel selection and packaging technology choices now determine profitability more than species origin alone.
Product Type:
Farmed salmon commands the deepest margin pools through volume scale and supply predictability, while smoked salmon extracts premium returns in specialty retail channels.
- Farmed Salmon:Atlantic salmon raised in ocean net pens or land-based recirculating aquaculture systems delivers consistent fat content and flesh coloration through controlled feed regimens. Restaurant chains in the Pacific Northwest and Northeast corridors anchor procurement volumes, though state-level density restrictions in Washington and Maine are pushing investment toward RAS alternatives.
- Wild Salmon:Pacific species including Chinook, Coho, and Sockeye harvested under NOAA fisheries management protocols carry seasonal availability constraints and higher unit procurement costs. Alaska's harvest quotas and Bristol Bay run strength determine annual supply volumes, with smokehouses and direct-to-consumer platforms capturing value from limited-availability positioning.
- Smoked Salmon:Value-added processing commands shelf-space premiums in Whole Foods and regional co-ops through ASC-certified and organic-grade positioning.
- Canned Salmon:Shelf-stable format serves institutional buyers and food banks with lower per-unit margins but steady demand through economic cycles.
Farmed salmon holds installed capacity. Smoked salmon is rotating up the share rankings.
Distribution Channel:
Channel selection determines spoilage risk allocation and documentation burden under FDA seafood HACCP mandates, with cold-chain infrastructure availability shaping geographic reach.
- Online Retail:Direct-to-consumer platforms bypass traditional seafood counter intermediaries, capturing margin previously absorbed by wholesale distributors. Vacuum-sealed packaging enables cross-country logistics with extended shelf life, expanding household penetration in Colorado, Utah, and Texas where fresh salmon consumption per capita remains below coastal levels.
- Supermarkets:Kroger, Albertsons, and regional chains dominate volume throughput through farmed Atlantic salmon fillet programs with specification-grade consistency requirements.
- Specialty Stores:Premium positioning focuses on ASC-certified and organic-grade differentiation with segregated supply chains for additive-free product lines.
- Fish Markets:Independent operators maintain local relationships with restaurant buyers and high-frequency household purchasers seeking whole-fish butchering services.
Supermarkets hold installed capacity. Online retail is expanding most quickly.
End User:
End-user segmentation tracks labor cost pressures and back-of-house economics, with pre-portioned formats gaining traction where skilled fish butchering has become uneconomical.
- Restaurants:Casual dining chains in the Southeast consolidate procurement toward individually quick-frozen fillets as labor costs compress traditional seafood counter relationships. Broadline distributors displace independent suppliers through integrated food safety documentation and specification-grade consistency.
- Households:Direct-to-consumer platforms and supermarket fresh counters serve meal-kit subscribers and high-frequency purchasers with vacuum-sealed convenience formats.
- Food Service Providers:Institutional buyers including hospitals, universities, and corporate cafeterias prioritize frozen and pre-packaged formats with HACCP-compliant traceability systems.
- Grocery Stores:In-house seafood departments function as both end users and resale intermediaries, absorbing spoilage risk before final household purchase.
Restaurants hold installed capacity. Food service providers are climbing the fastest.
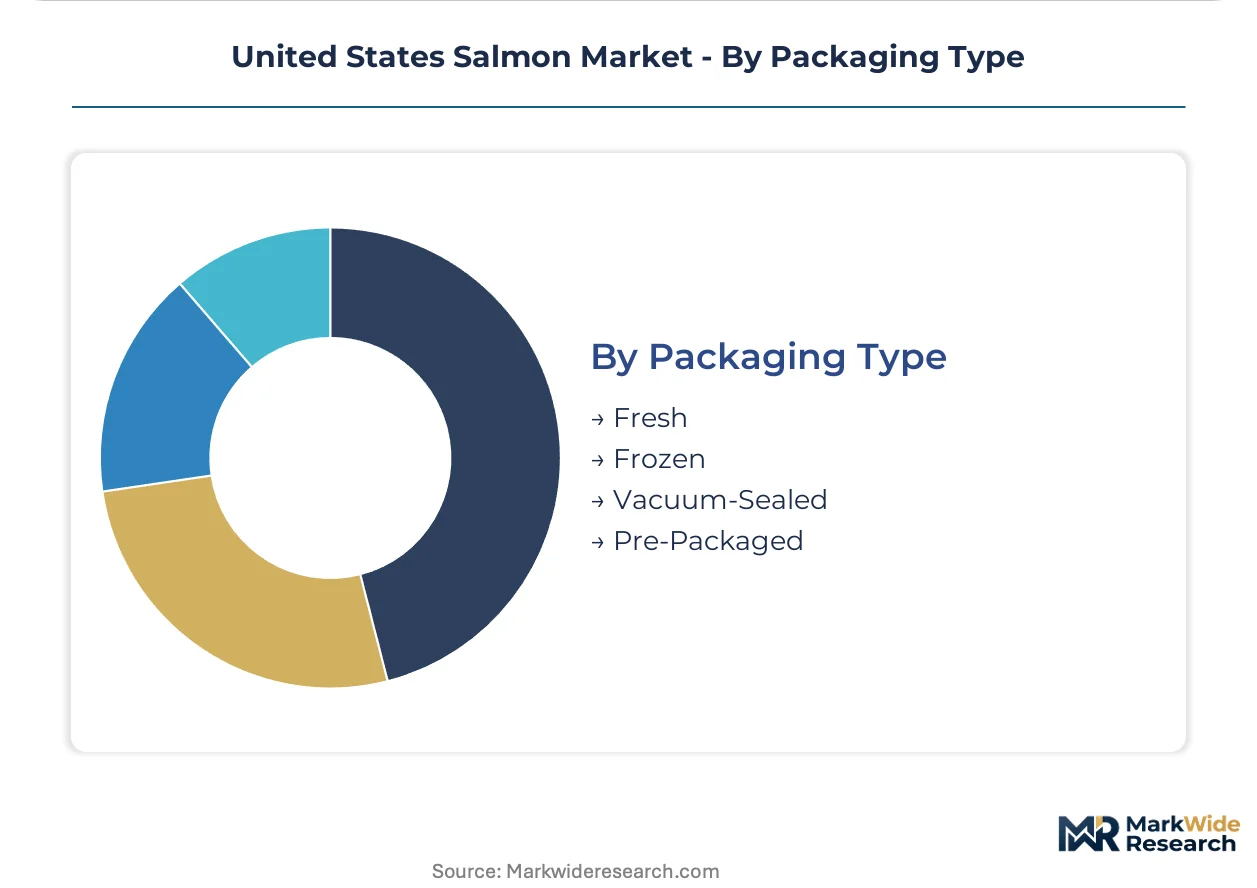
Packaging Type:
Packaging technology investment directly correlates with shelf-life extension and freight radius expansion, reshaping competitive boundaries between coastal and inland supply.
- Vacuum-Sealed:Modified atmosphere packaging extends shelf life from days to weeks, enabling cross-country logistics from Pacific Northwest processing facilities to inland population centers. This format commands procurement preference from online retailers and broadline distributors seeking reduced spoilage rates.
- Fresh:Ice-packed fillets delivered within 24 hours of processing serve restaurant chains and high-frequency supermarket replenishment cycles along cold-chain-dense corridors.
- Frozen:Individually quick-frozen formats support inventory flexibility for institutional buyers and casual dining chains with variable menu placement.
- Pre-Packaged:Portion-controlled retail packs reduce consumer handling and support grab-and-go merchandising strategies in time-constrained shopping environments.
Fresh packaging holds installed capacity. Vacuum-sealed formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic salmon supply clusters along coastal states with established cold-chain infrastructure, while land-based recirculating aquaculture systems fragment production geography toward inland population centers. State-level environmental regulations in Washington and Maine restrict net pen density, redirecting capital toward alternative production models.
Pacific Northwest
Washington and Oregon host established ocean net pen operations serving restaurant chains and supermarket seafood counters. The Washington State Department of Ecology enforces effluent discharge permits that limit stocking densities, forcing operators toward offshore or land-based alternatives. Seattle-Tacoma processing clusters handle fresh fillet distribution to California and inland markets via refrigerated logistics networks.
Northeast Corridor
Maine's coastline supports Atlantic salmon farming operations targeting Boston and New York metropolitan demand. Maine Department of Marine Resources regulations on net pen siting create compliance burdens that favor land-based RAS investment. Portland processing facilities supply fresh product to institutional buyers along the I-95 corridor within 24-hour delivery windows.
Florida
Land-based RAS facilities in Florida exploit year-round growing conditions insulated from seasonal temperature swings. The state's aquaculture permitting framework under Florida Fish and Wildlife Conservation Commission enables indoor salmon production without ocean access. Miami-Dade and Palm Beach counties host emerging facilities targeting Southeast restaurant chains with reduced freight distances.
Midwest
Indiana and Ohio RAS operations compress supply chains to Chicago, Detroit, and Cleveland markets previously served by coastal freight. Per capita salmon consumption in these states remains below coastal benchmarks, presenting expansion opportunity as cold-chain infrastructure densifies. Indianapolis processing hubs distribute vacuum-sealed product to grocery retailers across the Corn Belt.
Mountain West
Colorado and Utah represent underpenetrated demand territories where fresh salmon consumption trails national averages. Denver and Salt Lake City distribution centers receive vacuum-sealed shipments from Pacific Northwest and Midwest origins. Local food service providers prioritize pre-portioned frozen formats until fresh delivery economics improve.
United States Salmon Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated ocean pen operators competing against capital-intensive land-based specialists. Market structure tilts toward consolidated volume leadership among multinational aquaculture groups, while domestic RAS ventures fragment the emerging land-based tier. Three archetypes dominate: integrated feed-to-fillet multinationals, land-based RAS technology developers, and regional smokehouse value-add processors. Competitive moves center on backward integration into feed production and geographic diversification of processing assets.
Among Norwegian-integrated operators, Mowi and SalMar ASA represent scale-driven archetypes with feed-to-fillet control across multiple coastal states. Bakkafrost occupies a differentiated position through welfare-certified positioning in premium retail channels. Atlantic Sapphire exemplifies the land-based technology vector, with Florida RAS facilities targeting domestic production without ocean pen exposure.
| Leading Market Players |
|---|
| SalMar ASA |
| Bakkafrost |
| Mowi |
| Nordlaks Produkter AS |
| Ideal Foods Ltd. |
| Atlantic Sapphire |
| Cermaq |
| BluGlacier |
| AquaChile |
| Others |
Cost & Logistics Intelligence
Land-based recirculating aquaculture system adoption is displacing ocean pen production across multiple states, compressing freight distances to inland population centers while raising unit capital costs and reshaping price competitiveness against import-dependent supply.
Pricing Analysis
USDA organic aquaculture audits dictate the pricing tier structure across retail channels, separating certified organic fillets from conventional farmed product through federal verification protocols. Three-tier pricing structure across premium ASC-certified, standard farmed Atlantic, and economy frozen formats reflects certification grade and cold-chain delivery cost. Pricing pressure stems from feed input cost volatility tied to Peruvian anchovy harvest quotas. Casual dining chains in the Southeast exhibit highest price sensitivity, while specialty retailers in the Northeast corridor show lowest sensitivity to organic-grade premiums.
Supply Chain Analysis
Panama Canal transit congestion and Pacific Northwest port capacity constraints expose import-dependent buyers to scheduling disruptions and inventory carrying cost spikes. Supply concentrates in Norway and Chile for Atlantic salmon, with Alaska anchoring Pacific wild species harvest. Fishmeal and fish oil from Peruvian anchovy fisheries, plus specialized RAS engineering components, constitute critical input dependencies. Single-source vulnerability runs through Norwegian-Chilean origin concentration. Distribution runs through cold-chain logistics networks along coastal corridors with vacuum-sealed packaging enabling inland extension.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer platform interoperability with meal-kit subscription ecosystems is creating platform-economics inflection, rewarding operators who integrate traceability data with consumer-facing mobile interfaces.
For Market Incumbents: Consolidate feed-to-fillet control through backward integration into specialized aquafeed production, defending margin position against marine ingredient cost volatility. Secure ASC certification ahead of 14-18 month audit backlogs to capture premium shelf placement at Whole Foods and regional co-ops before competitors. Channel control through exclusive broadline distributor relationships protects specification-grade consistency requirements.
For New Entrants and Emerging Players: Anchor in Colorado and Utah demand territories where fresh salmon consumption per capita remains half coastal levels, presenting white space for cold-chain extension from Midwest RAS facilities. Target food service providers in Denver and Salt Lake City with pre-portioned frozen formats until fresh delivery economics improve. Go-to-market angle centers on renewable-powered production narratives aligned with IRA clean energy incentives.
For Investors and Strategic Acquirers: The market sits at a technology-convergence phase that favors land-based RAS specialists with demonstrated biological technician training programs and Florida or Indiana facility locations. Long-term viability hinges on EPA effluent standard resolution and renewable energy cost curves. Acquisition target archetype combines RAS engineering expertise with existing retail channel relationships. Signal to watch is ASC certification timeline compression as audit backlogs stretch premium price realization windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Land-Based RAS Capacity Expansion | Florida and Indiana facilities reduce ocean pen regulatory exposure while serving Southeast restaurant chains with shorter freight distances. |
| Backward Integration into Aquafeed | In-house production of fishmeal substitutes insulates margins from Peruvian anchovy quota volatility and marine ingredient price spikes. |
| ASC Certification Investment | Federal verification protocols reduce label fraud risk while unlocking premium shelf placement at Whole Foods and regional co-ops. |
| Direct-to-Consumer Platform Launch | Vacuum-sealed packaging enables cross-country logistics that bypass wholesale distributor margin capture in underpenetrated Mountain West states. |
| Renewable Energy Sourcing Agreement | IRA tax credits for clean-powered agriculture infrastructure reduce operating cost premiums versus conventional ocean pen production. |
Research Approach
Desk research of FDA seafood HACCP guidance documents, NOAA fisheries management protocols, and USDA organic aquaculture audit procedures preceded structured interviews with RAS facility operations managers, broadline distributor procurement leads, restaurant chain supply chain directors, and supermarket seafood category buyers. Secondary validation drew from EPA effluent standard dockets, state-level environmental regulation filings in Washington and Maine, and trade data on Norwegian and Chilean salmon imports. Bottom-up volume modeling triangulated against top-down market sizing from cold-chain infrastructure capacity assessments.
Variance decomposition across product type, distribution channel, packaging format, and end-user segments structured the analytical framework over the projection horizon. Modeled dimensions included farmed versus wild origin, fresh versus frozen versus smoked processing grade, vacuum-sealed versus ice-packed versus canned packaging, and restaurant versus household versus institutional demand. CAGRs derived from segment-level growth rate assumptions weighted by base-year volume shares. Forecast inputs incorporated Peruvian anchovy harvest quota projections and EPA regulatory timeline scenarios.
Decision-makers should treat outputs as directional under stable cold-chain infrastructure investment and no material EPA effluent rule acceleration assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Norwegian-Chilean disease outbreak patterns and renewable energy cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global Smoked Fish Market
Seafood
United States Lobster Market
Seafood
Europe Shrimp Market
Seafood
Smoked Whiting Market
Seafood
Fish Hydrolysate Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Saudi Arabia Seafood Market
Seafood
Global Commercial Fishing Market
Seafood
Sea Biscuits Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Oyster Meal Market
Seafood
Fish Meal Market
Seafood
Rainbow Trout Market
Seafood
Mussel Extract Market
Seafood
Fin Fish Market
Seafood
Krill Meal Market