
 Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market | 2026-2036
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market Insights
EU Green Deal sustainability criteria for aquaculture feed sourcing is consolidating procurement standards across European aquaculture supply chains. Cargill Incorporated leverages its integrated aquaculture nutrition platform to sustain bulk supply contracts with industrial farm operators. BASF SE anchors its position through specialty additive formulations targeting gut health optimization in intensive shrimp systems. Biomar Group differentiates via precision nutrition protocols developed for recirculating aquaculture environments.
Fish and shrimp feed and additives encompass formulated nutritional inputs combining protein meals, lipid sources, carbohydrate binders, and functional micro-ingredients processed through extrusion, pelleting, or cold-pressing into water-stable feed matrices designed to deliver complete dietary requirements across aquatic species life stages. Probiotic and enzyme additive categories command premium positioning due to their documented effects on feed conversion ratios and pathogen resistance in high-density production systems. Pellet and crumble product formats dominate volume flows to large-scale aquaculture farms, while powder and granule segments serve hatchery and nursery applications where particle size precision governs survival rates.
EFSA feed additive authorization protocols, EU REACH chemical safety standards, and national aquaculture licensing regimes in Indonesia, Vietnam, and Thailand collectively determine market access conditions and product registration timelines. These regulatory frameworks elevate barriers for uncertified suppliers while rewarding manufacturers with documented traceability systems and third-party verified formulations. Stakeholders must monitor evolving antibiotic residue thresholds and emerging novel feed ingredient approval pathways to sustain competitive positioning.
Market Dynamics
EU Green Deal sustainability criteria for aquaculture feed sourcing is consolidating procurement standards across European aquaculture supply chains. Cargill Incorporated leverages its integrated aquaculture nutrition platform to sustain bulk supply contracts with industrial farm operators. BASF SE anchors its position through specialty additive formulations targeting gut health optimization in intensive shrimp systems. Biomar Group differentiates via precision nutrition protocols developed for recirculating aquaculture environments.
Growth Catalysts
- EFSA Feed Additive Authorization:Streamlined approval pathways for novel enzymes and probiotics are accelerating functional ingredient penetration in EU member state aquaculture operations.
- Recirculating Aquaculture Systems:Closed-loop production infrastructure in Denmark and the Netherlands is generating specialized feed demand with precise nutrient delivery specifications.
- Southeast Asian Cluster Expansion:Industrial shrimp farming zones across Indonesia, Vietnam, and Thailand are scaling formulated feed adoption to replace wild catch dependency.
Market Restraints
- Fishmeal Supply Concentration:Peruvian and Chilean anchovy harvest volatility creates protein input cost instability for marine-based feed formulations.
- EU REACH Compliance Burden:Chemical safety documentation requirements for novel additives extend product registration timelines and elevate R&D expenditure thresholds.
- Plant Protein Digestibility Limits:Anti-nutritional factors in soybean and pea concentrates constrain substitution rates for carnivorous species like salmon and seabass.
Strategic Opportunities
- Insect Protein Integration:Black soldier fly larvae meal approval under EU novel food regulations opens alternative protein pathways for premium aquaculture segments.
- Microalgae Omega-3 Sourcing:Schizochytrium and Nannochloropsis cultivation is displacing fish oil dependence in salmonid and shrimp larval nutrition.
- Direct-to-Farm Digital Platforms:B2B e-procurement channels in Vietnamese Mekong Delta farming cooperatives are compressing distributor margin capture.
Industry Challenges
- Formulation Talent Scarcity:Aquaculture nutrition specialists with species-specific metabolic expertise command premium compensation and constrain R&D team scaling.
- Multi-Site Certification Complexity: simultaneous ASC, BAP, and GLOBALG.A.P. audit maintenance across Indonesian archipelago farming networks drains operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market |
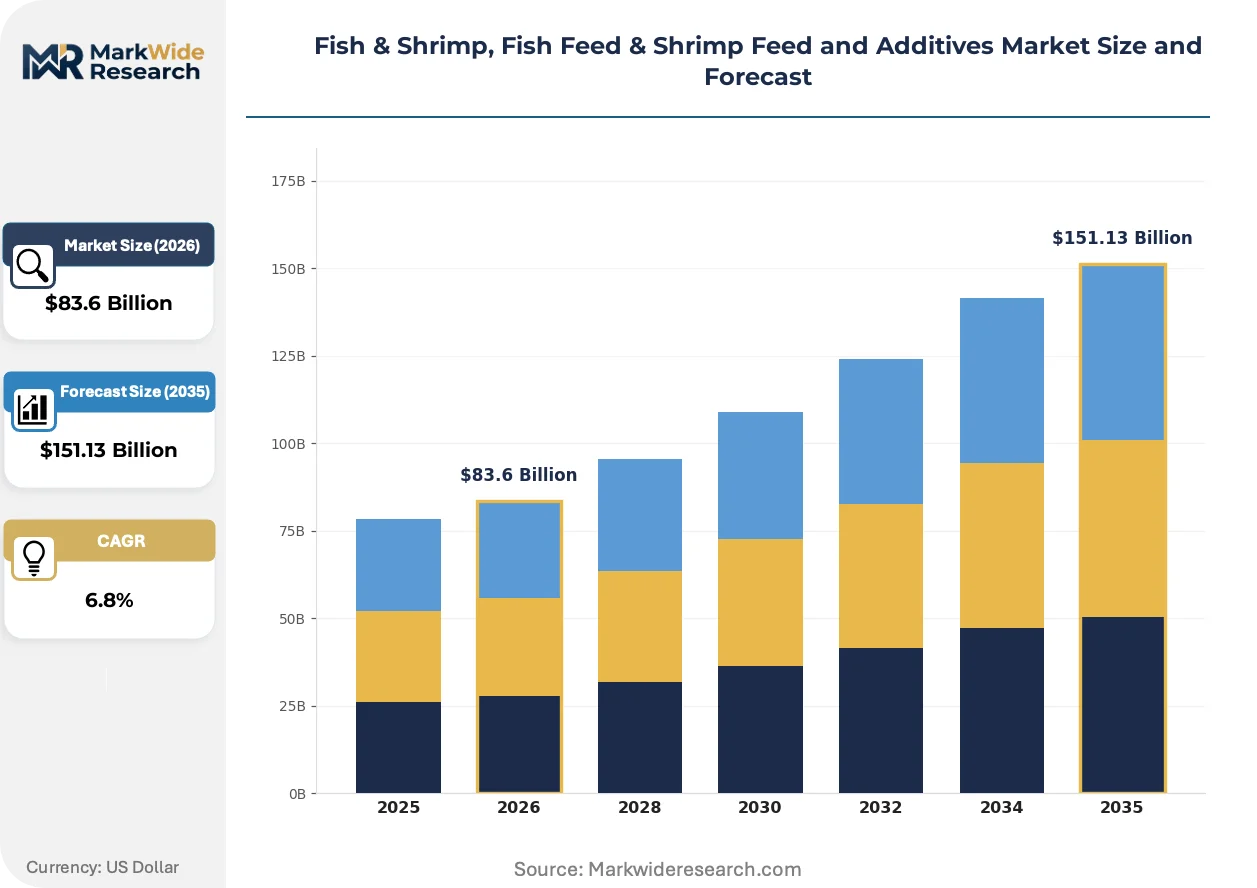
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $151.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellet, Crumble, Powder, Granule Additive Type: Vitamins, Amino Acids, Probiotics, Enzymes End User: Aquaculture Farms, Feed Manufacturers, Research Institutions, Fish Hatcheries Distribution Channel: Online Retail, Distributors, Wholesale, Direct Sales |
| Companies Covered | Alltech Inc, Aller Aqua A/S, Cargill Incorporated, BASF SE, Biomin GmbH, Nutreco NV, Archer Daniels Midland Co, Ridley Corporation, Biomar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market Trends and Innovations
Precision fermentation and single-cell protein production is actively reshaping raw material sourcing strategies across formulated aquaculture nutrition. Novel manufacturing pathways are compressing traditional supply dependencies while opening formulation flexibility for species-specific dietary optimization.
Cellular agriculture-derived protein ingredients is decentralizing marine resource extraction by enabling land-based production of nutritionally equivalent fishmeal substitutes. Nordic salmon feed manufacturers are integrating fermented microbial biomass at commercial scale. This technology is decentralizing supply chain risk away from volatile wild catch harvests toward controlled bioreactor output.
EU F-Gas Regulation phase-down mandates are accelerating cold-chain infrastructure retrofit requirements for temperature-sensitive additive storage. Feed compounders operating across Germany and France face capital allocation decisions for refrigeration system upgrades. Specialty probiotic and enzyme suppliers with stabilized formulation platforms are capturing preference share from conventional liquid concentrate providers.
Consolidated procurement by vertically integrated shrimp conglomerates in Thailand's Eastern Seaboard is compressing spot-market feed transactions. Long-term offtake agreements with volume-tiered pricing now dominate supply relationships for industrial-scale operators. Vietnamese pangasius farming cooperatives are replicating this contracting model to secure input cost predictability across eighteen-month production cycles.
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market Segmentation
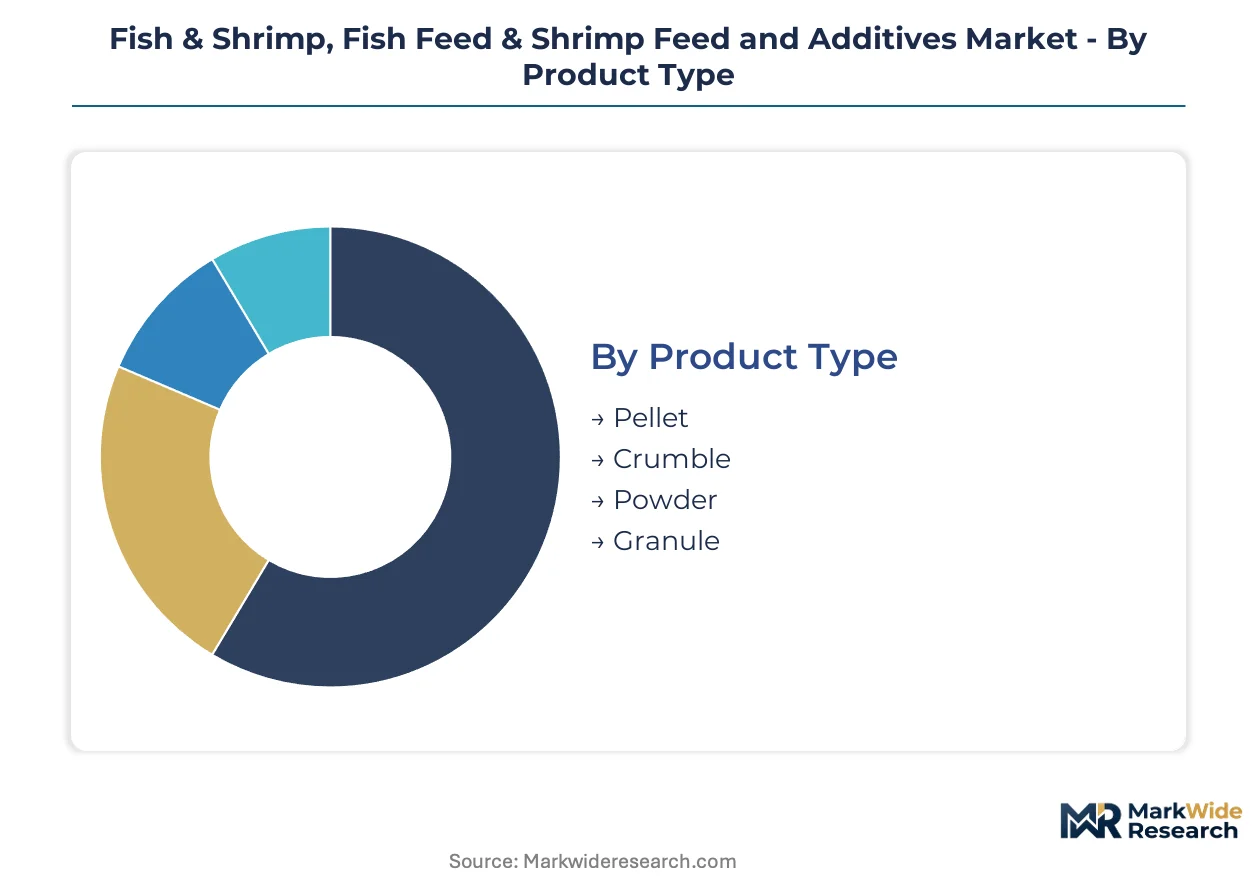
Segmentation in aquaculture feed markets reveals distinct capital deployment patterns across production formats and functional inputs. Feed formulators align product architecture with species-specific consumption behavior, water stability requirements, and farm infrastructure constraints.
Product Type:
Pellet and crumble formats demand the highest capital intensity due to extrusion equipment requirements and die customization for water stability profiles.
- Pellet:Extruded cylindrical matrices with controlled buoyancy characteristics serve intensive salmon and seabass cage operations. Norwegian and Chilean Atlantic salmon producers specify slow-sinking variants for deep-water net pen deployment. Capital recovery cycles for twin-screw extrusion lines extend operational planning horizons.
- Crumble:Fragmented intermediate particle sizes bridge starter and grower diet transitions in shrimp nursery phases. Vietnamese Mekong Delta intensive ponds source crumble for post-larval stocking protocols where feed conversion efficiency governs survival economics. Die wear rates elevate maintenance budgets relative to pellet systems.
- Powder:Micronized formulations for larval fish and shrimp nauplii stages concentrate demand in specialized hatchery facilities across Indonesia and Thailand.
- Granule:Cold-pressed binders suit low-density extensive pond systems where mechanical durability requirements remain modest.
Most installed capacity flows through Pellet. Expansion is steepest in Crumble.
Additive Type:
Functional additive selection tracks species metabolic priorities and regulatory approval status across destination markets.
- Vitamins:Fat-soluble and water-soluble premixes prevent deficiency pathologies in high-density recirculating systems. Danish RAS operators specify stabilized ascorbic acid derivatives for rainbow trout production where oxidative stress limits growth performance. EFSA additive registry compliance governs EU market access timelines.
- Amino Acids:Crystalline lysine, methionine, and threonine supplementation enables plant protein substitution in carnivorous species diets. Thai shrimp feed compounders balance cost reduction against taurine retention requirements in marine-based formulations. Sourcing contracts with fermentation-derived amino acid suppliers anchor input cost predictability.
- Probiotics:Bacillus and lactic acid bacteria strains colonize shrimp gut microbiota to suppress Vibrio pathogen loads in Indonesian intensive ponds.
- Enzymes:Phytase and non-starch polysaccharide degraders unlock phosphorus and energy from plant meals in tilapia grower diets.
Volume leadership sits with Vitamins. Probiotics gain share fastest in premium shrimp segments.
End User:
Customer procurement sophistication diverges sharply between industrial-scale operators and fragmented extensive farming networks.
- Aquaculture Farms:Vertically integrated salmon producers in Norway and Chile operate captive feed mills with real-time formulation adjustment capabilities. Direct sourcing of bulk additives bypasses distributor markups while demanding dedicated technical service relationships. Capital deployment into on-site extrusion infrastructure locks in supply security.
- Feed Manufacturers:Independent compounders across Vietnam and Indonesia blend base mixes with species-specific premixes for regional farm cooperatives. Formulation talent scarcity constrains R&D team scaling relative to multinational competitors. Toll manufacturing arrangements proliferate for novel additive trials.
- Research Institutions:University and government hatchery networks in Thailand validate novel ingredient digestibility through controlled feeding trials.
- Fish Hatcheries:Specialized larval nutrition demands concentrate procurement of live feed substitutes and microencapsulated diets.
Revenue concentration aligns with Aquaculture Farms. Feed Manufacturers expand blending capacity most aggressively.
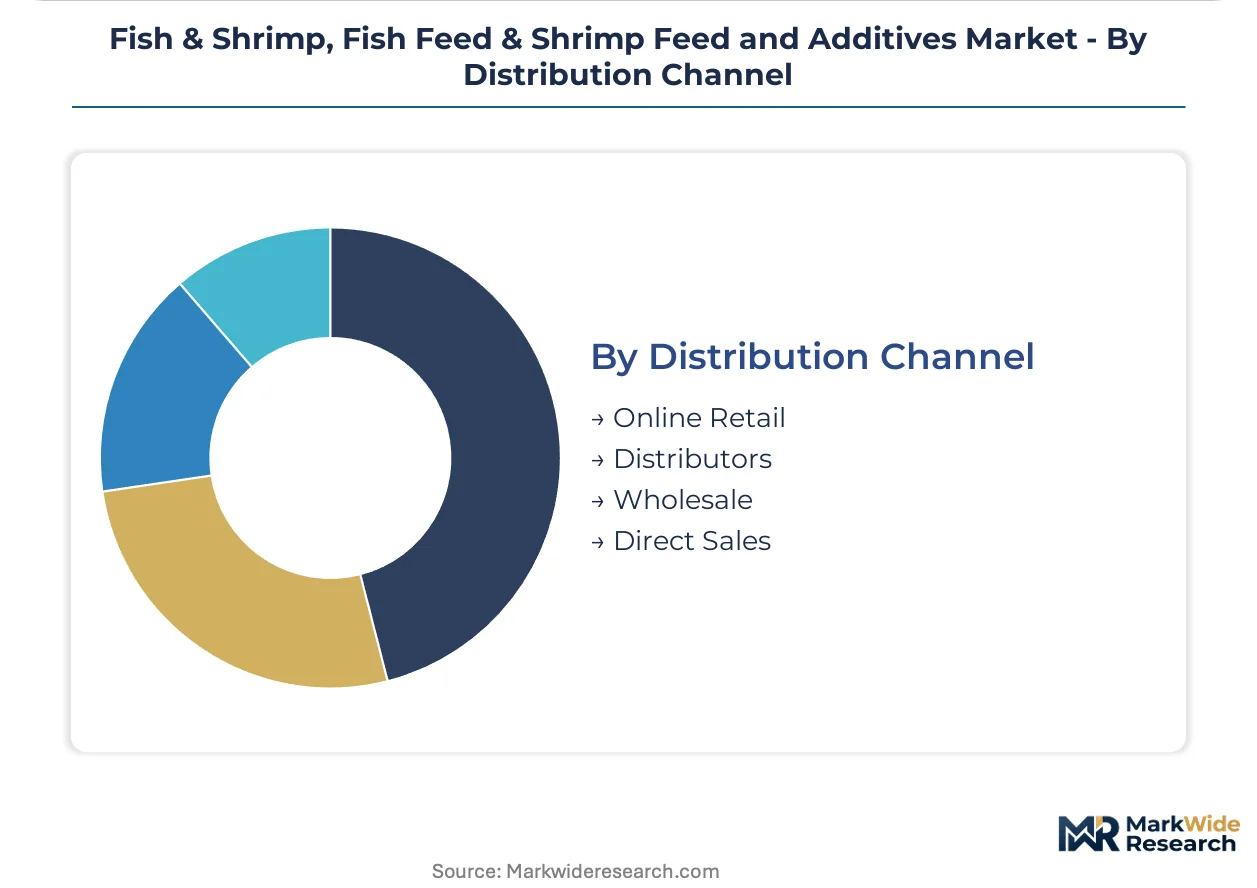
Distribution Channel:
Channel selection reflects farm scale, geographic dispersion, and input criticality to production cycles.
- Distributors:Regional warehousing networks across Indonesian archipelago farming zones manage inventory for scattered smallholder pond operators. Credit extension and technical advisory services bundle with physical product delivery. Working capital intensity exceeds direct sales models.
- Direct Sales:Long-term offtake agreements dominate Thai Eastern Seaboard shrimp conglomerate procurement with volume-tiered pricing structures. Dedicated account teams coordinate formulation customization and delivery scheduling across multi-site operations. Relationship maintenance costs scale with customer concentration.
- Online Retail:B2B platforms in Vietnamese Mekong Delta cooperatives compress traditional distributor margins through price transparency.
- Wholesale:Bulk break-bulk operations serve intermediate aggregators in secondary Indonesian market towns.
Distributors handle the greatest tonnage. Direct Sales capture margin expansion in consolidated customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aquaculture feed production first achieved industrial scale in Norway during the 1970s Atlantic salmon farming boom. This Nordic foundation established extrusion technology and marine protein formulation standards that now propagate across global production zones. Contemporary market geography reflects this technical lineage while diversifying into tropical shrimp clusters and recirculating system corridors.
Norway
Atlantic salmon cage operations in Vestland and Trøndelag counties consume specialized slow-sinking pellet formulations for deep-water net pen deployment. EFSA feed additive authorization protocols govern probiotic and enzyme ingredient registrations entering Norwegian compounders. Bergen and Stavanger host integrated nutrition R&D facilities serving North Sea farming concessions.
Vietnam
Mekong Delta intensive shrimp ponds and pangasius cage systems drive crumble and extruded pellet procurement at industrial scale. The country's national aquaculture licensing regime mandates traceability documentation for export-oriented feed manufacturers. Cần Thơ and An Giang provinces concentrate toll-milling capacity for regional farming cooperatives.
Indonesia
Java Sea and Sulawesi shrimp farming zones scale formulated feed adoption to displace wild catch dependency in hatchery operations. BAP certification requirements from the Global Aquaculture Alliance shape procurement standards for export-oriented producers. Lampung and East Java harbor blending facilities serving scattered archipelago pond networks.
Thailand
Eastern Seaboard industrial shrimp conglomerates execute long-term offtake agreements with volume-tiered pricing structures. The country's national aquaculture licensing regime enforces antibiotic residue thresholds across feed supply chains. Chonburi and Rayong provinces anchor vertically integrated production from hatchery through processing.
Netherlands
Recirculating aquaculture systems in Zeeland and Limburg generate demand for precision nutrition protocols with exact nutrient delivery specifications. EU REACH chemical safety standards extend registration timelines for novel additive formulations entering Dutch compounders. Wageningen University corridors host fermentation-derived ingredient pilot facilities.
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market Competitive Landscape
Capital-heavy producers with captive extrusion infrastructure compete with asset-light formulation designers licensing toll-milling capacity. Market structure tilts toward consolidation among integrated nutrition platforms while regional compounders fragment across Southeast Asian farming clusters. Three archetypes dominate: multinational agribusiness divisions with aquaculture-dedicated verticals; European specialty additive houses targeting gut health optimization; and Asia-Pacific toll manufacturers serving cooperative procurement networks. Dominant competitive moves include backward integration into alternative protein cultivation and geographic expansion through distributor acquisition in Vietnamese Mekong Delta corridors.
Within the integrated nutrition tier, Cargill Incorporated and Nutreco NV occupy positions exemplifying bulk supply contract execution with industrial farm operators. Among European specialty additive houses, BASF SE and Biomin GmbH represent archetypes anchoring gut health formulation development for intensive shrimp systems. Biomar Group sits within the precision nutrition specialist tier, reflecting recirculating aquaculture environment protocols developed through Danish RAS corridor partnerships.
| Leading Market Players |
|---|
| Alltech Inc |
| Aller Aqua A/S |
| Cargill Incorporated |
| BASF SE |
| Biomin GmbH |
| Nutreco NV |
| Archer Daniels Midland Co |
| Ridley Corporation |
| Biomar Group |
| Others |
Pricing and Supply Chain Analysis
Captive feed mill integration among Norwegian and Chilean salmon conglomerates anchors both supply security and pricing power through direct additive sourcing and real-time formulation control. This vertical consolidation compresses distributor margins while insulating large operators from Peruvian anchovy harvest volatility that destabilizes marine protein input costs.
Pricing Analysis
Long-term offtake agreements with volume-tiered pricing structures dominate Thai Eastern Seaboard shrimp conglomerate procurement, separating premium ASC-certified formulations from standard BAP-grade feeds and economy-tier uncertified products. Price differentiation hinges on certification grade and volume scale, with customization for species-specific life stages commanding additional premiums. Cost compression in economy tiers is intensifying because Vietnamese pangasius cooperatives replicate volume-contracting models to secure eighteen-month input predictability. Smallholder pond operators across Indonesian archipelago zones exhibit highest price sensitivity, while vertically integrated Nordic salmon producers demonstrate lowest sensitivity due to captive mill economics.
Supply Chain Analysis
Specialized aquaculture nutritionists with species-specific metabolic expertise remain scarce in Danish and Dutch recirculating system corridors, constraining formulation team scaling for precision feed manufacturers. Manufacturing gravity centers on Norway, Vietnam, and Thailand, with extrusion infrastructure concentrated in Vestland county, Cần Thơ province, and Chonburi province respectively. Raw material sourcing draws from Peruvian fishmeal, Brazilian soybean concentrate, and Danish fermented microbial biomass suppliers. Single-source vulnerability in marine protein inputs creates structural exposure to El Niño-driven anchovy harvest disruptions. Distribution runs through regional warehousing networks across Indonesian archipelago farming zones for smallholders, while direct sales channels serve consolidated Thai and Vietnamese industrial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as premium probiotic and enzyme formulations displace commodity feeds in intensive shrimp and recirculating salmon systems. Demand is shifting toward gut health optimization and pathogen resistance specifications that command sustained margin premiums.
For Market Incumbents: Deepen backward integration into alternative protein cultivation to neutralize Peruvian anchovy supply volatility, while expanding precision fermentation capacity for single-cell protein production. EFSA feed additive authorization timelines and REACH compliance documentation requirements pose regulatory barriers that favor established players with dedicated regulatory affairs infrastructure. Certification investment in simultaneous ASC, BAP, and GLOBALG.A.P. maintenance across multi-site Indonesian networks locks in export market access. For New Entrants and Emerging Players: B2B e-procurement platforms in Vietnamese Mekong Delta farming cooperatives offer the most penetrable route, compressing traditional distributor margins through price transparency and technical advisory bundling. White-space targets include microalgae omega-3 sourcing for larval nutrition and toll-milling services for regional Indonesian compounders lacking extrusion capacity. Direct-to-farm digital platforms with embedded credit extension represent the optimal go-to-market angle for scattered smallholder pond operators. For Investors and Strategic Acquirers: Roll-up economics work for European specialty additive houses because formulation talent scarcity and multi-jurisdiction regulatory compliance create natural fragmentation barriers that scale advantages can consolidate. Long-term viability centers on five-to-ten year positions in precision nutrition and alternative protein technology platforms. Acquisition target archetypes include Danish RAS-focused protocol developers and Indonesian toll manufacturers with established BAP certification. The signal to watch is EU novel food approval velocity for insect protein and microalgae ingredients, which would accelerate alternative protein substitution economics and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Protein Cultivation | Black soldier fly larvae and single-cell protein production insulate Norwegian compounders from volatile marine harvest cycles. |
| Precision Fermentation Capacity Expansion | Schizochytrium and Nannochytrium cultivation facilities enable Dutch manufacturers to displace fish oil dependence in salmonid nutrition. |
| EFSA Additive Authorization Investment | Streamlined probiotic and enzyme approval pathways accelerate functional ingredient penetration in EU member state aquaculture operations. |
| Direct-to-Farm Digital Platform Launch | B2B e-procurement channels in Vietnamese Mekong Delta cooperatives compress distributor margins through price transparency. |
| Multi-Site Certification Maintenance | Simultaneous ASC, BAP, and GLOBALG.A.P. audit management across Indonesian archipelago networks secures export market access. |
Research Methodology
Coverage spans Nordic salmon corridors, Southeast Asian shrimp clusters, and European recirculating system zones, with primary inputs from each. The approach combines structured interviews with aquaculture nutrition directors, feed mill operations managers, regulatory affairs specialists at additive houses, and procurement leads at vertically integrated farming conglomerates with secondary validation. Sources include EFSA additive registry filings, EU REACH chemical safety documentation, national aquaculture licensing records from Indonesia, Vietnam, and Thailand, and trade flow data for fishmeal and soybean concentrate imports. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Rate-of-change decomposition separates volume drivers from price-mix effects across the analysis window. The framework models segmentation dimensions including feed format, additive functional category, species target, farm scale tier, and distribution channel structure. CAGRs derive from production capacity expansion trajectories, formulation substitution elasticities, and regulatory approval velocity assumptions. Industry-specific inputs capture EFSA authorization pipeline status, Peruvian anchovy biomass survey results, and RAS infrastructure deployment rates in Denmark and the Netherlands.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation and cellular agriculture protein production would alter the outlook for marine ingredient demand and feed cost structures. Forecasts reflect assumptions about regulatory approval timelines, harvest volatility patterns, and certification adoption rates. Material deviation in EFSA additive authorization velocity, El Niño Southern Oscillation intensity, or EU Green Deal sustainability enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Organic Shrimp Market
Seafood
COD Market
Seafood
Canned Mackerel Market
Seafood
North America Seafood Market
Seafood
South America Canned Seafood Market
Seafood
Toothfish Market
Seafood
Europe Shrimp Market
Seafood
Europe Salmon Market
Seafood
United Arab Emirates Seafood Market
Seafood
European Frozen Seafood Market
Seafood
Alaskan Salmon Market
Seafood
Crustacean Market
Seafood
Global Commercial Fishing Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Seafood Processing Market
Seafood
Groundfish Market