
 Latin America Salmon Market | 2026-2036
Latin America Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Salmon Market Intelligence
Multi-source feed procurement is broadening across the Latin America salmon industry. Ventisqueros S.A. leverages integrated hatchery-to-harvest operations across southern Chile. Blumar Seafoods anchors its position through proprietary genetics programs and selective breeding lines. AquaChile S.A. dominates volume output via extensive sea-site networks in the Los Lagos region.
Latin America salmon comprises farmed Atlantic and Coho species raised in marine net-pen systems, with harvest weights typically ranging from four to six kilograms and flesh coloration graded on the SalmoFan scale from twenty to thirty-four. The primary commercial purpose centers on supplying protein for human consumption through fresh, frozen, smoked, and canned formats. Fresh product commands premium positioning in retail and food service channels, while frozen formats sustain margin pools in wholesale and export-oriented segments. Smoked salmon concentrates value-addition in processing facilities near Puerto Montt and Chiloé, with vacuum-sealed packaging extending shelf life for distant markets.
Chile's SUBPESCA enforces aquaculture concessions and environmental monitoring through the RAMA licensing system, while Brazil's MAPA and ANVISA govern import sanitation and cold-chain compliance for processed salmon entry. Peru's SANIPES and Mexico's COFEPRIS add overlapping sanitary protocols that shape cross-border trade flows. Stakeholders must monitor evolving antibiotic residue thresholds and fallowing-period mandates that determine site productivity and market access eligibility.
Market Dynamics
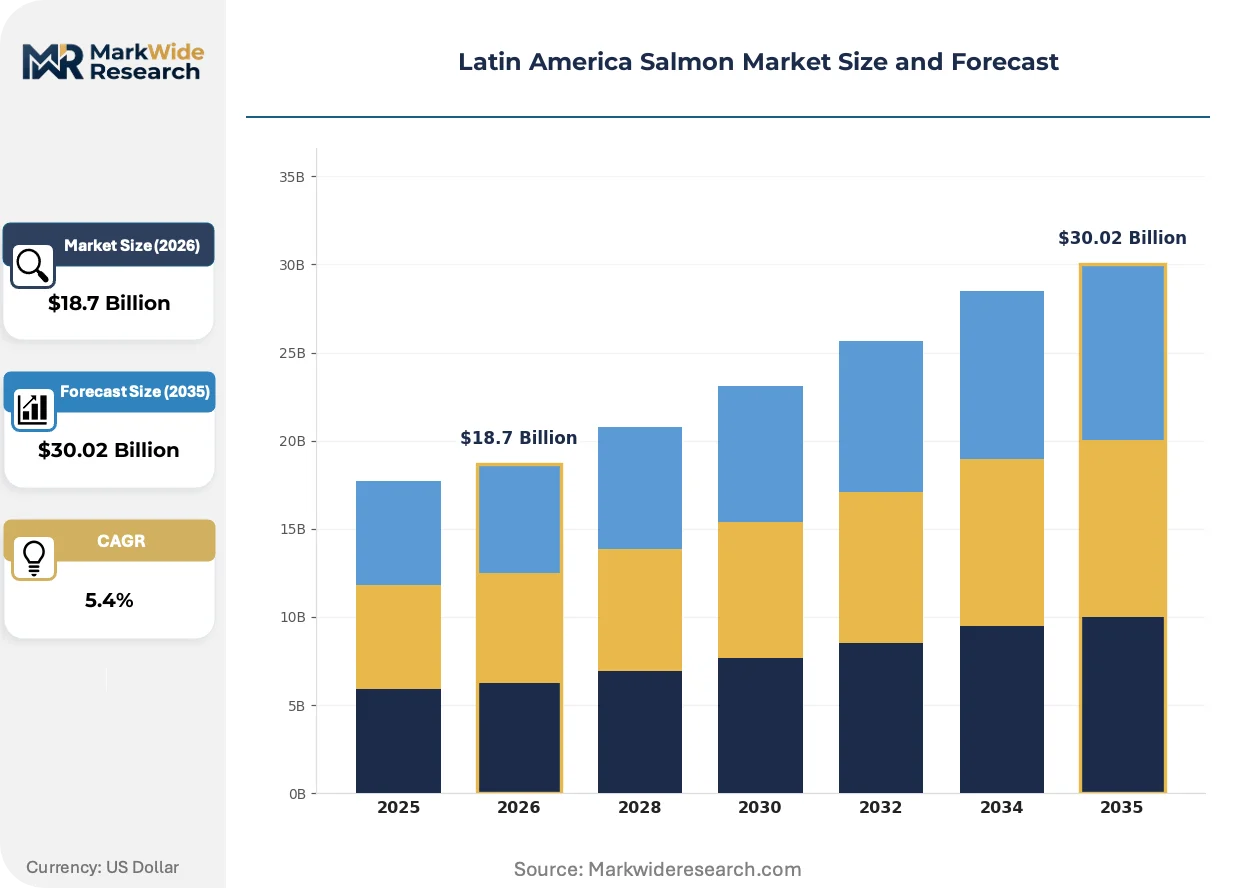
Chile's SUBPESCA concession reforms and escalating cold-chain infrastructure investments are restructuring production economics across Latin America salmon aquaculture, compressing harvest-to-market timelines and redrawing competitive boundaries between integrated operators and fragmented independents.
Growth Catalysts
- SUBPESCA RAMA Licensing Modernization:Chile's streamlined environmental monitoring protocols are accelerating site turnover rates and reducing regulatory friction for concession renewals in the Los Lagos and Aysén regions.
- Brazilian Cold-Chain Expansion:MAPA-sanctioned refrigeration corridors connecting São Paulo distribution hubs to northern retail networks are extending fresh salmon shelf-access windows and reducing frozen-format dependency.
- SalmoFan Color Grading Automation:Machine-vision flesh assessment systems are standardizing quality premiums and reducing manual grading labor intensity at processing facilities near Puerto Montt.
Market Restraints
- Feed Input Cost Volatility:Marine protein and vegetable oil price swings compress margin predictability for net-pen operators dependent on extruded pellet supply from third-party manufacturers.
- Geographic Supply Concentration:Chile's Los Lagos region accounts for disproportionate harvest volume, exposing buyers to localized algal bloom or pathogen outbreak disruption risks.
- ANVISA Sanitary Friction:Brazil's residue testing protocols and documentation requirements create import clearance delays that elevate working capital requirements for cross-border traders.
Strategic Opportunities
- Peruvian Coastal Underpenetration:SANIPES regulatory frameworks for northern Piura and Tumbes aquaculture zones remain nascent, offering first-mover positioning for Atlantic salmon pilot projects outside Chilean dominance.
- Direct-to-Processor Procurement Platforms:Digital auction systems connecting Chilean harvest cooperatives to Mexican food manufacturers are disintermediating traditional wholesale layers and capturing margin compression.
- COFEPRIS Organic Certification Pathway:Mexico's evolving antibiotic-free labeling standards create premium positioning channels for operators achieving reduced-chemotherapy production protocols.
Industry Challenges
- Veterinary Pathology Specialist Scarcity:Sea lice management and infectious salmon anemia diagnostics require trained aquatic veterinarians, with Chilean universities producing insufficient graduates for expanding site density.
- Genetic Broodstock Quarantine Complexity:Import licensing for Norwegian or Icelandic egg strains involves multi-month SANIPES and SUBPESCA approval timelines that delay selective breeding program iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Salmon Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Smoked, Canned Distribution Channel: Retail, Food Service, E-commerce, Wholesale Packaging Type: Vacuum Sealed, Tray Packs, Cans, Bulk End User: Households, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | Ventisqueros S.A., Blumar Seafoods, AquaChile S.A., Nova Austral S.A., Los Fiordos S.A., Salmones Multiexport S.A., Australis Seafoods S.A., Cermaq Group AS, Salmones Camanchaca S.A., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Salmon Market Strategic Shifts & Innovations
Automation and biological risk management technologies are compressing operational variability across Latin America salmon production, while regulatory harmonization pressures and buyer consolidation reshape value capture distribution between harvesters and processors.
Recirculating aquaculture system (RAS) hatchery modules are decentralizing smolt production geography across Chilean operations. Mid-scale Los Lagos operators are adopting closed-containment nursery systems to reduce early-stage mortality and accelerate sea-site transfer timing. This technology is decentralizing biosecurity risk away from concentrated coastal hatchery corridors and enabling inland freshwater production nodes.
Chile's SUBPESCA fallowing-period mandates and benthic impact monitoring requirements are intensifying site rotation discipline and capital deployment planning. Operators must now sequence harvest cycles across dispersed concessions to maintain continuous production volume. Smoked and value-added processing facilities near Chiloé are most affected, restructuring procurement contracts to secure raw material across irregular harvest windows.
Food service distributors in São Paulo and Mexico City are consolidating procurement authority and demanding lot-traceable delivery schedules. Large restaurant groups are displacing traditional wholesale market purchasing with direct processor relationships and contracted volume commitments. This concentration is most visible in Brazilian urban retail corridors, where cold-chain reliability guarantees now determine supplier selection ahead of spot-price competition.
Latin America Salmon Market Segmentation
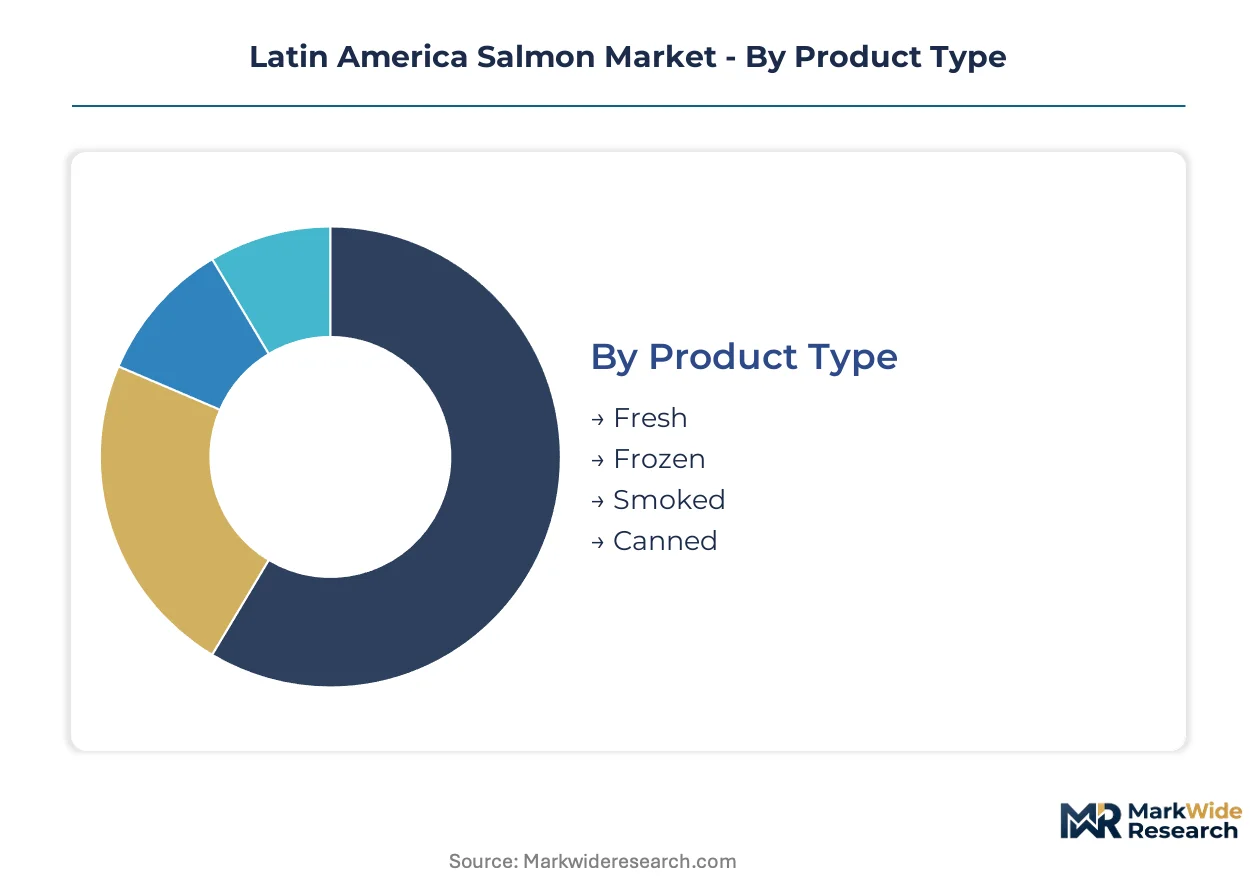
Segmentation in Latin America salmon reveals how regulatory frameworks and cold-chain capabilities fragment commercial pathways. Distinct certification burdens, shelf-life constraints, and buyer consolidation patterns shape which segments capture margin and which face commoditization pressure.
Product Type:
ANVISA residue testing protocols and SUBPESCA fallowing mandates impose divergent compliance costs across product categories, with fresh formats bearing the heaviest real-time traceability requirements.
- Fresh:Whole fish and fillets maintained at 0-2°C through MAPA-sanctioned cold chains command premium positioning in São Paulo retail corridors and Santiago restaurant supply. Brazilian urban distributors now require lot-traceable delivery schedules that displace spot-market purchasing.
- Frozen:Blast-frozen at -40°C and stored at -18°C, this format sustains margin pools in wholesale and export-oriented segments where extended shelf life compensates for lower unit pricing. Frozen dependency is declining in Brazilian corridors with refrigeration infrastructure expansion.
- Smoked:Vacuum-sealed cold-smoked products processed near Puerto Montt and Chiloé extend shelf life for distant Mexican and US markets.
- Canned:Thermally processed salmon in brine or oil serves price-sensitive household segments with minimal cold-chain requirements.
Fresh sits at the top of the volume ranking, with smoked climbing the fastest.
Distribution Channel:
Cost tier stratification separates capital-intensive direct delivery systems from fragmented intermediary networks, with margin capture shifting toward integrated operators controlling temperature integrity.
- Retail:Supermarket chains across São Paulo, Santiago, and Mexico City consolidate procurement through direct processor relationships, displacing traditional wholesale layers. Cold-chain reliability guarantees now determine supplier selection ahead of price competition.
- Food Service:Restaurant groups and hotel chains demand portion-controlled fillets with SalmoFan color consistency, creating volume concentration among certified processors capable of contracted delivery schedules.
- E-commerce:Direct-to-consumer platforms are emerging in Brazilian urban corridors, though last-mile refrigeration constraints limit geographic reach.
- Wholesale:Traditional fish markets and independent distributors serve smaller restaurants and regional retailers with higher price volatility and limited traceability.
Food service captures the steepest expansion trajectory as Brazilian and Mexican restaurant groups consolidate procurement authority.
Packaging Type:
Customer type differentiation drives format selection, with institutional buyers prioritizing handling efficiency while retail channels emphasize shelf presentation and portion control.
- Vacuum Sealed:Modified atmosphere packaging extends shelf life from days to weeks, enabling Chilean processors to supply distant Mexican markets through COFEPRIS-compliant cold chains. This format dominates smoked salmon exports from Chiloé processing facilities.
- Tray Packs:Pre-portioned fillets in modified atmosphere trays serve Brazilian supermarket chains demanding ready-to-cook convenience formats with visible SalmoFan color grading.
- Cans:Retort packaging for ambient distribution serves household pantry stocking with minimal infrastructure requirements.
- Bulk:Ice-packed whole fish in insulated containers serve food manufacturers and large caterers with in-house processing capabilities.
Vacuum sealed leads volume ranking, with tray packs gaining share fastest through Brazilian retail consolidation.
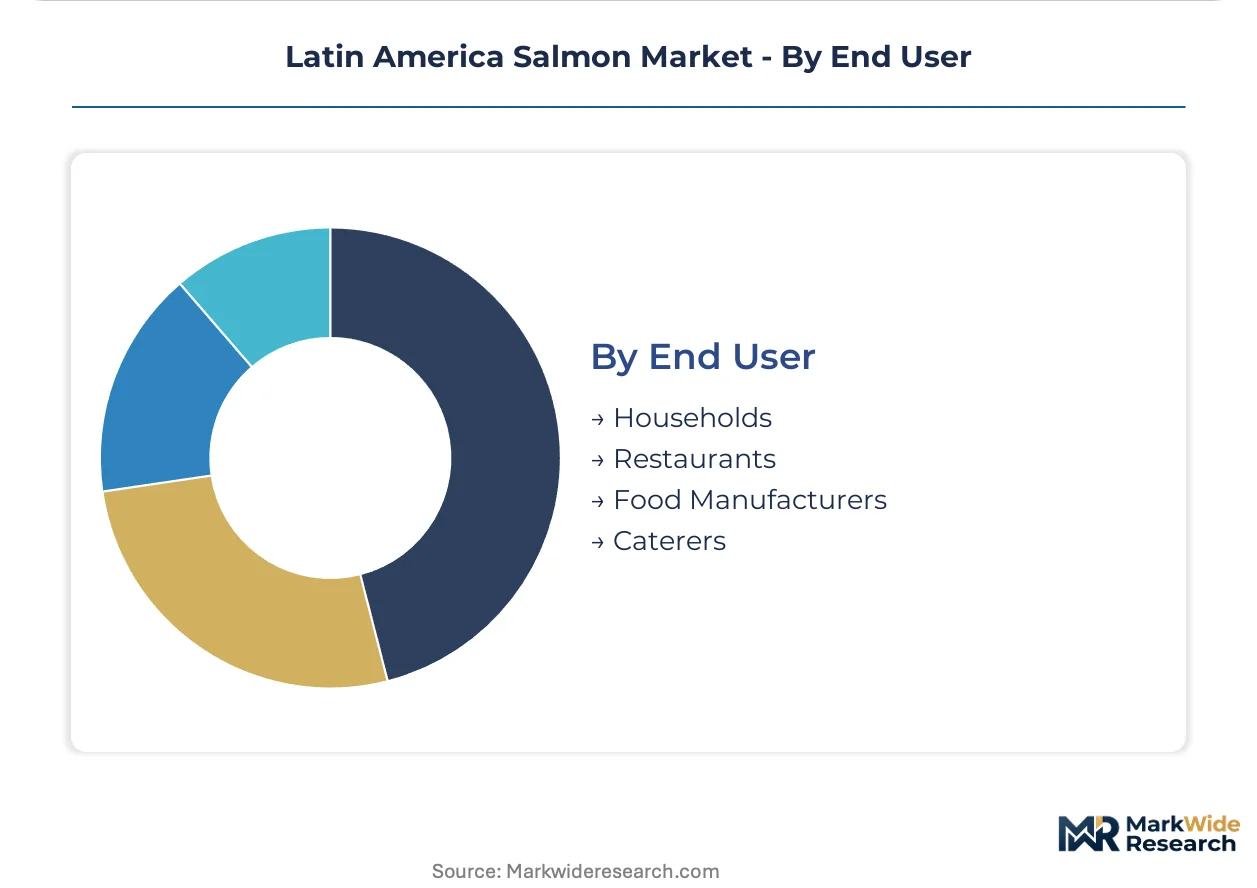
End User:
Application maturity varies sharply, with established restaurant supply networks contrasting nascent direct-to-manufacturer procurement platforms that disintermediate traditional wholesale structures.
- Households:Retail-purchased fresh and frozen fillets concentrate in Brazilian middle-income segments where cold-chain expansion has extended shelf-access windows. ANVISA-compliant labeling and origin certification increasingly influence purchase decisions.
- Restaurants:Fine-dining establishments across São Paulo and Mexico City demand specific SalmoFan grades (28-34) with documented harvest dates, creating premium tier separation from casual dining procurement.
- Food Manufacturers:Processors of ready meals and seafood products source frozen bulk formats through digital auction platforms that connect Chilean harvest cooperatives directly to Mexican production facilities.
- Caterers:Event and institutional food service operators prioritize portion consistency and reliable delivery scheduling over origin differentiation.
Restaurants anchor volume concentration, with food manufacturers expanding most quickly through direct procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Los Lagos aquaculture corridor concentrates Latin American salmon production capacity, with secondary demand nodes emerging across Brazilian urban retail networks and Mexican food service channels.
Chile
Los Lagos and Aysén regions host the continent's densest marine net-pen operations, supplying Atlantic and Coho salmon to export markets. SUBPESCA's RAMA licensing system enforces environmental monitoring and fallowing-period mandates that structure harvest cycles. Puerto Montt and Chiloé processing clusters specialize in smoked and value-added formats for North American and Asian buyers.
Brazil
São Paulo's restaurant groups and supermarket chains drive premium fresh fillet procurement through MAPA-sanctioned cold-chain corridors. ANVISA residue testing protocols and import documentation requirements create clearance friction that elevates working capital needs for Chilean exporters. Northern retail network expansion is reducing frozen-format dependency in middle-income household segments.
Mexico
Mexico City food service distributors consolidate procurement authority for portion-controlled products with SalmoFan color consistency requirements. COFEPRIS antibiotic-free labeling standards and evolving organic certification pathways create premium positioning channels for reduced-chemotherapy supply. Vacuum-sealed imports from Chiloé processors dominate distant market access.
Peru
Piura and Tumbes coastal zones remain underpenetrated for Atlantic salmon aquaculture pilot projects outside Chilean supply dominance. SANIPES regulatory frameworks for northern aquaculture concessions are nascent, offering first-mover positioning for operators achieving biosecurity compliance. Lima-based importers currently rely on Chilean frozen bulk supply for food manufacturing inputs.
Argentina
Tierra del Fuego's colder water temperatures support limited Coho salmon production for domestic consumption and selective export. Provincial environmental permits and federal fisheries coordination create multi-layer regulatory navigation for concession holders. Ushuaia processing facilities serve Buenos Aires restaurant demand through domestic air freight corridors.
Latin America Salmon Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized certification niches and direct-to-processor digital platforms. Chile's Los Lagos region concentrates integrated operators with hatchery-to-harvest capabilities alongside fragmented independents dependent on third-party smolt supply. Three archetypes dominate: vertically integrated volume leaders controlling genetics and processing, mid-scale cooperatives aggregating harvest for auction platforms, and specialist smokers commanding premium positioning in distant markets. Competitive moves center on concession consolidation through SUBPESCA license transfers and cold-chain partnerships with Brazilian distributors.
Among Chilean S.A.-structured producers, Ventisqueros S.A., AquaChile S.A., and Blumar Seafoods exemplify contrasting scale and specialization strategies. Ventisqueros S.A. represents integrated hatchery-to-harvest operations across southern Chilean sites. AquaChile S.A. occupies a position emphasizing extensive sea-site network coverage in the Los Lagos region. Blumar Seafoods anchors the genetics-forward archetype through proprietary breeding program investments. These three entities illustrate how operator configuration around biological control, geographic dispersion, or selective breeding shapes competitive positioning within SUBPESCA regulatory constraints.
| Leading Market Players |
|---|
| Ventisqueros S.A. |
| Blumar Seafoods |
| AquaChile S.A. |
| Nova Austral S.A. |
| Los Fiordos S.A. |
| Salmones Multiexport S.A. |
| Australis Seafoods S.A. |
| Cermaq Group AS |
| Salmones Camanchaca S.A. |
| Others |
Cost & Logistics Intelligence
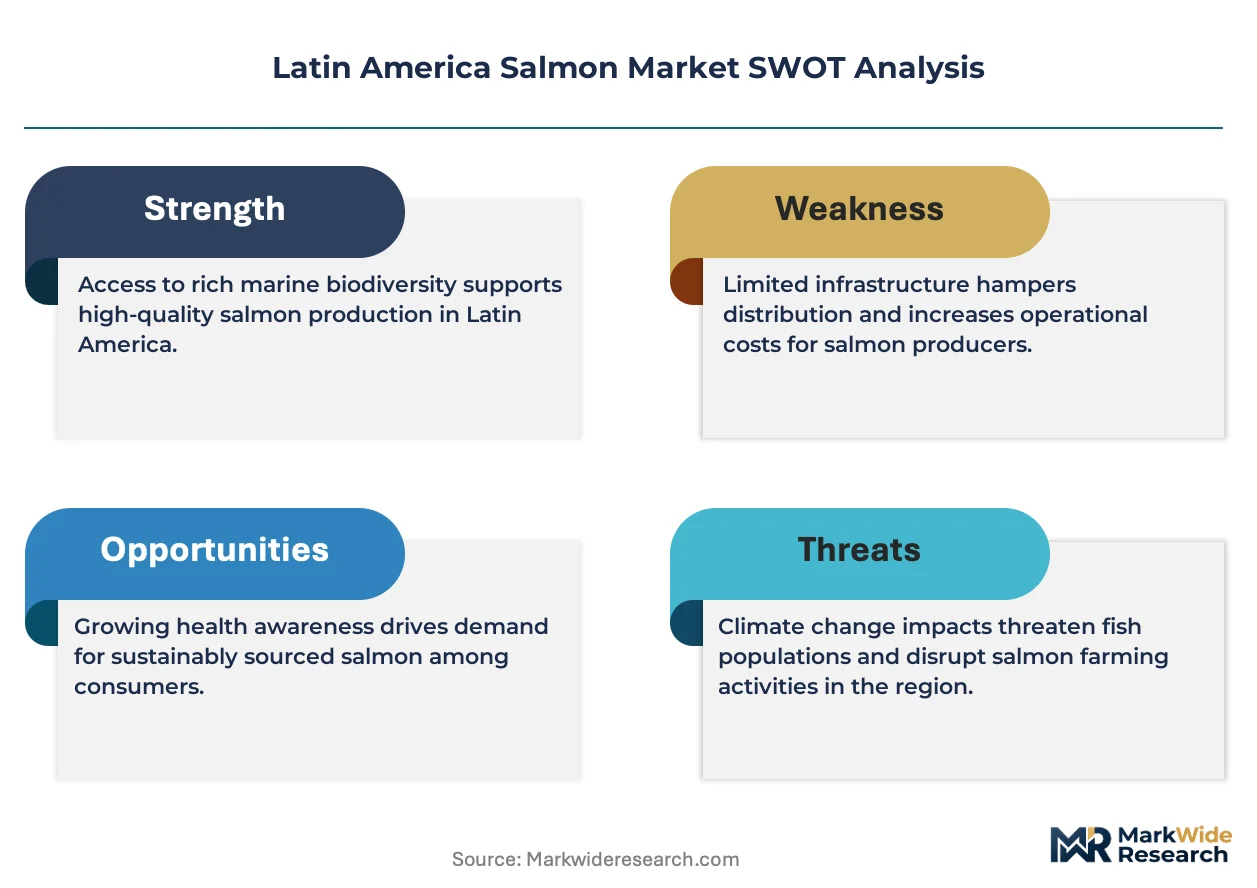
SUBPESCA fallowing-period mandates and RAMA licensing compliance requirements gate both qualified supply and premium-tier pricing access, compressing harvest windows for Los Lagos operators while rewarding certified processors with SalmoFan-grade premiums in São Paulo and Mexico City corridors.
Pricing Analysis
Input-cost pass-through from marine protein and vegetable oil volatility compresses margin predictability for net-pen operators dependent on extruded pellet supply. Pricing stratifies across premium, standard, and economy tiers based on SalmoFan color grade and organic certification status. Cost compression in frozen bulk segments is intensifying because Brazilian cold-chain expansion reduces frozen-format dependency. Food manufacturers sourcing through digital auction platforms exhibit highest price sensitivity, while fine-dining establishments in São Paulo and Mexico City demonstrate lowest sensitivity to origin-certified premiums.
Supply Chain Analysis
Workforce availability constraints for aquatic veterinarians and benthic monitoring specialists concentrate operational risk in Chile's Los Lagos and Aysén regions. Supply draws from Norwegian and Icelandic genetic broodstock imports, Peruvian Piura pilot project development, and Brazilian MAPA-sanctioned cold-chain corridors. Single-source vulnerability from Chilean harvest concentration exposes buyers to localized algal bloom disruption. Distribution runs through direct processor relationships with São Paulo supermarket chains and Mexico City food service distributors, displacing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by São Paulo and Mexico City restaurant groups consolidating procurement authority toward SalmoFan-grade portion consistency and lot-traceable delivery schedules.
For Market Incumbents: Anchor concession consolidation through SUBPESCA license transfers in Los Lagos and Aysén regions to secure continuous harvest volume across mandated fallowing cycles. Deepen cold-chain partnerships with Brazilian MAPA-sanctioned distributors to defend against emerging direct-to-processor digital platforms disintermediating wholesale layers.
For New Entrants and Emerging Players: Capture Peruvian Piura and Tumbes coastal zones where SANIPES regulatory frameworks remain nascent for Atlantic salmon pilot projects outside Chilean supply dominance. Target COFEPRIS organic certification pathways in Mexico through reduced-chemotherapy production protocols, entering via direct relationships with Mexico City food manufacturers seeking antibiotic-free labeling.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cooperatives aggregating harvest for auction platforms because buyer consolidation in Brazilian and Mexican urban corridors creates volume concentration premiums for aggregated supply. Watch SUBPESCA concession renewal timelines as inflection indicator for site productivity and qualified supply access.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Consolidation | SUBPESCA license transfers in Los Lagos secure continuous harvest across fallowing mandates. |
| Cold-Chain Partnership | MAPA-sanctioned Brazilian corridors extend fresh salmon shelf-access windows beyond frozen dependency. |
| Genetics Program Investment | Proprietary breeding lines reduce import licensing delays from Norwegian and Icelandic broodstock sources. |
| Digital Procurement Platform | Direct auction systems connecting Chilean cooperatives to Mexican manufacturers disintermediate wholesale margins. |
| Organic Certification Pathway | COFEPRIS antibiotic-free standards unlock premium positioning in Mexico City food service channels. |
Research Approach
Direct dialogue with hatchery operations managers, SUBPESCA regulatory affairs officers, São Paulo supermarket category buyers, and Chiloé processing facility directors grounded qualitative findings in operational reality. Secondary validation drew from SUBPESCA RAMA licensing databases, ANVISA import clearance records, MAPA cold-chain infrastructure disclosures, and COFEPRIS organic certification registries. Bottom-up harvest volume estimates triangulated against top-down protein consumption models across the analysis window.
Segment-level projections for fresh, frozen, smoked, and canned formats incorporated SalmoFan grading automation adoption curves, RAS hatchery deployment timelines, and Brazilian retail consolidation patterns. CAGRs derived from historical harvest-to-market flow analysis and cold-chain infrastructure investment trajectories. Model inputs included veterinary pathology specialist graduation rates from Chilean universities and genetic broodstock quarantine approval timelines from SANIPES and SUBPESCA.
Antibiotic residue threshold revisions, algal bloom frequency in Los Lagos, and Brazilian real exchange rate volatility are the dominant revision risks warranting forecast reassessment. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United States Frozen and Canned Seafood Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Middle East Seafood Market
Seafood
Tuna Fish Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Canned Salmon Market
Seafood
Shellfish Extract Market
Seafood
Fin Fish Market
Seafood
Groundfish Market
Seafood
Seafood Powders Market
Seafood
Wild Pollock Market
Seafood
Europe Shrimp Market
Seafood
COD Market
Seafood
Europe Dried Scallop Market
Seafood
Fish Processing Market
Seafood
Global Commercial Fishing Market