
 Fish Meal and Fish Oil Market | 2026-2036
Fish Meal and Fish Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Meal and Fish Oil Market Insights
EU F-Gas Regulation is shifting the cost-of-entry calculus for fish oil processors serving European aquafeed buyers. Austevoll Seafood ASA leverages its integrated North Atlantic trawling and refining footprint to sustain volume commitments across volatile quota cycles. Omega Protein Corporation anchors its position through Menhaden fishery control along the US Gulf and Atlantic coasts. Cargill, Inc. competes by extending its compound feed formulation expertise into species-specific aquaculture nutrition blends.
Fish meal and fish oil denote protein-rich and lipid-rich derivatives produced through cooking, pressing, drying, and solvent extraction of whole fish or fish trimmings, typically yielding meals with 60-72% crude protein and oils with 25-35% omega-3 fatty acid content by weight. These ingredients serve as essential nutritional inputs for farmed aquatic species, poultry, and companion animals where plant-based alternatives fail to match amino acid density or long-chain fatty acid profiles. Fish meal dominates value capture in mature aquafeed formulations where species like Atlantic salmon require fixed marine protein inclusion rates, while hydrolyzed fish protein is gaining traction in premium pet food and functional food applications where digestibility scores and clean-label positioning command margin premiums. Fish oil concentrates its profit pool in nutraceutical-grade refining for human dietary supplements, a segment where oxidation stability standards and contaminant testing protocols create steep qualification barriers.
EU F-Gas Regulation, REACH, and Norway's Seafood Research Fund sustainability criteria collectively constrain supply expansion while redirecting investment toward certified fisheries and alternative raw material streams. The US EPA and FDA jointly oversee residue limits and Good Manufacturing Practice compliance for fish meal destined for livestock and pet food channels, creating dual-track compliance obligations for exporters. Stakeholders must monitor quota negotiations in Peru and Chile, the dominant reduction fishery jurisdictions, as these bilateral determinations set the annual volume ceiling for global fish meal and fish oil availability.
Market Dynamics
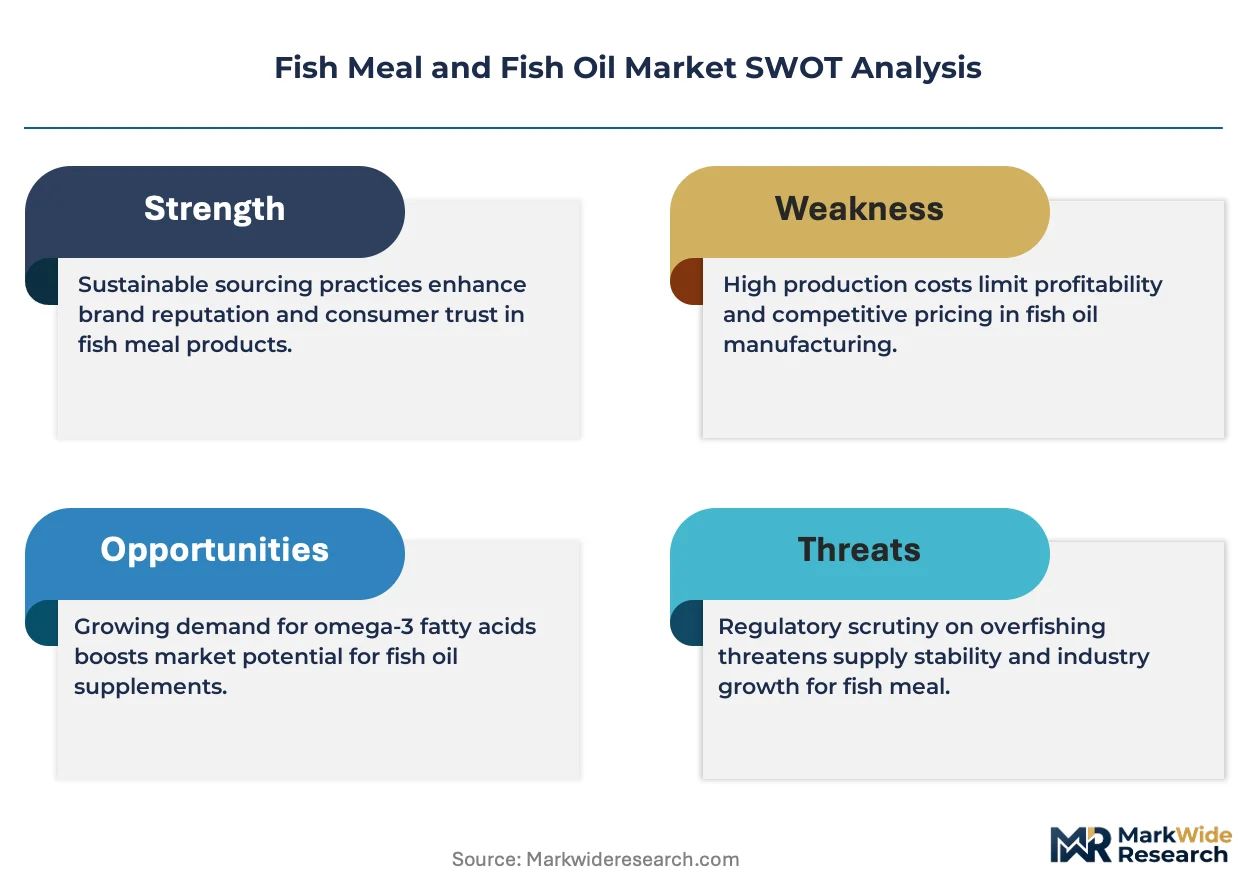
EU F-Gas Regulation and tightening sustainability certification schemes are compressing supply availability while redirecting procurement toward traceable marine inputs, forcing feed manufacturers to restructure supplier relationships around quota-constrained North Atlantic and Southeast Pacific fisheries.
Growth Catalysts
- Aquaculture feed expansion:Salmon farming operations in Norway and Chile are locking in long-term offtake agreements for premium-grade fish oil to meet fixed marine protein inclusion rates in grower diets.
- REACH compliance premiums:EU-registered aquafeed producers are paying certification premiums for Marine Stewardship Council chain-of-custody documentation to access retail-facing European markets.
- Omega-3 retention technology:Low-temperature enzymatic hydrolysis processes are preserving long-chain fatty acid integrity through the rendering chain, opening nutraceutical-grade applications.
Market Restraints
- Peru-Chile quota volatility:Annual bilateral catch determinations for anchoveta reduction fisheries impose hard volume ceilings on global fish meal availability with six-month visibility windows.
- Plant protein substitution:Fermented soybean meal and insect protein isolates are capturing formulation share in poultry and shrimp feeds where amino acid density requirements allow partial marine displacement.
- F-Gas refrigeration costs:EU processors face stepped compliance costs for cold-chain solvent extraction infrastructure, compressing margin structures for non-integrated refiners.
Strategic Opportunities
- Algae-derived EPA/DHA convergence:Photobioreactor cultivation of Schizochytrium and Nannochloropsis strains is creating non-marine omega-3 feedstocks for vegetarian-certified aquafeed positioning.
- Pet food humanization:Hydrolyzed fish protein with digestibility scores above 90% is commanding premium placement in clean-label companion animal nutrition.
- Norway Seafood Research Fund incentives:Public co-financing for closed-containment salmon systems is accelerating demand for precision-formulated marine lipid profiles.
Industry Challenges
- Marine chemist talent scarcity:Specialized expertise in oxidation stability testing and contaminant screening for nutraceutical-grade certification is concentrating among legacy refiners with in-house analytical laboratories.
- Multi-jurisdiction residue compliance:Simultaneous adherence to US FDA, EPA, and EU EFSA maximum residue limits requires parallel testing protocols that extend batch release timelines.
- Retrofitting solvent recovery systems:Capital requirements for hexane recapture infrastructure are stranding mid-scale rendering facilities without access to project finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Meal and Fish Oil Market |
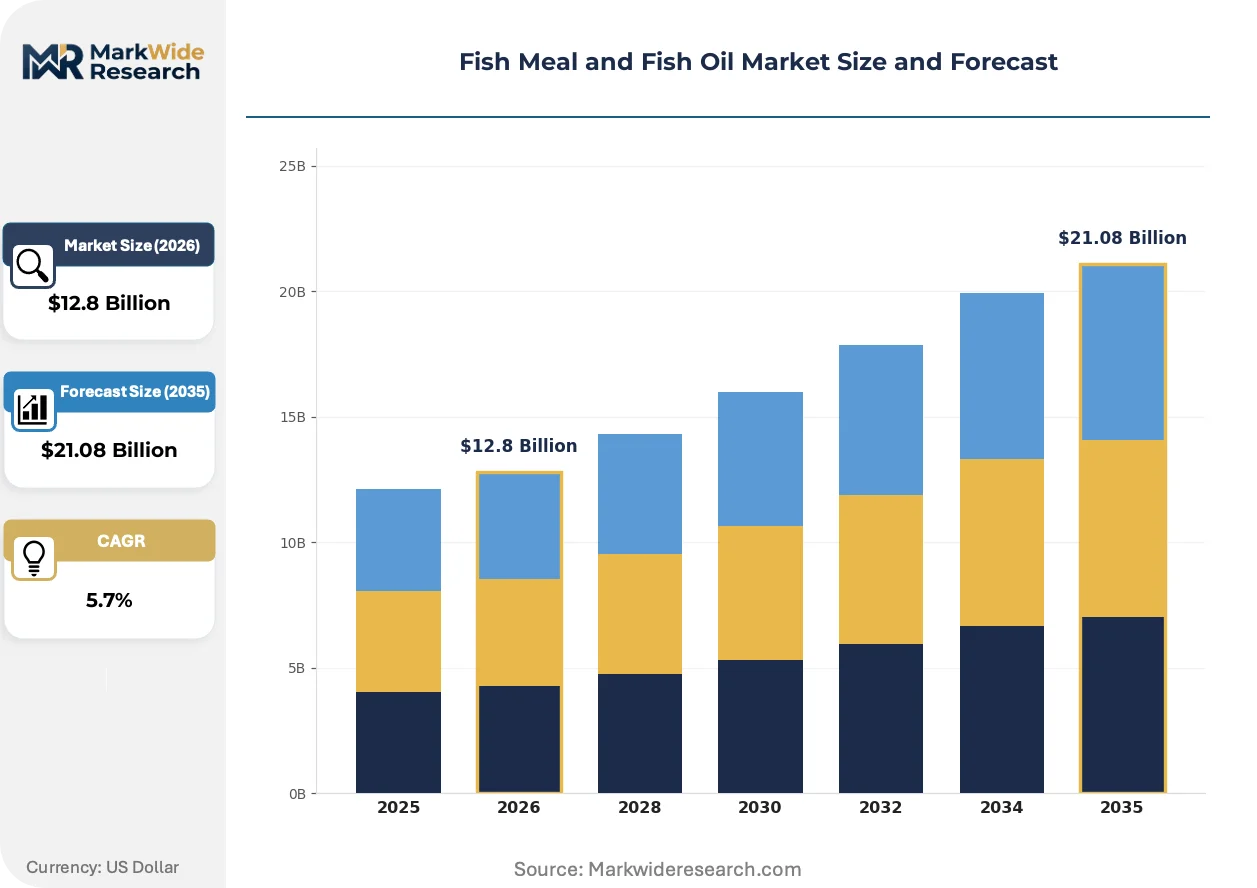
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Meal, Fish Oil, Hydrolyzed Fish Protein, Fish Solubles End User: Aquaculture, Livestock Feed, Pet Food, Nutraceuticals Application: Animal Nutrition, Dietary Supplements, Aquafeed, Functional Foods Distribution Channel: Direct Sales, Distributors, Online Retail, Export |
| Companies Covered | Omega Protein Corporation, Austevoll Seafood ASA, Tecnológica de Alimentos S.A., TripleNine Group A/S, FF Skagen A/S, Pelagia AS, FMC Corporation, Pesquera Diamante S.A., Cargill, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Meal and Fish Oil Market Trends and Innovations
Processing technology and raw material sourcing strategies are diverging between premium nutraceutical channels and commodity feed applications, with automation and alternative biomass streams compressing traditional reduction fishery dependence.
Enzymatic hydrolysis of fish trimmings is consolidating control over protein quality differentiation in premium pet food and functional ingredient channels. Specialty feed compounders in Northern Europe are adopting continuous-flow reactor systems to achieve batch-to-batch consistency in peptide molecular weight distribution. This consolidation is compressing the addressable market for standard fish meal in applications where digestibility scores determine formulation premiums.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent extraction facilities to retrofit with ammonia or CO2-based cooling systems. The industrial consequence is accelerated consolidation among processors with capital access to absorb compliance-driven capex cycles. Norwegian and Danish refiners with integrated trawling operations are capturing displaced volume from smaller Baltic competitors facing stranded asset risk.
Long-term offtake contracting is displacing spot market procurement for aquafeed manufacturers with certified sustainability commitments. Norwegian salmon integrators are locking three to five-year supply agreements directly with North Atlantic reduction fleets, bypassing traditional trader intermediaries. This disintermediation is most visible in Bergen and Aalesund clustering zones where vertical coordination between trawlers and feed mills has compressed working capital cycles for marine raw material sourcing.
Fish Meal and Fish Oil Market Segmentation
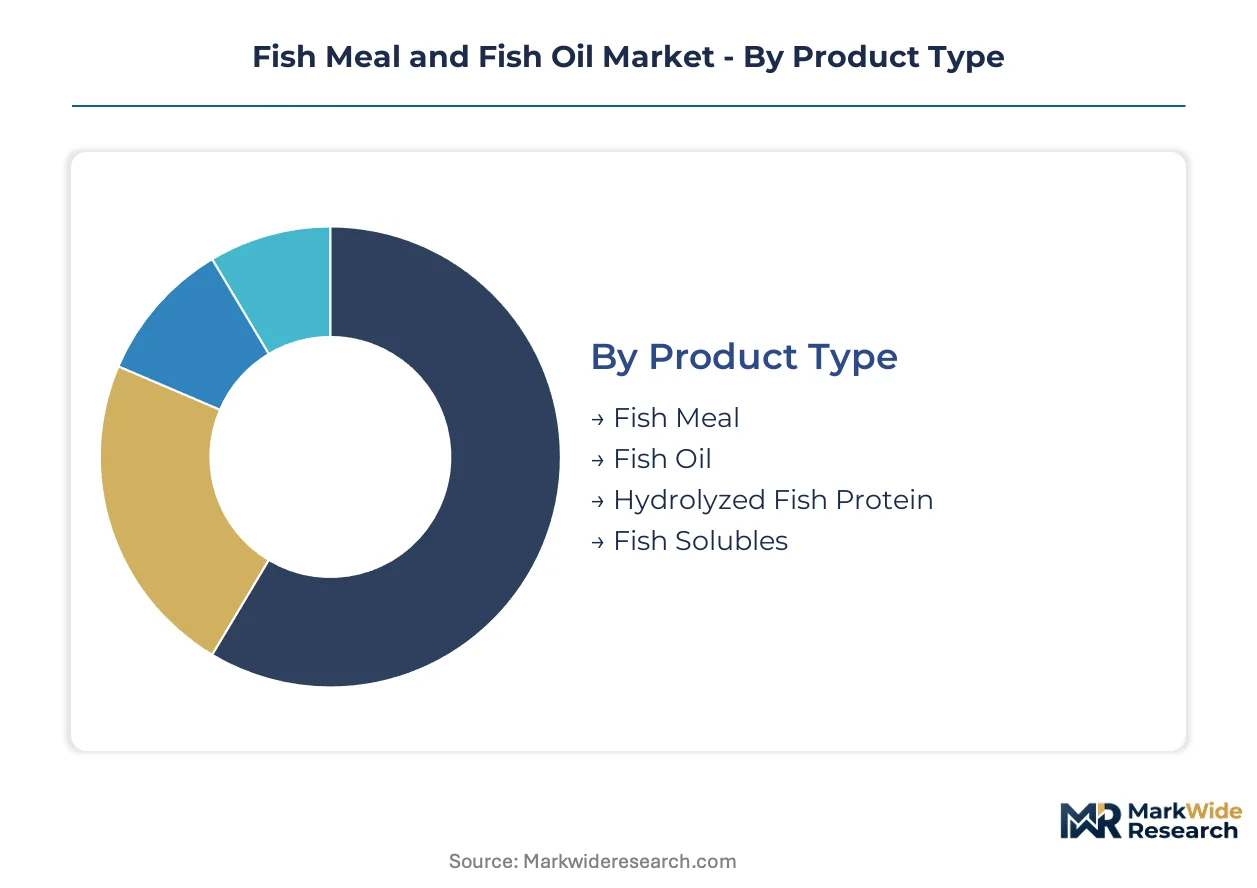
Segmentation in fish meal and fish oil markets reveals how supply chain control and processing sophistication determine margin capture. Product type stratification separates commodity feed inputs from premium nutraceutical grades, while end-user concentration in Norwegian salmon farming anchors volume commitments.
Product Type:
Supply concentration in North Atlantic and Southeast Pacific reduction fisheries shapes competitive dynamics across processing tiers.
- Fish Meal:Dried and ground powder containing 60-72% crude protein derived from whole fish or trimmings through cooking, pressing, and drying. Norwegian salmon integrators in Bergen and Aalesund clusters lock multi-year offtake agreements for premium grades with fixed marine protein inclusion mandates.
- Fish Oil:Lipid-rich extract yielding 25-35% omega-3 fatty acid content through solvent extraction or cold-pressing methods. Human dietary supplement manufacturers in Denmark and Norway pay certification premiums for oxidation-stable, contaminant-tested nutraceutical grades.
- Hydrolyzed Fish Protein:Enzymatically processed peptides with digestibility scores exceeding 90% for premium pet food applications.
- Fish Solubles:Concentrated liquid co-products from rendering processes used as palatability enhancers in livestock and aquafeed formulations.
Today's leader: Fish Meal. Tomorrow's challenger: Hydrolyzed Fish Protein.
End User:
Cost tier stratification separates commodity volume buyers from premium specification customers.
- Aquaculture:Farmed Atlantic salmon operations in Norway and Chile require fixed marine protein and lipid inclusion rates in grower diets. EU F-Gas Regulation compliance and Marine Stewardship Council chain-of-custody documentation command 15-25% procurement premiums over uncertified alternatives.
- Nutraceuticals:Human dietary supplement manufacturers demand pharmaceutical-grade refining with parallel US FDA, EPA, and EU EFSA residue testing protocols.
- Livestock Feed:Poultry and swine producers in the US Southeast and Brazil blend fish meal as amino acid-dense protein supplements where plant alternatives fall short on methionine and lysine density.
- Pet Food:Clean-label companion animal nutrition brands specify hydrolyzed fish protein for digestibility scores and palatability positioning.
Volume concentrates in Aquaculture. Margin expansion concentrates in Nutraceuticals.
Application:
Customer type fragmentation separates formulation-driven compounders from direct retail channels.
- Aquafeed:Species-specific grower diets for Atlantic salmon, rainbow trout, and marine shrimp require precision-formulated marine lipid profiles. Norway's Seafood Research Fund co-finances closed-containment systems accelerating demand for premium-grade fish oil.
- Animal Nutrition:Broiler and layer operations in the US Gulf states and Southeast Asia incorporate fish meal for starter diet amino acid density where fermented soybean meal substitution remains incomplete.
- Dietary Supplements:EPA/DHA concentrates for cardiovascular and cognitive health applications require molecular distillation and contaminant screening exceeding feed-grade specifications.
- Functional Foods:Omega-3 fortified dairy, bakery, and infant nutrition products demand taste-masked, oxidation-stable oil emulsions.
Specification intensity peaks in Dietary Supplements. Volume scale peaks in Aquafeed.
Distribution Channel:
Geography-driven channel selection reflects raw material sourcing patterns and customer concentration.
- Direct Sales:Norwegian salmon integrators contract directly with North Atlantic trawling fleets, bypassing trader intermediaries and compressing working capital cycles.
- Distributors:Regional feed compounders in Peru, Chile, and Denmark rely on specialized marine ingredient traders for quota-constrained volume allocation.
- Export:Peruvian and Chilean reduction fishery output ships to Asian aquafeed manufacturers facing domestic marine protein deficits.
- Online Retail:Direct-to-consumer nutraceutical brands in Germany and the UK bypass wholesale channels for omega-3 supplement sales.
Relationship intensity dominates Direct Sales. Reach extension dominates Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine chemists and oxidation stability specialists concentrate in North Atlantic refining clusters, anchoring premium-grade fish oil production for aquafeed and nutraceutical channels.
Norway
Salmon farming operations in Bergen and Aalesund drive premium fish oil offtake under fixed marine protein inclusion mandates. The Seafood Research Fund co-finances closed-containment systems that accelerate demand for precision-formulated marine lipid profiles. Trawler-feed mill coordination in these coastal clusters compresses working capital cycles for raw material procurement.
Denmark
Human dietary supplement manufacturers pay certification premiums for oxidation-stable, contaminant-tested nutraceutical grades. EFSA maximum residue limits and REACH compliance create dual-track testing obligations for exporters serving EU retail channels. Copenhagen-area refiners leverage integrated analytical laboratories to sustain batch-to-batch consistency in EPA/DHA concentrates.
Peru
Anchoveta reduction fisheries set annual volume ceilings on global fish meal availability through bilateral quota negotiations with six-month visibility windows. The country's national fisheries regulator oversees catch determinations that constrain supply expansion for international aquafeed manufacturers. Callao and Chimbote processing zones export the majority of output to Asian markets facing domestic marine protein deficits.
United States
Menhaden fishery control along the Gulf and Atlantic coasts anchors volume commitments for livestock and pet food channels. EPA and FDA jointly oversee residue limits and Good Manufacturing Practice compliance, creating parallel testing protocols for exporters. Reedville, Virginia and Moss Point, Mississippi reduction facilities concentrate rendering capacity for domestic poultry and swine starter diet formulations.
Chile
Salmon farming operations in the Los Lagos and Aysén regions lock long-term offtake agreements for premium-grade fish oil to match Norwegian supply security models. Bilateral quota coordination with Peru on shared anchoveta stocks introduces volatility in raw material access for local processors. Puerto Montt and Chonchi industrial zones house enzymatic hydrolysis capacity serving digestibility-score premiums in export markets.
Fish Meal and Fish Oil Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered processing segments. The vendor base stratifies between integrated North Atlantic trawler-refiners, Southeast Pacific reduction fleet operators, and compound feed formulators extending into marine ingredient blending. Three archetypes dominate: quota-integrated harvesters with captive raw material access, nutraceutical-grade refiners with in-house oxidation stability testing, and aquafeed compounders backward-integrating into marine protein sourcing. Competitive moves concentrate on long-term offtake contracting and solvent recovery infrastructure retrofitting.
Among quota-integrated harvesters, Omega Protein Corporation exemplifies the US Gulf-Atlantic archetype through menhaden fishery control. Austevoll Seafood ASA represents the North Atlantic integrated model with trawling and refining coordination. Cargill, Inc. occupies the diversified compounder position, extending feed formulation expertise into species-specific aquaculture nutrition blends. These three anchors illustrate how raw material access, processing sophistication, and distribution reach determine margin capture across volatile quota cycles.
| Leading Market Players |
|---|
| Omega Protein Corporation |
| Austevoll Seafood ASA |
| Tecnológica de Alimentos S.A. |
| TripleNine Group A/S |
| FF Skagen A/S |
| Pelagia AS |
| FMC Corporation |
| Pesquera Diamante S.A. |
| Cargill, Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned trawler operations in Norway and Denmark maintain disciplined long-term offtake contracting with salmon integrators, anchoring pricing stability through captive raw material access while compressing spot market liquidity for non-integrated processors facing F-Gas compliance capex cycles.
Pricing Analysis
Long-term contract premiums separate bundled sustainability certification from unbundled commodity spot procurement. Three-tier pricing structure across premium, standard, and economy levels reflects Marine Stewardship Council chain-of-custody status, oxidation stability grades, and volume commitment scale. Pricing pressure stems from algae-derived EPA/DHA convergence threatening nutraceutical-grade fish oil premiums. Spot buyers in Asian aquafeed manufacturing show highest price sensitivity; Norwegian salmon integrators with fixed marine protein mandates absorb certification premiums with least elasticity.
Supply Chain Analysis
Anchoveta biomass availability rests on Peru-Chile bilateral quota negotiations with six-month visibility windows, tethering global fish meal volume ceilings to volatile political fishery management. Raw material dependencies center on North Atlantic capelin, Southeast Pacific anchoveta, and US Gulf menhaden stocks. Single-source vulnerability concentrates in Peruvian reduction fleet output serving Asian aquafeed deficits. Distribution runs through direct trawler-mill coordination in Bergen-Aalesund clusters and specialized marine ingredient traders for quota-constrained volume allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by fixed marine protein inclusion mandates in Atlantic salmon grower diets that resist complete substitution across the analysis window.
For Market Incumbents: Anchor quota-integrated positions through multi-year trawler fleet commitments in North Atlantic fisheries, defending against algae-derived omega-3 displacement in nutraceutical channels. Prioritize solvent recovery infrastructure retrofitting to absorb F-Gas Regulation compliance costs that strand non-integrated Baltic competitors. Certification investment in Marine Stewardship Council chain-of-custody documentation preserves premium tier access for EU retail-facing aquafeed sales. For New Entrants and Emerging Players: Enter via enzymatic hydrolysis specialization targeting premium pet food digestibility-score premiums where legacy fish meal processors lack peptide molecular weight consistency capabilities. White-space concentrates in clean-label companion animal nutrition and functional food emulsion systems. Go-to-market leverage rests on photobioreactor cultivation partnerships for vegetarian-certified aquafeed positioning bypassing marine quota constraints entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Baltic refiners facing stranded asset risk from F-Gas refrigeration retrofit requirements without project finance access. Long-term viability favors integrated North Atlantic harvester-refiners with captive raw material access and in-house oxidation stability testing laboratories. Watch Peru-Chile quota negotiation timing as inflection trigger for global fish meal availability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct trawler-mill coordination in Norway compresses working capital cycles for salmon integrators. |
| Backward Integration | Captive North Atlantic fleet access insulates processors from volatile Peru-Chile quota cycles. |
| Green Manufacturing Transition | Ammonia and CO2-based cooling retrofits satisfy EU F-Gas Regulation phase-down schedules. |
| Capacity Expansion | Enzymatic hydrolysis investments capture digestibility-score premiums in premium pet food channels. |
| Joint Venture | Photobioreactor partnerships with algae cultivators create non-marine omega-3 feedstock alternatives. |
Research Methodology
Coverage spans Norway, Denmark, Peru, Chile, and the United States, with primary inputs from each combining executive interviews with aquafeed procurement directors, marine refinery operations managers, fisheries regulatory officials, and sustainability certification auditors alongside secondary validation through customs trade data, national fisheries institute catch reports, Marine Stewardship Council chain-of-custody databases, and SEC filings from publicly traded processors. Bottom-up volume modeling triangulates against top-down industry association aggregates.
Granularity-level framing applies species-specific marine inclusion rate modeling by salmon grower diet stage, certification tier stratification, and regional production cluster economics across the projection horizon. CAGRs derive from quota-constrained supply elasticity functions and demand substitution elasticity estimates for algae-derived alternatives. Industry-specific inputs include Peru-Chile anchoveta biomass forecasts and EU F-Gas Regulation compliance cost curves for solvent extraction infrastructure.
The model holds under stable bilateral fishery management cooperation; deviation in Peru-Chile quota negotiation breakdowns or accelerated algae omega-3 cost parity would shift availability and pricing trajectories. Forecasts reflect documented assumptions regarding marine protein substitution resistance in Atlantic salmon diets. A small set of named triggers—quota volatility, refrigerant regulation enforcement intensity, and photobioreactor scale economics—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
COD Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Processed Seafood Market
Seafood
Fish Protein Concentrate Market
Seafood
Fish Oil Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Global Smoked Fish Market
Seafood
Canned Fishery Product Market
Seafood
Canned Seafood Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Rainbow Trout Market
Seafood
Fish Protein Market
Seafood
United States Seafood Market
Seafood
Seafood Flavors Market
Seafood
Food Clamshells Market
Seafood
Fish Nutrition Market