
 Europe Salmon Market | 2026-2036
Europe Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Salmon Market Intelligence
Subscription-based traceability services is restructuring what European salmon producers sell, shifting contracts from commodity volume to verified provenance tiers. Mowi ASA leverages its integrated feed-to-fork infrastructure to control quality consistency across North Sea operations. SalMar ASA anchors its competitive position through offshore farming technology leadership at its Ocean Farm sites. Lerøy Seafood Group ASA specializes in premium smoked and pre-portioned products for Scandinavian retail channels.
Europe salmon comprises anadromous fish of the genus Salmo salar, typically harvested at 4-6 kg whole-body weight after 14-22 month grow-out cycles in marine net pens or land-based tanks, prized for omega-3 fatty acid content and protein density in human nutrition. Fresh salmon dominates value capture in supermarket and fish market channels where per-kilo premiums reflect harvest-to-shelf speed. Smoked salmon represents the fastest-growing product type as portion-pack formats penetrate breakfast and appetizer occasions across British and German households. Vacuum-sealed packaging concentrates margin pools by extending shelf life and enabling direct-to-consumer online retail expansion.
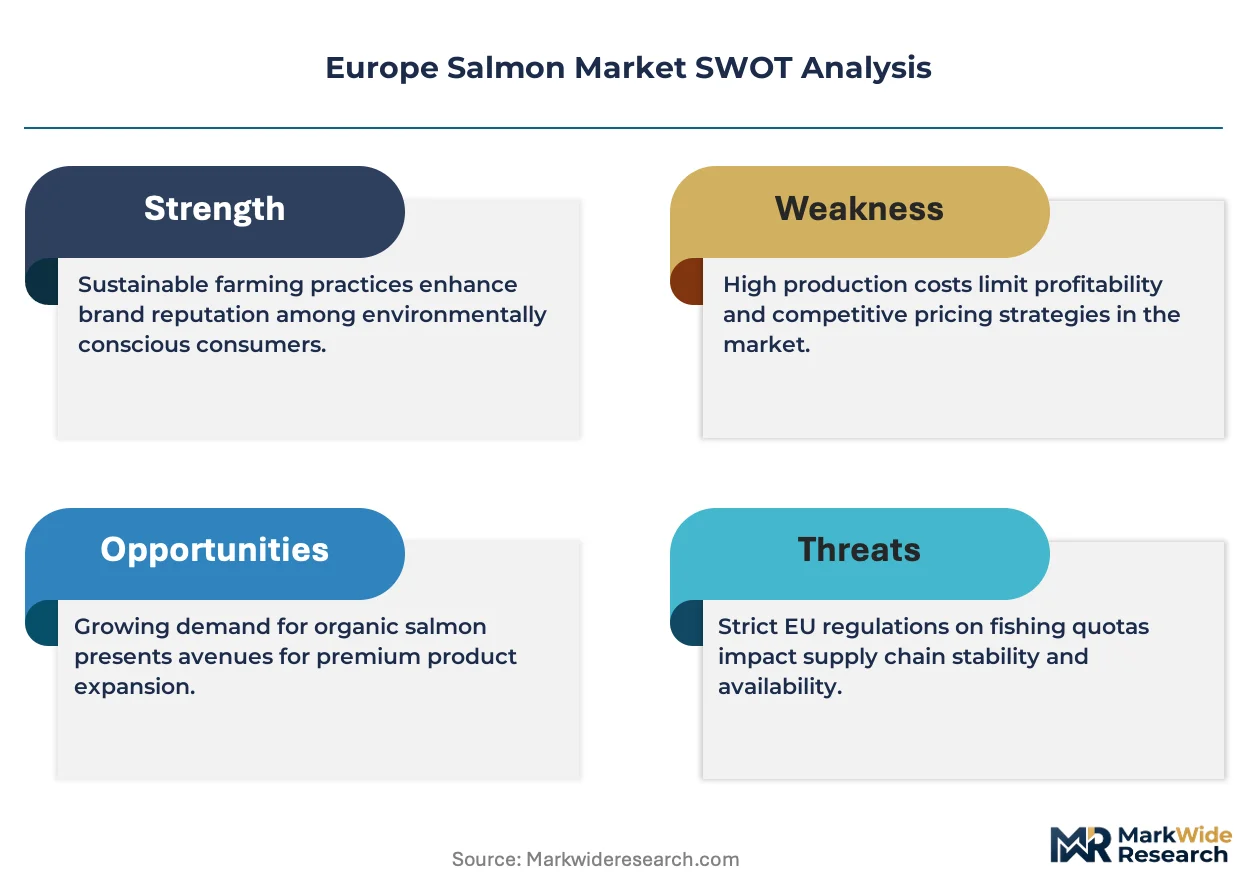
The EU's Common Fisheries Policy and EFSA food safety standards govern harvest quotas, veterinary residue limits, and labeling requirements that shape market access for Norwegian and Scottish producers. REACH chemicals regulation and national coastal zone permits from Norway's Directorate of Fisheries constrain expansion of conventional open-pen farming, redirecting capital toward closed-containment innovation. Stakeholders must monitor how the EU Green Deal's nutrient runoff caps and emerging animal welfare directives recalibrate cost structures across fjord and land-based production systems.
Market Dynamics
Land-based recirculating aquaculture systems are compressing the dominance of Norwegian fjord-based open-pen farming, forcing capital reallocation toward closed-containment infrastructure as coastal zone permits tighten under EU Green Deal nutrient runoff caps.
Growth Catalysts
- EFSA food safety standards:Mandatory residue testing protocols elevate certified Norwegian and Scottish salmon above uncertified imports in German and French retail channels.
- Smoked salmon portion-pack formats:British and German breakfast and appetizer occasions drive volume expansion through vacuum-sealed convenience packaging.
- Oslo-Petroleum Fund aquaculture allocation:Sovereign wealth capital flows concentrate on offshore farming technology clusters along Norway's central coast.
Market Restraints
- Fishmeal and fish oil price volatility:Peruvian anchovy harvest fluctuations transmit directly to Norwegian feed cost structures, compressing farm-gate margins.
- Norwegian Directorate of Fisheries coastal permits:Moratorium expansions in Troms and Finnmark constrain conventional net-pen capacity additions.
- Plant-based seafood analogues:Nordic consumer trial rates for mycoprotein and algae-derived alternatives divert trial budgets from conventional salmon.
Strategic Opportunities
- Polish and Romanian retail underpenetration:Supermarket salmon sections in Warsaw and Bucharest remain underdeveloped relative to Western European assortment density.
- EU Green Deal circular bioeconomy incentives:Subsidized capital expenditure programs for land-based RAS installations redirect public funding toward closed systems.
- Blockchain-IoT traceability convergence:Real-time harvest-to-retail data streams enable subscription-based provenance verification for Scandinavian direct-to-consumer channels.
Industry Challenges
- Marine biologist and veterinary specialist shortages:Norwegian university aquaculture program enrollment lags behind RAS facility staffing requirements.
- Offshore farming platform certification timelines:DNV-GL and Bureau Veritas structural approval processes extend Ocean Farm-class deployment schedules.
- Legacy open-pen workforce retraining:Fjord-based technicians require reskilling for automated land-based tank monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Salmon Market |
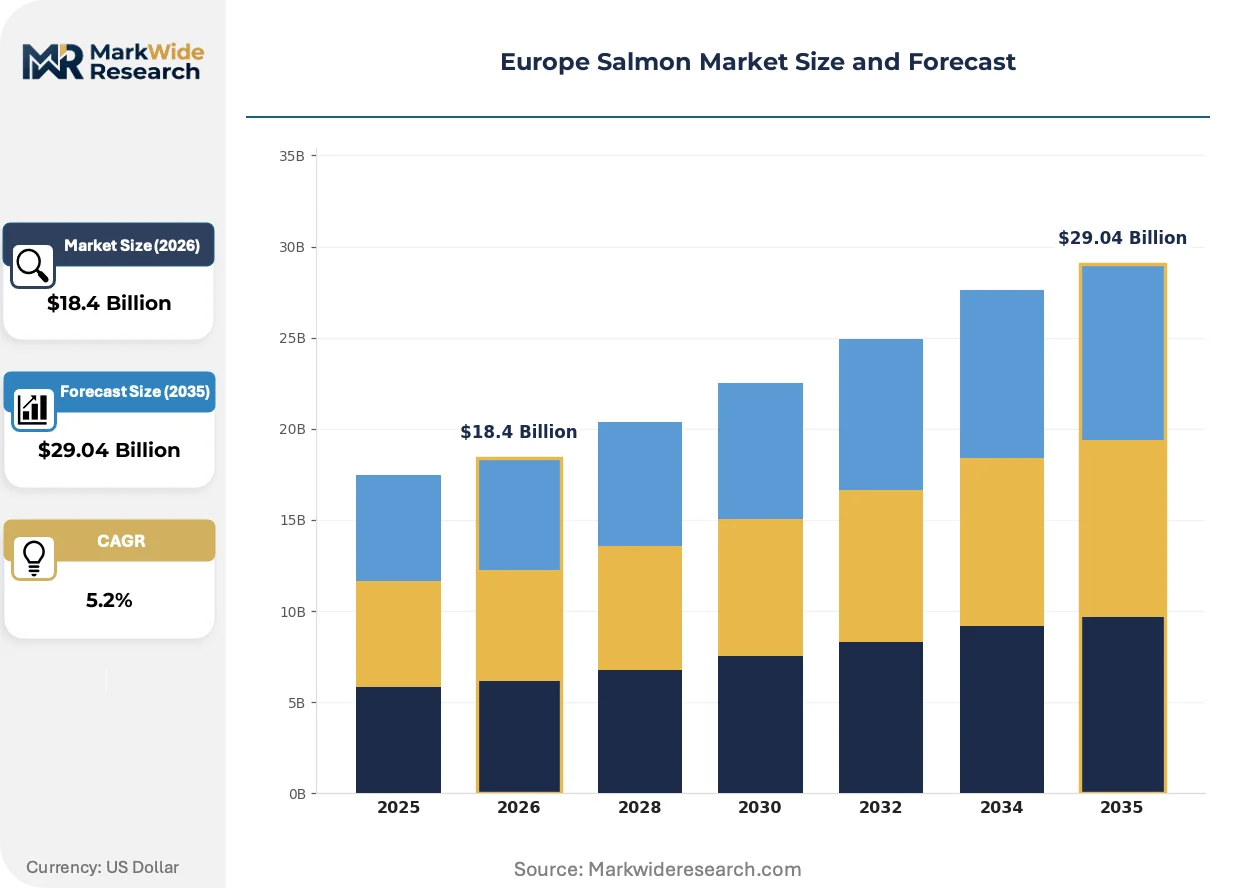
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $29.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Salmon, Frozen Salmon, Smoked Salmon, Canned Salmon Distribution Channel: Supermarkets, Online Retailers, Fish Markets, Restaurants End User: Households, Food Service, Retailers, Food Manufacturers Packaging Type: Bulk Packaging, Vacuum Sealed, Tray Pack, Portion Pack |
| Companies Covered | Mowi ASA, SalMar ASA, Lerøy Seafood Group ASA, Cermaq Group AS, Grieg Seafood ASA, Bakkafrost, Nordlaks, Scottish Sea Farms, Austevoll Seafood ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Salmon Market Strategic Shifts & Innovations
Biological and digital technologies are simultaneously reshaping production economics and consumer interface models across the European salmon value chain.
Post-smolt RAS nursery systems are overtaking traditional marine grow-out for the initial 1-2 kg weight gain phase. Scottish processors including those supplying Sainsbury's and Tesco are contracting for land-raised juvenile supply to shorten marine exposure windows. This technology compression is reducing sea lice treatment frequency and veterinary intervention costs across Highland farming corridors.
REACH chemicals regulation amendments are restricting formaldehyde-based bath treatments for sea lice control in Norwegian waters. Industrial consequence forces adoption of mechanical delousing and warm-water flushing technologies at harvesting facilities. Scottish producers face parallel pressure from Marine Scotland's environmental quality objectives, accelerating investment in non-chemical parasite management.
Subscription-based traceability services are replacing commodity spot purchasing among German food service distributors. Metro AG and similar wholesalers are unbundling traditional volume contracts into tiered provenance tiers with embedded origin verification. This procurement model evolution concentrates most visibly in Berlin and Hamburg restaurant supply chains where menu transparency commands premium positioning.
Europe Salmon Market Segmentation
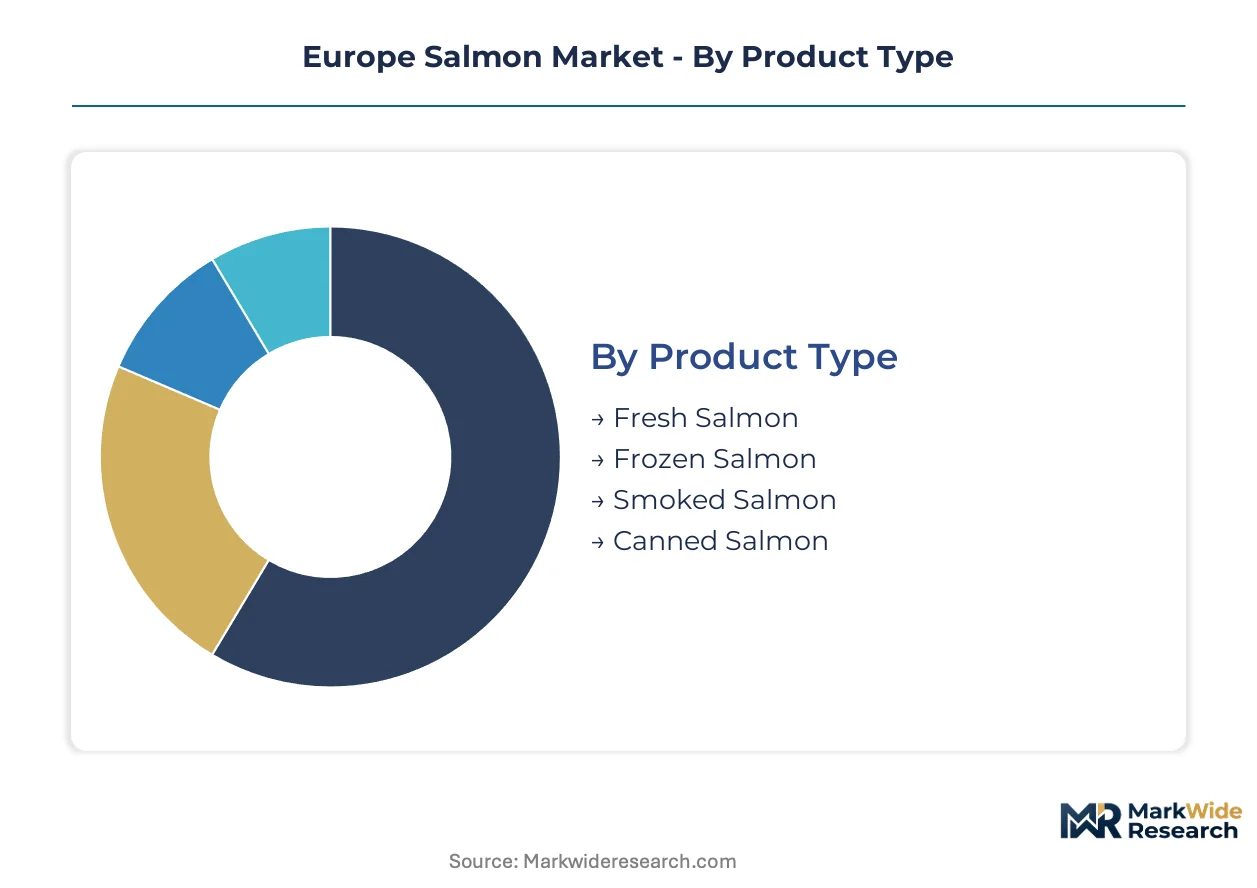
European salmon procurement patterns fragment across four distinct axes, each commanding different margin structures and supply chain configurations. Producers and distributors must align product formats with channel-specific velocity requirements and end-user preparation preferences.
Product Type:
Species handling protocols and shelf-life engineering define competitive positioning across the four primary product categories.
- Fresh Salmon:Whole-gutted or filleted fish maintained at 0-4°C through harvest-to-retail cold chains. Norwegian fjord-origin fresh salmon commands per-kilo premiums in Paris and Hamburg supermarket channels where harvest-to-shelf speed determines placement.
- Smoked Salmon:Cold-smoked or hot-smoked fillets processed through controlled wood-smoke exposure. British and German breakfast occasions and appetizer formats drive volume expansion through vacuum-sealed convenience packaging in Berlin and London retail corridors.
- Frozen Salmon:Blast-frozen at -18°C for extended distribution reach. Polish and Romanian supermarket channels rely on frozen supply to offset underdeveloped fresh cold chain infrastructure in Warsaw and Bucharest.
- Canned Salmon:Thermally processed and shelf-stable for ambient storage. Southern European pantry stocking and emergency food reserve purchasing sustains residual demand in Spanish and Italian retail.
Fresh salmon leads on scale; smoked salmon leads on momentum.
Distribution Channel:
Channel selection dictates margin capture speed and traceability investment intensity.
- Supermarkets:Multi-banner retail chains with dedicated fish counters and pre-pack sections. German REWE and Edeka networks concentrate volume through centralized procurement and private-label salmon programs.
- Online Retailers:Direct-to-consumer platforms with subscription and same-day delivery capabilities. Scandinavian urban corridors in Oslo and Copenhagen show highest penetration for traceability-verified home delivery.
- Fish Markets:Traditional wet markets and municipal fish halls with whole-fish display. Scottish Highland processing corridors supply whole-gutted salmon to Edinburgh and Glasgow market halls.
- Restaurants:Food service operators from fine dining to fast-casual. French and German restaurant groups are expanding salmon menu placements across Berlin and Lyon metropolitan dining scenes.
Supermarkets dominate volume throughput; online retailers are climbing the fastest.
End User:
Final consumption context shapes portion sizing, packaging, and certification requirements.
- Households:Residential consumers purchasing for home meal preparation. British and German households show strongest adoption of smoked salmon portion-packs for breakfast and weekend dining occasions.
- Food Service:Restaurants, hotels, and catering operations requiring consistent supply. Metro AG and similar wholesalers in Hamburg and Berlin are unbundling contracts into tiered provenance tiers with embedded origin verification.
- Retailers:Supermarket and specialty food store operators reselling to consumers. Sainsbury's and Tesco in the UK contract for land-raised juvenile supply to shorten marine exposure windows.
- Food Manufacturers:Processed food and ready-meal producers incorporating salmon as ingredient. Ready-meal producers in France and Germany source frozen salmon for pasta, pie, and salad applications.
Households anchor demand volume; food service shows steepest expansion trajectory.
Packaging Type:
Packaging engineering directly determines shelf-life extension and channel accessibility.
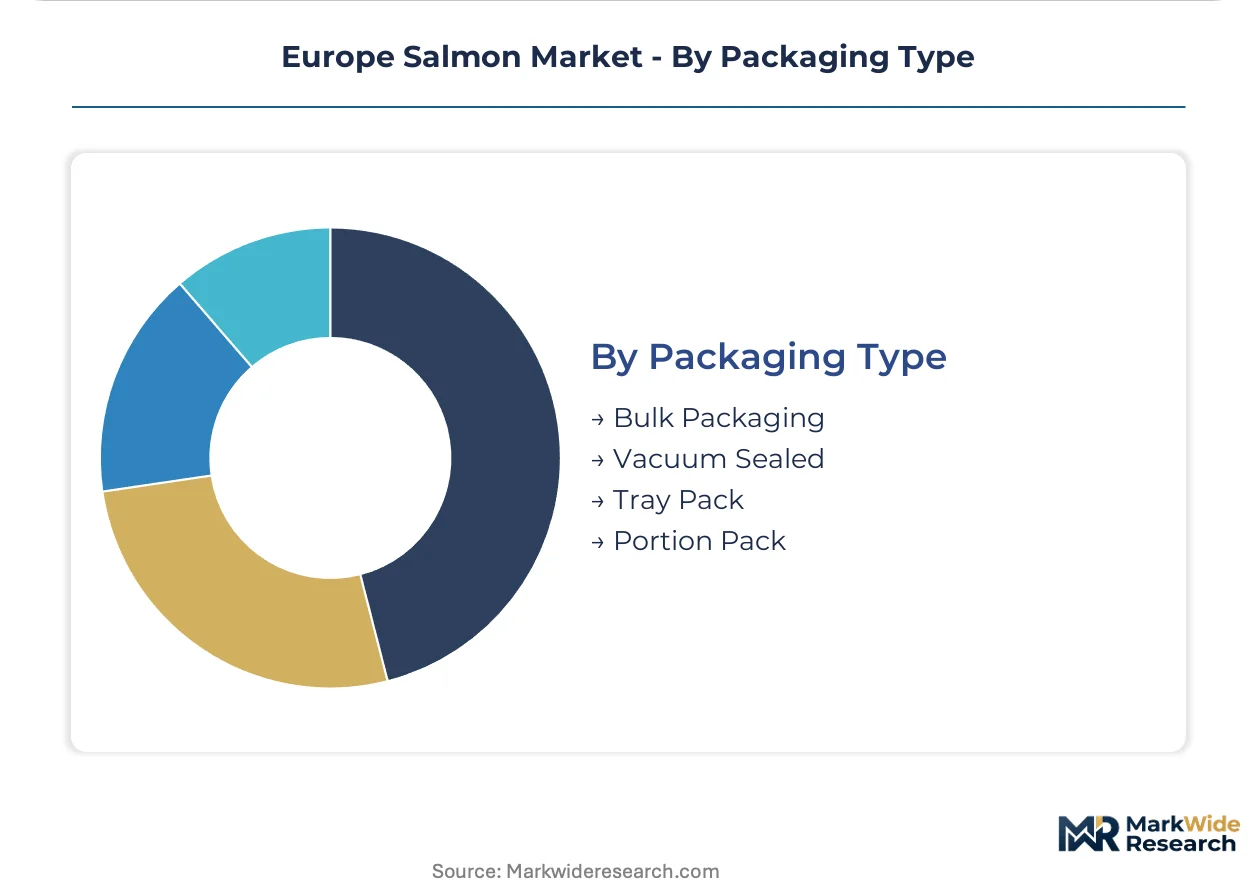
- Vacuum Sealed:Oxygen-extracted barrier films for extended refrigerated life. Concentrates margin pools by enabling direct-to-consumer online retail expansion across Scandinavian channels.
- Portion Pack:Single-serve or dual-serve pre-cut formats. Breakfast and appetizer occasions in British and German households drive fastest adoption for convenience-oriented consumption.
- Tray Pack:Modified-atmosphere overwrap on foam or recyclable trays. Dominates fresh salmon presentation in French and German supermarket fish counters.
- Bulk Packaging:Whole-fish or large fillet formats for food service and processing. Scottish processors supply whole-gutted salmon in insulated containers to Highland farming corridor distribution hubs.
Vacuum sealed commands premium positioning; portion packs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands the highest farm-gate output per capita while Germany dominates continental consumption volume, creating a supply-demand asymmetry that shapes cross-border trade flows across the North Sea basin.
Norway
Coastal municipalities in Troms and Finnmark host the densest concentration of licensed net-pen sites, with Bergen-based processors commanding premium export pricing into German retail channels. The Norwegian Directorate of Fisheries enforces strict coastal zone moratoriums that redirect capital toward offshore farming pilots. Trøndelag county anchors technology development clusters where Ocean Farm-class platforms undergo sea trials.
Germany
REWE and Edeka procurement networks absorb the largest share of Norwegian fresh fillet imports, with Hamburg and Berlin food service distributors unbundling contracts into traceability-verified tiers. EFSA residue testing protocols elevate certified Norwegian salmon above uncertified alternatives in supermarket placement. The North Sea port of Bremerhaven concentrates cold-chain logistics infrastructure for re-export into Polish and Czech markets.
United Kingdom
Scottish Highland farming corridors supply whole-gutted salmon to Edinburgh and Glasgow municipal fish halls while Sainsbury's and Tesco contract for land-raised juvenile supply. Marine Scotland environmental quality objectives accelerate non-chemical parasite management investment. Shetland processing sites specialize in premium smoked output for London metropolitan retail.
France
Parisian supermarket fish counters command per-kilo premiums for rapid harvest-to-shelf Norwegian origin salmon, with Lyon restaurant groups expanding raw and lightly cured menu placements. ANSM veterinary residue surveillance aligns with EFSA standards to restrict non-compliant import channels. Brittany ports handle secondary processing for Spanish and Italian re-export.
Poland
Warsaw supermarket salmon sections remain underdeveloped relative to Western European assortment density, creating whitespace for frozen and vacuum-sealed format penetration. National food safety inspections implement EU-harmonized protocols that ease Norwegian supplier market access. Gdańsk cold storage terminals aggregate Baltic re-distribution to Romanian and Bulgarian emerging markets.
Europe Salmon Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated feed-to-fork operators commanding margin pools in premium channels while volume processors serve price-sensitive retail tiers. Market concentration tilts toward Norwegian and Scottish coastal clusters where fjord access and processing infrastructure create geographic moats. Three archetypes dominate: vertically integrated aquaculture conglomerates with captive hatchery and feed operations; specialist smokers and portion-pack processors serving branded retail programs; and emerging land-based RAS operators capturing Green Deal subsidy flows. Competitive dynamics center on offshore farming technology licensing and automated processing capacity expansion.
Within the integrated conglomerate tier, Mowi ASA and SalMar ASA exemplify scale-driven positioning across North Sea production corridors. Among specialist processors, Lerøy Seafood Group ASA occupies a branded premium position in Scandinavian retail channels. These three entities anchor competitive intensity through differentiated control over feed sourcing, farming technology, and distribution reach.
| Leading Market Players |
|---|
| Mowi ASA |
| SalMar ASA |
| Lerøy Seafood Group ASA |
| Cermaq Group AS |
| Grieg Seafood ASA |
| Bakkafrost |
| Nordlaks |
| Scottish Sea Farms |
| Austevoll Seafood ASA |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EFSA-verified Norwegian origin and uncertified Baltic alternatives manifests in per-kilo premiums at Hamburg supermarket counters while simultaneously compressing procurement timelines for German food service distributors seeking traceability-guaranteed supply. This bifurcation rewards integrated feed-to-fork operators with pricing power in premium channels while forcing spot-market traders toward thinner margins in frozen bulk formats.
Pricing Analysis
Capacity additions in Polish cold storage terminals are reshaping price floors for frozen salmon re-export into Romanian and Bulgarian emerging markets. Three-tier pricing structure across premium, standard, and economy levels separates Oslo-verified fresh fillets from Scottish land-raised juvenile supply and bulk frozen blocks. Price differentiation hinges on harvest-to-shelf velocity and embedded origin verification. Margins are tightening due to Peruvian anchovy meal cost transmission into Norwegian feed formulations. Food manufacturers sourcing frozen blocks for ready-meal applications show highest price sensitivity; Berlin fine-dining groups purchasing provenance-tiered contracts show lowest.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket procurement through REWE and Edeka centralized buying desks. Supply concentrates in Norwegian fjord clusters and Scottish Highland farming corridors with secondary processing at Shetland and Bergen sites. Raw material dependencies draw from Peruvian fishmeal fisheries, Scottish hatchery smolt production, and Baltic transport logistics. Single-source vulnerability runs through Norwegian Directorate of Fisheries coastal permit allocations constraining conventional net-pen expansion. Distribution runs through Bremerhaven cold-chain hubs for continental re-export and Gdańsk terminals for Baltic redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European salmon rests on accelerating land-based RAS adoption slashing veterinary intervention costs while premium-tier traceability subscriptions capture provenance premiums from German food service buyers.
For Market Incumbents: Extend offshore farming technology licensing to capture Oslo-Petroleum Fund capital flows before regulatory moratoriums harden in Troms and Finnmark. Deepen backward integration into captive smolt hatchery capacity to insulate grow-out cycles from Baltic juvenile supply volatility. Lock long-term offtake contracts with Metro AG and similar Hamburg distributors before subscription-based traceability models commoditize origin verification. For New Entrants and Emerging Players: Polish supermarket category managers represent the most penetrable buyer archetype given Warsaw salmon section underdevelopment relative to Western European assortment density. Target vacuum-sealed format penetration in Bucharest and Sofia through Gdańsk cold storage aggregation points. Lead with direct-to-consumer subscription models offering real-time blockchain-IoT harvest verification to bypass entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where land-based RAS facility staffing requirements outpace Norwegian university aquaculture program enrollment. Long-term viability favors operators with demonstrated closed-containment biosecurity protocols and secured EU Green Deal circular bioeconomy subsidy allocations. Acquisition target archetype: mid-scale Scottish processors with established Sainsbury's and Tesco supply relationships and convertible infrastructure for post-smolt nursery expansion. Signal to watch: DNV-GL and Bureau Veritas acceleration of Ocean Farm-class structural approval timelines indicating offshore platform deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Land-Based RAS Capacity Buildout | EU Green Deal subsidies redirect capital toward closed-containment systems bypassing coastal permit moratoriums. |
| Blockchain-IoT Traceability Integration | Real-time harvest-to-retail data streams enable subscription-based provenance verification for Scandinavian direct-to-consumer channels. |
| Offshore Farming Technology Licensing | Ocean Farm-class platform deployments concentrate sovereign wealth capital along Norway's central coast technology clusters. |
| Post-Smolt Nursery Contracting | Scottish processors shorten marine exposure windows through land-raised juvenile supply agreements with major retailers. |
| Mechanical Delousing Equipment Adoption | REACH chemical restrictions force substitution of formaldehyde bath treatments with warm-water flushing at harvesting facilities. |
Research Approach
Bottom-up household and food service demand modeling reconciled against top-down Norwegian and Scottish harvest volume tracking forms the analytical core. Primary interviews with salmon farming operations managers, supermarket category buyers at REWE and Edeka, restaurant procurement directors in Berlin and Lyon, and veterinary compliance officers at Marine Scotland were cross-validated against secondary sources including EFSA residue surveillance databases, Norwegian Directorate of Fisheries licensing records, EU customs trade statistics, and seafood industry association production reports.
Input-output matrices mapped product type, distribution channel, end user, and packaging format segments across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints. Forecast inputs incorporated fishmeal price volatility indices, coastal permit issuance rates, and smoked salmon portion-pack adoption velocity in British and German retail channels.
Inputs from EFSA surveillance databases and Norwegian licensing authorities were available through the study window; gaps in private RAS facility production data introduce uncertainty bands around land-based supply projections. Forecasts reflect documented assumptions regarding EU Green Deal implementation timelines and REACH chemical restriction enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Saudi Arabia Seafood Market
Seafood
Seafood Flavors Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Sea Biscuits Market
Seafood
Asia-Pacific Shrimp Market
Seafood
European Frozen Seafood Market
Seafood
Groundfish Market
Seafood
Canned Mackerel Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Fish Nutrition Market
Seafood
Halibut Market
Seafood
Trout Market
Seafood
Seafood Powders Market
Seafood
United States Lobster Market
Seafood
Tinned Fish Market
Seafood
Fish Protein Hydrolysate Market