
 Casual Marinated Products Market | 2026-2036
Casual Marinated Products Market Size, Share, and Industry Trends Forecast 2026-2036
Casual Marinated Products Market Insights
Specialty sauce producers in Southeast Asia is realigning capacity toward Western export markets as marinated meat demand rises. McCormick & Company leverages its spice sourcing networks to control raw material quality for retail marinade lines. Kikkoman Corporation anchors production in soy-based fermentation expertise that underpins umami-forward formulations. Unilever competes through multi-brand portfolio breadth spanning ethnic and mainstream flavor platforms.
Casual marinated products comprise proteins, vegetables, or plant-based substrates infused with seasoned liquid blends—typically containing acids, oils, aromatics, and salt—then packaged for direct cooking or further processing. The primary commercial purpose is to reduce home-kitchen preparation time while delivering consistent flavor intensity through controlled osmotic penetration and enzymatic tenderization. Meat marinades occupy the dominant revenue position given higher per-unit value and established retail placement, while vegetable and tofu segments are gaining velocity among flexitarian consumers. Bottled formats command shelf-space premiums in supermarkets, though sachet and single-serve configurations are expanding fastest through online retail and foodservice portion-control programs.
FDA labeling requirements and USDA process verification standards govern ingredient disclosure and pathogen control in the United States, while EFSA additive evaluations and EU Green Deal sustainability criteria shape formulation choices across European markets. These frameworks elevate compliance costs for smaller processors but also create barriers that favor scaled manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor evolving clean-label thresholds and carbon-footprint disclosure obligations as purchase criteria harden across retail and institutional procurement channels.
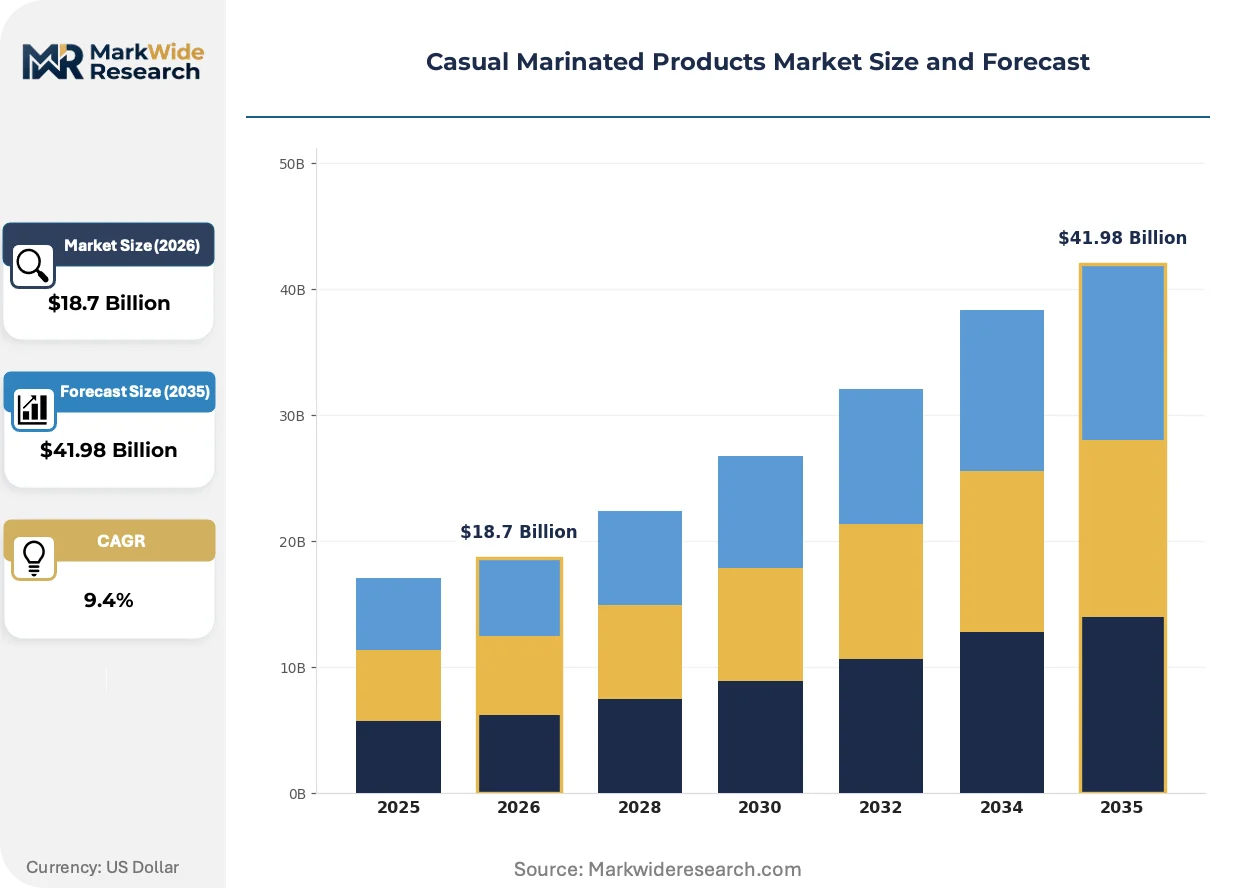
Market Dynamics
Clean-label formulation mandates under FDA and EFSA guidance are forcing ingredient system overhauls across marinated protein portfolios, compressing permissible preservative loadings while extending shelf-life targets. This regulatory compression is redrawing competitive advantage toward manufacturers with captive fermentation capabilities and natural acidification expertise.
Growth Catalysts
- USDA Process Verification Standards:Third-party validation protocols for pathogen control are accelerating adoption of high-pressure processing lines among mid-tier co-packers serving retail private label programs.
- Foodservice Labor Compression:Back-of-house staffing shortages across quick-service and fast-casual operators are pulling pre-marinated portion-cut proteins into central commissary and direct-store-delivery models.
- Soy Sauce Fermentation Expertise:Controlled umami development through traditional koji-based methods is displacing synthetic flavor enhancers in premium marinade formulations targeting clean-label retail shelves.
Market Restraints
- Input Cost Volatility in Edible Oils:Sunflower and canola oil price swings tied to Black Sea supply disruptions are compressing gross margins for oil-dominant marinade formulations.
- Technical Limitation in Enzymatic Tenderization:Protease-induced texture breakdown creates shelf-stability conflicts with extended distribution timelines, limiting application in ambient-stable retail formats.
- Regulatory Friction from EU Green Deal:Carbon-footprint disclosure obligations and packaging waste directives are elevating compliance overhead for exporters serving European retail banners.
Strategic Opportunities
- Underpenetrated Plant-Based Substrates:Mycoprotein and fermented legume bases in marinated formats remain nascent in US retail, offering first-mover positioning ahead of flexitarian saturation.
- Technology Convergence:Combination of modified-atmosphere packaging with active antimicrobial films is opening ambient-stable marinated vegetable segments previously confined to refrigerated distribution.
- Channel Innovation via Quick-Commerce:Dark-store fulfillment networks in urban China are creating same-day delivery slots for single-serve marinated protein SKUs previously excluded from e-grocery.
Industry Challenges
- Capex Intensity in Cold-Chain Expansion:Refrigerated last-mile infrastructure requirements for marinated protein direct-to-consumer models demand capital deployment that strains emerging brand balance sheets.
- Certification Timeline Compression:Dual organic and animal-welfare certification audits are extending new product introduction cycles by four to six months, delaying seasonal flavor launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casual Marinated Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Seafood, Vegetables, Tofu Flavor Profile: Spicy, Sweet, Savory, Tangy Packaging Type: Bottles, Sachets, Cans, Jars Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice |
| Companies Covered | McCormick & Company, Kraft Heinz Company, Unilever, Conagra Brands, Nestlé, General Mills, Kikkoman Corporation, Ken's Foods, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casual Marinated Products Market Trends and Innovations
Formulation science and packaging engineering are converging to extend shelf integrity without synthetic preservatives, while digital traceability systems reshape how marinated product provenance is communicated to buyers. These shifts are compressing traditional trade-offs between convenience, transparency, and sensory performance.
High-pressure processing technology is modularizing the pathogen intervention step in marinated meat production, enabling processors to locate pasteurization capacity at distributed co-manufacturing nodes rather than centralized thermal facilities. Mid-size regional meat processors are adopting HPP units at twice the rate of three years prior. This distributed intervention model is compressing the geographic radius between production and retail distribution, reducing refrigerated transport exposure.
EFSA additive re-evaluations under the EU Green Deal framework are systematically delisting traditional preservatives including certain benzoates and sulfites from approved marinade applications. Industrial consequence includes accelerated R&D spending on cultured celery powder and fermented rice vinegar as replacement acidification systems. Clean-label marinated poultry lines destined for German and French retail are reformulating fastest, with some banners already excluding synthetic preservative carriers from approved supplier lists.
Buyer concentration among consolidated foodservice procurement groups is compressing supplier negotiation cycles and unbundling technical service from base ingredient supply. Large multi-unit operators are centralizing marinade specification authority at headquarters level, displacing distributed chef-driven purchasing. This procurement consolidation is most visible in the United States, where three national broadline distributors now control specification access to over sixty percent of chain restaurant marinated protein volume.
Casual Marinated Products Market Segmentation
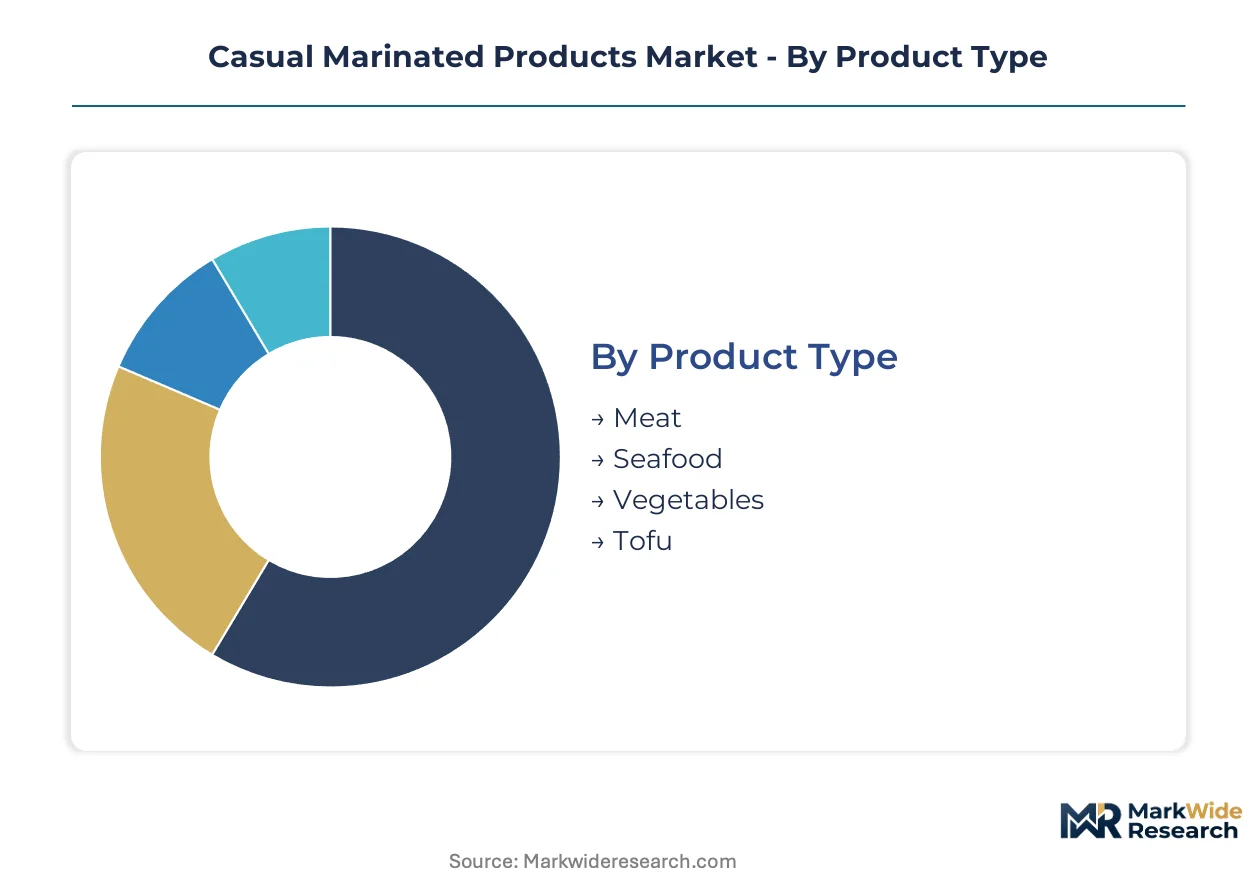
Segmentation in the casual marinated products market reveals distinct technical and commercial fault lines. Product formulation chemistry, packaging barrier properties, and channel cold-chain requirements create divergent margin profiles across each axis.
Product Type:
Protein substrate chemistry determines marinade penetration rates, enzymatic tenderization windows, and shelf-stability thresholds.
- Meat:Myofibrillar protein structures absorb acidic marinades through osmotic gradients, enabling controlled tenderization. Demand concentrates in United States retail and foodservice channels where USDA process verification standards govern pathogen control protocols.
- Seafood:Collagen-dense fish muscle requires shorter acid contact times to prevent textural breakdown. Japanese and South Korean retail banners drive premium positioning for soy-fermented seafood marinades.
- Vegetables:Cellular plant tissue permits rapid flavor saturation without enzymatic degradation. German and French clean-label retail programs are expanding ambient-stable vegetable marinade placements.
- Tofu:Soy protein curd matrices absorb marinades through capillary action, creating uniform flavor distribution. Urban China quick-commerce networks are scaling single-serve tofu marinade SKUs.
Meat leads on scale; tofu leads on momentum.
Flavor Profile:
Flavor chemistry alignment with substrate reactivity and regional palate preference shapes formulation R&D allocation.
- Spicy:Capsaicin-oil emulsions require stabilized suspension systems to prevent separation during shelf life. Southeast Asian export producers are realigning capacity toward Western markets as chili-forward marinades gain shelf space.
- Savory:Glutamate-rich fermentation bases deliver umami intensity without synthetic enhancers. EFSA additive re-evaluations are accelerating cultured celery powder adoption in European savory formulations.
- Sweet:Reducing sugar content in high-moisture marinades demands modified-atmosphere packaging to prevent Maillard browning. United States retail private label programs are expanding honey and maple-sweetened poultry lines.
- Tangy:Organic acid systems from fermented rice vinegar or citrus provide clean-label acidification. German retailers are excluding synthetic preservative carriers from approved tangy marinade supplier lists.
Savory commands the deepest technical moats; spicy is climbing the fastest.
Packaging Type:
Barrier performance and portion economics determine channel access and margin capture.
- Bottles:Multi-layer PET or glass formats with oxygen scavenging layers support extended refrigerated shelf life. United States supermarkets command shelf-space premiums for branded bottle formats.
- Sachets:Metallized film laminates provide moisture and light barrier at unit economics suitable for emerging markets. Online retail velocity in China and India is expanding fastest through sachet configurations.
- Cans:Metal packaging enables ambient stability through thermal processing compatibility. Foodservice portion-control programs in institutional catering favor can formats.
- Jars:Glass jar formats signal premium positioning and support reuse-oriented sustainability claims. Specialty stores in Germany and France are expanding artisan jarred marinade assortments.
Bottles dominate value capture; sachets dominate volume expansion.
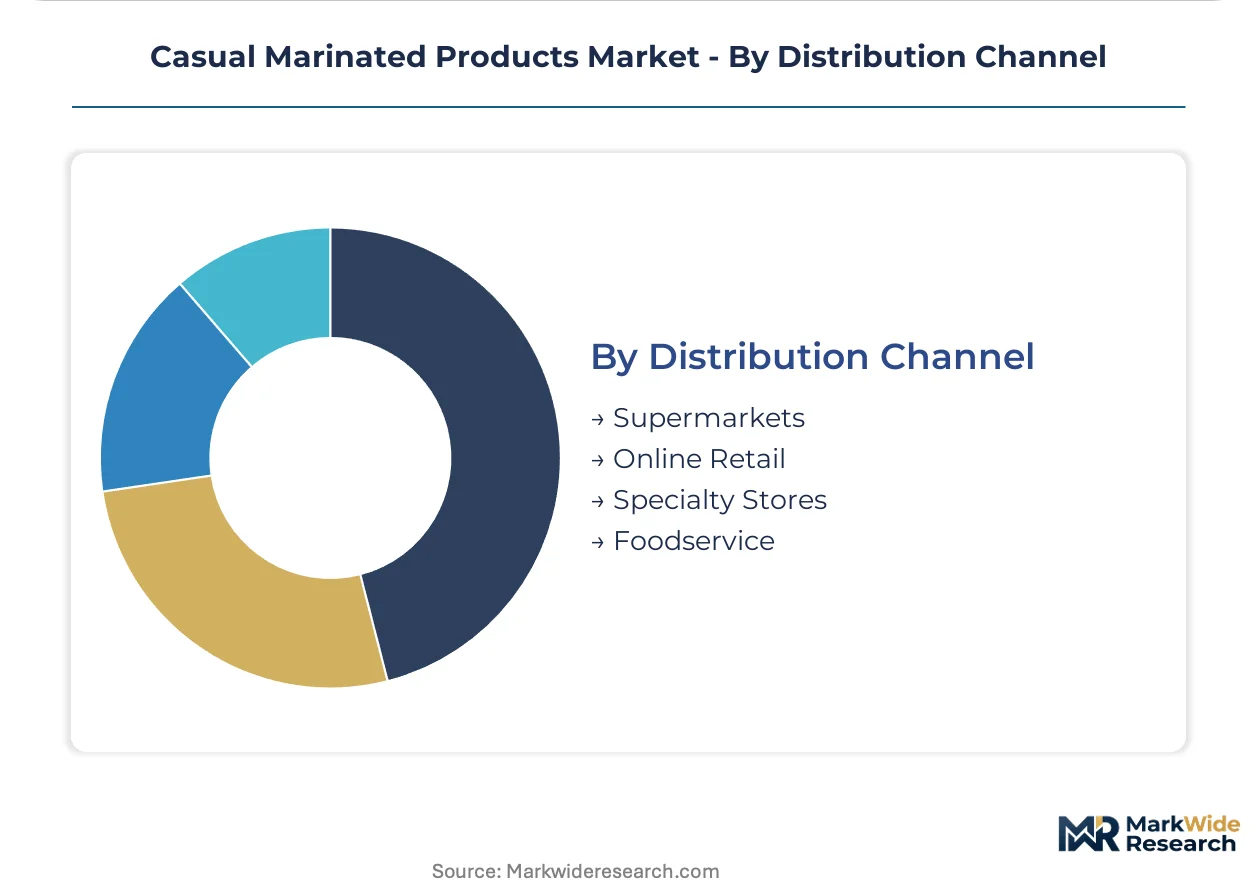
Distribution Channel:
Cold-chain infrastructure requirements and buyer concentration patterns segment channel economics.
- Supermarkets:Refrigerated case placement demands consistent supply reliability and promotional funding depth. United States and German retail banners are consolidating approved supplier lists for marinated protein lines.
- Online Retail:Direct-to-consumer models require insulated last-mile packaging that strains emerging brand balance sheets. Dark-store fulfillment networks in urban China are creating same-day delivery slots.
- Specialty Stores:Curated assortments favor small-batch and certified organic positioning with extended margin structures. French and Italian specialty food retailers are expanding regional marinade provenance stories.
- Foodservice:Centralized procurement at multi-unit operators displaces distributed chef-driven purchasing. Three United States broadline distributors now control specification access to over sixty percent of chain restaurant marinated protein volume.
Foodservice leads on contract value; online retail leads on growth steepness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate capacity toward jurisdictions with lower compliance-cost burdens for clean-label formulation. The United States, China, and Germany anchor demand concentration, yet formulation and packaging investments are dispersing across secondary production clusters seeking pathogen-control protocol equivalency at reduced certification overhead.
United States
Foodservice labor compression and quick-service chain expansion are pulling pre-marinated proteins into central commissary models. USDA process verification standards govern pathogen control protocols, accelerating high-pressure processing adoption among mid-tier co-packers. Greater Chicago and Atlanta metropolitan clusters concentrate private-label manufacturing capacity serving broadline distributor consolidation.
China
Urban quick-commerce networks and dark-store fulfillment are scaling same-day delivery for single-serve marinated SKUs. SAMR food safety supervision and GB standards for prepackaged foods shape additive disclosure requirements. Yangtze River Delta manufacturing zones around Shanghai anchor soy-fermentation expertise for umami-forward export formulations.
Germany
Retail banner consolidation and clean-label procurement criteria are excluding synthetic preservative carriers from approved supplier lists. EFSA additive re-evaluations and EU Green Deal carbon-footprint disclosure obligations elevate compliance overhead for marinated protein exporters. Bavaria and North Rhine-Westphalia host reformulation R&D facilities targeting fermented acidification systems.
Japan
Premium positioning for soy-fermented seafood marinades drives demand in domestic retail and South Korean export channels. METI food industry policy and JIS packaging standards influence barrier-film specifications for extended shelf-life formats. Kansai region fermentation clusters around Osaka maintain koji-based traditional production methods for umami intensity.
United Kingdom
Specialty food retail expansion and flexitarian protein diversification are creating placement opportunities for marinated vegetable and tofu segments. FSA allergen labeling and post-EU import regime adjustments complicate continental supply relationships. London-Southeast distribution hubs coordinate refrigerated last-mile infrastructure for direct-to-consumer marinated protein models.
Casual Marinated Products Market Competitive Landscape
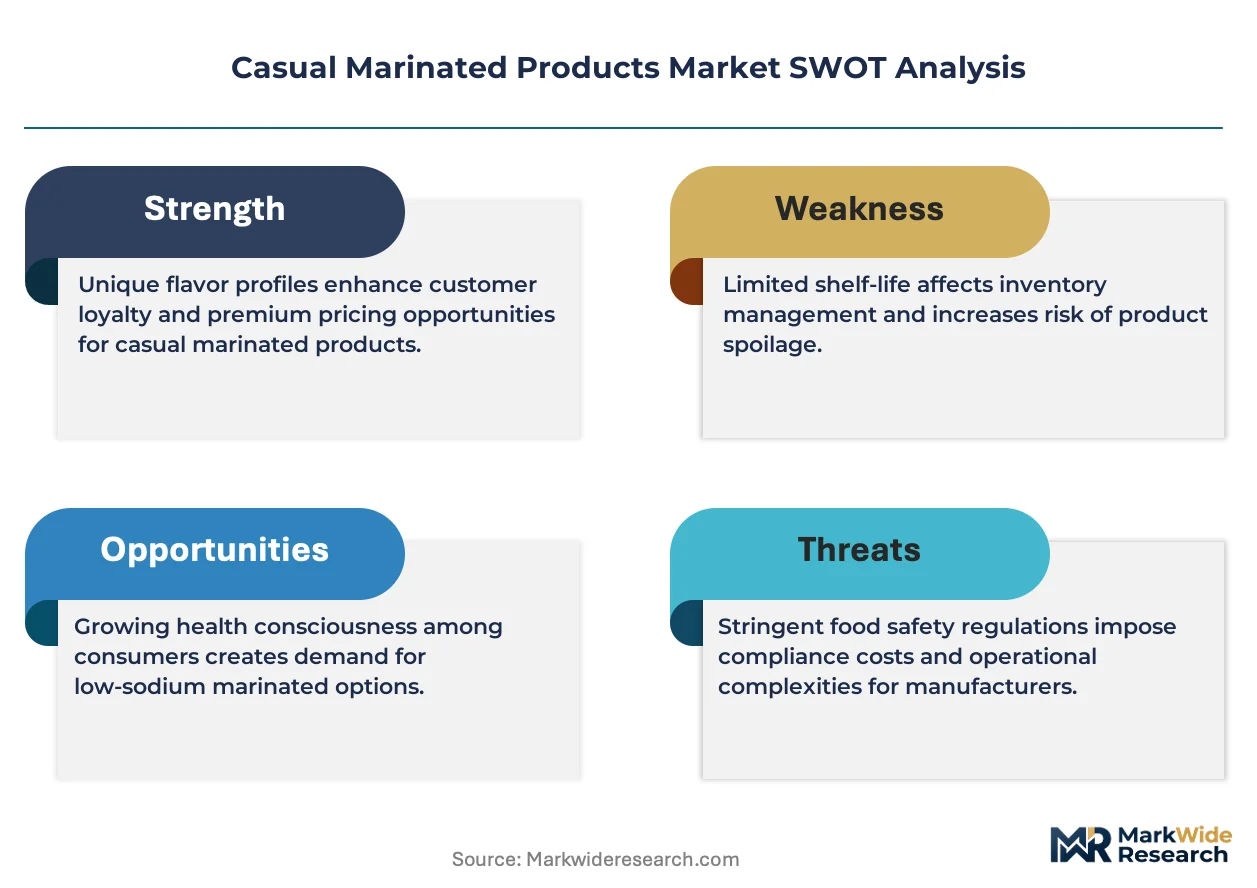
Established producers occupy the standard tier; emerging entrants pursue plant-based substrate specialization and quick-commerce channel integration. The vendor base stratifies across three maturity tiers: multinational seasoning conglomerates with captive spice sourcing, mid-cap regional processors with co-manufacturing flexibility, and venture-backed alternative protein formulators. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with dark-store fulfillment networks.
Within the multinational seasoning tier, McCormick & Company and Kikkoman Corporation exemplify divergent raw-material control strategies. McCormick leverages its spice sourcing networks to anchor quality consistency for retail marinade lines. Kikkoman occupies a position defined by soy-based fermentation expertise underpinning umami-forward formulations. Unilever sits within the multi-brand portfolio archetype, competing through breadth spanning ethnic and mainstream flavor platforms.
| Leading Market Players |
|---|
| McCormick & Company |
| Kraft Heinz Company |
| Unilever |
| Conagra Brands |
| Nestlé |
| General Mills |
| Kikkoman Corporation |
| Ken's Foods |
| Campbell Soup Company |
| Others |
Pricing and Supply Chain Analysis
Consolidated foodservice procurement groups in the United States now control specification access to over sixty percent of chain restaurant marinated protein volume, forcing suppliers toward contract-based long-term offtake pricing with volume-scaled discounts rather than spot-market transactions. This buyer concentration compresses margin capture for mid-tier processors while rewarding scaled manufacturers with dedicated regulatory affairs functions and captive fermentation capacity.
Pricing Analysis
Distributor margin layers in the United States broadline channel absorb twelve to eighteen points before retail markup, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on clean-label certification grade and USDA process verification status, with organic and animal-welfare certified lines commanding shelf-space premiums. Cost compression in oil-dominant formulations is intensifying because Black Sea supply disruptions in sunflower and canola inputs compress gross margins. Quick-service operators exhibit highest price sensitivity due to centralized procurement authority, while specialty stores in Germany and France tolerate extended margin structures for provenance-positioned SKUs.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Greater Chicago metropolitan clusters, and Bavaria anchor hub-and-spoke patterns for marinated protein fulfillment. Manufacturing concentrates in China for soy-fermentation expertise, the United States for USDA-verified private-label capacity, and Germany for EFSA-compliant reformulation R&D. Raw material dependencies draw from Southeast Asian spice sourcing networks, Black Sea edible oil corridors, and domestic fermentation substrate supplies. Single-source vulnerability in high-pressure processing equipment creates chokepoint exposure for mid-tier co-packers seeking pathogen intervention capacity. Distribution runs through refrigerated last-mile infrastructure for direct-to-consumer models, dark-store fulfillment networks in urban China, and broadline distributor consolidation in North American foodservice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The casual marinated products market functions as a stable compounder anchored by irreversible foodservice labor compression that pulls pre-marinated proteins into central commissary models across quick-service and fast-casual channels.
For Market Incumbents: Deepen backward integration into koji-based fermentation capacity and captive spice sourcing networks to defend against emerging plant-based substrate specialists. Invest in high-pressure processing lines at distributed co-manufacturing nodes to compress geographic radius between production and retail distribution. Prioritize dual organic and animal-welfare certification investment to maintain shelf-space access as German and French retail banners exclude synthetic preservative carriers from approved supplier lists. For New Entrants and Emerging Players: Quick-commerce channel integration through dark-store fulfillment partnerships in urban China offers the most penetrable route for single-serve marinated tofu and vegetable SKUs previously excluded from e-grocery. Target underpenetrated mycoprotein and fermented legume bases in United States retail ahead of flexitarian saturation. Pursue go-to-market positioning through certified clean-label formulations that bypass four-to-six-month certification timeline compression faced by conventional processors. For Investors and Strategic Acquirers: Seasoning conglomerates with captive fermentation capabilities and established retail marinade lines are the most active acquirer in this space, seeking regional processors with co-manufacturing flexibility and USDA process verification credentials. Five-to-ten year viability hinges on clean-label formulation moats and quick-commerce channel integration rather than commodity scale. Watch for inflection signals in EFSA additive re-evaluation timelines that would accelerate R&D spending requirements and consolidate advantage toward scaled manufacturers with dedicated regulatory affairs functions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Kikkoman Corporation's koji-based expertise anchors umami-forward clean-label formulations displacing synthetic enhancers. |
| High-Pressure Processing Line Deployment | Mid-tier United States co-packers adopt HPP units at twice prior rates to meet USDA pathogen verification standards. |
| Quick-Commerce Channel Partnership | Dark-store fulfillment networks in urban China create same-day delivery slots for single-serve marinated protein SKUs. |
| Clean-Label Certification Investment | German retail banners already exclude synthetic preservative carriers from approved marinated poultry supplier lists. |
| Plant-Based Substrate R&D Expansion | Mycoprotein and fermented legume bases remain nascent in United States retail, offering first-mover positioning ahead of saturation. |
Research Methodology
Bottom-up foodservice and retail channel modeling reconciled against top-down fermentation capacity and spice sourcing tracking forms the analytical core of this study. Primary interviews with brand managers at seasoning conglomerates, category buyers at United States and German retail banners, supply planners at broadline distributors, technical R&D directors at regional processors, and regulatory affairs leads at export-oriented manufacturers were combined with secondary validation. Secondary sources include FDA and USDA process verification filings, EFSA additive re-evaluation documentation, SAMR GB standards disclosures, Nielsen retail audit data for marinated protein shelf placement, and customs records for Southeast Asian spice and edible oil trade flows.
Historical trendline analysis of marinated protein volume by channel and substrate type informed the projection framework across the analysis window. Segmentation dimensions modeled include protein substrate chemistry, flavor profile reactivity, packaging barrier properties, and distribution channel cold-chain requirements. CAGRs were derived from regression analysis of channel penetration rates and formulation adoption curves. Industry-specific forecast inputs incorporate high-pressure processing capacity expansion timelines and EFSA clean-label threshold evolution.
The model assumes a particular technology adoption path for high-pressure processing and modified-atmosphere packaging; alternative pathways for enzymatic tenderization or active antimicrobial films would alter the outlook for ambient-stable format penetration. Forecasts reflect documented assumptions regarding regulatory timeline compression and foodservice procurement consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Imitation Whipped Cream Market
Processed Foods
United States Ice Cream Market
Processed Foods
Processed Vegetable Market
Processed Foods
Low Moisture Food Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Processed Peanut Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Fat Free Soup Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Africa Soup Market
Processed Foods
Fat Free Food Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Tomato Puree Market
Processed Foods
Apple Butter Market
Processed Foods
Processed Eucheuma Seaweed Market