
 Fish Oil Market | 2026-2036
Fish Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Oil Market Intelligence
REACH compliance is repositioning the cost-of-entry calculus for European fish oil suppliers, forcing capital allocation toward contaminant testing and supply chain documentation. Omega Protein Corporation leverages vertical integration across Gulf menhaden fisheries to sustain cost advantages in crude oil supply. DSM Nutritional Products anchors its position through pharmaceutical-grade concentration technology, competing on purity specifications that exceed monograph thresholds.
Fish oil comprises omega-3 fatty acids—primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—extracted from pelagic species such as anchovy, sardine, and menhaden through rendering or wet pressing, then refined for use in human nutrition, animal feed, and pharmaceutical formulations. The application dimension shows dietary supplements commanding the largest value pool while functional foods represent the fastest-expanding frontier as brands fortify beverages and dairy with microencapsulated omega-3 powders. Product type segmentation reveals concentrated oil capturing disproportionate margin as pharmaceutical manufacturers specify ethyl ester and re-esterified triglyceride forms above standard refined grades.
EMA pharmacovigilance requirements and USP monograph standards shape quality benchmarks for pharmaceutical-grade fish oil, while FDA New Dietary Ingredient notifications create compliance friction for novel delivery formats. EPA and DHA content claims face tightening substantiation pressure from the FTC and EFSA, directing formulation investments toward clinically validated ratios. Stakeholders must monitor the divergence between pharmaceutical and nutraceutical regulatory pathways as this split determines which product specifications and documentation investments will yield market access.
Market Dynamics
REACH compliance is forcing European fish oil suppliers to redirect capital toward contaminant testing infrastructure and chain-of-custody documentation systems, fundamentally altering the cost-of-entry calculus for pharmaceutical-grade production.
Growth Catalysts
- EMA Pharmacovigilance Standards:Pharmaceutical manufacturers are specifying ethyl ester and re-esterified triglyceride forms above standard refined grades, pulling demand toward concentrated oil with purity thresholds exceeding monograph baselines.
- Microencapsulation Technology:Functional food brands are fortifying beverages and dairy with omega-3 powders, expanding the addressable market beyond traditional softgel delivery formats into shelf-stable applications.
- Norwegian Processing Infrastructure:Pelagic rendering capacity and MSC certification density in Norway create supply advantages for pharmaceutical-grade output, concentrating procurement decisions around traceable North Atlantic sourcing.
Market Restraints
- Wild-Catch Input Volatility:Anchovy and sardine biomass fluctuations off Peru and Chile generate raw material cost instability that compresses margin predictability for crude oil refiners.
- Plant-Based Substitution:Algal DHA and EPA from fermentation processes are capturing vegan-formulation demand in dietary supplements, eroding addressable volume for marine-derived alternatives.
- EU Fisheries Control Regulation:Revised traceability mandates are extending documentation burdens to smaller fleet operators, reducing eligible supplier pools and tightening upstream concentration.
Strategic Opportunities
- Clinical Validation Expansion:Cumulative cardiovascular and cognitive trial data is repositioning omega-3 from commodity supplement toward prescriptive therapeutic, opening pharmacy channel access.
- Pet Nutrition Fortification:Premium companion animal food manufacturers are specifying omega-3 inclusion for coat and joint claims, creating a parallel demand vertical with lower regulatory friction.
- Direct-to-Consumer Subscription:Fresh-delivery models for liquid fish oil are bypassing retail markup structures, capturing lifetime value through auto-replenishment relationships.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Contaminant testing for dioxins, PCBs, and heavy metals requires specialized chromatography expertise that outpaces current vocational pipeline output.
- Dual Certification Timelines:Simultaneous pursuit of USP monograph compliance and Friend of the Sea sustainability marks extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Oil Market |
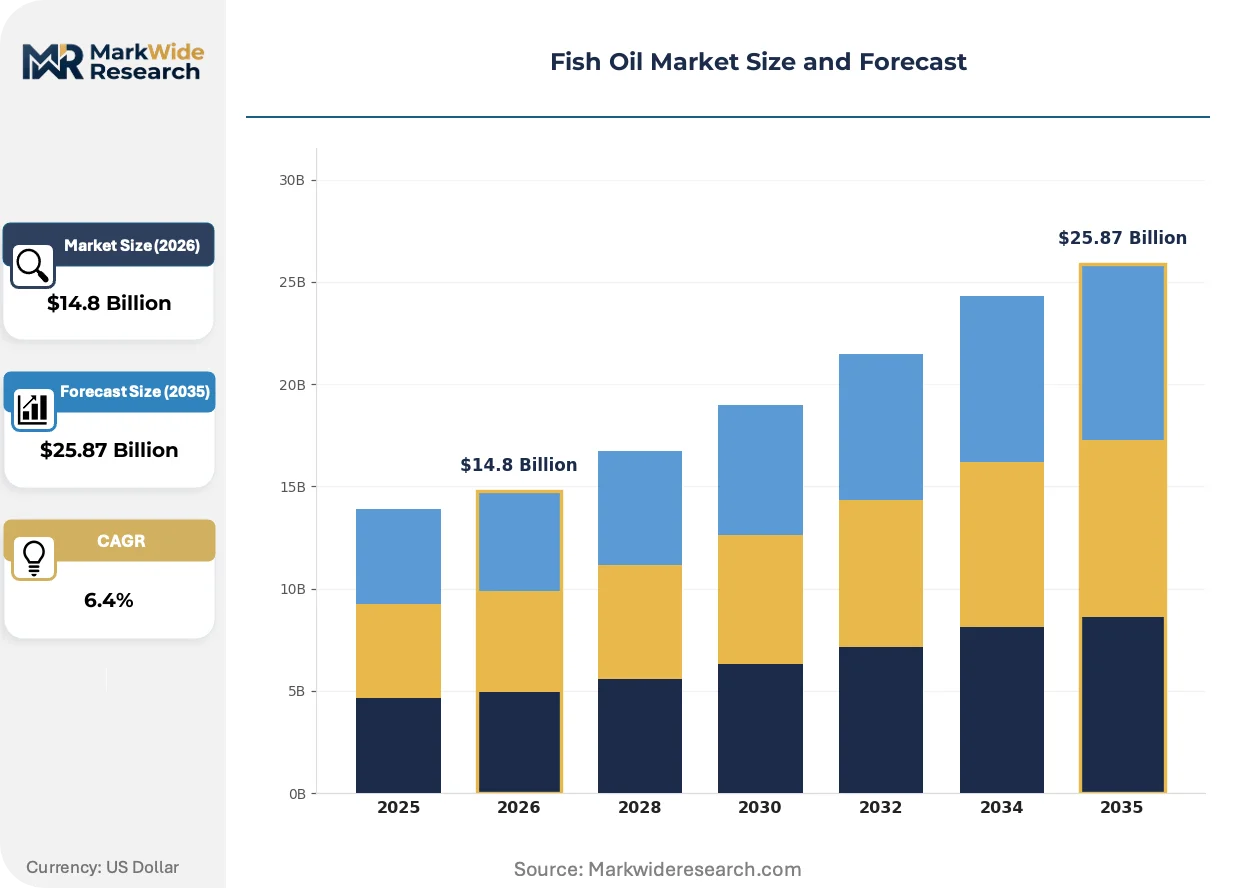
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Concentrated Oil, Pharmaceutical Grade, Food Grade Application: Dietary Supplements, Animal Nutrition, Pharmaceuticals, Cosmetics, Functional Foods Form: Liquid, Capsule, Softgel, Tablet, Emulsion End User: Sports Nutrition Brands, Pharmaceutical Manufacturers, Personal Care Companies, Animal Feed Producers |
| Companies Covered | Omega Protein Corporation, BASF SE, DSM Nutritional Products, Cargill, Croda International plc, GC Rieber Oils, Pelagia AS, TripleNine Group, OLVEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Oil Market Strategic Shifts & Innovations
Concentration technology and delivery format innovation are compressing the traditional value chain, enabling ingredient suppliers to capture margin historically retained by finished goods manufacturers.
Re-esterified triglyceride concentration is overtaking ethyl ester forms in pharmaceutical procurement specifications. Drug manufacturers in Germany and Switzerland are requiring 85% EPA+DHA purity thresholds for new cardiovascular formulations. This technology shift is enabling API suppliers to command ingredient premiums that exceed standard refined oil multiples by factor ranges previously reserved for synthetic alternatives.
REACH authorization requirements for processing solvents are compelling Nordic refiners to retrofit molecular distillation units with supercritical CO2 extraction capability. ECHA substance evaluation timelines are extending capital deployment cycles by 18-24 months. Pharmaceutical-grade producers in Denmark and Iceland are responding by consolidating testing capabilities into centralized analytical hubs shared across cooperative supply networks.
Certification-driven procurement is fragmenting buyer decision criteria beyond price and purity. Dietary supplement brands in the United States are specifying dual MSC and IFFO RS certification as table stakes for supplier qualification. This behavioral shift is most visible in contract manufacturing agreements, where sustainability documentation is displacing traditional quality agreements as the primary negotiation leverage point.
Fish Oil Market Segmentation
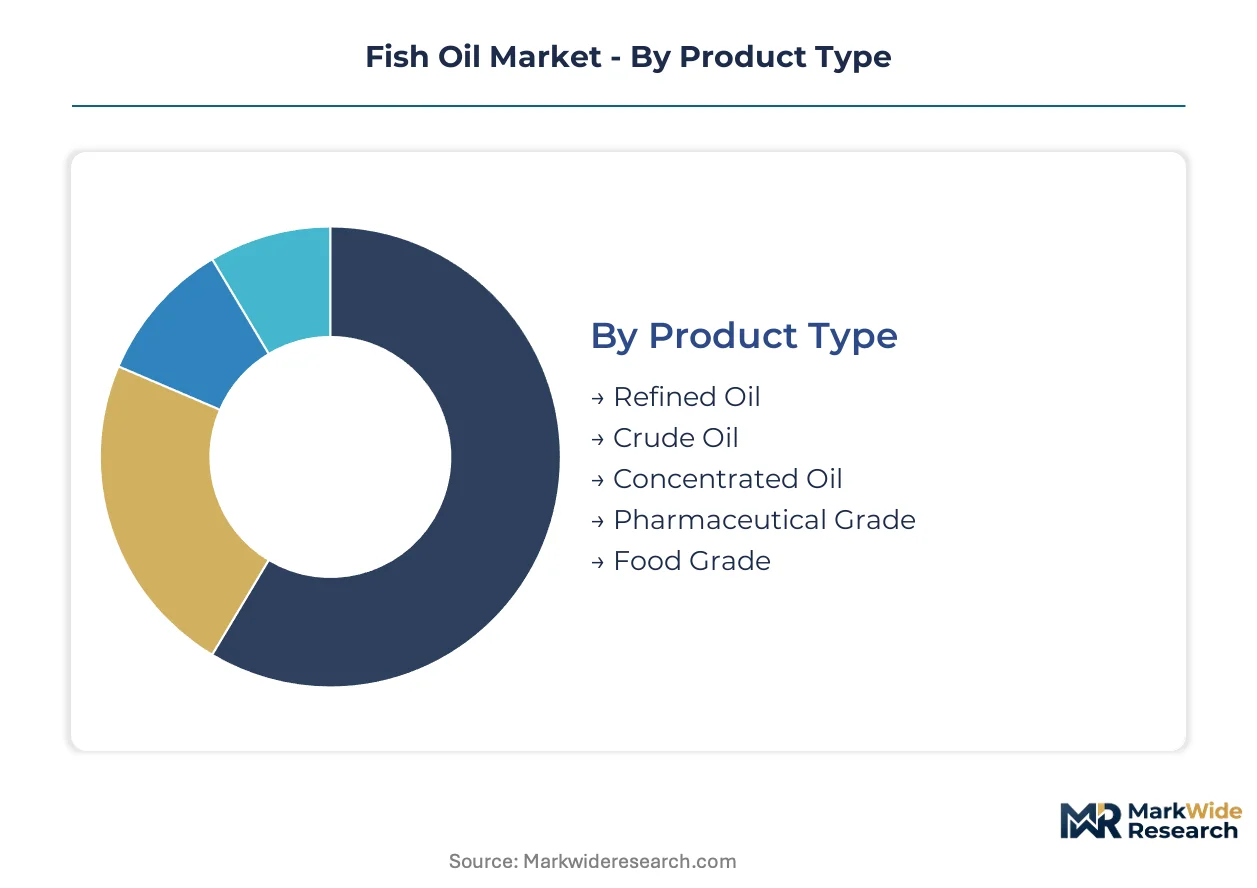
Segmentation in fish oil reveals how supply chain configuration and regulatory thresholds fragment value capture across the value chain. Product grade distinctions determine which suppliers can access pharmaceutical procurement channels versus commodity feed applications.
Product Type:
Supply concentration around Norwegian and Peruvian processing infrastructure creates divergent cost positions across grade tiers.
- Refined Oil:Standardized through degumming, bleaching, and deodorization to achieve free fatty acid levels below 0.1% and peroxide values under 5 meq O2/kg. Demand concentrates in North American dietary supplement contract manufacturers seeking USP monograph compliance without concentration premiums.
- Concentrated Oil:Ethyl ester and re-esterified triglyceride forms achieve EPA+DHA purity above 60%, with German and Swiss pharmaceutical manufacturers now specifying 85% thresholds for cardiovascular drug formulations. Molecular distillation and supercritical CO2 extraction infrastructure in Denmark and Iceland supply this tier.
- Crude Oil:Unrefined output from wet pressing or rendering of anchovy, sardine, and menhaden; traded in bulk for further processing.
- Pharmaceutical Grade:Exceeds monograph baselines for dioxins, PCBs, and heavy metals; EMA pharmacovigilance documentation required.
- Food Grade:Meets CODEX Alimentarius and national food safety standards for direct human consumption applications.
Concentrated oil absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
End-use diversification is compressing traditional channel boundaries as ingredient suppliers build finished formulation capabilities.
- Dietary Supplements:Softgel and liquid formats dominate, with FTC and EFSA tightening substantiation requirements for EPA and DHA content claims. Direct-to-consumer subscription models for fresh liquid delivery are bypassing retail markup structures.
- Functional Foods:Microencapsulated omega-3 powders enable beverage and dairy fortification with shelf-stable oxidation resistance. Brands in the United States and Germany are expanding addressable market beyond traditional delivery formats.
- Animal Nutrition:Premium companion animal food manufacturers specify omega-3 inclusion for coat and joint claims.
- Pharmaceuticals:Prescription omega-3 formulations require API-grade documentation and batch release testing.
- Cosmetics:Topical applications leverage anti-inflammatory positioning in dermocosmetic formulations.
Dietary supplements command the largest value pool; functional foods are climbing the fastest.
Form:
Delivery technology investments determine which suppliers can access functional food and beverage channels versus traditional supplement formats.
- Softgel:Gelatin and plant-based shell encapsulation of oil-based actives; dominates adult supplement positioning.
- Liquid:Fresh-delivery models capture lifetime value through auto-replenishment relationships in North American and Nordic markets.
- Capsule:Hard-shell formats for powder or granule delivery; common in combination products.
- Tablet:Compressed powder applications with limited omega-3 loading due to oxidation sensitivity.
- Emulsion:Water-dispersible formats for infant nutrition and clinical enteral feeding applications.
Softgel retains the dominant share; emulsion formats are gaining share fastest in medical nutrition.
End User:
Procurement criteria diverge sharply between regulated pharmaceutical channels and performance-positioned consumer brands.
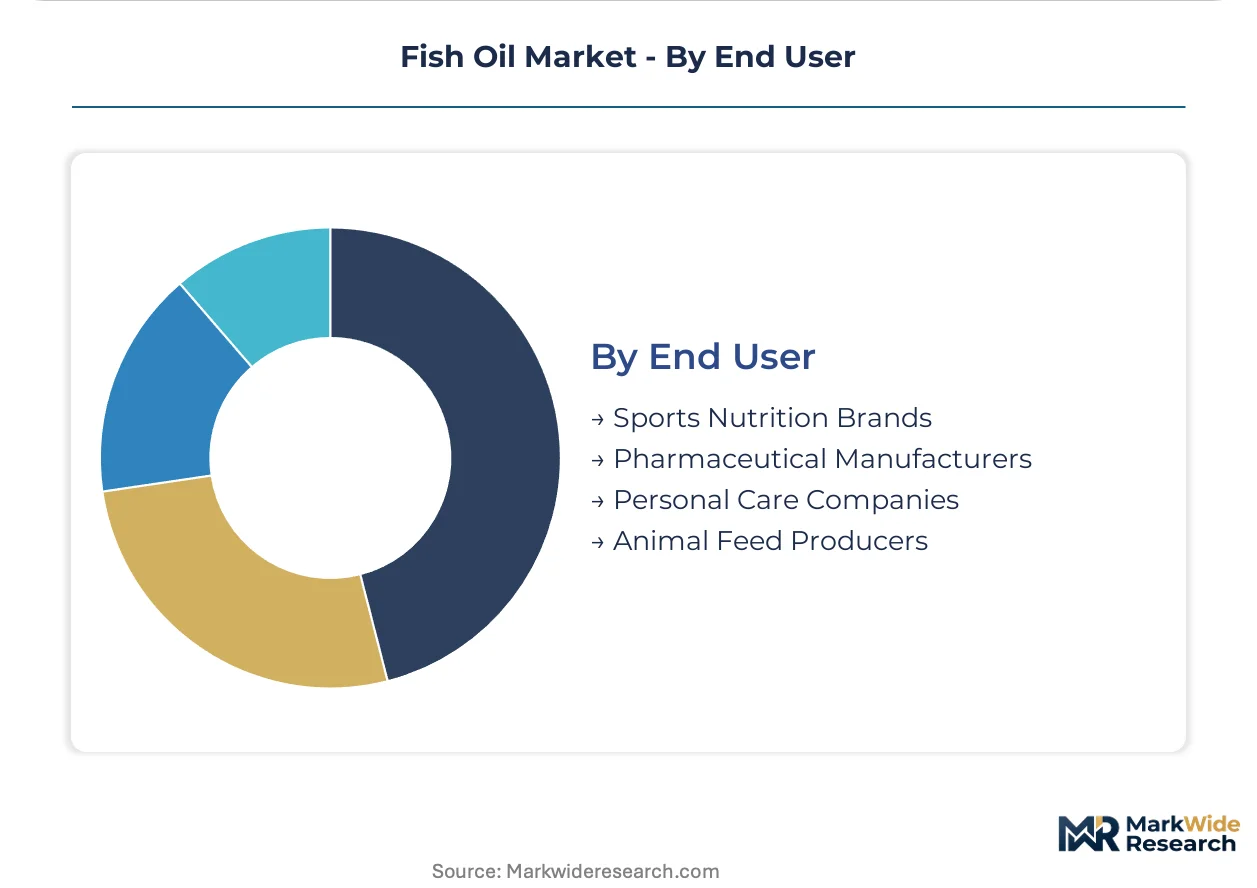
- Pharmaceutical Manufacturers:German, Swiss, and Danish drug companies specify ethyl ester and re-esterified triglyceride forms with purity thresholds exceeding monograph baselines. Dual USP monograph and Friend of the Sea certification extends supplier qualification timelines by 8-14 months.
- Animal Feed Producers:Aquaculture and premium pet food manufacturers drive volume demand for standard refined grades with lower documentation burdens.
- Sports Nutrition Brands:Position omega-3 within recovery and inflammation management portfolios.
- Personal Care Companies:Source cosmetic-grade oils for topical anti-aging and barrier repair formulations.
Pharmaceutical manufacturers absorb the bulk of high-grade supply; animal feed producers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's pelagic processing zones attract pharmaceutical-grade investment through MSC certification density and EEA regulatory alignment. Special economic treatment of North Atlantic fisheries infrastructure concentrates ethyl ester concentration capacity around Bergen and Ålesund.
Norway
Pelagic rendering infrastructure in Bergen and Ålesund supplies pharmaceutical manufacturers specifying 85% EPA+DHA purity thresholds. EEA alignment with EMA pharmacovigilance standards streamlines batch release documentation for German and Swiss drug companies. The Sunnmøre region anchors supercritical CO2 extraction retrofit activity responding to REACH solvent authorization timelines.
United States
Dietary supplement contract manufacturers in New Jersey and California drive demand for USP monograph-compliant refined grades. FDA New Dietary Ingredient notifications create compliance friction for novel delivery formats entering interstate commerce. The Gulf Coast menhaden fishery cluster sustains crude oil supply through vertically integrated rendering operations.
Germany
Pharmaceutical manufacturers in Frankfurt and Basel-adjacent Baden-Württemberg specify re-esterified triglyceride forms exceeding monograph baselines. BfArM enforcement of EMA quality benchmarks tightens supplier qualification timelines. The Hamburg port complex concentrates import logistics for Norwegian and Peruvian refined oil streams.
Peru
Anchovy biomass fluctuations off the Humboldt Current generate raw material cost instability for crude oil exporters. PRODUCE fisheries management frameworks attempt to stabilize catch quotas amid El Niño variability. The Chimbote processing corridor retains volume leadership despite sustainability certification gaps constraining pharmaceutical-grade access.
Denmark
Cooperative supply networks in Esbjerg and Kalundborg centralize analytical testing capabilities shared across Nordic refiners. ECHA substance evaluation timelines extend capital deployment cycles for molecular distillation retrofits. The Danish Straits logistics hub enables just-in-time delivery to German pharmaceutical manufacturing sites.
Fish Oil Market Key Industry Players
Nordic producers anchor the pharmaceutical-grade tier; Gulf Coast and Peruvian specialists hold volume positions in crude and refined supply. The vendor base splits between concentrated purity leaders and commodity-scale renderers. Three archetypes dominate: vertically integrated fishery operators, API-grade concentration technology licensors, and sustainability-certification aggregators. Competitive moves concentrate on supercritical CO2 extraction licensing and cooperative analytical hub formation.
Within the vertically integrated tier, Omega Protein Corporation exemplifies Gulf Coast fishery control sustaining crude cost advantages. DSM Nutritional Products occupies the concentration technology position through pharmaceutical-grade ethyl ester and re-esterified triglyceride supply. GC Rieber Oils represents the Nordic certification-density model leveraging MSC documentation for European pharmaceutical procurement channels.
| Leading Market Players |
|---|
| Omega Protein Corporation |
| BASF SE |
| DSM Nutritional Products |
| Cargill |
| Croda International plc |
| GC Rieber Oils |
| Pelagia AS |
| TripleNine Group |
| OLVEA Group |
| Others |
Cost & Logistics Intelligence
REACH authorization timelines for processing solvents gate both qualified supply and premium-tier pricing access, concentrating pharmaceutical-grade procurement around Nordic refiners with supercritical CO2 extraction capability. ECHA substance evaluation cycles extend capital deployment horizons, compressing margin predictability for suppliers lacking cooperative testing infrastructure.
Pricing Analysis
Lead-time-driven pricing stratification rewards short-cycle delivery with premium capture while spot inventory trades at structural discounts. Three-tier pricing structure across pharmaceutical, nutraceutical, and feed-grade levels anchors on certification density and purity thresholds. Cost compression in standard refined grades intensifies as Peruvian anchovy biomass volatility feeds raw material instability. Animal feed producers exhibit highest price sensitivity; German pharmaceutical manufacturers absorb premium multiples for API-grade documentation.
Supply Chain Analysis
MSC and IFFO RS qualification gates upstream access, fragmenting eligible supplier pools around traceable North Atlantic sourcing. Supply concentrates in Norway, Peru, and Denmark, with crude rendering anchored in Gulf Coast menhaden fisheries. Raw material flows draw from anchovy, sardine, and menhaden biomass, with omega-3 concentration resting on molecular distillation and supercritical CO2 inputs. Single-source vulnerability runs through Humboldt Current catch variability. Distribution runs through Hamburg and Danish Straits logistics hubs serving German pharmaceutical manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fish oil market reads as a cost-of-compliance story where EMA pharmacovigilance standards erect barrier-to-entry moats favoring incumbent analytical infrastructure holders.
For Market Incumbents: To counter algal DHA substitution in vegan-formulation segments, deepen backward integration into pelagic rendering capacity and consolidate testing capabilities into shared cooperative hubs. Anchor defensive positioning through dual USP monograph and Friend of the Sea certification density that extends rival qualification timelines.
For New Entrants and Emerging Players: Supercritical CO2 extraction licensing offers technology-first entry into pharmaceutical-grade concentration tiers with reduced REACH solvent authorization exposure. White-space targets center on pet nutrition fortification and direct-to-consumer fresh-delivery subscription models. Pursue Nordic cooperative network participation to bypass standalone analytical chemistry talent scarcity.
For Investors and Strategic Acquirers: Re-esterified triglyceride procurement specification shifts at German and Swiss drug manufacturers is the leading indicator that pharmaceutical-grade API supply will consolidate around concentration technology licensors. Long-term viability favors acquisition targets with installed supercritical CO2 capacity and existing EMA batch release documentation systems. Monitor ECHA substance evaluation timeline extensions as margin compression signal for solvent-dependent molecular distillation operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Retrofit | REACH solvent authorization compliance enables pharmaceutical-grade market access for Nordic refiners. |
| Cooperative Analytical Hub Formation | Shared dioxin and PCB testing infrastructure defrays capital burdens across Danish supply networks. |
| Dual Certification Pursuit | Simultaneous USP monograph and Friend of the Sea marks extend product launch cycles but lock pharmacy channel eligibility. |
| Direct-to-Consumer Subscription Launch | Fresh-delivery liquid models bypass retail markup structures and capture lifetime value in North American markets. |
| Pet Nutrition Vertical Entry | Premium companion animal food specifications create parallel demand with lower regulatory friction than human pharmaceutical pathways. |
Research Approach
Independent corroboration across primary interviews with refining operations directors, pharmaceutical procurement managers, sustainability certification auditors, and dietary supplement contract manufacturers underwrites the qualitative findings. Secondary validation draws from ECHA substance evaluation databases, EMA pharmacovigilance records, IFFO RS certification registries, and customs trade flows for omega-3 fatty acid derivatives. Bottom-up volume triangulation against top-down value estimation anchors segmentation outputs.
Rate-of-change decomposition across product grade tiers, application end-uses, and regional regulatory clusters structures the analytical framework throughout the forecast period. CAGRs derive from segment-level volume build-ups and value-per-unit assumptions calibrated to pharmaceutical versus nutraceutical pricing stratification. Forecast inputs incorporate REACH compliance cost trajectories and El Niño-driven anchovy biomass volatility indices.
Several conditions sit outside the modeled scope, including speculative algal fermentation scale-up economics and unannounced EU Fisheries Control Regulation enforcement intensity shifts. Forecasts reflect documented assumptions regarding certification adoption curves and solvent authorization timeline stability. A model refresh is warranted upon material change in EMA pharmacovigilance documentation requirements or Peruvian PRODUCE quota allocation frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
United States Plant-Based Seafood Market
Seafood
Sea Bream Market
Seafood
Salmon Fish Market
Seafood
Fish Maw Market
Seafood
Tinned Fish Market
Seafood
Europe Seafood Market
Seafood
European Frozen Seafood Market
Seafood
Fin Fish Market
Seafood
Shellfish Market
Seafood
Herring Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
North America Salmon Market
Seafood
Fish Nutrition Market
Seafood
Mussel Extract Market
Seafood
Global Shrimp Market