
 Australia Coffee Market | 2026-2036
Australia Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Coffee Market Analysis
Brazilian arabica harvest volatility is realigning Australian roaster sourcing calendars toward diversified origin contracts. Nestle Australia leverages its soluble coffee infrastructure to secure shelf space in national supermarket chains. JDE Peets Australia sustains office coffee service accounts through automated equipment leasing programs. Vittoria Coffee anchors its position in foodservice channels with Italian-style espresso blends tailored to Australian palate preferences.
Coffee comprises roasted seeds of Coffea arabica and Coffea canephora (robusta), processed through washing or natural drying to achieve moisture content below 12% before grinding or extraction into beverage form. The product serves as a functional stimulant and social ritual anchor across commercial and domestic settings. Pods command disproportionate margin pools in households despite slower volume growth, while whole bean sales accelerate through specialty retail and subscription service channels. Café end users dominate wholesale value flows, though office recovery post-pandemic is redistributing demand across service type segments.
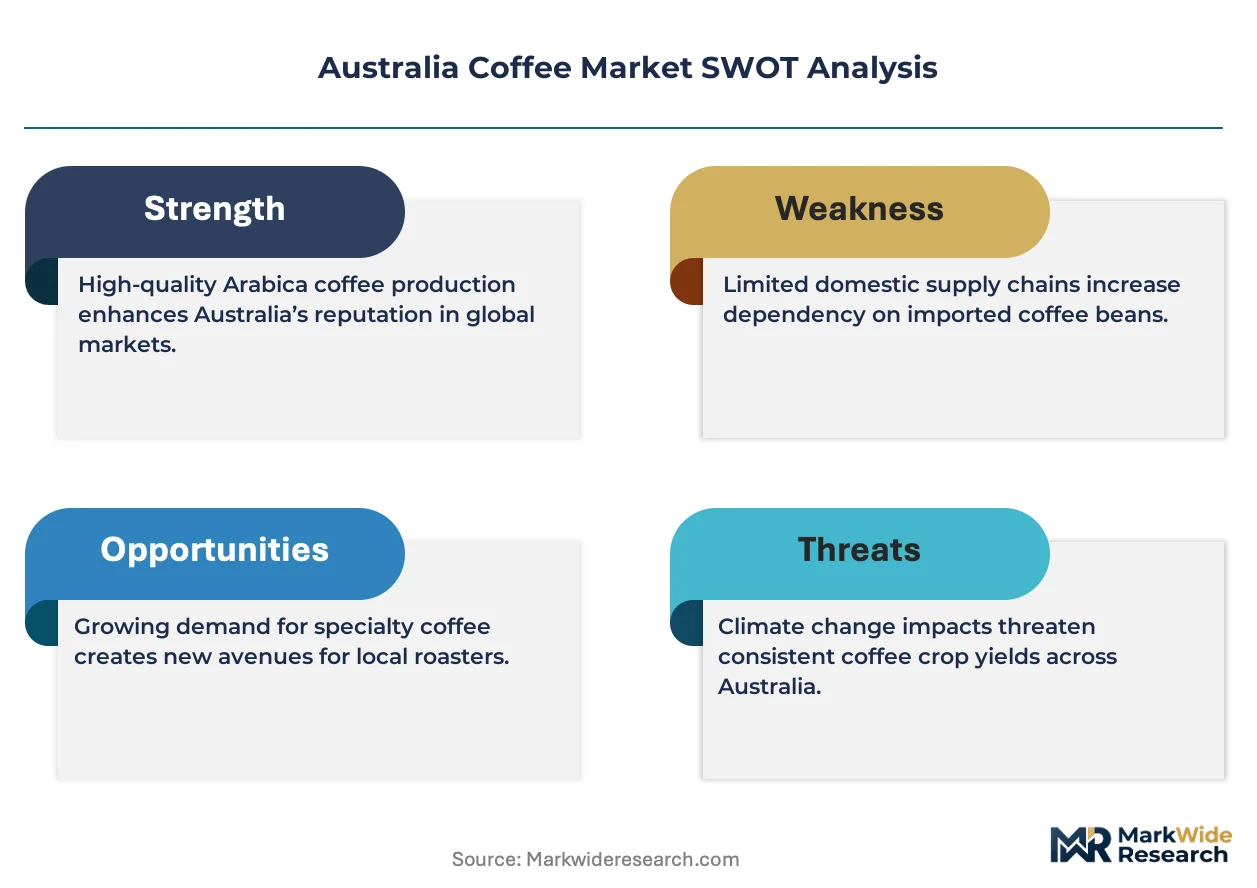
Food Standards Australia New Zealand governs labeling integrity and caffeine disclosure, while the Australian Competition and Consumer Commission enforces greenwashing penalties that constrain marketing claims around sustainability. Biosecurity import permits from the Department of Agriculture, Fisheries and Forestry regulate green bean entry and shape roaster inventory planning. Stakeholders must monitor origin climate stress and regulatory tightening on packaging waste as dual determinants of supply security and compliance cost trajectories.
Market Dynamics
Brazilian arabica harvest volatility is compressing Australian roaster planning horizons and forcing accelerated diversification into Colombian, Ethiopian, and Vietnamese origin contracts. Food Standards Australia New Zealand labeling mandates for sustainable sourcing claims are simultaneously raising compliance thresholds and reshaping procurement documentation requirements across the value chain.
Growth Catalysts
- Specialty café expansion:Melbourne and Sydney operators are scaling single-origin bean procurement, creating premium tier demand that pulls upstream investment into traceability infrastructure and direct trade relationships.
- FSANZ sustainable sourcing framework:Updated labeling requirements for environmental claims are legitimizing certified products and enabling price premiums for verified provenance in retail channels.
- Office coffee service recovery:Post-pandemic workplace attendance normalization is redistributing wholesale demand toward automated equipment leasing and managed service contracts across New South Wales and Victoria.
Market Restraints
- Brazilian supply concentration:Climate-induced harvest volatility at origin creates inventory planning friction and forces Australian roasters to absorb basis risk or pay premiums for forward coverage.
- Biosecurity permit delays:Department of Agriculture, Fisheries and Forestry import processing timelines constrain green bean availability and extend working capital cycles for smaller roasting operations.
- Instant coffee substitution:Nestle Australia's soluble coffee infrastructure maintains price-competitive shelf positioning that caps whole bean penetration in price-sensitive household segments.
Strategic Opportunities
- Subscription channel development:Direct-to-consumer whole bean services are capturing recurring revenue pools with higher lifetime value than supermarket retail, particularly in metropolitan Melbourne.
- Victoria-NSW roasting cluster expansion:Geographic concentration of specialty demand enables shared logistics infrastructure and co-roasting arrangements that reduce per-unit fixed costs.
- Packaging waste regulation preparation:Anticipated tightening of Australian environmental standards creates first-mover advantage for compostable pod and recyclable flexible film investments.
Industry Challenges
- Green coffee grading expertise scarcity:Specialized cupping and origin assessment capabilities are concentrated among senior buyers, constraining roaster capacity to evaluate diversified supplier portfolios.
- Legacy equipment integration:Automated brewing systems in office channels require retrofitting with telemetry and remote diagnostics, complicating service model transitions for established distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Coffee Market |
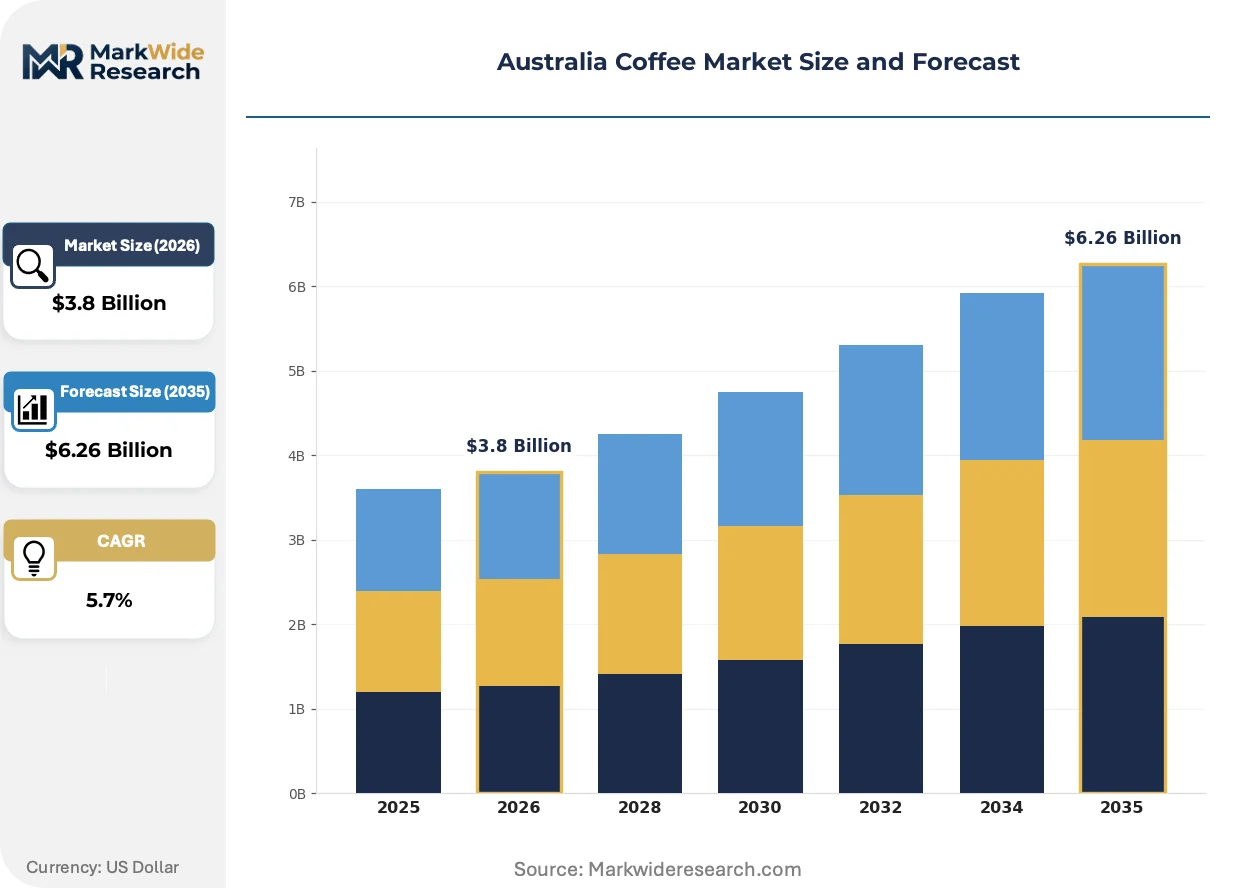
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
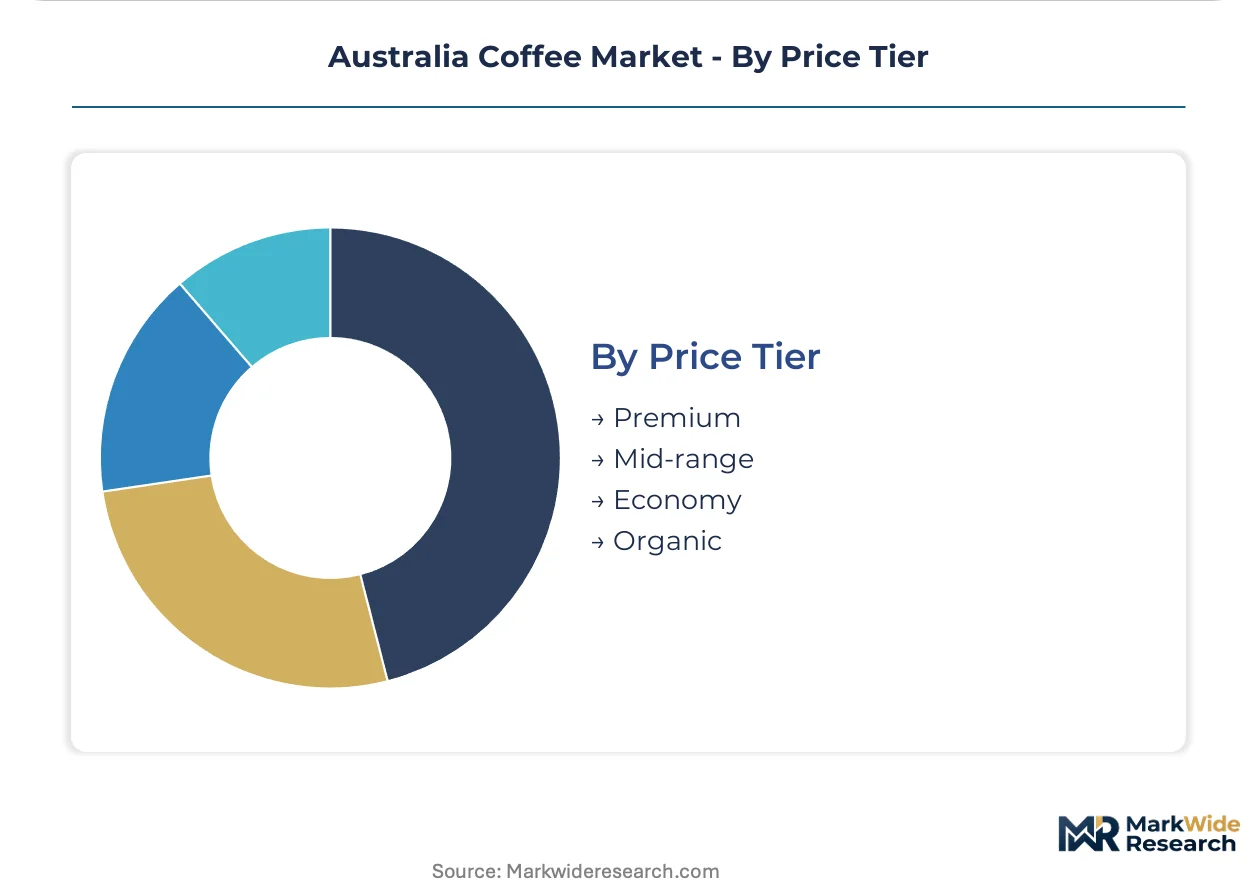
| Segmentation | Product Type: Whole Bean, Ground, Instant, Pods End User: Households, Cafés, Restaurants, Offices Service Type: Retail, Online, Wholesale, Subscription Price Tier: Premium, Mid-range, Economy, Organic |
| Companies Covered | Nestle Australia, JDE Peets Australia, Vittoria Coffee, Grinders Coffee, Campos Coffee, Toby’s Estate Coffee Roasters, Five Senses Coffee, Merlo Coffee, Di Bella Coffee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Coffee Market Emerging Trajectories
Technology-enabled traceability and regulatory pressure on sustainability claims are converging to reshape competitive positioning across Australian coffee value chains. Procurement documentation, roasting automation, and consumer-facing provenance verification are becoming interdependent capabilities.
Blockchain-enabled origin tracking is overtaking paper-based certification as the standard for specialty segment credibility. Melbourne and Sydney café operators are demanding lot-level traceability within eighteen-month procurement cycles. This technology is compressing information asymmetry between origin farmers and Australian end buyers, enabling direct trade relationships that bypass traditional importer intermediaries.
Food Standards Australia New Zealand updated its labeling requirements for sustainable sourcing claims in 2024, mandating substantiation documentation for environmental marketing. Roasters must now maintain chain-of-custody records that withstand ACCC greenwashing enforcement actions. Premium retail segments are responding by investing in third-party audit infrastructure, while economy-tier brands face compliance cost pressure that favors larger operational scale.
Subscription-based replenishment models are displacing supermarket bulk purchasing among metropolitan Australian households. Specialty roasters in Victoria and New South Wales are capturing recurring revenue through personalized curation algorithms and flexible delivery scheduling. This behavioral shift is most visible in inner-Sydney and inner-Melbourne postcodes where café culture density correlates with home brewing equipment ownership and willingness to pay for freshness-guaranteed supply.
Australia Coffee Market Segmentation
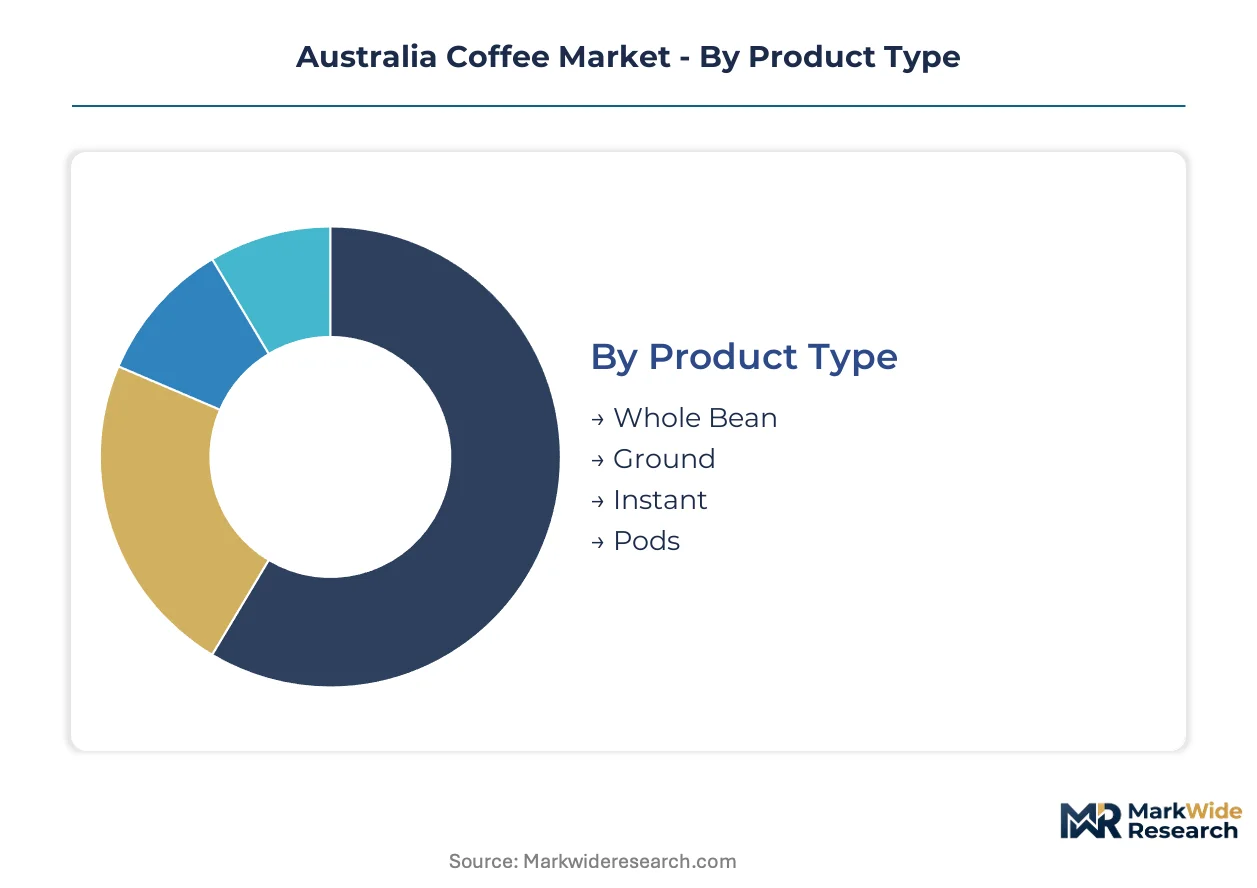
Segmentation reveals how capital deployment and margin capture diverge across Australian coffee channels. Roasting infrastructure, cold-chain logistics, and certification compliance create distinct investment profiles that shape competitive entry barriers.
Product Type:
Capital intensity peaks with in-house roasting and packaging automation, while trading operations require minimal fixed asset commitment.
- Whole Bean:Requires precision roasting equipment with batch control systems and nitrogen-flushing packaging lines to preserve volatile aromatics. Specialty cafés in Melbourne's inner-north drive procurement of traceable single-origin lots with direct trade documentation.
- Pods:Demands proprietary brewing system compatibility and multi-layer barrier film technology to achieve shelf stability. Nespresso-compatible formats dominate household penetration in Sydney's eastern suburbs despite higher per-cup cost structures.
- Ground:Sits between whole bean freshness and pod convenience with shorter distribution windows. Major supermarket chains control shelf placement through slotting fee arrangements.
- Instant:Relies on spray-drying or freeze-drying infrastructure with significant energy inputs. Nestle Australia's soluble production facility in Gymea supplies private-label programs for discount retailers.
Most installed capacity flows through Ground. Expansion is steepest in Pods.
End User:
Customer concentration determines contract structure, with volume commitments and equipment leasing terms varying sharply by account type.
- Cafés:Melbourne's laneway specialty operators and Sydney's beachside espresso bars anchor wholesale value flows. These accounts demand consistent supply, barista training support, and equipment maintenance programs that lock in multi-year relationships.
- Offices:Post-pandemic attendance normalization in New South Wales and Victoria is redistributing demand toward automated brewing systems with telemetry monitoring. JDE Peets sustains market presence through machine leasing bundled with consumable supply contracts.
- Households:Purchase frequency correlates with café culture density in metropolitan postcodes. Subscription services are displacing supermarket bulk buying in inner-Melbourne and inner-Sydney.
- Restaurants:Require consistent Italian-style blends that pair with dessert menus and tolerate variable extraction quality across staff turnover. Foodservice distributors consolidate procurement across multi-site operators.
Revenue concentration sits with Cafés. Account growth is climbing the fastest in Offices.
Service Type:
Channel economics separate inventory risk bearers from pure intermediaries, with working capital cycles stretching longest in wholesale operations.
- Wholesale:Roasters carry green bean inventory exposure and extend trade credit to café accounts. Biosecurity permit delays from the Department of Agriculture, Fisheries and Forestry constrain just-in-time replenishment.
- Subscription:Direct-to-consumer models capture recurring revenue with personalized curation algorithms. Victorian and New South Wales roasters lead freshness-guaranteed delivery scheduling.
- Retail:Supermarket chains extract promotional allowances and category management fees that compress net margins for packaged coffee suppliers.
- Online:Marketplace platforms aggregate discovery but commoditize pricing through comparison tools. Specialty roasters bypass aggregators through owned-channel investment.
Transaction volume concentrates in Retail. Margin expansion is gaining share fastest in Subscription.
Price Tier:
Certification and provenance documentation create cost structures that separate defendable premium positioning from commodity competition.
- Premium:Single-origin and micro-lot offerings command traceability premiums through direct trade relationships. Melbourne's specialty café density validates consumer willingness to pay for cupping-score transparency.
- Organic:Requires certification compliance with Food Standards Australia New Zealand substantiation requirements and third-party audit maintenance. Supply scarcity relative to conventional green beans creates input cost premiums.
- Mid-range:Blends balance consistency requirements with cost discipline for mainstream foodservice accounts. Vittoria Coffee anchors this tier through Italian-style espresso formulations.
- Economy:Private-label and instant products compete on shelf price with minimal marketing investment. Nestle Australia's soluble infrastructure maintains cost leadership through scale economies.
Volume flows through Mid-range. Price realization is expanding most quickly in Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and Colombia diverge sharply in how Australian roasters calibrate their origin exposure, with harvest timing and freight economics pulling procurement calendars in opposite directions across the Pacific.
Victoria
Melbourne's laneway café density sustains the nation's highest per-capita specialty coffee consumption. Food Standards Australia New Zealand labeling mandates for sustainable sourcing claims operate with full enforcement weight here. The inner-north roasting cluster in Brunswick and Collingwood anchors direct trade relationships with Ethiopian and Colombian suppliers.
New South Wales
Sydney's eastern suburbs and beachside espresso bars drive premium pod and whole bean demand through subscription channels. The Australian Competition and Consumer Commission monitors greenwashing enforcement with particular attention to environmental marketing in this high-visibility market. Parramatta and North Shore office corridors are normalizing post-pandemic automated equipment leasing.
Queensland
Brisbane's subtropical climate shapes cold brew and iced coffee preference distinct from southern states. Biosecurity import permits from the Department of Agriculture, Fisheries and Forestry face processing delays at the Port of Brisbane that extend working capital cycles. Gold Coast tourism corridors concentrate foodservice demand in seasonal patterns.
Western Australia
Perth's geographic isolation from eastern roasting hubs elevates freight costs and supports local micro-roaster development. The state's consumer protection regulator applies ACCC-aligned standards to sustainability claims with independent enforcement capacity. Fremantle's port precinct hosts emerging direct trade cupping facilities serving Indian Ocean origin contracts.
Australia Coffee Market Vendor Landscape
Italian-style heritage roasters anchor one tier; Australian-founded specialty operators hold differentiated positions in traceability-driven segments. The market exhibits tiered concentration with multinational soluble manufacturers, mid-scale regional blenders, and micro-roasting artisans occupying distinct competitive spaces. Three archetypes dominate: scale-driven instant producers, Italian-heritage foodservice suppliers, and direct-trade specialty originators. Capacity expansion and certification compliance represent the primary competitive vectors reshaping positioning.
Within the multinational tier, Nestle Australia exemplifies scale-driven soluble infrastructure. JDE Peets Australia occupies a position bridging automated office service and retail packaged goods. Vittoria Coffee anchors Italian-style espresso blending for foodservice channels. These three represent divergent responses to the same regulatory and sourcing pressures reshaping Australian coffee value chains.
| Leading Market Players |
|---|
| Nestle Australia |
| JDE Peets Australia |
| Vittoria Coffee |
| Grinders Coffee |
| Campos Coffee |
| Toby's Estate Coffee Roasters |
| Five Senses Coffee |
| Merlo Coffee |
| Di Bella Coffee |
| Others |
Supply Flow & Price Mechanics
Arabica futures traded on the Intercontinental Exchange cascade through Australian roaster procurement calendars into three-tier pricing structures across premium, standard, and economy levels. Brazilian harvest volatility transmits basis risk premiums into forward contracts, while specialty café demand in Melbourne and Sydney validates traceability premiums that separate direct-trade single-origins from commodity blends.
Pricing Analysis
Distributor margin compression runs through supermarket channel negotiations where slotting fees and promotional allowances constrain net realization for packaged coffee suppliers. Subscription-based direct-to-consumer models capture recurring revenue with higher lifetime value than retail, while café wholesale accounts trade volume commitments against equipment leasing subsidies. Price differentiation hinges on certification documentation and provenance transparency, with Food Standards Australia New Zealand compliance costs favoring scaled operators over micro-roasters. Office coffee service segments show lowest price sensitivity due to bundled equipment contracts, whereas economy-tier household segments face intense substitution pressure from Nestle Australia's soluble infrastructure.
Supply Chain Analysis
Chain-of-custody certification gating through Rainforest Alliance and Fairtrade documentation shapes green bean eligibility for premium tier placement. Supply concentrates in Brazil, Colombia, and Vietnam for volume contracts, with Ethiopian and Kenyan origins serving specialty micro-lot demand. Raw material dependencies rest on arabica and robusta price differentials, ocean freight rates from Santos and Cartagena, and biosecurity processing timelines at Australian ports. Single-origin concentration risk intensifies with climate-induced harvest volatility, while distribution runs through Melbourne and Sydney roasting clusters serving Victoria and New South Wales café density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Coffee Market functions as a stable compounder anchored by ritual consumption patterns and café culture institutionalization that sustains premium tier expansion through economic cycles.
For Market Incumbents: Cement defensible positions by deepening backward integration into Ethiopian and Colombian direct-trade relationships that bypass importer intermediaries and secure lot-level traceability. Expand nitrogen-flushing packaging capacity in Brunswick and Collingwood to serve freshness-guaranteed subscription growth. FSANZ substantiation requirements for sustainable sourcing claims favor scaled audit infrastructure investment over competitor compliance cost absorption.
For New Entrants and Emerging Players: Blockchain-enabled origin verification offers technology-first entry into specialty café procurement where Melbourne operators demand eighteen-month lot tracking within direct trade frameworks. Target Queensland cold brew and iced coffee white space where subtropical climate preferences diverge from southern state espresso dominance. Pursue co-roasting arrangements in Victoria-NSW clusters to minimize fixed asset commitment.
For Investors and Strategic Acquirers: Asymmetric upside sits with subscription-channel specialists possessing proprietary curation algorithms and recurring revenue visibility. Five-to-ten year viability frames roasting automation and certification compliance as durable competitive moats. Monitor Brazilian arabica basis risk transmission as inflection indicator for margin compression across commodity-exposed portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Trade Origin Partnerships | Bypasses importer markups and secures cupping-score transparency for Melbourne specialty cafés. |
| Compostable Pod Development | Anticipates Australian packaging waste regulation tightening with first-mover environmental compliance. |
| Subscription Platform Investment | Captures recurring revenue pools with higher lifetime value than supermarket retail channels. |
| Automated Equipment Leasing | Locks multi-year consumable supply contracts through JDE Peets-style office service bundling. |
| Blockchain Traceability Deployment | Meets FSANZ substantiation requirements for sustainable sourcing claims with audit-resistant documentation. |
Methodological Framework
Direct dialogue with green coffee buyers, roasting operations managers, café proprietors, and Food Standards Australia New Zealand compliance officers grounded qualitative findings in procurement decision-making realities. Secondary validation drew from Australian Bureau of Agricultural and Resource Economics trade data, Department of Agriculture biosecurity permit records, ACCC greenwashing enforcement actions, and customs import declarations. Bottom-up volume estimates triangulated against top-down consumption surveys across metropolitan postcodes.
Segmented outputs across product type, end user, service type, and price tier dimensions informed value allocation modeling throughout the projection horizon. CAGRs derived from historical consumption trajectories, origin supply elasticity, and regulatory cost pass-through assumptions. Brazilian harvest volatility indices and freight rate fluctuations from Santos served as external shock inputs.
The model holds under stable Brazilian supply conditions and consistent FSANZ enforcement intensity; deviation in biosecurity processing timelines or origin climate stress would shift inventory planning assumptions and working capital requirements. A model refresh is warranted upon material change in Food Standards Australia New Zealand labeling mandates or Australian Competition and Consumer Commission greenwashing penalty structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Roaster Market
Coffee
Reusable Coffee Cup Market
Coffee
Chewable Coffee Market
Coffee
Middle East Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Cafix Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Decaffeinated Coffee Market
Coffee
Robusta Coffee Beans Market
Coffee
Drip Coffee Machine Market
Coffee
Coffee Grinder Market
Coffee
US Coffee Roaster Market
Coffee
Global Coffee Market
Coffee
Encapsulated Caffeine Market
Coffee
UK Coffee Roaster Market
Coffee
Raw Coffee Beans Market