
 North America Frozen Seafood Market | 2026-2036
North America Frozen Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen Seafood Market Intelligence
FSMA's traceability rule is decoupling small importers from mainstream retail supply chains. Mowi ASA leverages its integrated aquaculture platform to control Atlantic salmon quality from hatchery to frozen fillet. Clearwater Seafoods anchors its position through Arctic surf clam and coldwater shrimp specialization in Canadian Atlantic waters. Thai Union Group PCL extends its reach via branded and private-label tuna portfolios across North American mass retail.
North America frozen seafood encompasses finfish, shellfish, and value-added products preserved at temperatures below minus eighteen degrees Celsius to halt enzymatic degradation and microbial proliferation, with individual quick freezing representing the dominant industrial technique for preserving cellular integrity and texture upon thawing. The IQF processing method leads volume throughput due to its suitability for portion-controlled foodservice applications, while breaded and marinated value-added segments capture disproportionate margin pools through retail premiumization. Fish products dominate absolute tonnage, though shrimp commands higher per-unit value and faster velocity in both supermarket and online retail channels.
FDA's Seafood HACCP framework, the USDA's Country of Origin Labeling provisions, and Canada's CFIA Safe Food for Canadians Regulations collectively govern import clearance, species verification, and cold-chain documentation across the trade corridor. These standards elevate compliance costs for non-integrated distributors while creating structural advantages for vertically coordinated harvesters and processors. Stakeholders must monitor evolving traceability mandates and carbon disclosure requirements that will reshape supplier qualification criteria and procurement priorities.
Market Dynamics
Foodservice labor inflation and FDA's Seafood HACCP traceability mandates are forcing procurement consolidation toward vertically integrated processors capable of documenting vessel-to-retail chain of custody without margin-destroying compliance overhead.
Growth Catalysts
- IQF Processing Scale-Up:Individual quick freezing infrastructure expansion along the U.S. Gulf Coast corridor is enabling portion-controlled supply to institutional buyers with minimal thaw-loss.
- Canada's CFIA Alignment:Harmonized Safe Food for Canadians Regulations with U.S. import documentation standards is accelerating cross-border processor qualification and reducing customs clearance friction.
- Cloud Kitchen Demand:Delivery-native restaurant concepts require frozen seafood with extended holding tolerance and consistent cook-yield, favoring blast-frozen over fresh supply.
Market Restraints
- Wild-Catch Input Volatility:Bering Sea pollock and Gulf menhaden quotas fluctuate seasonally, compressing margin predictability for non-integrated distributors lacking aquaculture hedges.
- Cold-Chain Energy Density:Diesel-powered reefer transport and -18°C warehouse holding impose fuel-cost exposure that electric alternatives have not yet scaled to displace at intermodal distance.
- Substitute Protein Competition:Plant-based seafood analogs and cultivated fish prototypes are capturing trial among coastal urban consumers with sustainability-weighted purchasing criteria.
Strategic Opportunities
- Direct-to-Institutional Channels:Hospital and university foodservice systems are bypassing broadline distributors to contract directly with frozen seafood processors for spec-controlled volume.
- Carbon Disclosure Tailwinds:Proposed SEC climate disclosure rules and Canada's evolving emissions reporting framework will advantage processors with verified low-carbon catch methods and electrified cold chains.
- Value-Added Margin Capture:Marinated, breaded, and sauced frozen seafood products command shelf-space premiums in club retail and e-grocery fulfillment centers.
Industry Challenges
- HACCP Compliance Talent Scarcity:Qualified seafood safety plan developers and third-party audit coordinators command wage premiums that strain mid-size processor staffing.
- Legacy ERP Integration:Lot-level traceability systems required for FDA compliance often conflict with decades-old inventory management infrastructure, forcing expensive middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen Seafood Market |
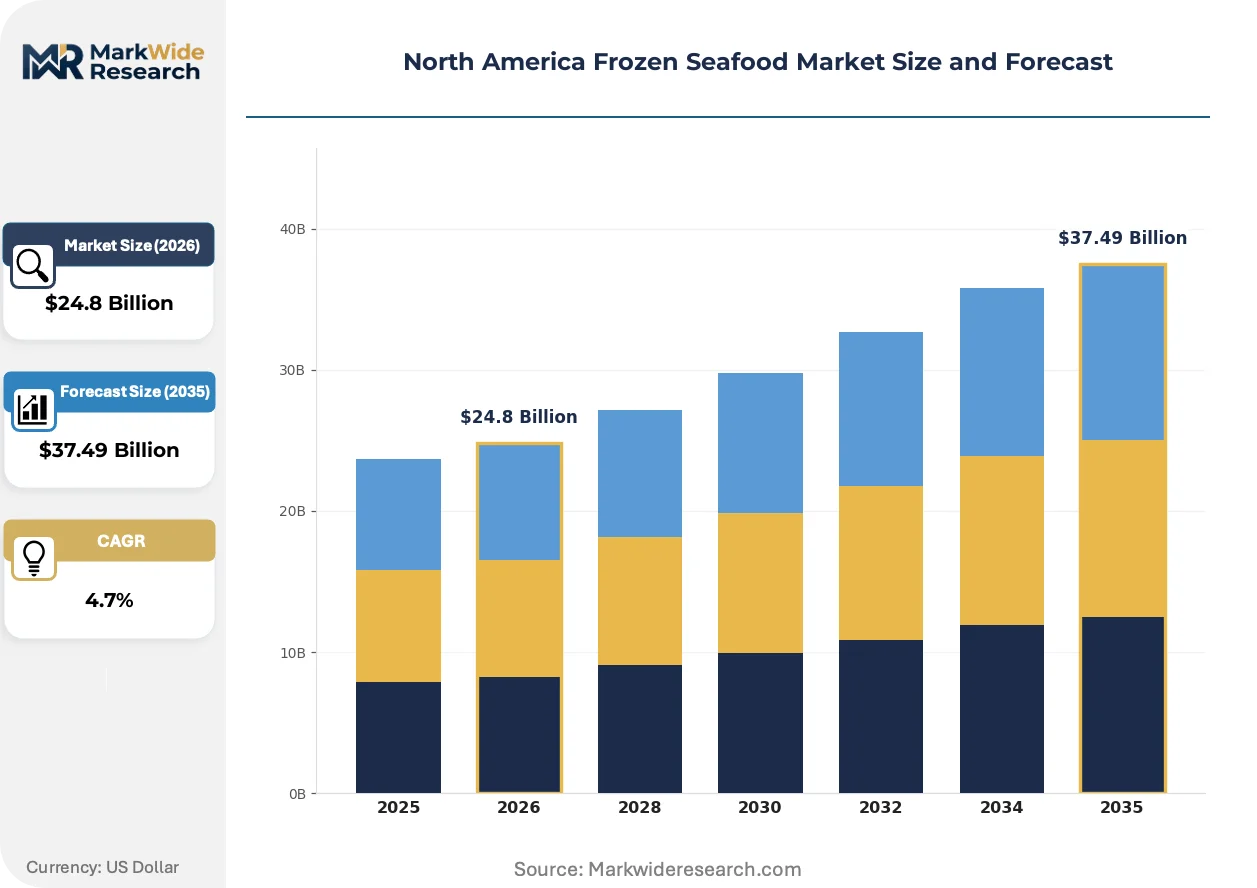
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.49 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shrimp, Crustaceans, Mollusks End User: Restaurants, Retailers, Foodservice Providers, Households Distribution Channel: Supermarkets, Online Retail, Wholesalers, Direct Sales Processing Method: IQF, Block Frozen, Breaded, Marinated |
| Companies Covered | Mowi ASA, Clearwater Seafoods, Thai Union Group PCL, Bumble Bee Foods, Pacific Seafood, High Liner Foods Inc., Nippon Suisan USA, Beaver Street Fisheries, Trident Seafood Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen Seafood Market Strategic Shifts & Innovations
Processing technology and regulatory transparency mandates are compressing traditional distributor roles while elevating data-rich, vertically coordinated supply relationships between harvesters and end-use buyers.
Blockchain-enabled traceability platforms are decentralizing chain-of-custody verification away from paper-based documentation and third-party audits toward immutable distributed ledgers accessible to regulators and retail buyers in real time. Major foodservice distributors and grocery retailers are piloting these systems for high-value species. This architecture is decentralizing compliance authority from centralized quality assurance departments toward operational nodes at the point of harvest and primary processing.
FDA's updated Seafood Hazard Analysis Critical Control Point regulations are mandating electronic traceability records for species-specific high-risk categories including tuna, mahi-mahi, and swordfish. Processors must maintain lot-level data from harvest through distribution. Smaller importers lacking IT infrastructure are exiting retail supply chains, while integrated harvester-processors are capturing displaced volume.
Buyer concentration among national foodservice management companies and e-grocery fulfillment platforms is compressing supplier margins while demanding spec-customized product configurations. Broadline distributors are losing share to processor-direct relationships. This pattern concentrates most visibly in the U.S. Northeast corridor and Ontario's Golden Horseshoe, where institutional procurement consolidation has advanced furthest.
North America Frozen Seafood Market Segmentation
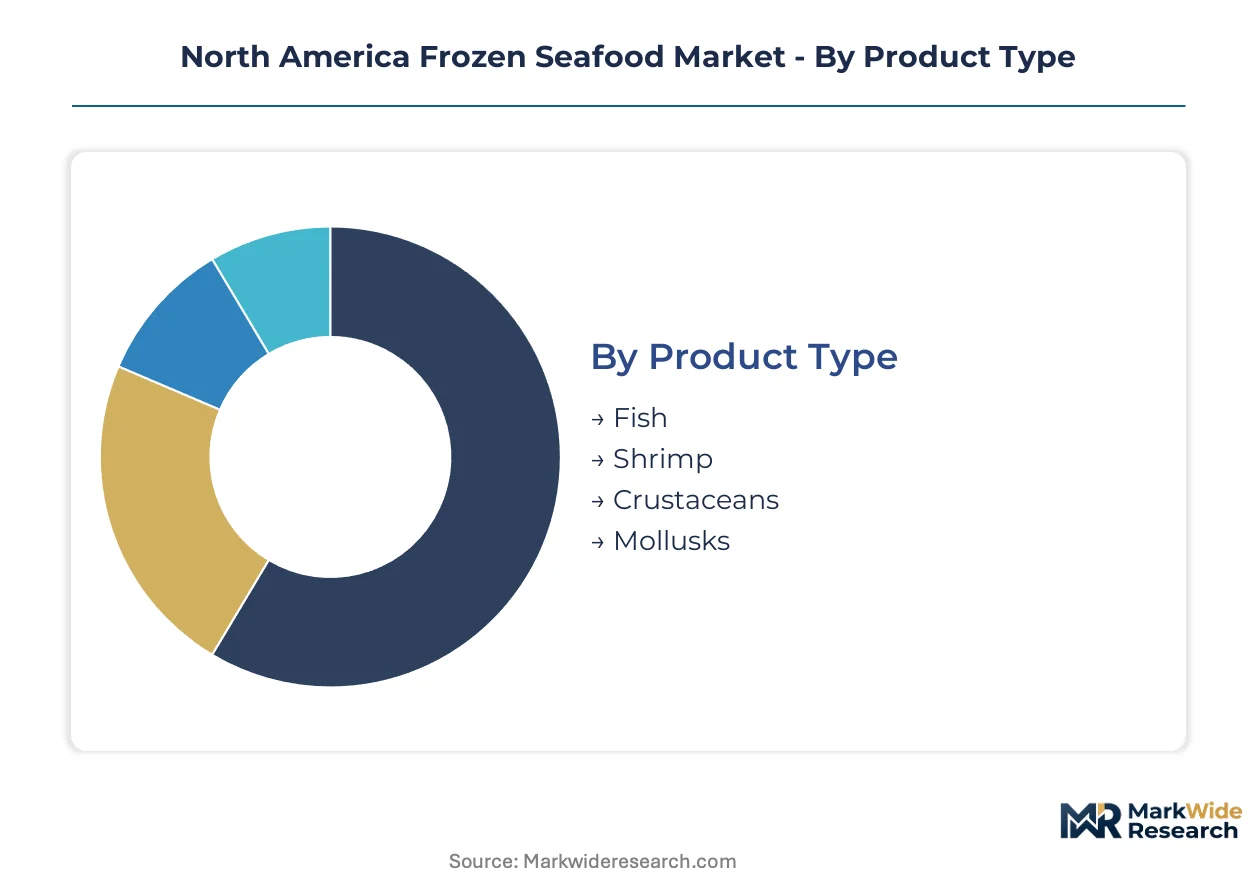
Segmentation in frozen seafood reveals how supply chain configuration and end-use requirements fragment procurement patterns across North America. Each dimension exposes distinct margin structures, regulatory exposure, and channel access requirements that shape processor investment priorities.
Product Type:
Supply concentration among wild-catch fisheries and aquaculture zones dictates which species categories command processing infrastructure investment and cold-chain prioritization.
- Fish:Pollock, cod, and salmon dominate absolute tonnage through IQF fillet processing optimized for foodservice portion control. Gulf Coast processors from Louisiana through Texas concentrate whitefish capacity to serve institutional buyers demanding consistent thaw-yield and cook-performance.
- Shrimp:Penaeid and coldwater varieties command per-unit premiums and faster inventory velocity across supermarket and e-grocery channels. FDA's Seafood HACCP species-specific traceability mandates hit shrimp imports hardest, advantaging vertically integrated suppliers with vessel-level documentation systems.
- Crustaceans:Snow crab and lobster segments depend on seasonal quota allocations from Alaskan and Atlantic Canadian fisheries.
- Mollusks:Scallop and clam processing clusters around Massachusetts and Atlantic Canada, serving raw-bar and retail deli applications.
Fish absorbs the bulk of installed capacity; shrimp is expanding most quickly.
End User:
Customer type determines specification tolerance, lot-size economics, and compliance documentation intensity across the value chain.
- Restaurants:Full-service and casual dining operators prioritize IQF portions with predictable cook-yields to manage kitchen labor costs. Cloud kitchen expansion is accelerating frozen seafood procurement for delivery-native concepts requiring extended holding tolerance.
- Foodservice Providers:Hospital and university systems are bypassing broadline distributors to contract directly with processors for spec-controlled volume, compressing traditional intermediary margins.
- Retailers:Supermarket and club store buyers demand value-added configurations including marinated and breaded products for private-label premiumization.
- Households:Direct-to-consumer e-grocery fulfillment favors individually packaged, recipe-ready frozen seafood with clear origin labeling.
Foodservice providers absorb the bulk of installed capacity; restaurants are climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale, geographic density, and tolerance for supply chain complexity versus price transparency.
- Supermarkets:Traditional grocery retail maintains dominant volume share through frozen seafood cases and dedicated planogram space for value-added products. Chains in the U.S. Northeast corridor and Ontario's Golden Horseshoe have advanced procurement consolidation furthest.
- Wholesalers:Broadline distributors face margin compression as processor-direct relationships displace traditional intermediary roles, particularly among national foodservice management companies.
- Online Retail:E-grocery fulfillment platforms demand spec-customized configurations with extended cold-chain resilience for last-mile delivery.
- Direct Sales:Institutional bypass channels are gaining traction among processors with sufficient scale to manage customer-specific documentation and logistics.
Supermarkets absorb the bulk of installed capacity; online retail is gaining share fastest.
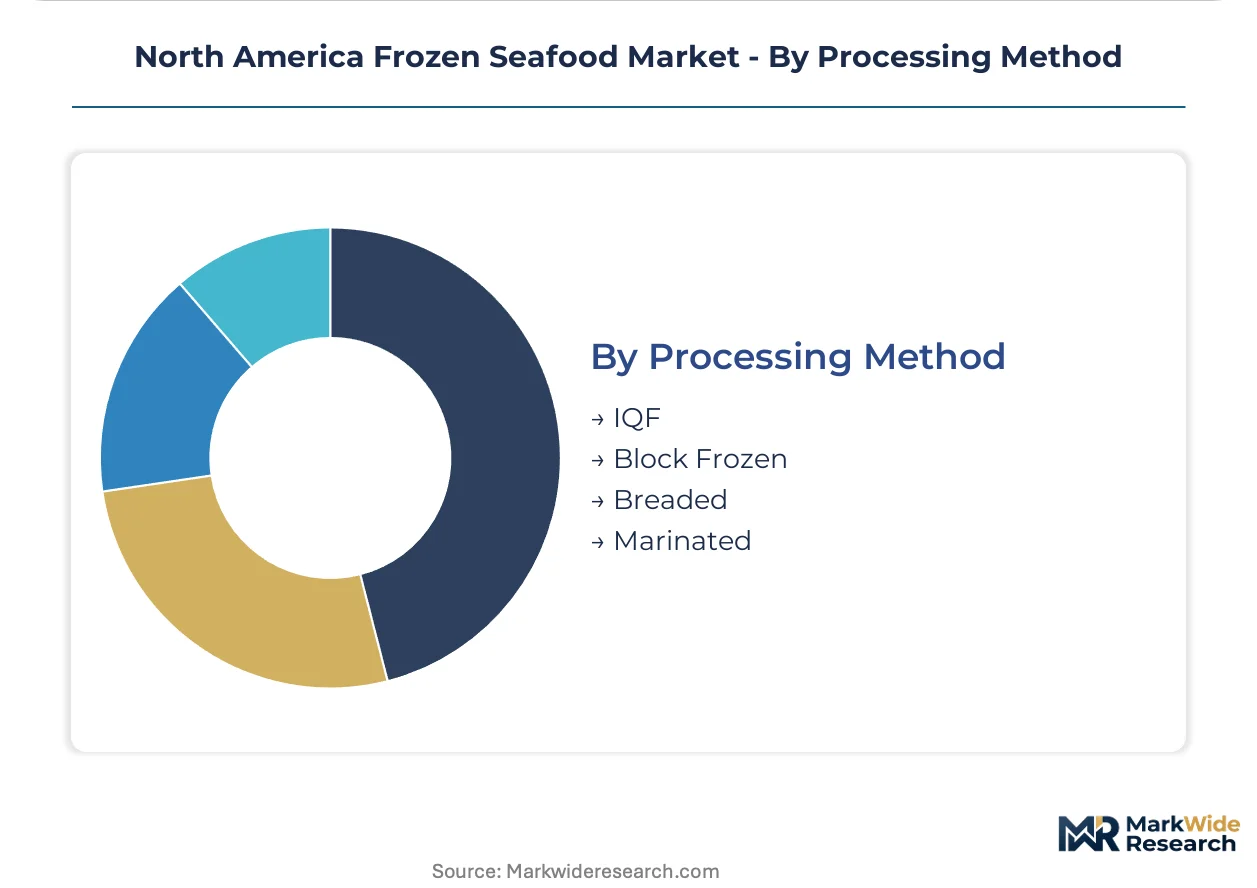
Processing Method:
Technology selection governs cellular integrity preservation, portion precision, and margin capture potential across end-use applications.
- IQF:Individual quick freezing dominates industrial throughput through blast-freeze tunnels that preserve texture upon thawing. This method leads volume due to suitability for portion-controlled foodservice applications from Louisiana through Texas processing corridors.
- Breaded:Value-added coating operations command shelf-space premiums in club retail and capture disproportionate margin pools through convenience positioning.
- Block Frozen:Traditional bulk freezing persists for commodity species destined for further processing or industrial food manufacturing.
- Marinated:Sauced and seasoned products target retail premiumization with recipe-ready positioning for time-constrained household consumers.
IQF absorbs the bulk of installed capacity; breaded is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Opportunity Zone tax incentives have concentrated frozen seafood processing infrastructure along the Louisiana-Texas corridor, drawing capital toward integrated cold-chain facilities serving institutional buyers.
United States
Foodservice labor inflation and FDA Seafood HACCP traceability mandates are consolidating procurement toward vertically integrated processors. The FDA's electronic traceability requirements for high-risk species are forcing smaller importers to exit retail channels. Gulf Coast processing clusters from Houma to Corpus Christi dominate whitefish IQF capacity for national foodservice distribution.
Canada
CFIA Safe Food for Canadians Regulations harmonization with U.S. import standards is accelerating cross-border processor qualification. Arctic surf clam and coldwater shrimp specialization anchors Atlantic Canada processing in Newfoundland and Nova Scotia. Clearwater Seafoods exemplifies this geographic concentration through integrated harvesting and primary processing operations.
Mexico
Shrimp aquaculture expansion in Sonora and Sinaloa is feeding frozen value-added processing for North American export. Mexican regulators align cold-chain documentation with USDA and CFIA standards to maintain preferential market access. Mazatlán processing clusters specialize in breaded and marinated shrimp products for U.S. club retail channels.
North America Frozen Seafood Market Key Industry Players
U.S. Gulf Coast producers anchor one tier; Canadian Atlantic specialists hold differentiated positions in premium coldwater species. The market exhibits tiered concentration with integrated harvester-processors commanding procurement relationships with national foodservice management companies. Three archetypes dominate: vertically integrated aquaculture operators, wild-catch specialists with quota-controlled access, and diversified protein conglomerates with branded retail portfolios. Competitive moves center on direct-to-institutional channel bypass and carbon disclosure credentialing for ESG-weighted procurement.
Within the integrated aquaculture tier, Mowi ASA represents end-to-end Atlantic salmon control from hatchery through frozen fillet distribution. Among diversified protein conglomerates, Thai Union Group PCL exemplifies branded and private-label tuna portfolio scale across North American mass retail. Clearwater Seafoods occupies a specialist position in Canadian Arctic surf clam and coldwater shrimp, demonstrating how quota-based wild-catch access creates defensible supply positions.
| Leading Market Players |
|---|
| Mowi ASA |
| Clearwater Seafoods |
| Thai Union Group PCL |
| Bumble Bee Foods |
| Pacific Seafood |
| High Liner Foods Inc. |
| Nippon Suisan USA |
| Beaver Street Fisheries |
| Trident Seafood Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between HACCP-compliant vessel-to-retail documentation and spot-market commodity lots manifests in both pricing premiums and supply chain configuration. FDA's electronic traceability mandates reward integrated harvester-processors with procurement access while decoupling small importers from mainstream retail channels.
Pricing Analysis
Short lead-time premiums attach to IQF portions with same-day fulfillment capability from Gulf Coast cold storage facilities. Contract-based long-term offtake dominates institutional procurement, with price differentiation driven by HACCP certification tier and volume scale commitments. Cost compression in commodity block-frozen segments is intensifying because diesel-powered reefer transport exposes distributors to fuel-cost volatility. Hospital and university foodservice systems show least price sensitivity given spec-controlled requirements, while broadline distributors face acute margin pressure from processor-direct bypass.
Supply Chain Analysis
Diesel-powered reefer transport and -18°C warehouse holding impose fuel-cost exposure that electric alternatives have not yet scaled to displace at intermodal distance. Supply concentrates in the United States Gulf Coast corridor from Louisiana through Texas, with secondary clusters in Atlantic Canada and Mexican Pacific processing zones. Raw material dependencies draw from Bering Sea pollock fisheries, Gulf menhaden quotas, and Sonora-Sinaloa shrimp aquaculture operations. Single-source vulnerability runs through seasonal quota allocations for wild-catch species lacking aquaculture hedges. Distribution runs through processor-direct channels displacing traditional broadline distributor roles among national foodservice management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability platforms are replacing paper-based documentation systems, compressing traditional distributor roles while elevating data-rich supply relationships between harvesters and end-use buyers.
For Market Incumbents: Lock in vessel-level documentation systems and electrified cold-chain infrastructure before SEC climate disclosure rules harden supplier qualification criteria. Defend margin position by deepening backward integration into hatchery and feed operations for aquaculture species. Prioritize certification investment in HACCP plan development talent to offset compliance talent scarcity compressing mid-size processor staffing. For New Entrants and Emerging Players: FDA's Seafood HACCP traceability mandates in the United States open a window for technology-native entrants with cloud-based lot-tracking systems. Target direct-to-institutional channels where hospital and university foodservice systems bypass broadline distributors for spec-controlled volume. Pursue carbon disclosure credentialing as the primary go-to-market angle for ESG-weighted procurement among coastal urban retailers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated aquaculture operators given FDA's electronic traceability requirements forcing smaller importers to exit retail channels. Long-term viability over the next decade hinges on controlling upstream supply positions with documented low-carbon catch methods. Watch for processor-direct contract announcements with national foodservice management companies as the inflection indicator signaling procurement consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Immutable distributed ledgers decentralize compliance authority from centralized quality assurance departments toward harvest nodes. |
| Electrified Cold-Chain Infrastructure | Electric reefer transport and warehouse systems reduce diesel-cost exposure while satisfying emerging carbon disclosure requirements. |
| Direct-to-Institutional Channel Development | Processor-direct relationships with hospital and university foodservice systems compress traditional broadline distributor margins. |
| Value-Added Product Line Expansion | Breaded and marinated configurations command shelf-space premiums in club retail and e-grocery fulfillment centers. |
| HACCP Compliance Talent Acquisition | Qualified seafood safety plan developers command wage premiums that create structural advantages for scaled processors. |
Research Approach
Trade databases, regulatory filings, and customs records formed the secondary backbone for volume and trade flow validation. Primary interviews with seafood processing executives, foodservice procurement directors, cold-chain logistics operators, and regulatory compliance officers combined with secondary validation to triangulate operational constraints and procurement priorities. Bottom-up and top-down approaches cross-checked segment-level estimates against aggregate market sizing.
Bottom-up modeling built volume and value outputs from species-specific processing capacity, quota allocations, and channel-specific price points across the projection horizon. Segmentation dimensions included product type, end user category, distribution channel, and processing method. CAGRs were derived from trend extrapolation of historical trade flows adjusted for regulatory phase-in schedules and technology adoption curves. Forecast inputs incorporated FDA traceability compliance timelines and electrified cold-chain infrastructure deployment rates.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled traceability would alter the outlook if distributed ledger standards fragment across competing platforms. Forecasts reflect assumptions regarding HACCP compliance phase-in adherence and diesel-to-electric reefer conversion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Seafood Flavors Market
Seafood
Japan Frozen Seafood Market
Seafood
Fish Oil Market
Seafood
Fish Processing Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
North America Salmon Market
Seafood
Tuna Market
Seafood
Fish Maw Market
Seafood
Lobster Market
Seafood
Oyster Market
Seafood
United States Seafood Market
Seafood
Caviar Market
Seafood
Global Seafood Market
Seafood
Alaskan Salmon Market
Seafood
Seafood Extracts Market