
 Argentina Nutraceuticals Market | 2026-2036
Argentina Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Nutraceuticals Market Outlook
Single-source ingredient procurement is decoupling from legacy supply arrangements as Argentine nutraceutical makers diversify botanical sourcing. Nestlé Argentina S.A. leverages its Cordoba manufacturing footprint to anchor domestic tablet and capsule production. Herbalife International Inc competes through direct-selling infrastructure that controls last-mile distribution in secondary cities.
Nutraceuticals comprise bioactive compounds, vitamins, minerals, and herbal extracts formulated at specified concentrations to deliver physiological benefits beyond basic nutrition, typically manufactured through spray-drying, microencapsulation, or fermentation processes for shelf-stable delivery in food, beverage, and supplement applications. Vitamins and probiotics command the deepest margin pools as Argentine consumers prioritize immunity and gut health positioning. Online Retail and Pharmacies split volume leadership, with digital channels capturing younger adult cohorts while pharmacy counters sustain senior trust and repeat purchase behavior.
ANMAT, Argentina's national drug and food control authority, enforces pre-market registration and Good Manufacturing Practice compliance that filters out informal importers and elevates quality thresholds for market entry. The country's food code and Mercosur technical regulations on supplements create a dual-layer compliance burden that favors established formulators with in-house regulatory affairs capacity. Stakeholders must monitor pending ANMAT guidance on novel ingredient classifications to anticipate reformulation costs and registration timelines.
Market Dynamics
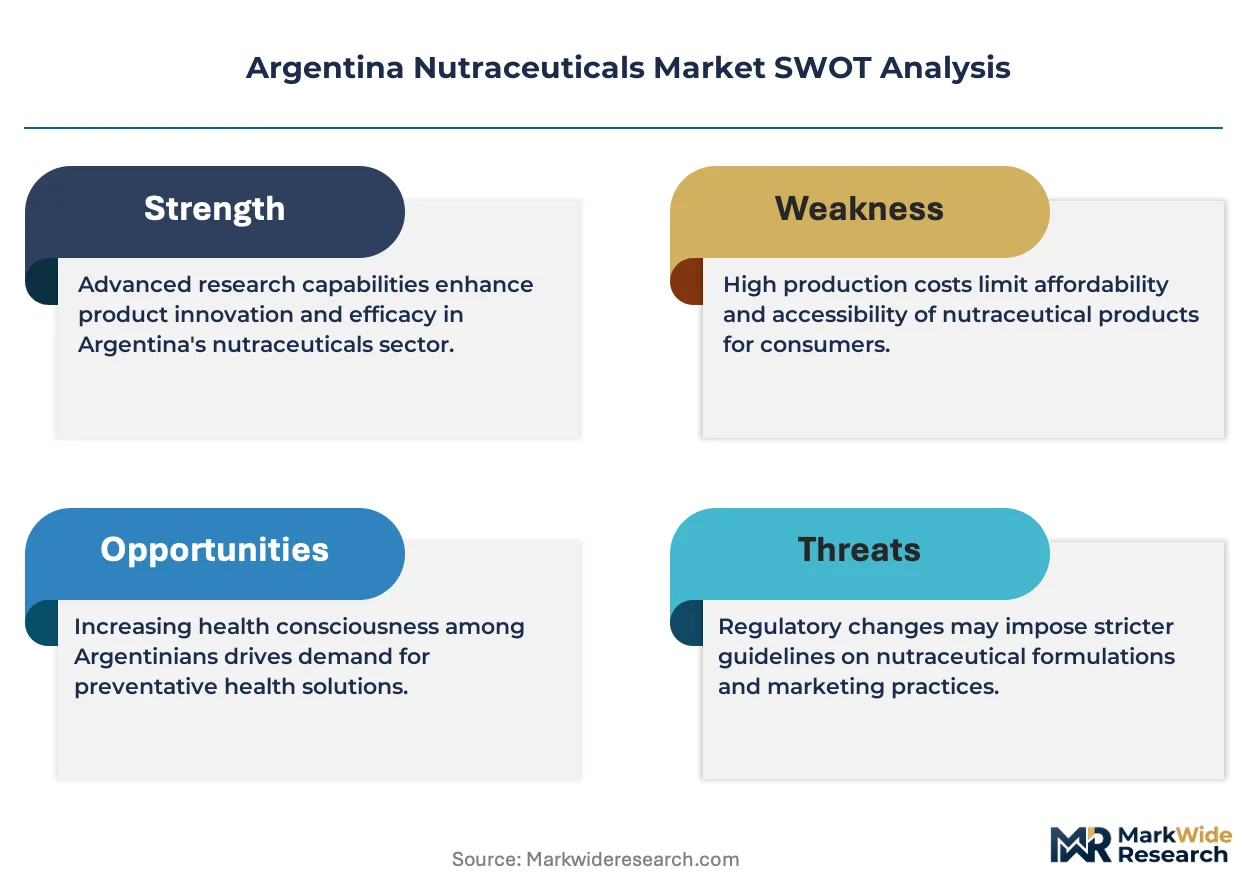
ANMAT's tightened labeling rules are forcing Argentine nutraceutical formulators to rebuild product registration dossiers, compressing time-to-market for botanical extracts and probiotic formulations while elevating compliance costs for smaller domestic manufacturers.
Growth Catalysts
- Sports Nutrition Adoption:Amateur athletes in Buenos Aires province and Córdoba are driving sustained demand for protein isolates and pre-workout formulations, expanding the addressable consumer base beyond traditional wellness segments.
- Pharmacy Channel Dominance:Chain pharmacies control shelf space allocation across Argentina's wealthiest provinces, creating predictable offtake volumes for registered supplement brands with established trade relationships.
- Mercosur Technical Regulations:Harmonized supplement standards across member states enable Argentine manufacturers to access Brazilian and Uruguayan markets without duplicative safety testing protocols.
Market Restraints
- Botanical Input Volatility:Yerba mate and calendula extract supply depends on harvest cycles in Misiones and Entre Ríos provinces, exposing formulators to raw material price swings.
- Import Dependency for Probiotic Strains:Lactobacillus and Bifidobacterium cultures concentrate among European and North American suppliers, creating foreign exchange exposure for domestic tablet producers.
- ANMAT Registration Bottlenecks:Novel ingredient classifications face extended evaluation timelines, delaying product launches for innovators ahead of established competitors.
Strategic Opportunities
- Patagonia Regional Expansion:Underpenetrated pharmacy networks in Neuquén, Río Negro, and Chubut provinces offer first-mover positioning for direct-selling operators with cold-chain logistics capability.
- E-commerce Subscription Models:Digital-native consumers in Rosario and Mendoza are migrating toward auto-replenishment platforms, reducing customer acquisition costs for recurring revenue streams.
- Clean Label Positioning:ANMAT's pending guidance on natural claim substantiation creates regulatory tailwind for brands with transparent supply chain documentation and third-party certification.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Experienced professionals capable of navigating ANMAT-Mercosur dual compliance are concentrated among incumbent firms, constraining new entrant execution speed.
- Microencapsulation Equipment Lead Times:Specialized spray-drying and fluid-bed coating systems require 18-24 month procurement cycles, compressing capital deployment flexibility for capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Nutraceuticals Market |
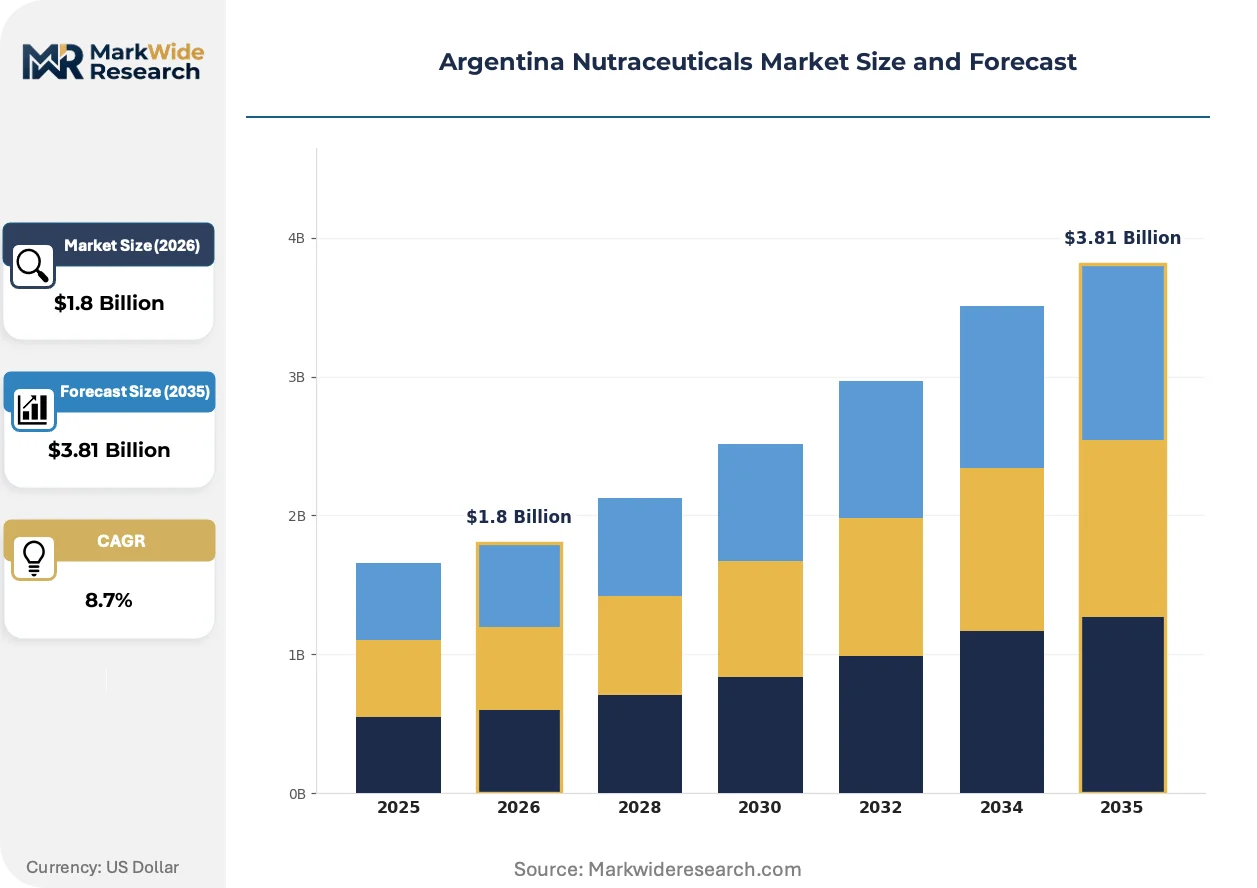
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Probiotics Distribution Channel: Online Retail, Pharmacies, Health Stores, Supermarkets End User: Adults, Seniors, Athletes, Children Form: Tablets, Capsules, Powders, Liquids |
| Companies Covered | Reckitt Benckiser Group PLC, Red Bull, Nestle SA, The Kellogg's Company, Herbalife International Inc, PepsiCo, The Coca-Cola Company, Nestlé Argentina S.A., Danone SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Nutraceuticals Market Strategic Shifts
Formulation science and distribution architecture are undergoing simultaneous transformation as Argentine consumers demand precision-dosed delivery formats and seamless omnichannel access to verified products.
Microencapsulation technology is overtaking conventional tablet compression for heat-sensitive probiotics and lipid-soluble vitamins, enabling shelf-stable products without refrigeration. Premium domestic brands and imported specialty lines are adopting this process to differentiate at pharmacy counters. The shift is compressing margin structures for legacy powder-format suppliers unable to fund equipment upgrades.
ANMAT's forthcoming novel food guidance is tightening safety dossier requirements for botanical extracts and postbiotic ingredients, forcing reformulation of existing SKUs. Manufacturers with in-house toxicology capabilities are accelerating pre-submission testing to secure early-mover registration slots. Probiotic and herbal supplement categories face the steepest compliance burden under the proposed rules.
Direct-to-consumer digital channels are capturing younger adult cohorts who bypass traditional pharmacy consultations for subscription-based personalized nutrition stacks. Buenos Aires-based wellness platforms leverage telehealth integrations to prescribe condition-specific supplement regimens. This behavioral pivot is fragmenting volume concentration away from pharmacy chains in Argentina's capital region.
Argentina Nutraceuticals Market Segmentation
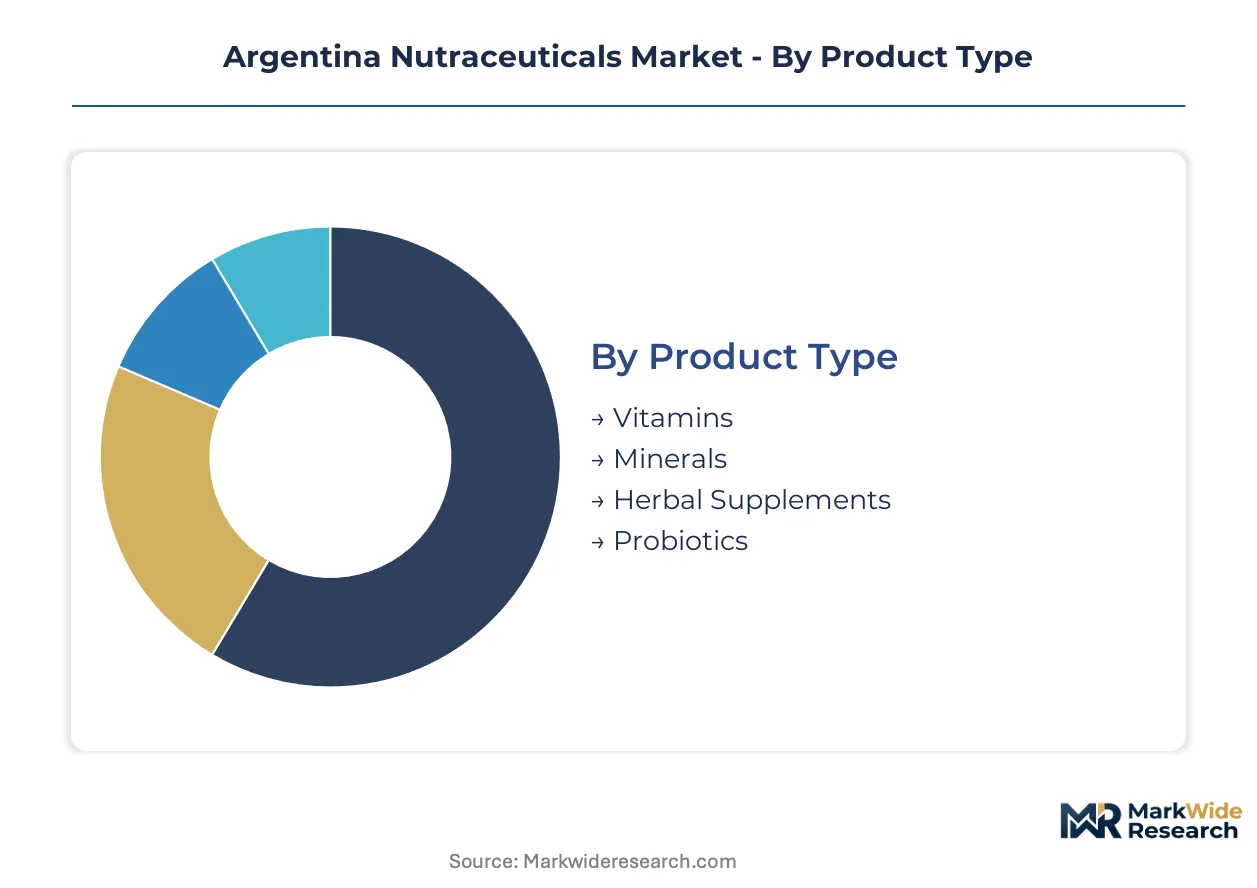
Segmentation in Argentina's nutraceuticals market reveals distinct procurement patterns across consumer demographics and channel preferences. Product form and distribution architecture determine margin capture, while end-user specialization drives formulation complexity and registration strategy.
Product Type:
Volume leadership concentrates in mass-market vitamins, yet premium positioning clusters around condition-specific probiotics and botanical extracts with substantiated health claims.
- Vitamins:Multivitamin complexes and single-nutrient formulations dominate pharmacy shelf space in Buenos Aires province. Adult consumers in Córdoba and Rosario sustain predictable replenishment cycles for immunity-positioned SKUs, though price compression from private-label entrants is narrowing brand premiums.
- Probiotics:Live culture formulations require cold-chain integrity and specialized microencapsulation for shelf stability. Demand from gut-health-conscious adults in Mendoza and Santa Fe is accelerating, with ANMAT's novel ingredient evaluations creating registration bottlenecks for strain-specific claims.
- Herbal Supplements:Yerba mate extracts and calendula formulations leverage domestic botanical sourcing from Misiones and Entre Ríos provinces.
- Minerals:Calcium, magnesium, and iron supplements serve pediatric and geriatric cohorts through pharmacy-dispensed formats.
Mature deployment sits with Vitamins. Newer deployment is concentrated in Probiotics.
Distribution Channel:
Channel selection determines customer acquisition economics, with digital platforms capturing subscription loyalty while pharmacy counters sustain trust-based repurchase behavior.
- Pharmacies:Chain pharmacy networks in Buenos Aires, Córdoba, and Santa Fe provinces control shelf space allocation and pharmacist recommendation influence. Senior consumers depend on counter consultation for condition-specific product matching, creating defensive moats for registered brands with established trade terms.
- Online Retail:Direct-to-consumer platforms and marketplace listings capture younger adult cohorts in Rosario and Mendoza. Auto-replenishment subscriptions reduce customer acquisition costs, though ANMAT's e-commerce labeling enforcement is elevating compliance burdens for digital-native entrants.
- Health Stores:Specialty retailers in Buenos Aires capital district serve clean-label seekers with third-party certified botanicals.
- Supermarkets:Mass-market vitamin and mineral placements reach price-sensitive consumers through grocery consolidation trips.
Volume concentration remains with Pharmacies. Digital expansion is climbing the fastest among channels.
End User:
User segmentation dictates formulation potency, delivery format preferences, and the regulatory pathway for health claim substantiation.
- Adults:Working-age consumers aged 25-55 drive volume across stress-management adaptogens, omega-3 fatty acids, and protein supplementation. Buenos Aires province households allocate disproportionate spending to preventive wellness stacks combining multiple product categories.
- Athletes:Amateur and semi-professional competitors in Córdoba and Buenos Aires province sustain demand for pre-workout formulations, protein isolates, and recovery-positioned branched-chain amino acids. Sports nutrition brands compete on batch-tested certification and banned-substance screening.
- Seniors:Bone health and cognitive support formulations serve Argentina's aging population through pharmacy-dispensed, pharmacist-guided selection.
- Children:Pediatric vitamin D and omega-3 formulations face stringent ANMAT dosing restrictions and packaging safety requirements.
Established demand centers on Adults. Emerging momentum clusters with Athletes.
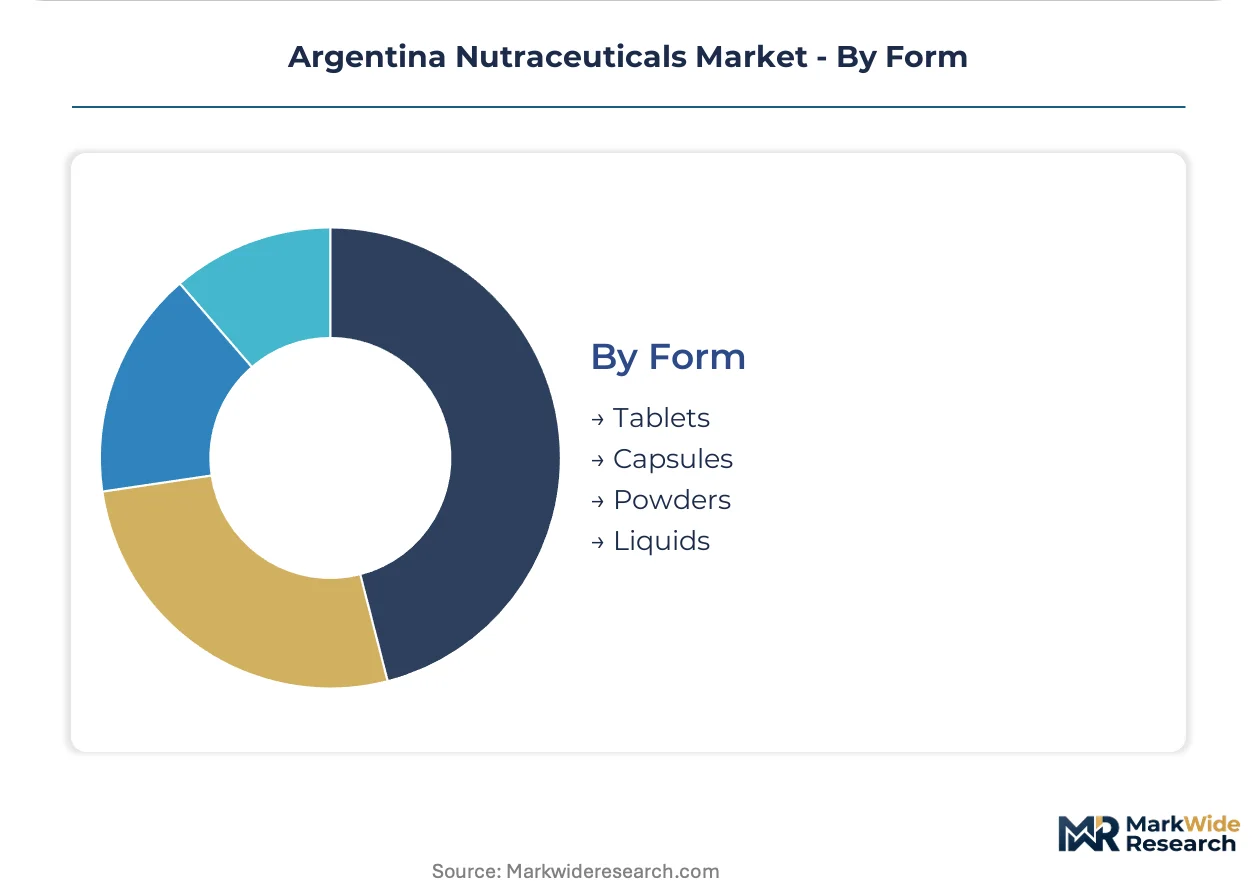
Form:
Delivery technology selection balances bioavailability claims, manufacturing capital requirements, and consumer convenience preferences across temperature zones.
- Capsules:Gelatin and vegetable-based shells enable precise dosing of lipid-soluble vitamins and probiotic blends. Argentine manufacturers with fluid-bed coating capability command premium positioning for enteric-release formulations targeting the pharmacy channel.
- Tablets:Compressed powder formats remain the cost-optimized default for mass-market mineral and vitamin production. Nestlé Argentina's Córdoba facility anchors domestic tablet capacity, though legacy equipment struggles with heat-sensitive probiotic integration.
- Powders:Bulk protein and pre-workout formulations serve athlete segments with flavor-customizable dosing flexibility.
- Liquids:Pediatric and geriatric-focused formulations prioritize ease of swallowing and dose titration in Misiones and Entre Ríos distribution.
Tablet production holds mature scale. Capsule adoption is expanding most quickly for premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Misiones province's yerba mate plantations and Entre Ríos calendula harvests anchor Argentina's botanical nutraceutical supply base, with extraction facilities clustering near raw material sources to minimize transport spoilage.
Buenos Aires Province
Pharmacy chains control shelf space allocation across Greater Buenos Aires and La Plata, driving predictable offtake volumes for registered supplement brands. ANMAT's pre-market registration requirements filter informal competitors from pharmacy counters. Industrial parks in Pilar and Campana host tablet and capsule manufacturing operations serving national distribution networks.
Córdoba
Amateur athletes sustain demand for protein isolates and pre-workout formulations through specialty retailers and direct-selling channels. Nestlé Argentina's manufacturing footprint anchors domestic production capacity for mass-market vitamins. The city of Córdoba serves as a logistics hub connecting central Argentina to Mendoza and Santa Fe distribution corridors.
Mendoza
Wine country wellness tourism generates seasonal demand for antioxidant-positioned resveratrol supplements and grape seed extracts. Online retail platforms capture younger adult cohorts migrating toward auto-replenishment subscription models. Local health stores in Mendoza capital specialize in clean-label botanicals with third-party organic certification.
Santa Fe
Rosario's industrial base supports packaging and labeling suppliers serving nutraceutical formulators across the Litoral region. Pharmacy networks in Santa Fe city maintain established trade relationships with registered supplement brands. The province's soybean processing infrastructure creates byproduct opportunities for lecithin and protein concentrate derivatives.
Patagonia South
Underpenetrated pharmacy networks in Neuquén, Río Negro, and Chubut provinces offer expansion terrain for direct-selling operators with cold-chain logistics capability. Seasonal population fluctuations around tourism and energy sectors create demand volatility for supplement distributors. Bariloche and Neuquén city clusters represent nascent health store development.
Argentina Nutraceuticals Market Competitive Environment
Global majors compete with regional champions across formulation technology and distribution reach, producing a tiered structure where multinational CPG conglomerates hold mass-market scale and domestic specialists capture premium positioning. The market fragments across direct-selling networks, pharmacy-dependent registered brands, and digital-native subscription platforms. Three archetypes dominate: diversified nutrition conglomerates with manufacturing depth, direct-selling operators controlling last-mile access, and specialty botanical formulators leveraging domestic sourcing. Competitive moves center on ANMAT registration dossier preparation and microencapsulation equipment procurement.
Among diversified nutrition conglomerates, Nestlé Argentina S.A. and Nestle SA occupy positions exemplifying integrated manufacturing and brand portfolio breadth. Herbalife International Inc represents the direct-selling archetype with infrastructure controlling secondary city distribution. Reckitt Benckiser Group PLC anchors the pharmacy-channel specialist tier with registered brands navigating ANMAT compliance pathways.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| Red Bull |
| Nestle SA |
| The Kellogg's Company |
| Herbalife International Inc |
| PepsiCo |
| The Coca-Cola Company |
| Nestlé Argentina S.A. |
| Danone SA |
| Others |
Value Chain & Pricing Dynamics
Captive botanical sourcing from Misiones and Entre Ríos provinces anchors both supply security and premium pricing power for Argentine formulators, while import-dependent probiotic strains expose cost structures to foreign exchange volatility. ANMAT registration requirements create tiered market access where compliant manufacturers capture pharmacy shelf premiums against informal competitors.
Pricing Analysis
Service-bundled registration consulting separates formal pharmacy-channel brands from unassisted digital entrants facing ANMAT compliance delays. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and cold-chain integrity guarantees. Price compression in mass-market vitamins intensifies as private-label entrants narrow brand premiums. Senior consumers through pharmacy counters show lowest price sensitivity, while younger digital-native cohorts prioritize subscription convenience over unit cost.
Supply Chain Analysis
ANMAT Good Manufacturing Practice certification gates supplier qualification, filtering informal importers from formal channel access. Botanical inputs concentrate in Argentina's northeastern provinces, while live probiotic cultures draw from European and North American specialist suppliers. Single-source vulnerability in microencapsulation equipment creates eighteen-to-twenty-four-month procurement bottlenecks for capacity expansion. Distribution runs through chain pharmacy networks in Buenos Aires and Córdoba, with direct-selling infrastructure penetrating secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's nutraceutical sector sits in a delivery-format transition, with microencapsulation technology displacing conventional tablet compression for heat-sensitive probiotics and lipid-soluble vitamins.
For Market Incumbents: Deepen captive control over yerba mate and calendula extraction capacity in Misiones to defend margin position against botanical price volatility. Prioritize in-house toxicology capabilities for ANMAT novel ingredient pre-submission testing ahead of pending guidance releases. For New Entrants and Emerging Players: Amateur athletes in underpenetrated Patagonia provinces represent a service-underserved buyer archetype with unmet demand for batch-tested sports nutrition. Build cold-chain logistics partnerships with regional distributors before pharmacy chains consolidate shelf access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutrition conglomerates seeking ANMAT-registered manufacturing footprints. Long-term viability favors targets with dual Mercosur export capability and microencapsulation equipment already installed. Watch ANMAT novel food guidance publication timing as inflection indicator for reformulation cost waves.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Equipment Procurement | Enables shelf-stable probiotic formulations without refrigeration for pharmacy channel premium positioning. |
| ANMAT Registration Dossier Acceleration | Secures early-mover slots for novel botanical extracts ahead of competitor submission backlogs. |
| Direct-Selling Infrastructure Expansion | Controls last-mile distribution in secondary cities where pharmacy chain penetration remains thin. |
| Backward Integration into Botanical Extraction | Captures margin from yerba mate and calendula supply through captive processing in Misiones. |
| E-commerce Subscription Platform Launch | Captures recurring revenue from younger adults in Rosario and Mendoza bypassing pharmacy counters. |
Study Parameters
ANMAT regulatory filings, Mercosur technical regulation databases, and Argentine customs trade records formed the secondary backbone for supply chain mapping and competitive landscape validation. Primary interviews with regulatory affairs directors at registered supplement manufacturers, procurement managers at chain pharmacy networks, and formulation scientists at Córdoba manufacturing facilities combined with secondary triangulation using bottom-up production capacity estimates and top-down consumption surveys.
Historical trendline analysis of vitamin, probiotic, and botanical supplement volumes informed projection modeling across product type, distribution channel, end user, and delivery form dimensions. CAGRs derived from segment-level growth trajectory extrapolation incorporated ANMAT registration timeline assumptions and pharmacy channel expansion rates into the analytical framework.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANMAT novel ingredient classification delays and Mercosur harmonization pace. Forecasts reflect documented assumptions on regulatory approval timelines and raw material harvest cycle stability. A model refresh is warranted upon material change in ANMAT guidance publication schedules or significant currency volatility affecting probiotic strain import costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Omega 3 Market