
 United States Plant-Based Seafood Market | 2026-2036
United States Plant-Based Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
United States Plant-Based Seafood Market Intelligence
Precision fermentation of algal oils and legume-derived protein isolates is reshaping the ingredient architecture of plant-based seafood, enabling manufacturers to replicate the flaky texture and omega-3 lipid profiles of conventional catch. Good Catch leverages proprietary legume-blend formulations to anchor its position in the refrigerated case. Beyond Meat sustains R&D intensity across multiple alternative protein platforms. Sophie's Kitchen specializes in allergen-free recipes that differentiate its shelf-stable offerings.
Plant-based seafood comprises formulated food products engineered from non-animal proteins, algal extracts, and lipid systems to simulate the sensory properties, nutritional composition, and culinary performance of finfish and shellfish, typically achieving protein contents of 15-20 grams per serving through extrusion or shear-cell processing. These products serve commercial and institutional buyers seeking to reduce supply-chain exposure to wild-catch volatility and aquaculture environmental externalities. Fish fillets occupy the dominant volume position within product type segmentation, while shrimp formats represent the fastest-growing sub-category as batter-and-fry applications translate cleanly from conventional analogs. Pea protein anchors the ingredient source mix due to its neutral flavor and functional gelling properties, though seaweed-derived formulations are gaining traction in premium positioning.
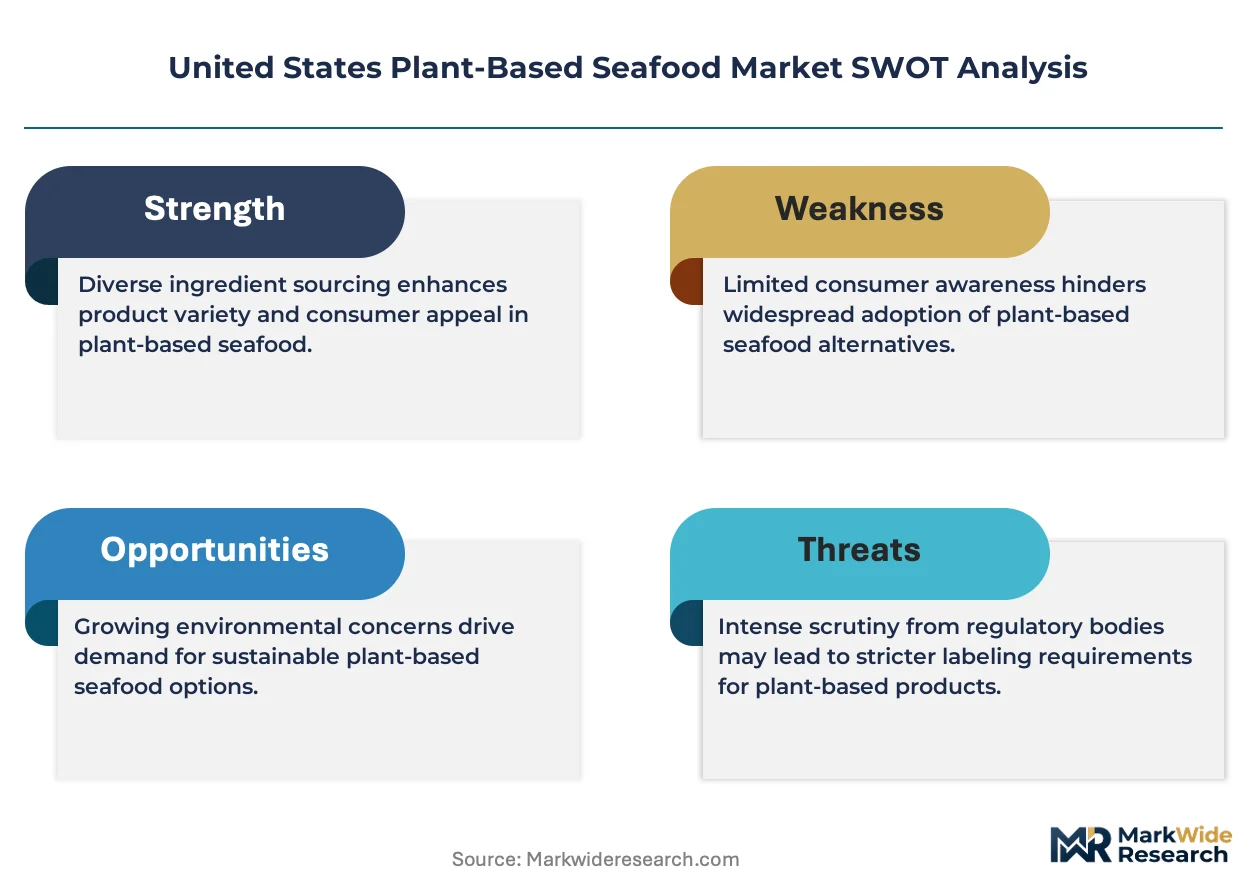
FDA standards of identity and USDA FSIS labeling jurisdiction shape how plant-based seafood products present themselves to consumers, with ongoing scrutiny of "seafood" descriptor usage creating compliance complexity for market entrants. California's Proposition 65 warning requirements and state-level clean-label statutes add layered obligations for brands distributing nationally. Stakeholders must monitor evolving federal enforcement postures on protein descriptor terminology while calibrating formulation investments against shifting state-level retail standards.
Market Dynamics
FDA standards of identity scrutiny and USDA FSIS labeling jurisdiction are compressing formulation-to-shelf timelines while forcing manufacturers to rebuild descriptor compliance protocols from the ground up. This regulatory pressure is concentrating investment in legal and R&D functions ahead of production scale.
Growth Catalysts
- California Proposition 65:Clean-label statutes in coastal states are accelerating reformulation investments that strip artificial binders from plant-based seafood recipes.
- University food service:Institutional procurement mandates for sustainable protein alternatives are pulling tonnage through distribution channels faster than retail adoption curves.
- Shear-cell processing:This extrusion technology is enabling flaky texture replication without traditional high-pressure equipment, lowering capital barriers for new entrants.
Market Restraints
- Pea protein concentrate:Input cost volatility in legume-derived isolates is squeezing gross margins for mid-tier producers without long-term supply contracts.
- Pacific Northwest processing:Supply concentration in coastal manufacturing clusters exposes distribution networks to climate-related logistics disruptions.
- Omega-3 lipid stability:Technical limitations in algal oil oxidation control are shortening refrigerated shelf life versus conventional frozen seafood.
Strategic Opportunities
- Midwest institutional cafeterias:Underpenetrated geography in landlocked states offers volume contracts with lower competitive intensity than coastal metros.
- IRA clean energy credits:Federal biomanufacturing incentives are offsetting fermentation facility capex for precision lipid production.
- Direct-to-foodservice platforms:Distribution innovation bypassing traditional broadline distributors is capturing margin and shortening feedback loops.
Industry Challenges
- Food technologist scarcity:Talent gaps in alternative protein formulation are extending product development cycles and inflating compensation benchmarks.
- FDA GRAS notification timelines:Certification delays for novel algal protein ingredients are freezing pipeline launches for twelve to eighteen months.
- Legacy ERP integration:Supply chain reconfiguration friction with conventional seafood tracking systems is complicating lot-traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Plant-Based Seafood Market |
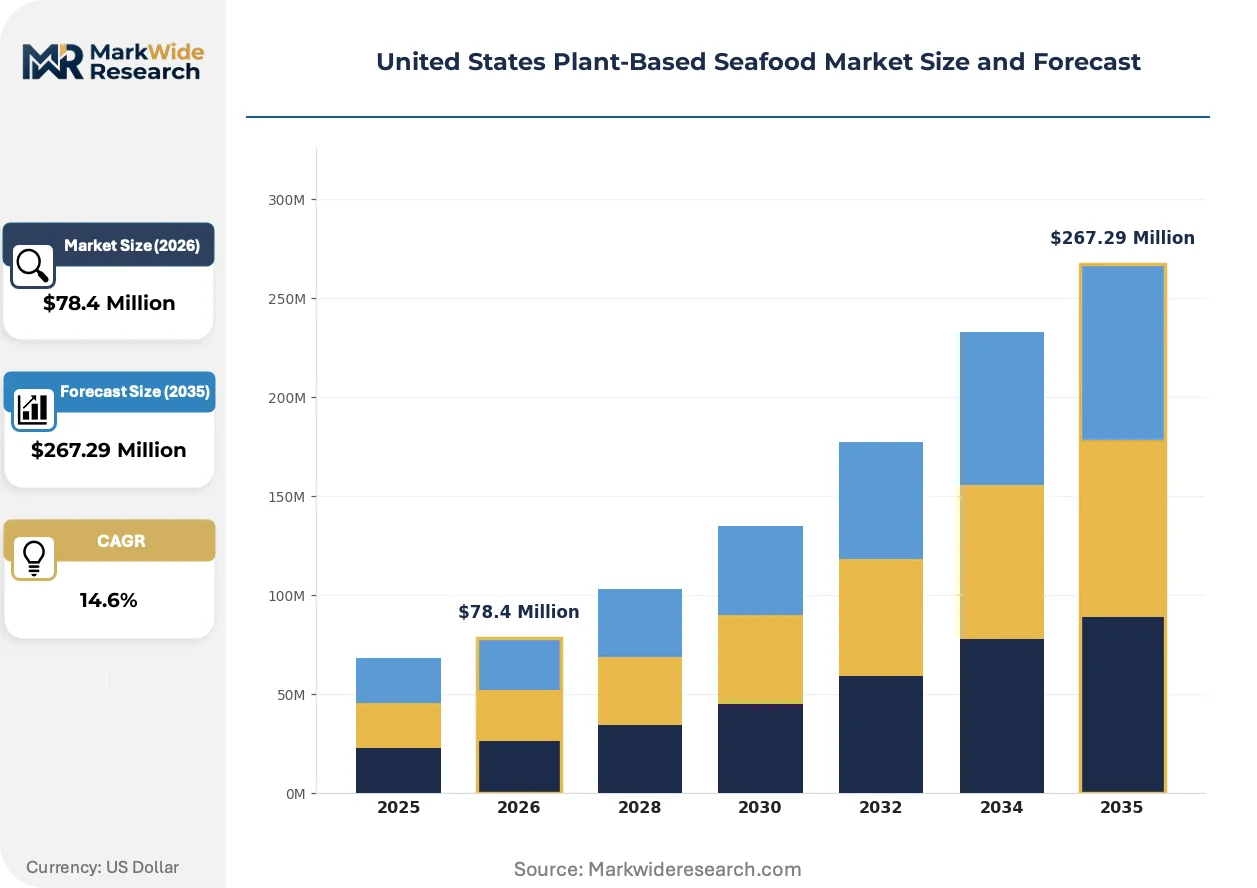
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $267.29 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Fillets, Shrimp, Crab Cakes, Fish Sticks End User: Households, Restaurants, Food Service, Retail Chains Distribution Channel: Online, Grocery Stores, Supermarkets, Specialty Stores Ingredient Source: Pea Protein, Seaweed, Soy Protein, Others |
| Companies Covered | Good Catch, Ocean Hugger Foods, New Wave Foods, Gardein, Beyond Meat, Impossible Foods, Sophie's Kitchen, The Plant Based Seafood Co., Turtle Island Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Plant-Based Seafood Market Strategic Shifts & Innovations
Ingredient architecture is fragmenting as manufacturers abandon single-source protein strategies in favor of modular formulation platforms that swap inputs based on cost and availability. This flexibility is becoming the defining operational capability separating viable scale players from niche brands.
Precision fermentation of algal oils is hybridizing with legume protein isolates to replicate both the lipid profile and muscle fiber structure of conventional catch. Foodservice operators in coastal metropolitan areas are adopting these hybrid formulations at accelerated pace for batter-and-fry applications. The technology is hybridizing cost structures, compressing the premium gap between plant-based and mid-tier conventional seafood to under fifteen percent at wholesale.
USDA FSIS labeling jurisdiction over certain plant-based seafood categories is tightening descriptor usage, forcing manufacturers to abandon "fish" and "shrimp" claims in favor of qualified compound terms. This industrial consequence is triggering packaging redesign cycles and retail slotting fee renegotiations. Refrigerated case products in California and Pacific Northwest grocery channels are most affected, with brands responding through front-of-package iconography systems that communicate species analogs without prohibited terminology.
Buyer concentration in contract foodservice management companies is consolidating procurement decisions into fewer hands, displacing the fragmented independent restaurant channel that drove early adoption. Broadline distributors are losing share to specialized alternative protein distributors with technical sales capabilities. This pattern is most visible in university and corporate campus dining verticals, where sustainability procurement scorecards now weight plant-based seafood inclusion as a scored criterion.
United States Plant-Based Seafood Market Segmentation
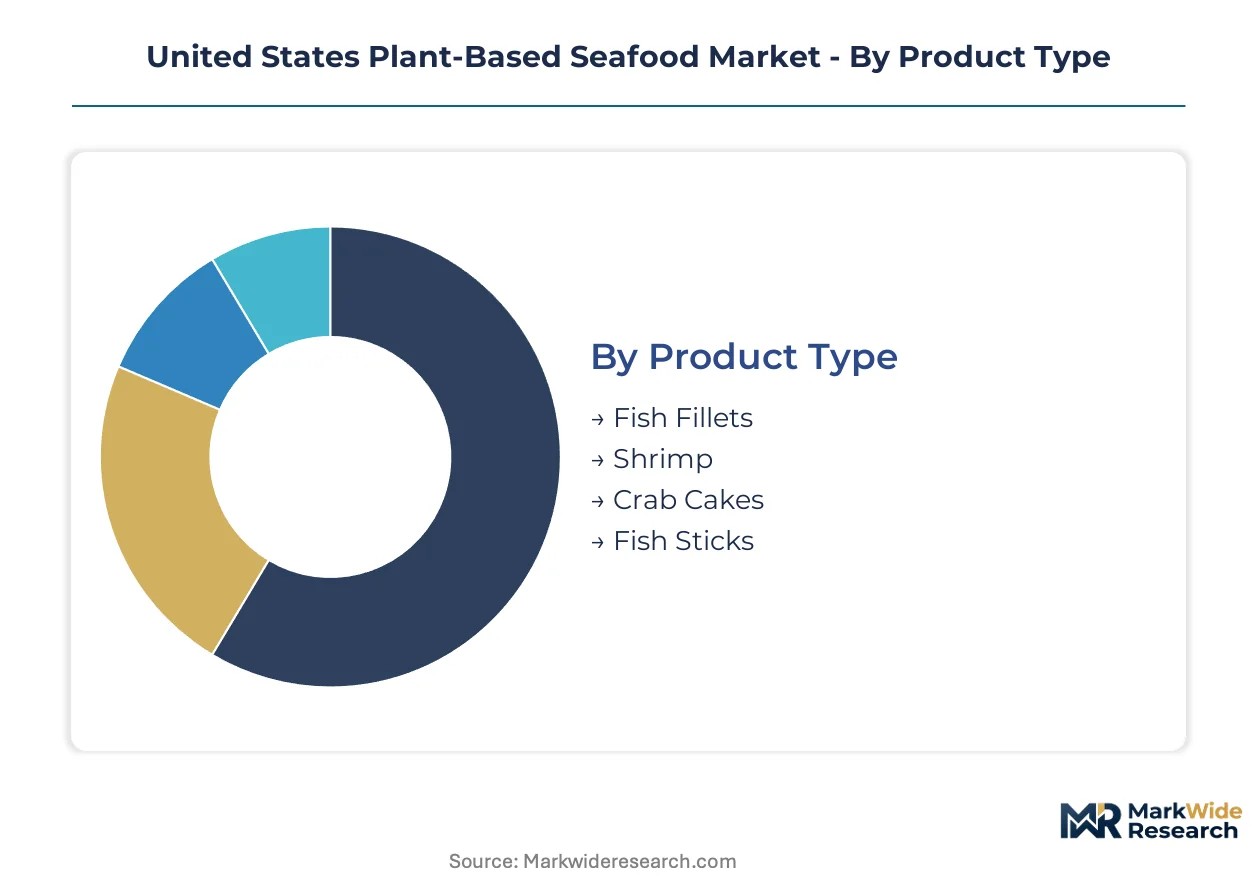
Plant-based seafood manufacturers configure production lines around distinct technical specifications and buyer requirements. Segment-level dynamics determine formulation investments, shelf placement negotiations, and margin structures across the value chain.
Product Type:
Inventory velocity varies sharply across formats, with frozen breaded items turning fastest and refrigerated whole-muscle products commanding extended shelf cycles.
- Fish Fillets:Extruded whole-cut formats replicate cod and tilapia flake structures through shear-cell processing. University cafeterias in California and the Pacific Northwest specify these for center-plate protein applications, though refrigerated distribution constraints limit geographic reach.
- Shrimp:Batter-coated bite formats achieve the highest velocity in quick-service fried applications. Foodservice operators in coastal metropolitan areas are expanding procurement as texture replication crosses acceptable sensory thresholds for mainstream consumers.
- Crab Cakes:Premium-priced formed products targeting white-tablecloth accounts with higher margin tolerance.
- Fish Sticks:Frozen family-pack formats driving trial through retail promotional cycles.
Fish fillets dominate installed base. Shrimp is where expansion concentrates.
End User:
Contract structures range from spot purchasing to multi-year sustainability procurement agreements, with institutional buyers extracting steeper volume discounts than fragmented household accounts.
- Households:Trial-driven purchasers responding to front-of-package sustainability claims and price promotions in conventional grocery.
- Restaurants:Independent operators testing limited-time offers before committing to permanent menu integration.
- Food Service:Contract management companies at universities and corporate campuses now mandate plant-based seafood inclusion in sustainability scorecards, consolidating procurement into fewer decision-makers.
- Retail Chains:Category managers negotiating slotting fees and refrigerated case placement against conventional frozen seafood.
Food service anchors volume commitment. Households represent the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, with direct-to-foodservice platforms bypassing traditional broadline distributor markups.
- Online:Subscription and direct-to-consumer models building repeat purchase through frozen home delivery.
- Grocery Stores:Regional chains testing limited SKU counts in frozen cases before refrigerated expansion.
- Supermarkets:National banners negotiating exclusive brand placements and promotional calendar coordination.
- Specialty Stores:Natural and organic retailers accepting premium price points for certified clean-label formulations.
Supermarkets control shelf access. Online is gaining share fastest.
Ingredient Source:
Input cost volatility and FDA GRAS notification timelines are fragmenting supplier strategies toward modular formulation platforms.
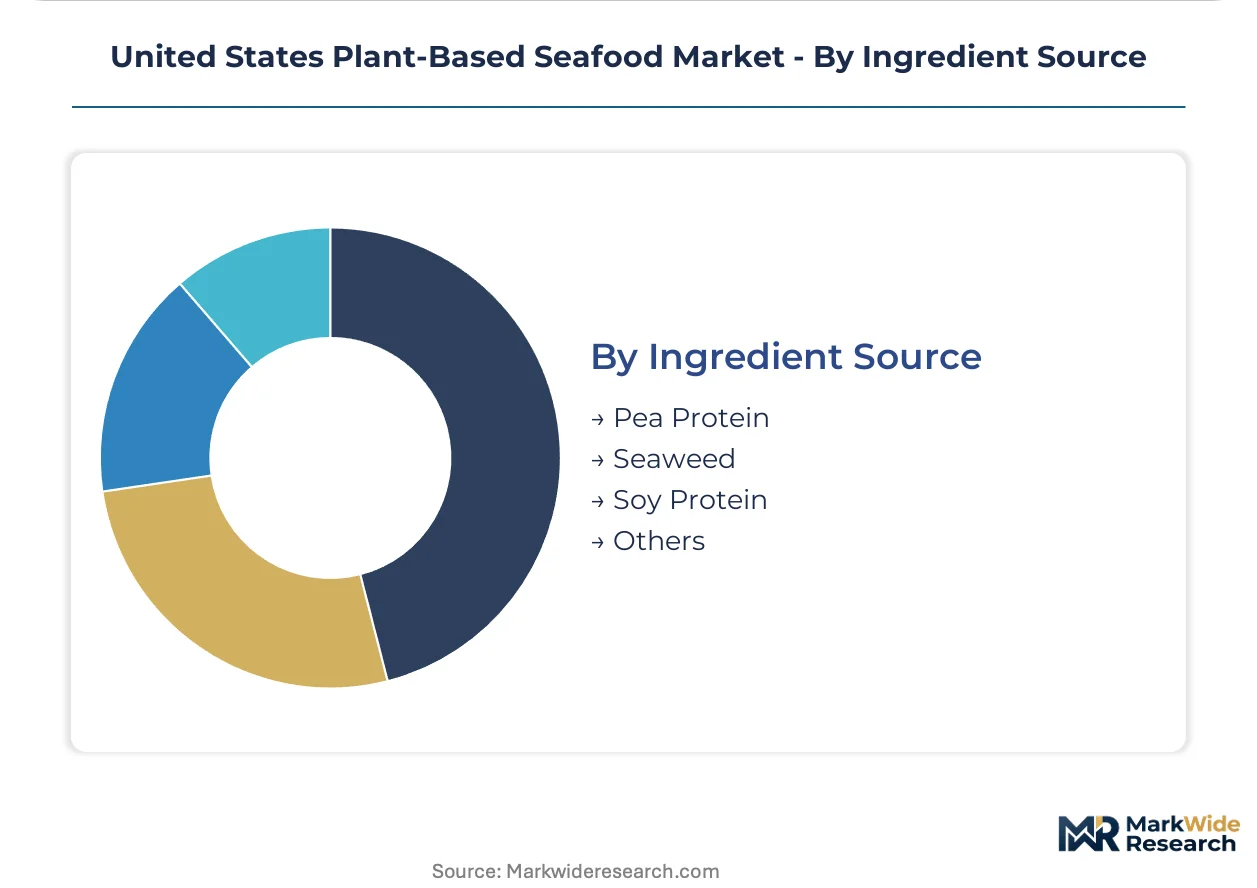
- Pea Protein:Neutral-flavor isolates with proven gelling functionality anchor mainstream production, though concentrate price swings squeeze mid-tier producers without long-term contracts.
- Seaweed:Algal extracts and whole-plant formulations enabling premium positioning and omega-3 lipid claims in coastal metropolitan markets.
- Soy Protein:Legacy ingredient with established supply chains but allergen labeling constraints limiting foodservice penetration.
- Others:Emerging legume blends and fungal protein isolates awaiting regulatory clearance for commercial scale.
Pea protein dominates formulation base. Seaweed is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement managers at universities and corporate campuses concentrate demand in coastal metropolitan corridors, while retail distribution networks extend refrigerated and frozen formats into secondary markets. Sustainability scorecards and clean-label mandates drive regional purchasing patterns.
California
University cafeteria systems and quick-service chains anchor volume procurement in Los Angeles and San Francisco metropolitan areas. Proposition 65 warning requirements and state-level clean-label statutes impose layered compliance obligations on brands distributing through California retail channels. Precision fermentation facilities in the San Diego biotech corridor supply algal oil inputs to regional formulation plants.
Pacific Northwest
Seattle and Portland foodservice operators lead adoption of whole-cut fish fillet formats for center-plate applications. Washington State Department of Agriculture enforcement of organic certification standards affects premium product positioning in specialty retail. Shear-cell processing equipment manufacturers cluster in the Portland metro area, serving regional contract manufacturers.
Texas
Dallas-Fort Worth and Houston institutional dining contracts represent underpenetrated expansion territory for direct-to-foodservice distribution platforms. Texas Department of State Health Services food safety regulations govern refrigerated supply chain protocols for plant-based seafood entering broadline distribution. Emerging production facilities in the Austin metro area target central U.S. logistics efficiency.
New York Metro
White-tablecloth restaurants and corporate campus dining in Manhattan and Brooklyn drive premium crab cake and formed product demand. New York State Department of Agriculture and Markets labeling enforcement shapes descriptor compliance for products entering Northeast retail banners. Brooklyn-based alternative protein R&D labs supply formulation expertise to regional brands.
Midwest
Chicago and Detroit university foodservice systems present volume contract opportunities with lower competitive intensity than coastal markets. Illinois Department of Agriculture inspection protocols align with USDA FSIS standards for alternative protein retail placement. Cold chain distribution hubs in the Chicago metropolitan area enable frozen format penetration into landlocked states.
United States Plant-Based Seafood Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base separates into scale-driven multinationals with broad protein platforms, mid-cap specialists with single-category focus, and emerging entrants leveraging novel processing technologies. Dominant competitive moves include portfolio diversification into adjacent alternative protein categories and strategic partnerships with foodservice management companies.
Within the specialist tier, Good Catch, Sophie's Kitchen, and Beyond Meat exemplify distinct formulation philosophies. Good Catch anchors legume-blend approaches in refrigerated case placement. Sophie's Kitchen occupies allergen-free positioning in shelf-stable formats. Beyond Meat represents scale-driven R&D intensity across multiple alternative protein platforms. These three players illustrate how technical differentiation and channel strategy separate viable competitors from niche participants.
| Leading Market Players |
|---|
| Good Catch |
| Ocean Hugger Foods |
| New Wave Foods |
| Gardein |
| Beyond Meat |
| Impossible Foods |
| Sophie's Kitchen |
| The Plant Based Seafood Co. |
| Turtle Island Foods |
| Others |
Cost & Logistics Intelligence
Pea protein concentrate supply contracts anchored to Canadian and U.S. pulse crop indices concentrate formulation cost volatility in the hands of mid-tier manufacturers lacking long-term procurement agreements, pushing margin pools toward foodservice operators with direct-to-manufacturer volume commitments and refrigerated case placement leverage.
Pricing Analysis
Cost-plus contracts indexed to legume commodity futures dominate ingredient procurement, with price differentiation hinging on organic certification tier and shear-cell processing capability. Three-tier pricing structure across premium, standard, and economy levels separates algal oil-enhanced formulations from baseline pea protein isolates. Pricing pressure stems from input cost swings in concentrated pea protein, squeezing mid-tier producers most acutely. Quick-service chains exhibit highest price sensitivity, while white-tablecloth accounts tolerate premium positioning.
Supply Chain Analysis
Upstream feedstock sourcing draws from Canadian prairie pulse growers, U.S. northern plains legume processors, and San Diego biotech corridor precision fermentation facilities. Raw material dependencies center on pea protein isolates, algal oil concentrates, and seaweed-derived binding agents. Single-source vulnerability in Pacific Northwest shear-cell processing equipment manufacturing exposes regional contract manufacturers to climate-related logistics disruptions. Distribution runs through specialized alternative protein distributors with technical sales capabilities, displacing traditional broadline markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from direct-to-foodservice platform subscriptions and formulation customization services expands faster than unit sales of frozen and refrigerated products, positioning service-attach models as the dominant value capture mechanism across the analysis window.
For Market Incumbents: Entrench position through backward integration into pea protein isolate production and captive algal oil fermentation capacity, insulating margin structures from commodity index volatility while locking in California and Pacific Northwest foodservice accounts through multi-year sustainability procurement agreements that embed switching costs. For New Entrants and Emerging Players: Build out white-space presence in Midwest university cafeteria systems and Dallas-Fort Worth institutional dining contracts, where competitive intensity lags coastal metros and direct-to-foodservice distribution platforms bypass entrenched broadline relationships. Lead with allergen-free formulations to differentiate against legacy soy-dependent portfolios. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across shear-cell processing equipment manufacturing as modular platform designs reduce per-line capex requirements, compressing returns for hardware-heavy entrants while favoring asset-light formulation specialists with proprietary IP. Target acquisition profiles center on mid-cap brands with FDA GRAS notification clearances and established foodservice management company relationships. The signal to watch is FDA enforcement posture on "seafood" descriptor usage, which would trigger packaging redesign cycles and retail slotting fee renegotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Isolate Production | Captive supply of neutral-flavor isolates insulates margin from Canadian pulse crop index volatility. |
| Precision Fermentation Facility Scale-Up | Algal oil production in San Diego biotech corridor shortens omega-3 lipid supply chains for West Coast formulators. |
| Direct-to-Foodservice Platform Launch | Bypassing broadline distributor markups captures margin and tightens feedback loops with university procurement managers. |
| Allergen-Free Formulation Certification | Clean-label positioning unlocks premium placement in California Proposition 65-compliant retail channels. |
| Shear-Cell Processing Equipment Partnership | Portland metro equipment manufacturers lower capital barriers for flaky texture replication without high-pressure systems. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with plant-based seafood R&D directors, foodservice procurement managers at contract management companies, FDA regulatory affairs consultants, and university sustainability officers; and secondary validation through FDA GRAS notification filings, USDA FSIS labeling guidance documents, SEC 10-K disclosures from publicly traded alternative protein companies, and Nielsen retail audit data for frozen and refrigerated seafood alternatives. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Forecast inputs considered product type segmentation across fish fillets, shrimp, crab cakes, and fish sticks; end-user splits among households, restaurants, foodservice, and retail chains; ingredient source dynamics for pea protein, seaweed, soy, and emerging legume blends; and distribution channel evolution in online, grocery, supermarket, and specialty retail. CAGRs were derived from regression analysis against historical adoption curves in adjacent alternative protein categories, with specific weighting applied to shear-cell processing technology diffusion rates and institutional procurement mandate implementation timelines.
Sensitivities concentrate around FDA descriptor enforcement actions, pea protein concentrate price volatility, and climate-related logistics disruptions in Pacific Northwest manufacturing clusters. Cross-checking against USDA FSIS alternative protein retail placement data and university sustainability procurement scorecard weightings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Halibut Market
Seafood
Organic Shrimp Market
Seafood
Shellfish Market
Seafood
Dry-Packaged Scallops Market
Seafood
Fish Meal Market
Seafood
Dried Scallop Market
Seafood
North America Seafood Market
Seafood
Middle East Seafood Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Groundfish Market
Seafood
Sea Bream Market
Seafood
Tuna Market
Seafood
Mussel Oil Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Fin Fish Market
Seafood
Canned Fishery Product Market