
 Walk-In Coolers and Freezers Market | 2026-2036
Walk-In Coolers and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Walk-In Coolers and Freezers Market Analysis
Refrigeration technician shortages across North America and Europe are redrawing installation capacity and aftermarket service economics for walk-in cooler and freezer deployments. Hussmann Corporation leverages its direct branch network to control project timelines in commercial food retail. Arctic Industries anchors its position through captive manufacturing of insulated panels and refrigeration systems. Carrier Commercial Refrigeration competes on energy-certified system integration for large-format supermarket chains.
Walk-in coolers and freezers are engineered cold-storage enclosures built with insulated metal or composite panels, typically maintaining temperatures from 35°F down to -10°F for commercial food preservation. Polyurethane-injected panel cores with cam-lock joining systems deliver thermal resistance values critical for regulatory energy compliance. Modular walk-ins lead volume due to faster site assembly and lower labor dependency, while energy-efficient units command premium positioning as utility rebate programs expand. Digital monitoring segments are gaining fastest as cloud-connected temperature logging becomes standard for HACCP documentation and insurance compliance.
The EPA's AIM Act refrigerant phasedown, the DOE's energy conservation standards for commercial refrigeration equipment, and California's Title 24 building efficiency code collectively reshape equipment specifications and replacement timelines across the United States. These frameworks push end users toward lower-global-warming-potential systems and tighter envelope performance, filtering which suppliers can participate in federally funded or utility-rebated projects. Stakeholders must weigh stranded asset risk in existing HFC-dependent installed bases against the capital timing of next-generation refrigerant transitions.
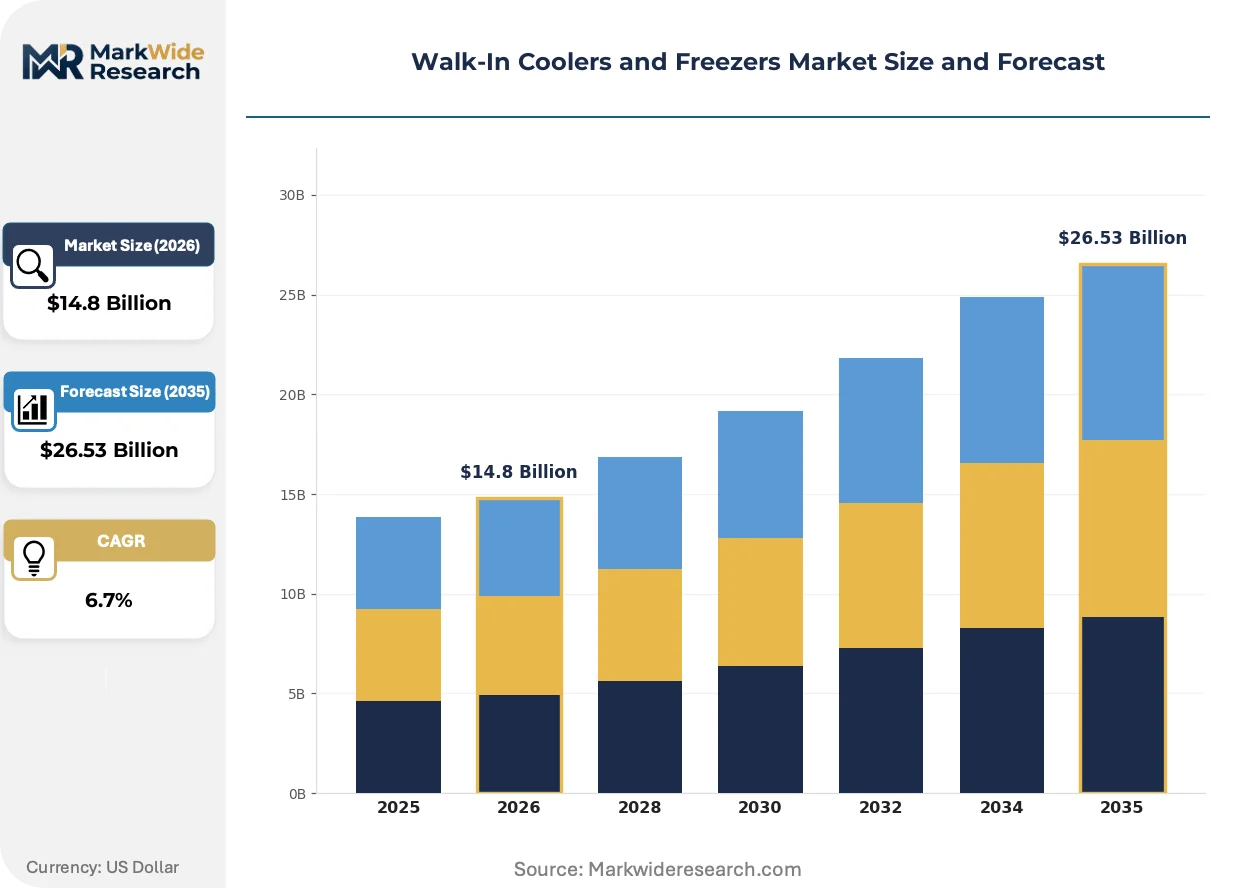
Market Dynamics
The EPA's AIM Act refrigerant phasedown is compressing equipment replacement cycles as operators face stranded asset risk in HFC-dependent installed bases. This regulatory pressure intersects with e-commerce grocery fulfillment expansion to reshape capital deployment timelines across cold storage infrastructure.
Growth Catalysts
- AIM Act Compliance Deadlines:The EPA's hydrofluorocarbon phasedown mandates accelerate retrofit and replacement demand as operators preempt regulatory penalties.
- Cloud-Connected Temperature Logging:Digital HACCP documentation requirements drive aftermarket monitoring hardware attachment rates in foodservice and pharmaceutical verticals.
- Prefabricated Modular Assembly:Faster site installation and reduced labor dependency expand addressable project capacity for regional contractors.
Market Restraints
- Polyurethane Raw Material Volatility:Isocyanate and blowing agent price swings compress panel manufacturer margins and destabilize project quoting.
- Refrigeration Technician Scarcity:North American and European installation and service labor shortages extend project timelines and inflate field labor costs.
- Next-Generation Refrigerant Uncertainty:A2L safety classification requirements and equipment compatibility questions delay capital commitments.
Strategic Opportunities
- Utility Rebate Program Expansion:DOE-certified energy-efficient equipment qualifies for accelerating incentive pools in deregulated electricity markets.
- Pharmaceutical Cold Chain Extension:Cell and gene therapy logistics create demand for ultra-low temperature walk-in configurations.
- Retrofit Digitalization Services:Legacy installed base monitoring upgrades offer recurring revenue streams independent of new construction cycles.
Industry Challenges
- Multi-Refrigerant Inventory Complexity:Service organizations must maintain parallel parts and certification streams during the HFC transition window.
- Panel-to-System Integration Testing:Envelope and refrigeration package interoperability validation extends factory lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walk-In Coolers and Freezers Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reach-In Coolers, Walk-In Freezers, Refrigerated Display Cases, Modular Walk-Ins End User: Restaurants, Supermarkets, Convenience Stores, Food Distributors Installation: On-Site, Prefabricated, Custom-Built, Retrofit Technology: Refrigeration Systems, Eco-Friendly Refrigerants, Digital Monitoring, Energy-Efficient Units |
| Companies Covered | Arctic Industries, Heatcraft Worldwide Refrigeration, Hussmann Corporation, Polar King, Norlake, Carrier Commercial Refrigeration, Koller, Frigoscandia, Kolpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walk-In Coolers and Freezers Market Emerging Trajectories
Equipment specifications are pivoting toward lower-global-warming-potential architectures as regulatory frameworks harden and energy economics intensify. Three converging developments are restructuring supplier capabilities and buyer procurement criteria.
CO2 transcritical booster systems are supplanting traditional HFC rack configurations in large-format supermarket applications. Retail chains with net-zero commitments are specifying these systems despite higher first costs. The technology is compressing incumbent equipment suppliers' service attach rates as specialized CO2 competence becomes a procurement gate.
The DOE's energy conservation standards for commercial refrigeration equipment tighten minimum efficiency thresholds on a preset schedule. Manufacturers must redesign condensing units and evaporator coils to maintain compliance eligibility. California's Title 24 building efficiency code extends these requirements to envelope performance, filtering supplier participation in rebate-eligible projects.
Food distributors are consolidating procurement authority at regional hub levels rather than individual facility managers. This concentration shifts negotiation leverage toward lifecycle cost models and standardized specifications. The pattern is most visible in United States warehouse construction, where national cold storage operators specify uniform panel and refrigeration packages across multi-site rollouts.
Walk-In Coolers and Freezers Market Segmentation
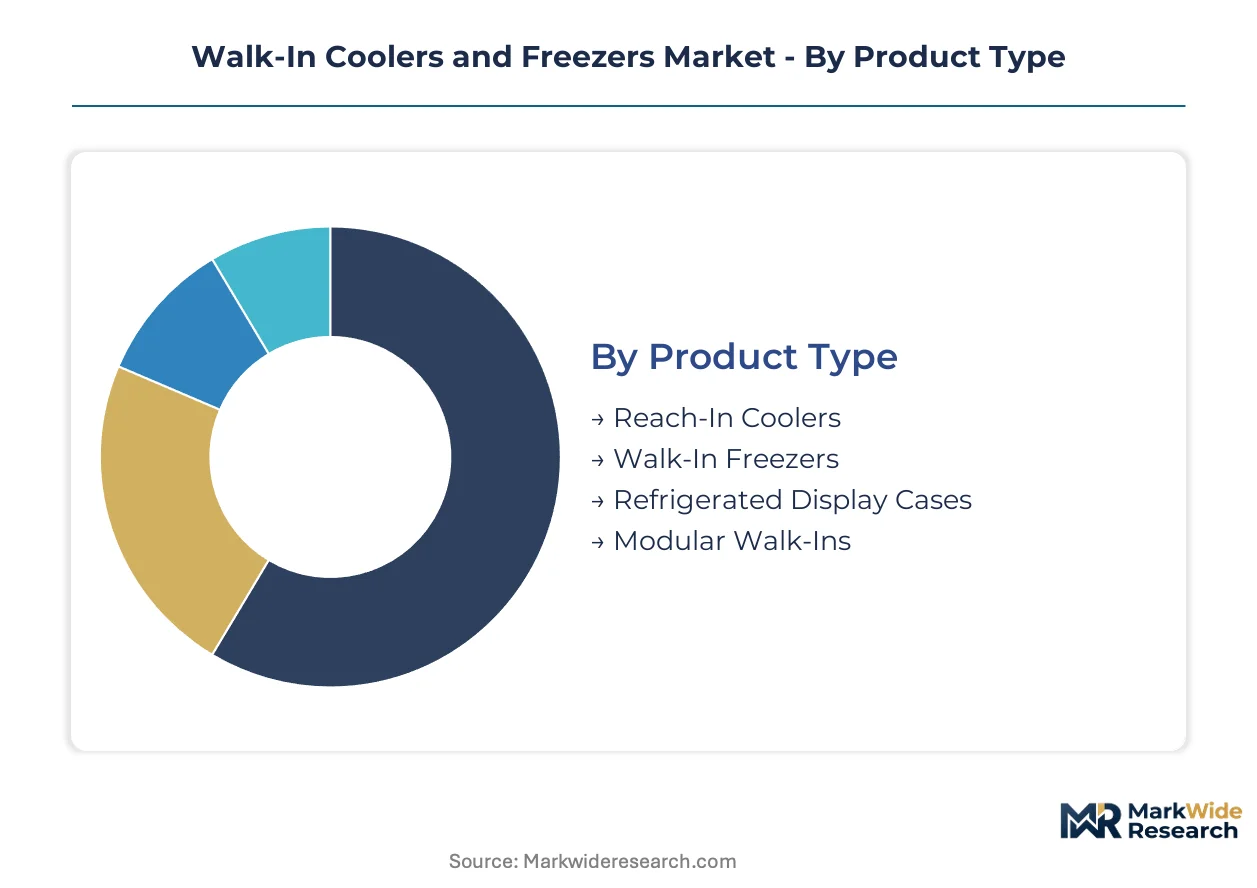
Segmentation in the Walk-In Coolers and Freezers Market reveals where substitution pressure and regulatory displacement are reshaping procurement patterns. Buyers now cross-shop between modular prefabricated units and custom-built installations based on labor availability and energy rebate eligibility rather than traditional durability metrics.
Product Type:
Substitution pressure runs strongest against reach-in coolers as operators consolidate cold storage footprints into centralized walk-in configurations. The EPA's AIM Act refrigerant phasedown accelerates this shift by forcing premature replacement of smaller HFC-dependent units.
- Modular Walk-Ins:Polyurethane-injected panel assemblies with cam-lock joining systems enable field assembly without specialized welding. Food distributors expanding e-commerce fulfillment centers in Texas and Florida specify these for accelerated site deployment. DOE-certified configurations qualify for utility rebate programs in deregulated electricity markets.
- Walk-In Freezers:Engineered enclosures maintaining temperatures from -10°F to 0°F with thicker panel insulation and higher-capacity refrigeration packages. Supermarket chains with net-zero commitments specify CO2 transcritical booster configurations despite elevated first costs. The segment captures premium positioning as HACCP documentation requirements harden.
- Reach-In Coolers:Self-contained units facing displacement from centralized walk-in systems in commercial kitchen redesigns.
- Refrigerated Display Cases:Merchandising-oriented units with glass fronts for customer-facing retail environments.
Modular Walk-Ins anchors the volume base while Walk-In Freezers gains share at the steepest rate.
End User:
Cost tier differentiation separates capital-intensive national deployments from price-sensitive independent operators. Food distributors command the largest average transaction values while restaurants exhibit the highest price elasticity.
- Food Distributors:Regional hub operators consolidating procurement authority at headquarters level rather than individual facility managers. These buyers specify uniform panel and refrigeration packages across multi-site rollouts in warehouse construction clusters. Lifecycle cost models dominate negotiation leverage over upfront capital expenditure.
- Supermarkets:Large-format retail chains driving specification of CO2 transcritical systems and energy-certified integration. California's Title 24 building efficiency code filters supplier participation in rebate-eligible projects for this segment. Net-zero commitments compress incumbent equipment suppliers' service attach rates.
- Restaurants:Fragmented independent operators prioritizing faster installation timelines over customization depth.
- Convenience Stores:Petroleum retail operators with standardized footprint requirements and limited mechanical room space.
Food Distributors anchors the volume base while Supermarkets climbs the fastest as energy economics intensify.
Installation:
Volume concentration favors prefabricated approaches as refrigeration technician scarcity across North America extends project timelines for on-site construction. Customer type determines acceptable trade-offs between speed and customization.
- Prefabricated:Factory-assembled panel systems delivered for rapid field connection. Reduced labor dependency expands addressable project capacity for regional contractors facing technician shortages. Faster site assembly compresses revenue recognition cycles for installation firms.
- Retrofit:Existing enclosure upgrades with digital monitoring hardware and refrigeration package replacements. Legacy installed base monitoring upgrades offer recurring revenue streams independent of new construction cycles. Cloud-connected temperature logging becomes standard for insurance compliance.
- On-Site:Traditional stick-built construction requiring extended field labor presence and specialized trades coordination.
- Custom-Built:Architect-specified configurations for unique spatial constraints or aesthetic integration requirements.
Prefabricated anchors the volume base while Retrofit expands most quickly as stranded asset risk accelerates replacement demand.
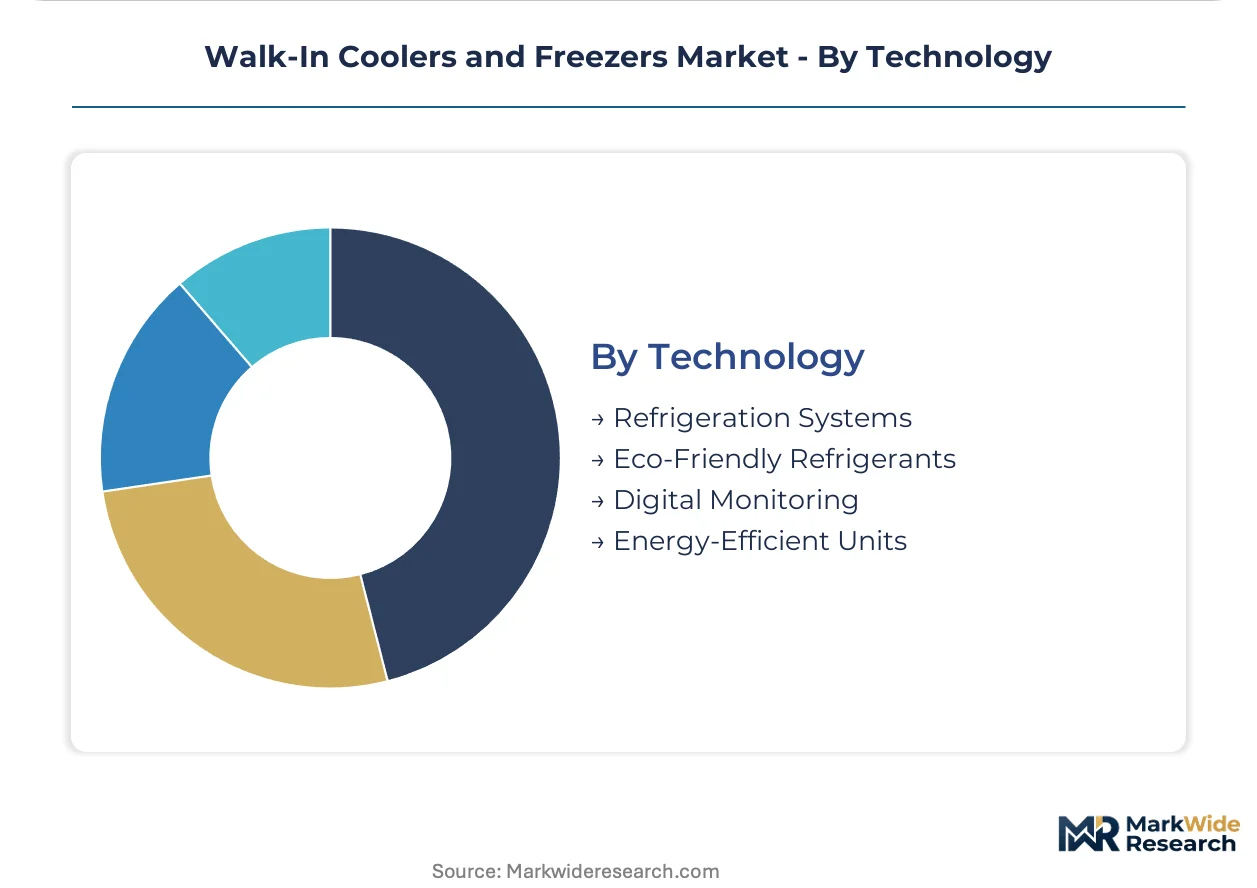
Technology:
Margin structure separates hardware commoditization from software-enabled recurring revenue. Digital monitoring commands the highest gross margins while refrigeration systems face price pressure from equipment manufacturer consolidation.
- Digital Monitoring:Cloud-connected temperature logging systems with HACCP documentation automation. Pharmaceutical cold chain extension for cell and gene therapy logistics creates demand for ultra-low temperature configuration validation. Insurance compliance requirements drive aftermarket hardware attachment rates.
- Eco-Friendly Refrigerants:Lower-global-warming-potential alternatives to phasedown HFCs including CO2 and A2L-classified hydrofluoroolefins. Next-generation refrigerant uncertainty around safety classification requirements delays some capital commitments. Multi-refrigerant inventory complexity strains service organization parts streams.
- Refrigeration Systems:Condensing units and evaporator coils facing DOE energy conservation standard redesign requirements.
- Energy-Efficient Units:DOE-certified equipment qualifying for accelerating incentive pools in utility rebate programs.
Refrigeration Systems anchors the volume base while Digital Monitoring captures the steepest expansion trajectory as documentation requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's AIM Act refrigerant phasedown anchors demand concentration in the United States, while parallel regulatory frameworks in Europe and Asia-Pacific reshape equipment specifications across their respective cold storage infrastructure markets.
United States
Food distributors expanding e-commerce grocery fulfillment centers in Texas and Florida drive prefabricated walk-in installations. The EPA's AIM Act hydrofluorocarbon phasedown compresses replacement cycles for HFC-dependent equipment. Warehouse construction clusters in the Dallas-Fort Worth metro and Central Florida corridor concentrate multi-site rollout activity.
Germany
Supermarket chains with net-zero commitments specify CO2 transcritical booster systems for large-format retail refrigeration. The EU F-Gas Regulation mandates lower-global-warming-potential refrigerant transitions across commercial equipment categories. Industrial refrigeration demand concentrates in Bavaria's food processing corridor and North Rhine-Westphalia's logistics hubs.
China
Cold chain infrastructure expansion for pharmaceutical distribution and fresh food e-commerce propels walk-in cooler deployments. The country's national environmental regulator enforces dual carbon goals that filter equipment supplier participation in state-funded projects. Manufacturing activity clusters in the Yangtze River Delta and Pearl River Delta regions.
Japan
Convenience store operators with standardized footprint requirements drive compact walk-in freezer specifications for limited mechanical room spaces. METI energy efficiency standards tighten minimum performance thresholds for commercial refrigeration equipment. Demand concentrates in the Kanto region surrounding Tokyo and the Kansai industrial zone around Osaka.
India
Foodservice expansion and organized retail growth generate walk-in cooler demand for commercial kitchen and supermarket applications. FSSAI cold chain regulations harden HACCP documentation requirements for temperature-controlled storage. Project activity clusters in Maharashtra's Mumbai-Pune corridor and Gujarat's industrial belt.
Walk-In Coolers and Freezers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the walk-in coolers and freezers market. The vendor base separates into integrated refrigeration system suppliers, captive panel manufacturers, and modular assembly specialists. Three strategic archetypes dominate: vertically integrated full-system providers, component-focused fabricators with regional installation networks, and digital monitoring platform vendors. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms address technician scarcity and refrigerant transition complexity.
Within the integrated-system tier, Carrier Commercial Refrigeration and Hussmann Corporation occupy positions exemplifying scale-driven equipment integration. Arctic Industries anchors the captive manufacturing archetype through in-house production of insulated panels. Heatcraft Worldwide Refrigeration sits within the global distribution network category, representing the refrigeration package specialist model.
| Leading Market Players |
|---|
| Arctic Industries |
| Heatcraft Worldwide Refrigeration |
| Hussmann Corporation |
| Polar King |
| Norlake |
| Carrier Commercial Refrigeration |
| Koller |
| Frigoscandia |
| Kolpak |
| Others |
Supply Flow & Price Mechanics
Panel manufacturing scale economies in the United States and Germany compress unit costs for polyurethane-injected assemblies while elevating price floors for smaller regional fabricators lacking captive blowing-agent sourcing. This concentration of insulated panel production capacity shapes competitive dynamics across prefabricated walk-in deployments, with national account buyers leveraging volume commitments against fragmented contractor networks.
Pricing Analysis
United States project quotes run 15-25 percent above comparable European installations due to tariffed steel inputs and extended refrigeration technician lead times. Three-tier pricing structure across premium DOE-certified systems, standard modular configurations, and economy-grade reach-in alternatives separates food distributor procurement from independent restaurant budgets. Cost compression in the standard tier is intensifying as Chinese panel imports pressure domestic manufacturers. Independent restaurants exhibit the highest price elasticity, deferring replacement cycles until regulatory deadlines force action, while supermarket chains with net-zero commitments absorb premium positioning for CO2 transcritical systems.
Supply Chain Analysis
Inventory cycles for isocyanate and hydrofluoroolefin blowing agents have lengthened from six to fourteen weeks as EPA phasedown deadlines concentrate demand spikes. Manufacturing gravity centers on the United States, Germany, and China, with polyurethane panel production anchored in Ohio and Bavaria while refrigeration system assembly concentrates in Jiangsu province. Supply chains draw from petrochemical feedstocks, aluminum coil stock, and specialized compressor components. Single-source vulnerability runs through Taiwanese semiconductor-dependent digital monitoring controllers. Distribution runs through manufacturer-direct branch networks for national accounts and regional HVAC wholesalers for fragmented foodservice buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
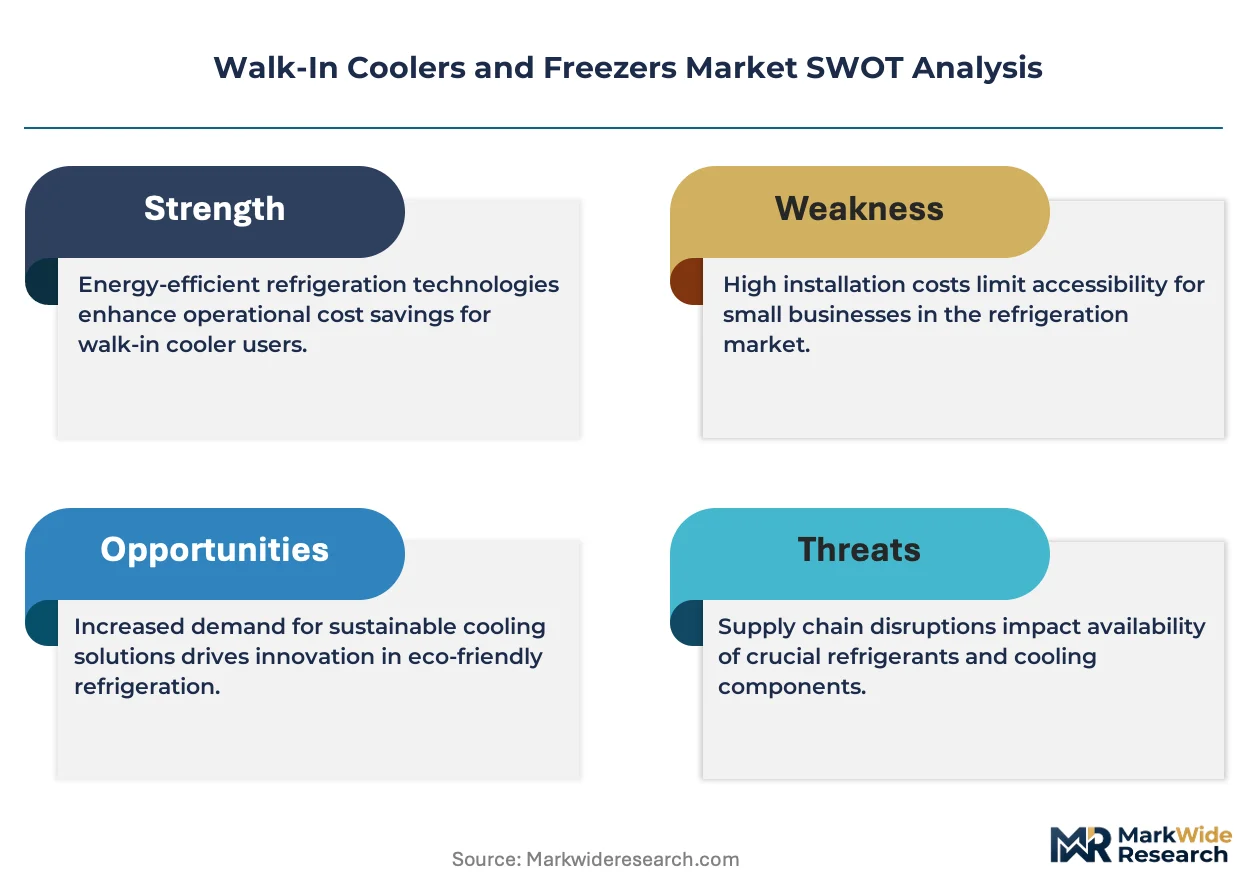
The walk-in coolers and freezers market is approaching a platform-economics inflection as cloud-connected temperature logging transforms hardware vendors into recurring-revenue service providers. Interoperability between envelope systems, refrigeration packages, and documentation software is becoming the procurement gate for large-format buyers.
For Market Incumbents: Shield installed base service contracts through preemptive digital monitoring retrofits before independent IoT vendors capture HACCP documentation relationships. Deepen backward integration into polyurethane panel core production to buffer isocyanate price volatility. Compress replacement cycle capture by bundling AIM Act compliance consulting with equipment quotes.
For New Entrants and Emerging Players: Differentiate on pharmaceutical cold chain validation capabilities as cell and gene therapy logistics create ultra-low temperature white space underserved by incumbent food retail specialists. Target independent restaurant clusters in Texas and Florida with prefabricated rental programs that convert capital expenditure to operating lease structures. Lead with installation speed guarantees backed by non-union contractor network partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital monitoring platform vendors with pharmaceutical vertical penetration, suggesting premium valuation durability against hardware commoditization cycles. Over the intermediate horizon, acquisition candidates with captive panel manufacturing and EPA-certified refrigeration system integration capabilities offer defensive positioning. The signal to watch is utility rebate program expansion velocity in deregulated electricity markets as a demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Core Production | Captive polyurethane injection capacity insulates margins from isocyanate price volatility in the United States. |
| Digital Monitoring Platform Acquisition | Cloud-connected temperature logging assets convert transactional equipment sales to recurring SaaS revenue streams. |
| Pharmaceutical Cold Chain Certification | Ultra-low temperature validation capabilities unlock cell and gene therapy logistics verticals beyond food retail saturation. |
| Utility Rebate Program Partnership | DOE-certified equipment pre-qualification accelerates incentive capture for national account rollouts in deregulated markets. |
| Regional Contractor Network Consolidation | Installation capacity control addresses technician scarcity bottlenecks compressing project timelines in North America. |
Methodological Framework
The analysis maps modular walk-in, walk-in freezer, reach-in cooler, and refrigerated display case sub-sectors, each validated through refrigeration contractor interviews, food distributor procurement directors, supermarket facilities managers, and restaurant operator field assessments. Primary intelligence combined with secondary validation from EPA AIM Act regulatory filings, DOE energy conservation standard dockets, and utility rebate program databases. Customs records for polyurethane panel imports and SEC 10-K equipment manufacturer disclosures provided supply-side triangulation. Bottom-up project pipeline tracking and top-down cold storage construction permit analysis were reconciled for consistency.
Outputs were validated against external benchmarks including regional construction cost indices and refrigeration technician wage surveys. Segmentation dimensions modeled across the projection horizon span product type, end-user vertical, installation methodology, and technology tier, with additional granularity on refrigerant transition timing. CAGRs were derived from replacement cycle compression analysis and e-commerce fulfillment center deployment trajectories. Forecast inputs incorporated AIM Act phasedown schedule adherence rates and utility incentive pool expansion assumptions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated refrigerant transition timelines would require recalibration. Forecasts reflect documented assumptions regarding technician labor availability and raw material price stability. Specific risks that could revise projections include A2L safety classification implementation delays and trade policy shifts affecting steel and aluminum input costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Canada Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market