
 United States Frozen and Canned Seafood Market | 2026-2036
United States Frozen and Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frozen and Canned Seafood Market Analytics
Subscription-based replenishment programs for frozen seafood is hardening into a core revenue layer as direct-to-consumer platforms lock in recurring household orders. Trident Seafoods Corporation leverages its Alaska-based harvesting fleet to sustain vertical control from catch to case. StarKist Co. anchors its position through shelf-stable pouches that dominate pantry-stock channels nationwide.
United States frozen and canned seafood comprises finfish and shellfish preserved through blast freezing at minus 18 degrees Celsius or thermal processing in hermetically sealed containers, with shelf lives extending from 18 months to 3 years depending on method and species. The primary commercial purpose centers on delivering protein-stable inventory to buyers with limited fresh supply access or seasonal demand spikes. Fish fillets and shrimp together command the largest product type volume, though clams gain ground in chowder-ready foodservice formats. Supermarkets and wholesale channels capture the dominant margin pools, while online retailers represent the fastest-growing distribution vector as cold-chain last-mile logistics mature.
FDA HACCP regulations and USDA FSIS labeling mandates govern safety protocols and species identification standards across domestic production and import streams. EPA discharge permits for coastal processing facilities constrain plant siting and wastewater treatment capital allocation. NOAA fisheries management quotas further limit raw material availability for certain Atlantic and Pacific species. Stakeholders must weigh traceability technology investments against pending traceability rule enforcement timelines.
Market Dynamics
FDA's pending traceability rule is compressing adoption timelines for cold-chain IoT systems, forcing processors to front-load compliance investments before enforcement windows close. This regulatory pressure intersects with Gulf Coast concentration of shrimp and tuna processing capacity.
Growth Catalysts
- Subscription replenishment models:Direct-to-consumer platforms lock recurring household orders through automated delivery schedules, reducing customer acquisition costs and smoothing demand volatility for frozen fillet SKUs.
- NOAA fisheries management frameworks:Quota systems for Atlantic and Pacific species stabilize raw material availability, enabling processors to commit to multi-year retail contracts with predictable supply baselines.
- Blast freezing at minus 18 degrees Celsius:This preservation standard extends shelf life to 18 months, opening inventory financing options for distributors serving landlocked markets with limited fresh seafood access.
Market Restraints
- Alaska pollock and Pacific cod quota volatility:NOAA catch limits create raw material scarcity cycles that compress processor margins during low-yield seasons and force substitution into lower-value species.
- Louisiana-through-Florida processing corridor concentration:Hurricane exposure and coastal flooding risk concentrate supply disruption potential in a narrow geographic band with limited alternative capacity.
- Thermal processing energy intensity:Canned tuna retort operations face natural gas price spikes that erode cost competitiveness against frozen alternatives with lower energy input requirements.
Strategic Opportunities
- Midwestern and Mountain West underpenetration:Cold-chain last-mile maturation enables frozen seafood subscription services to capture protein-switching households in Denver, Minneapolis, and Salt Lake City metro areas.
- USDA FSIS labeling harmonization:Unified species identification standards reduce compliance fragmentation across state lines, lowering barrier costs for regional processors expanding into national retail.
- Blockchain-IoT convergence:Integrated traceability stacks from harvest to retail shelf capture premium positioning for Gulf shrimp and Alaska salmon in transparency-sensitive foodservice accounts.
Industry Challenges
- HACCP modernization compliance timelines:FDA's updated seafood safety protocols demand facility revalidation and documentation system overhauls that strain quality assurance staffing at mid-scale processors.
- EPA discharge permit renewal cycles:Coastal processing plants face capital-intensive wastewater treatment upgrades during permit renewals, diverting funds from automation investments.
- Cold-chain technician scarcity:Specialized refrigeration and blast freezer maintenance skills concentrate in Gulf Coast and Pacific Northwest labor pools, constraining facility expansion in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frozen and Canned Seafood Market |
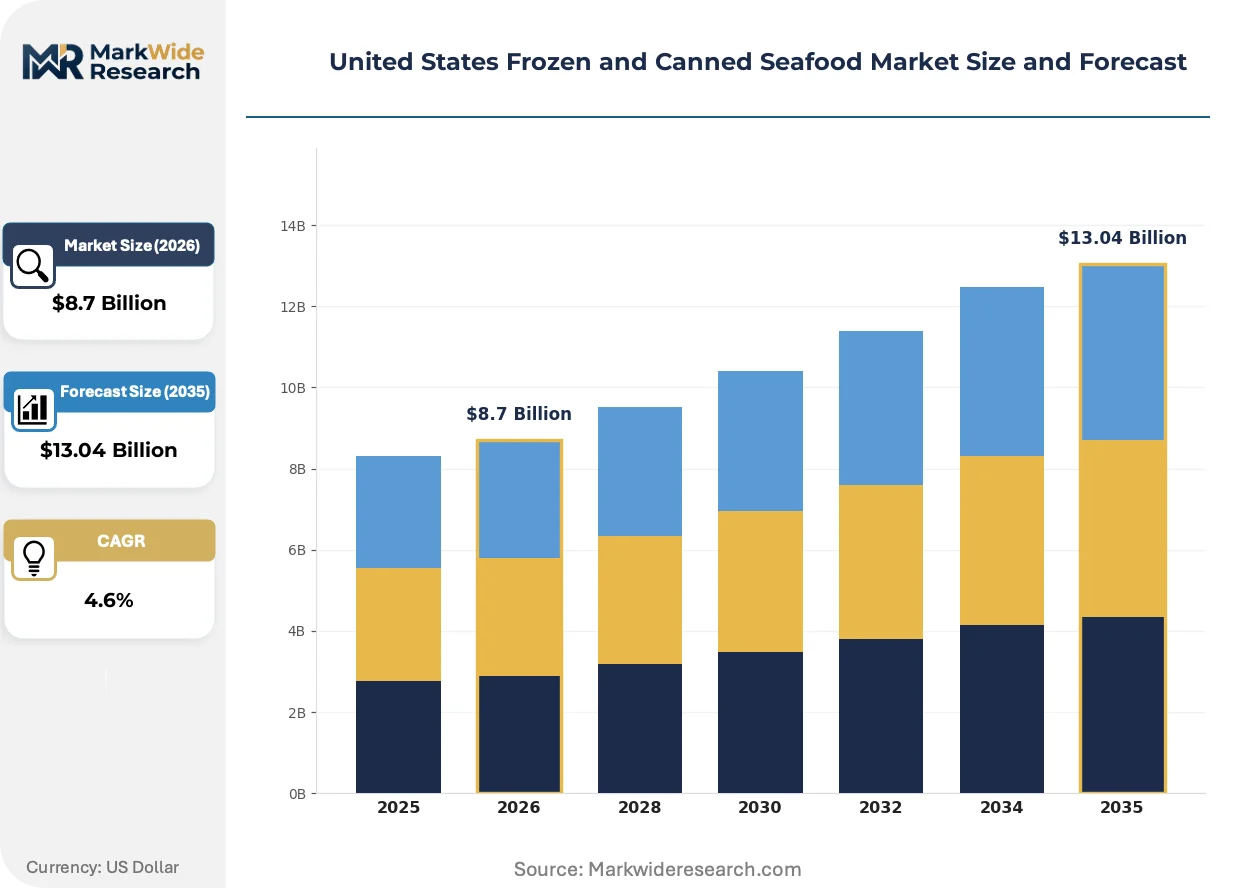
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Fillets, Shrimp, Clams, Tuna Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale End User: Households, Restaurants, Foodservice Providers, Retail Chains Packaging Type: Vacuum Sealed, Cans, Pouches, Glass Jars |
| Companies Covered | Trident Seafoods Corporation, Thai Union Group PCL, High Liner Foods Inc., Mowi ASA, Sysco Corporation, Pacific Seafood Group, StarKist Co., Maruha Nichiro Corporation, American Tuna Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frozen and Canned Seafood Market Evolving Landscape
Cold-chain digitization and preservation technology advances are compressing the freshness-perception gap between frozen and chilled seafood. These shifts reshape procurement criteria and channel economics simultaneously.
Blockchain-enabled traceability platforms is rewriting how foodservice buyers verify catch origin and temperature integrity. Large casual-dining chains now mandate lot-level tracking for tuna and shrimp suppliers. This transparency infrastructure compresses supplier qualification cycles and locks out processors lacking digitized chain-of-custody documentation.
FDA's Food Safety Modernization Act traceability mandates impose serialized tracking from harvest to retail. Processors must deploy electronic record systems interoperable with downstream distributors. Smaller Gulf Coast canneries face disproportionate compliance burdens relative to integrated operators with captive IT resources.
Pantry-stock channel rotation favors shelf-stable pouches over traditional cans in household replenishment patterns. StarKist's pouch format captures younger demographics in Midwest and Southeast supermarkets. This packaging pivot reshapes retail shelf space allocation and margin structures for legacy canneries.
United States Frozen and Canned Seafood Market Segmentation
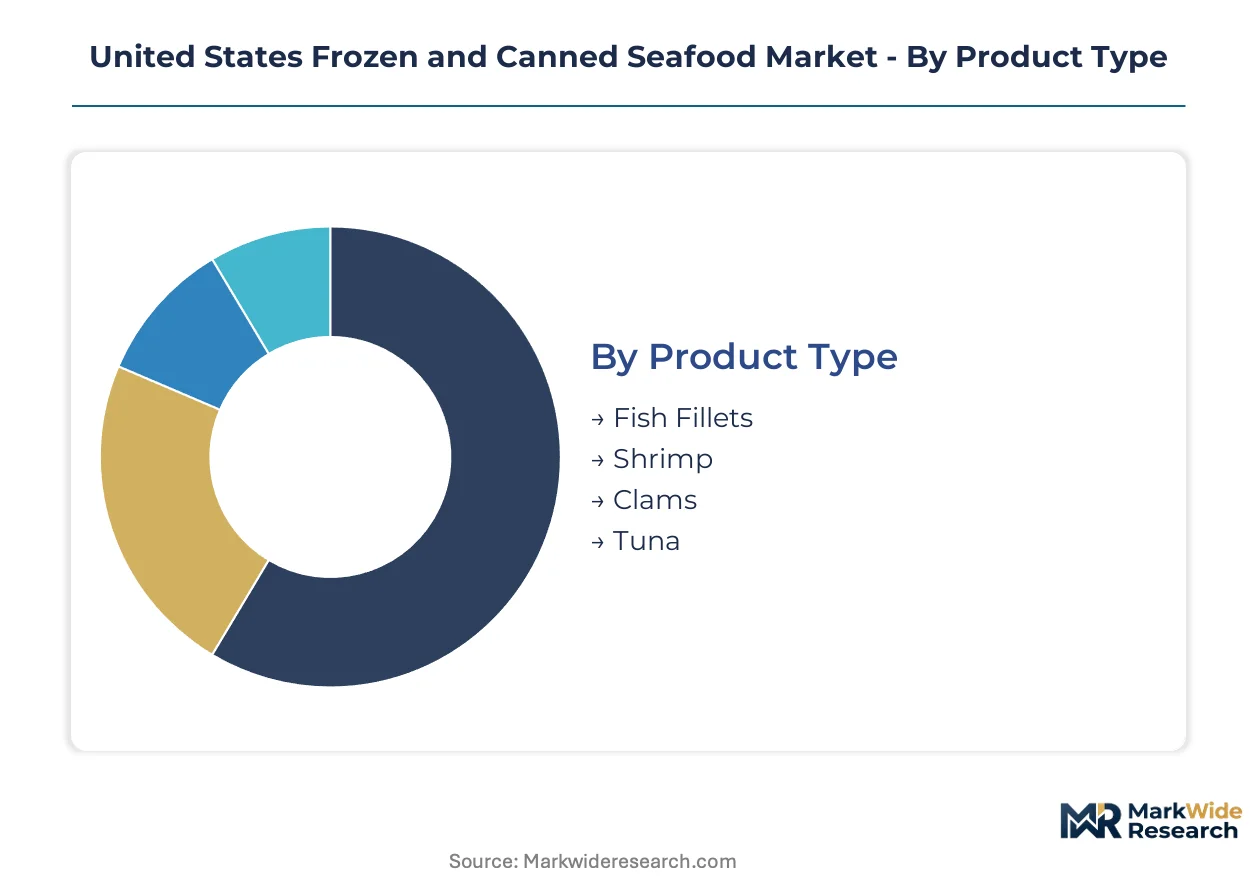
Frozen and canned seafood procurement varies sharply by buyer sophistication and supply chain access. Segmentation reveals how Gulf Coast processors, Denver-based subscription services, and institutional foodservice buyers source fundamentally different product configurations. Understanding these divides exposes margin concentration points and technology adoption gaps.
Product Type:
Standardization dominates commodity grades while premium tiers demand species-specific handling protocols and traceability documentation.
- Fish Fillets:Alaska pollock and Pacific cod portions processed through blast freezing at minus 18 degrees Celsius. Demand concentrates in Midwestern supermarkets where fresh supply remains intermittent and household buyers prioritize portion-controlled convenience.
- Shrimp:Gulf Coast brown and white shrimp dominate frozen raw and cooked formats. Louisiana-through-Florida processing corridor captures foodservice bulk procurement with HACCP-compliant IQF (individually quick frozen) specifications.
- Clams:Chopped and whole baby clams in chowder-ready formats serve New England and Mid-Atlantic foodservice accounts.
- Tuna:Skipjack and yellowfin species processed through thermal retort canning or raw frozen sashimi-grade loins for specialized buyers.
Leading the category by volume: Fish Fillets. Expanding most quickly: Shrimp.
Distribution Channel:
Channel selection tracks cold-chain maturity and buyer replenishment cadence across household and institutional segments.
- Supermarkets:Traditional retail capture for branded frozen seafood and canned shelf-stable inventory. Kroger and Albertsons chains dominate shelf space allocation in Gulf Coast and Southeast corridors.
- Online Retailers:Direct-to-consumer subscription platforms with automated replenishment algorithms. Cold-chain last-mile logistics enable penetration into Denver, Minneapolis, and Salt Lake City metro areas previously underserved.
- Specialty Stores:Premium and ethnic-format retailers catering to species-specific demand for sashimi-grade tuna and regional clam varieties.
- Wholesale:Institutional volume procurement for restaurant groups and foodservice distributors with centralized distribution centers.
Supermarkets retain the dominant revenue share. Online Retailers gain share fastest.
End User:
Procurement sophistication separates household replenishment from institutional specification requirements.
- Households:Subscription-based frozen seafood services lock recurring orders through automated delivery schedules. Portion-controlled fillet SKUs reduce waste perception among protein-switching consumers in landlocked markets.
- Restaurants:Casual-dining and fast-casual chains mandate lot-level traceability for shrimp and tuna suppliers. Blockchain-enabled verification compresses supplier qualification cycles.
- Foodservice Providers:Contract feeding and institutional accounts prioritize shelf-stable pouches for inventory stability and reduced refrigeration capital.
- Retail Chains:Private-label frozen seafood programs demand consistent supply baselines enabled by NOAA quota stabilization frameworks.
Foodservice Providers drive the largest absolute volume. Households show the steepest expansion trajectory.
Packaging Type:
Preservation method determines shelf life, energy input, and retail channel compatibility.
- Vacuum Sealed:Modified atmosphere packaging for frozen fillets extending shelf life to 18 months. Blast freezer integration required at processing facility.
- Cans:Traditional thermal retort processing for tuna and shelf-stable seafood. Natural gas price volatility erodes cost competitiveness against frozen alternatives.
- Pouches:Flexible retort packaging gaining shelf space in Midwest and Southeast supermarkets. Younger demographics favor pouch format for pantry-stock rotation convenience.
- Glass Jars:Specialty preserved seafood for ethnic and gourmet retail channels with higher margin but limited volume.
Vacuum Sealed leads frozen category volume. Pouches climb the fastest in shelf-stable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic catch volumes concentrate along Alaska and the Gulf Coast while consumption spreads across interior metropolitan areas with maturing cold-chain infrastructure. This geographic split forces processors to maintain dual supply networks: harvest-proximate plants for raw material intake and regional distribution hubs for last-mile fulfillment.
Alaska
Pollock and Pacific cod quotas under NOAA fisheries management frameworks determine annual raw material availability for fillet production. EPA discharge permits constrain coastal processing facility expansion in Dutch Harbor and Kodiak. Trident Seafoods Corporation operates harvesting fleets and shoreside plants that anchor the state's vertically integrated processing corridor.
Gulf Coast
Louisiana-through-Florida brown and white shrimp landings supply foodservice bulk procurement with HACCP-compliant IQF specifications. FDA seafood safety protocols demand facility revalidation for processors in Houma and Tampa. Hurricane exposure concentrates supply disruption risk in this narrow coastal band with limited alternative capacity.
Pacific Northwest
Salmon and Dungeness crab fisheries under NOAA quota systems stabilize supply baselines for premium frozen formats. Washington State Department of Ecology discharge regulations govern wastewater treatment at Seattle-area processing plants. Cold-chain technician scarcity constrains facility expansion beyond established Portland and Puget Sound labor pools.
Midwest Metro Corridors
Denver, Minneapolis, and Salt Lake City households drive subscription-based frozen seafood demand as protein-switching accelerates in landlocked markets. USDA FSIS labeling harmonization reduces interstate compliance barriers for regional distributors. Automated replenishment algorithms lock recurring orders through direct-to-consumer platforms with expanding cold-chain last-mile coverage.
Southeast Atlantic
North Carolina and South Carolina blue crab and clam processing serves chowder-ready foodservice formats in Mid-Atlantic accounts. State-level shellfish sanitation regulations align with FDA HACCP modernization timelines. Charleston and Morehead City plants specialize in thermal processing for shelf-stable regional seafood products.
United States Frozen and Canned Seafood Market Competitive Landscape
Capital-heavy producers with captive harvesting fleets compete with asset-light distributors sourcing through contract arrangements. The vendor base stratifies into three tiers: vertically integrated operators controlling catch-to-case supply chains, regional processors serving geographic niches, and national distributors leveraging procurement scale across multiple species. Consolidation pressure intensifies as FDA traceability mandates favor integrated operators with captive IT infrastructure. Geographic expansion and backward integration into harvesting represent the dominant competitive moves.
Within the vertically integrated tier, Trident Seafoods Corporation and Mowi ASA exemplify fleet-based upstream control over raw material flows. Thai Union Group PCL and Maruha Nichiro Corporation occupy positions as multinational processors with diversified species portfolios spanning frozen and shelf-stable formats. StarKist Co. anchors the shelf-stable segment through pouch-format innovation targeting pantry-stock channel rotation.
| Leading Market Players |
|---|
| Trident Seafoods Corporation |
| Thai Union Group PCL |
| High Liner Foods Inc. |
| Mowi ASA |
| Sysco Corporation |
| Pacific Seafood Group |
| StarKist Co. |
| Maruha Nichiro Corporation |
| American Tuna Inc. |
| Others |
Value Network & Pricing Analysis
Alaska pollock and Pacific cod quota volatility transmits directly through fillet pricing tiers, with NOAA catch limit announcements compressing processor margins and forcing substitution economics that separate premium sashimi-grade portions from economy blocks sold to institutional buyers.
Pricing Analysis
Margin tightening in frozen shrimp reflects natural gas price spikes hitting thermal retort operations, eroding canned tuna cost competitiveness against blast-frozen alternatives. Three-tier pricing structure across premium traceability-verified, standard HACCP-compliant, and economy commodity grades separates buyers by certification level and volume scale. Cost-down pressure on Gulf Coast processors accelerates because hurricane exposure concentrates supply disruption risk in a narrow coastal band. Foodservice providers show highest price sensitivity due to contract procurement cycles, while subscription households accept premium positioning for convenience.
Supply Chain Analysis
Domestic-content rules under FDA seafood HACCP modernization reshape sourcing toward vertically integrated operators with captive harvesting fleets. Raw material flows draw from Alaska pollock fisheries, Gulf Coast shrimp landings, and Pacific Northwest salmon runs. Supply chain risk centers on single-source vulnerability from Louisiana-through-Florida processing corridor concentration with limited alternative capacity. Distribution runs through supermarket wholesale channels and direct-to-consumer subscription platforms with maturing cold-chain last-mile coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States frozen and canned seafood market functions as a vertical-integration race where backward integration into harvesting fleets determines raw material security and traceability compliance leverage.
For Market Incumbents: Extend fleet-based upstream control over Alaska pollock and Pacific cod quotas to lock multi-year retail contract supply baselines. Consolidate Gulf Coast processing capacity to concentrate hurricane risk mitigation investment and capture EPA discharge permit renewal economies of scale. For New Entrants and Emerging Players: Launch via subscription-based replenishment algorithms targeting Denver, Minneapolis, and Salt Lake City metro areas where cold-chain last-mile maturation enables protein-switching household penetration. Exploit mid-scale processor HACCP compliance staffing gaps through outsourced quality assurance platforms. For Investors and Strategic Acquirers: FDA traceability rule enforcement timeline compression is the leading indicator that integrated operators with captive IT infrastructure will absorb regional canneries facing disproportionate compliance burdens. Long-term viability favors fleet-based harvesters with shoreside processing plants and blockchain-IoT traceability stacks already deployed.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet-Based Harvesting Expansion | NOAA quota stabilization enables multi-year retail contract commitments with predictable raw material baselines. |
| Cold-Chain IoT Traceability Deployment | FDA pending rule compliance locks out processors lacking digitized chain-of-custody documentation. |
| Subscription Platform Integration | Automated replenishment algorithms reduce customer acquisition costs for direct-to-consumer frozen fillet SKUs. |
| Retort Pouch Format Transition | Shelf-stable pouch packaging captures younger demographics in Midwest and Southeast supermarket channels. |
| Regional Distribution Hub Buildout | Denver and Salt Lake City cold-chain infrastructure enables landlocked market penetration for subscription services. |
Research Methodology
Document review covered NOAA fisheries management frameworks, FDA HACCP modernization protocols, and EPA discharge permit regulations, complemented by interviews with Gulf Coast processing plant managers, Alaska fleet operations directors, foodservice procurement leads, supermarket category buyers, and cold-chain logistics specialists. Secondary validation drew from customs trade data, SEC filings of publicly traded seafood processors, and retail audit databases. Bottom-up volume modeling triangulated against top-down market sizing across species segments.
Market value and volume outputs trace to analytical frameworks spanning product type, distribution channel, end user, and packaging format dimensions across the projection horizon. CAGRs derive from historical quota volatility patterns, cold-chain infrastructure investment trajectories, and subscription service adoption curves. Forecast inputs include NOAA pollock and cod quota announcements, natural gas price volatility for thermal processing energy costs, and FDA traceability rule enforcement timeline assumptions.
Quota volatility, hurricane disruption frequency, and regulatory enforcement acceleration are the dominant revision risks that could shift processor margin structures and subscription service expansion trajectories. Forecasts reflect documented assumptions about cold-chain maturation and traceability technology adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Seafood Processing Market
Seafood
United States Plant-Based Seafood Market
Seafood
Toothfish Market
Seafood
Canned Mackerel Market
Seafood
Striped Bass Market
Seafood
United States Lobster Market
Seafood
Seafood Takeout Market
Seafood
Seafood Extracts Market
Seafood
United States Seafood Market
Seafood
Lobster Market
Seafood
European Frozen Seafood Market
Seafood
Seafood Flavors Market
Seafood
Mussels Market
Seafood
Tuna Market
Seafood
Fish Nutrition Market
Seafood
Fish Protein Concentrate Market