
 GCC Seafood Market | 2026-2036
GCC Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Seafood Market Foresight
Saudi aquaculture hatchery development is consolidating regional supply chains as the Kingdom scales tilapia and shrimp production. Sea Pride LLC leverages integrated processing facilities along the Red Sea coast to control quality from catch to retail. Tabuk Fisheries Company anchors domestic landings through its fleet operations in the northern Red Sea. National Fishing Company K.S.C. competes via specialized deep-water trawling capabilities that target high-value species.
GCC seafood encompasses finfish, crustaceans, and mollusks harvested from marine and aquaculture operations, typically processed to maintain protein integrity below 4°C through cold-chain logistics. The category serves protein substitution in diets across the Arabian Peninsula where per capita fish consumption trails Mediterranean benchmarks. Frozen fish holds structural dominance in retail channels due to shelf-life requirements imposed by Gulf climate conditions and distribution distances. Foodservice Providers represent the fastest-growing distribution channel as hotel and restaurant chains expand procurement from centralized importers. Processed Seafood captures concentrated margin pools through value-added formats such as marinated fillets and ready-to-cook portions that command premium positioning in Saudi and UAE retail.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce halal handling protocols and maximum residue limits for aquaculture inputs across the Gulf. These frameworks shape import documentation requirements and domestic facility certification, directly influencing market access for non-regional suppliers. GCC standardization bodies are harmonizing seafood safety protocols under the Gulf Technical Regulation for Fishery Products. Stakeholders must monitor evolving aquaculture licensing regimes in Oman and Bahrain as both states expand offshore cage permits to reduce import dependency.
Market Dynamics
Hotel chains across the Gulf are consolidating procurement through centralized importers, compressing margins for fragmented distributors while rewarding scale players with cold-chain capabilities.
Growth Catalysts
- Recirculating Aquaculture Systems:The UAE's deployment of RAS technology is lifting domestic production yields and reducing import dependency for high-value finfish species.
- SFDA Food Security Mandates:Saudi Arabia's hatchery development programs are accelerating local tilapia and shrimp production capacity along the Red Sea coast.
- Foodservice Procurement Consolidation:International hotel operators are expanding long-term supply agreements with integrated processors capable of halal-certified cold-chain delivery.
Market Restraints
- Feed Input Volatility:Aquaculture operations face margin pressure from fluctuating fishmeal and soy protein concentrate costs sourced from South American suppliers.
- Import Concentration Risk:Over half of GCC seafood supply originates from a narrow set of Southeast Asian and Norwegian exporters, creating vulnerability to shipping disruptions.
- Halal Certification Friction:Emirates Authority for Standardization and Metrology documentation requirements impose extended clearance timelines for non-regional suppliers lacking pre-certified facilities.
Strategic Opportunities
- Oman Offshore Cage Expansion:The sultanate's aquaculture licensing reforms are opening deep-water sites for seabream and cobia farming with reduced environmental conflict.
- Ready-to-Cook Value Addition:Marinated fillets and portion-controlled packaging command premium positioning in Saudi retail channels where convenience demand outpaces supply.
- Blockchain Traceability Convergence:Integration of distributed ledger systems with IoT temperature sensors is enabling real-time halal chain-of-custody verification for export markets.
Industry Challenges
- Aquaculture Technician Scarcity:RAS operations and hatchery management require specialized marine biology expertise that remains underdeveloped in Gulf labor markets.
- Legacy Cold-Chain Gaps:Last-mile distribution infrastructure in Bahrain and Kuwait lacks consistent sub-4°C maintenance, constraining fresh product penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Seafood Market |
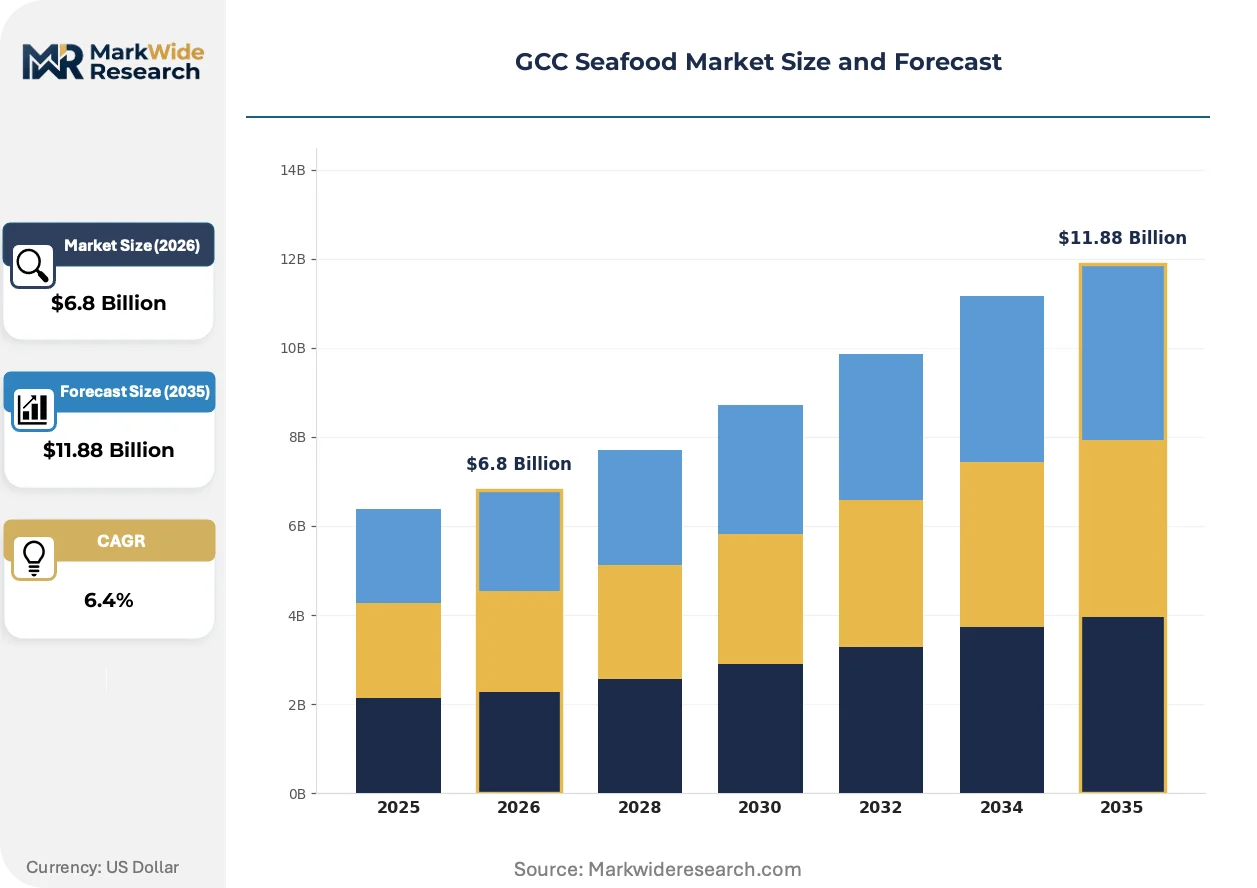
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fish, Frozen Fish, Crustaceans, Mollusks, Processed Seafood Distribution Channel: Supermarkets, Fish Markets, Online Retailers, Foodservice Providers, Specialty Stores Application: Household Consumption, Hospitality Sector, Catering Services, Food Processing, Institutional Dining Customer Type: Retail Consumers, Restaurateurs, Hotel Chains, Exporters, Seafood Wholesalers |
| Companies Covered | Sea Pride LLC, Tabuk Fisheries Company, National Fishing Company K.S.C., Almunajem Foods, Albatha Group, Oman Fisheries Co. SAOG, National Aquaculture Group, The Deep Seafood Company, Blue Island PLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Seafood Market Shifts & Advancements
Digital traceability systems and automated processing lines are compressing traditional supply hierarchies while regulatory harmonization across the Gulf reshapes competitive entry barriers.
Recirculating aquaculture systems with biofiltration and oxygen injection are transforming land-based production economics in water-scarce environments. Saudi hatchery operators are adopting these closed-loop designs at commercial scale, cutting water exchange rates by orders of magnitude. This technology is integrating vertically with processing facilities to enable same-day harvest-to-retail cycles that bypass conventional port logistics.
Gulf Technical Regulation for Fishery Products harmonization is creating unified safety protocols across Saudi Arabia, UAE, Kuwait, Oman, Qatar, and Bahrain. The framework eliminates redundant national testing regimes for cross-border seafood trade. Processors with single-point certification now access six markets without duplicate laboratory analysis, compressing compliance costs for integrated operators while raising barriers for small importers lacking technical documentation capacity.
Centralized procurement contracts are displacing spot-market purchasing among international hotel chains expanding across Dubai, Riyadh, and Jeddah. Long-term agreements with volume commitments and fixed pricing tiers are replacing fragmented supplier relationships. This concentration is most visible in the UAE, where flagship property developments are pre-contracting five-year supply agreements with single-source importers possessing dedicated cold-chain fleets.
GCC Seafood Market Segmentation
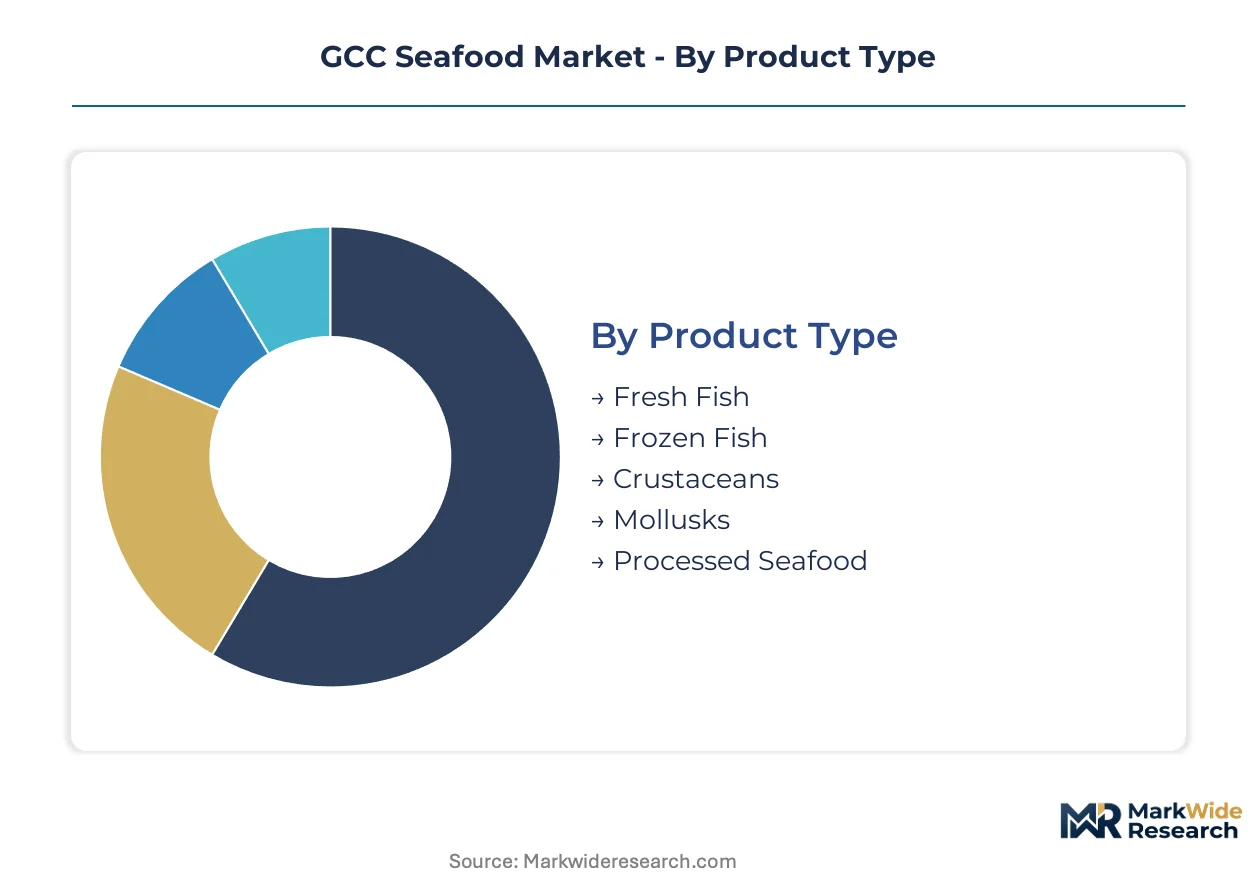
Segmentation reveals how Gulf climate constraints and halal certification requirements reshape procurement patterns across product formats and channel structures. Understanding these divides clarifies where cold-chain investments concentrate versus where spot-market purchasing persists.
Product Type:
Upgrade cycles in processing technology are shifting volume from commodity formats toward value-added products with extended shelf stability.
- Fresh Fish:Whole and filleted finfish requiring continuous sub-4°C handling from Red Sea landings through retail display. Demand clusters in Jeddah and Dubai hotel procurement where same-day delivery contracts command premium positioning against frozen alternatives.
- Frozen Fish:Blast-frozen at sea or shore-based facilities with glazing protocols that preserve protein integrity across Gulf distribution distances. Saudi retail chains and Kuwaiti importers depend on this format to overcome last-mile refrigeration gaps in interior markets.
- Crustaceans:Shrimp dominates regional aquaculture output with hatchery expansion along the Red Sea coast.
- Mollusks:Oysters and clams remain import-dependent with limited domestic cultivation.
- Processed Seafood:Marinated fillets and ready-to-cook portions targeting time-constrained Saudi households.
Frozen Fish sits at the top of the volume ranking, with Processed Seafood climbing the fastest.
Distribution Channel:
Channel selection tracks customer scale and certification burden, with integrated cold-chain operators capturing share from fragmented intermediaries.
- Supermarkets:Hypermarket chains in Riyadh and Abu Dhabi operate dedicated seafood counters with halal-certified processing rooms and traceability documentation. These formats are consolidating procurement through direct importer relationships that bypass traditional wholesale layers.
- Fish Markets:Traditional auction-based landing sites in Dammam and Muscat where restaurant buyers source whole fish for in-house butchering. SFDA and MOHAP inspection protocols are digitizing documentation workflows at these facilities.
- Online Retailers:E-commerce platforms with temperature-controlled last-mile fleets expanding in Dubai and Manama.
- Foodservice Providers:Centralized procurement arms of international hotel operators with multi-year supply agreements.
- Specialty Stores:High-end retailers focusing on premium imported species for expatriate consumers.
Foodservice Providers are gaining share fastest, though Fish Markets retain volume leadership in raw material throughput.
Application:
Application mix reflects the divergence between household substitution patterns and institutional procurement scale.
- Household Consumption:Retail purchases for home preparation where frozen fillets dominate due to storage convenience in Gulf climates. Saudi consumers show rising preference for value-added formats that reduce preparation time.
- Hospitality Sector:Hotel and restaurant operations across Dubai, Jeddah, and Doha with standardized menu specifications requiring consistent supply. This segment demands halal chain-of-custody documentation from catch to kitchen.
- Catering Services:Event and contract food providers with bulk volume requirements.
- Food Processing:Manufacturers producing breaded, smoked, or canned seafood products for regional distribution.
- Institutional Dining:Hospital, military, and university cafeterias with cost-focused procurement.
Household Consumption holds the largest volume position, while Hospitality Sector applications are expanding most quickly.
Customer Type:
Customer stratification follows procurement sophistication, with certified large buyers extracting terms unavailable to fragmented purchasers.
- Retail Consumers:Individual purchasers selecting products based on freshness indicators and price points at point of sale. This group shows growing sensitivity to origin labeling and sustainability claims in UAE and Saudi markets.
- Restaurateurs:Independent restaurant operators with flexible sourcing strategies mixing local landings and imported frozen inventory. Their buying decisions prioritize reliability over long-term contract commitments.
- Hotel Chains:International operators with centralized procurement functions and dedicated supplier audit programs.
- Exporters:Traders re-exporting Gulf-caught or processed seafood to Asian and European markets.
- Seafood Wholesalers:Traditional intermediaries consolidating landings for redistribution to smaller retail and foodservice accounts.
Hotel Chains command the steepest expansion trajectory in procurement volume, with Seafood Wholesalers retaining the top position in transaction count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands the largest procurement volumes in the GCC, while the UAE leads in aquaculture technology deployment and cold-chain sophistication. Kuwait and Bahrain remain import-dependent with nascent domestic production. Oman is accelerating offshore licensing to capture deep-water farming advantages.
Saudi Arabia
Red Sea hatchery clusters in Tabuk and Jazan are scaling tilapia and shrimp output under SFDA food security mandates. The Kingdom's aquaculture licensing reforms are streamlining permits for integrated shore-based operations. Sea Pride LLC controls quality from catch to retail through processing facilities along the western coastline.
United Arab Emirates
Dubai and Abu Dhabi hotel chains are consolidating procurement through centralized importers with dedicated cold-chain fleets. MOHAP inspection protocols are digitizing documentation workflows at landing sites. The Emirates' RAS technology deployment is lifting domestic finfish yields while reducing import dependency for high-value species.
Oman
Deep-water cage permits for seabream and cobia are expanding along the Dhofar coast under revised aquaculture licensing frameworks. The sultanate's offshore sites face reduced environmental conflict compared to nearshore alternatives. Muscat-based processors are integrating with these farming operations to enable same-day harvest-to-retail cycles.
Kuwait
Last-mile refrigeration gaps in interior markets constrain fresh product penetration, forcing reliance on frozen formats. The country's seafood supply chains depend on centralized importers with blast-freezing capabilities. Traditional fish markets in Shuwaikh retain volume leadership in raw material throughput despite digitization pressures.
Bahrain
Manama's foodservice sector is expanding temperature-controlled last-mile fleets to serve international hotel operators. The island's limited domestic production necessitates import concentration from Southeast Asian suppliers. Regulatory harmonization under Gulf Technical Regulation for Fishery Products is easing cross-border trade with Saudi and UAE partners.
GCC Seafood Market Competitive Landscape
Saudi producers anchor one tier; UAE and Omani specialists hold distinct positions in technology-forward and offshore farming respectively. The vendor base clusters around integrated processors with cold-chain capabilities, fragmented landing-site operators, and import-dependent distributors serving interior markets. Three archetypes dominate: shore-based integrated processors, offshore cage operators, and centralized procurement platforms. Competitive moves concentrate on backward integration into hatchery operations and long-term supply agreements with international hotel chains.
Among Saudi-based integrated operators, Sea Pride LLC and Tabuk Fisheries Company exemplify the shore-based processor archetype with Red Sea coastal positioning. National Fishing Company K.S.C. occupies a specialized tier targeting deep-water species through trawling capabilities. These three entities represent contrasting strategic postures within the Kingdom's consolidation trajectory—integrated quality control, fleet-based domestic landings, and high-value species specialization.
| Leading Market Players |
|---|
| Sea Pride LLC |
| Tabuk Fisheries Company |
| National Fishing Company K.S.C. |
| Almunajem Foods |
| Albatha Group |
| Oman Fisheries Co. SAOG |
| National Aquaculture Group |
| The Deep Seafood Company |
| Blue Island PLC |
| Others |
Supply & Pricing Matrix
Fishmeal price indices from South American suppliers cascade through GCC aquaculture operations into three distinct pricing tiers across retail and foodservice channels. Feed input volatility compresses margins at integrated processors while rewarding operators with captive hatchery supply and long-term procurement contracts with international hotel chains.
Pricing Analysis
Retailer markup layers dominate final price formation, with hypermarket chains in Riyadh and Abu Dhabi extracting substantial margins from halal-certified processing rooms and traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates same-day fresh deliveries from blast-frozen imports and commodity-grade frozen fillets. Cost compression in the standard tier is intensifying because feed input volatility and import concentration squeeze processor margins. Small restaurant operators show highest price sensitivity, while international hotel chains with centralized procurement functions prioritize reliability and certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology mandate multi-supplier qualification for hotel chains consolidating procurement through centralized importers. Geographic supply concentrates in Norway, Vietnam, and Thailand for high-value finfish and shrimp imports. Raw material dependencies rest on fishmeal and soy protein concentrate from South American suppliers, plus hatchery fry from specialized breeders. Single-source vulnerability from narrow Southeast Asian and Norwegian exporter bases creates exposure to shipping disruptions. Distribution runs through integrated cold-chain operators with dedicated fleets serving hotel procurement arms, bypassing fragmented wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC seafood functions as a regulatory compounder where Gulf Technical Regulation for Fishery Products harmonization creates unified safety protocols that consolidate market access around certified operators. This regulatory milestone accelerates demand concentration toward integrated processors capable of single-point certification across six Gulf markets.
For Market Incumbents: Lock in long-term supply agreements with international hotel chains expanding across Dubai, Riyadh, and Jeddah before procurement consolidation completes. Secure backward integration into Red Sea hatchery operations to control tilapia and shrimp fry supply against feed input volatility. SFDA licensing reforms threaten smaller landing-site operators with compliance costs that integrated players can absorb through scale. For New Entrants and Emerging Players: Blockchain traceability systems integrated with IoT temperature sensors offer a technology-first wedge into premium foodservice segments demanding real-time halal chain-of-custody verification. Ready-to-cook value-added formats in Saudi retail channels present the most penetrable white-space, with convenience demand outstripping domestic supply. A direct-to-hotel sales model bypassing fragmented distributor networks captures procurement consolidation momentum. For Investors and Strategic Acquirers: Asymmetric upside sits with shore-based integrated processors possessing Red Sea coastal positioning and existing SFDA facility certification. The five-to-ten year viability window favors operators combining hatchery control with processing capacity under unified quality management. Watch for Oman offshore cage licensing acceleration as the inflection signal indicating deep-water farming economics reaching commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Backward Integration | Captive fry supply from Red Sea facilities insulates margins from South American feed volatility. |
| Blockchain Traceability Deployment | Distributed ledger integration with MOHAP protocols enables premium positioning in hotel procurement. |
| Long-term Supply Agreement | Five-year contracts with Dubai flagship properties lock in volume commitments ahead of competitor consolidation. |
| RAS Technology Scale-Up | Closed-loop aquaculture systems cut water exchange rates and enable same-day harvest-to-retail cycles. |
| Oman Offshore Licensing | Deep-water cage permits for seabream and cobia farming reduce environmental conflict and import dependency. |
Research Methodology
Direct dialogue with aquaculture operations managers, hotel procurement directors, SFDA regulatory affairs leads, and cold-chain logistics specialists grounded qualitative findings in operational reality. Secondary validation drew from Gulf Technical Regulation for Fishery Products documentation, SFDA licensing registries, MOHAP inspection protocols, customs import records, and hotel development pipeline databases. Bottom-up hatchery capacity estimates and top-down tourism-driven demand projections were cross-referenced for triangulation.
Segmentation outputs across product type, distribution channel, application, and customer type were modeled over the projection horizon with CAGRs derived from historical trade flow analysis and capacity build-out timelines. Forecast inputs incorporated Red Sea hatchery expansion trajectories, RAS deployment schedules in the Emirates, and international hotel chain procurement consolidation patterns.
The model holds under stable regulatory harmonization and continued tourism capacity expansion; deviation in feed input cost spikes or shipping route disruptions would shift volume projections materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Meal Market
Seafood
North America Seafood Market
Seafood
Global White Shrimp Market
Seafood
United Arab Emirates Seafood Market
Seafood
Global Smoked Fish Market
Seafood
Oyster Meal Market
Seafood
Mussel Extract Market
Seafood
COD Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
United States Plant-Based Seafood Market
Seafood
Haddock Market
Seafood
Dry-Packaged Scallops Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Seafood Powders Market
Seafood
Middle East and Africa Canned Seafood Market