
 Canned Mackerel Market | 2026-2036
Canned Mackerel Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Mackerel Market Outlook
Fishery labor availability is bifurcating output capacity between artisanal fleets and industrial processors. Thai Union Group PCL anchors Southeast Asian supply through integrated cold-chain infrastructure. Bolton Group leverages Mediterranean sourcing networks to sustain European shelf presence. Maruha Nichiro Corporation dominates Japanese retail with species-specific canning protocols.
Canned mackerel denotes cooked, preserved pelagic fish sealed in hermetically processed containers with shelf stability exceeding thirty-six months at ambient temperature. Thermal sterilization at temperatures above 116°C eliminates Clostridium botulinum risk while retaining omega-3 fatty acid profiles above 1.5 grams per 100 grams for nutritional labeling claims. Tin can packaging retains dominant retail share due to established recycling infrastructure and transport durability. Flexible pouch formats attract single-serve convenience demand from urban households. In oil product variants command premium positioning through flavor intensity and Mediterranean recipe alignment.
EU REACH compliance governs coating chemistries in food-contact metal packaging across European distribution. Thailand's FDA-equivalent national food regulator enforces HACCP certification for export-oriented canneries accessing supermarket channels. Japan's JIS standards specify drained weight tolerances that directly determine wholesale acceptance thresholds. Stakeholders must monitor evolving extended producer responsibility frameworks for single-use packaging before committing to capacity expansion.
Market Dynamics
EU F-Gas Regulation mandates are forcing cold-chain equipment retrofits across Thai and Malaysian cannery clusters, compressing operating margins while accelerating consolidation among processors lacking capital reserves for compliant infrastructure.
Growth Catalysts
- Working household pantry stocking:Dual-income urban families in Japan and South Korea maintain baseline volume through recession-resistant protein purchases. Retail scanner data confirms repeat purchase rates above ambient protein alternatives.
- REACH coating compliance:ECHA food-contact metal packaging standards create barrier-to-entry advantages for certified European suppliers serving supermarket private-label programs.
- Omega-3 retention protocols:Thermal sterilization above 116°C preserves fatty acid profiles exceeding 1.5 grams per 100 grams, enabling premium nutritional labeling claims in health-conscious segments.
Market Restraints
- Tinplate input cost volatility:Steel coil and tin ingot price swings directly compress cannery gross margins, with Thai processors particularly exposed to import dependency.
- Fishery labor bifurcation:Artisanal fleet crew availability constrains raw material throughput to industrial processors during peak catch seasons.
- Flexible pouch substitution:Single-serve polymer formats capture urban convenience demand, eroding tin can share in Japanese convenience store channels.
Strategic Opportunities
- Extended producer responsibility frameworks:EU packaging waste directives incentivize closed-loop tin recycling investments, rewarding processors with established recovery infrastructure.
- Mediterranean recipe alignment:In-oil variants command shelf price premiums through flavor intensity positioning in Italian and Spanish retail.
- Southeast Asian export clustering:Thailand's FDA-equivalent HACCP certification creates passporting advantages into Middle Eastern supermarket supply chains.
Industry Challenges
- Hermetic seal certification timelines:JIS drained weight tolerance testing extends product approval cycles for Japanese market entry.
- Cold-chain capex intensity:F-Gas compliant refrigeration retrofits demand capital outlays exceeding smaller Malaysian cannery liquidity reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Mackerel Market |
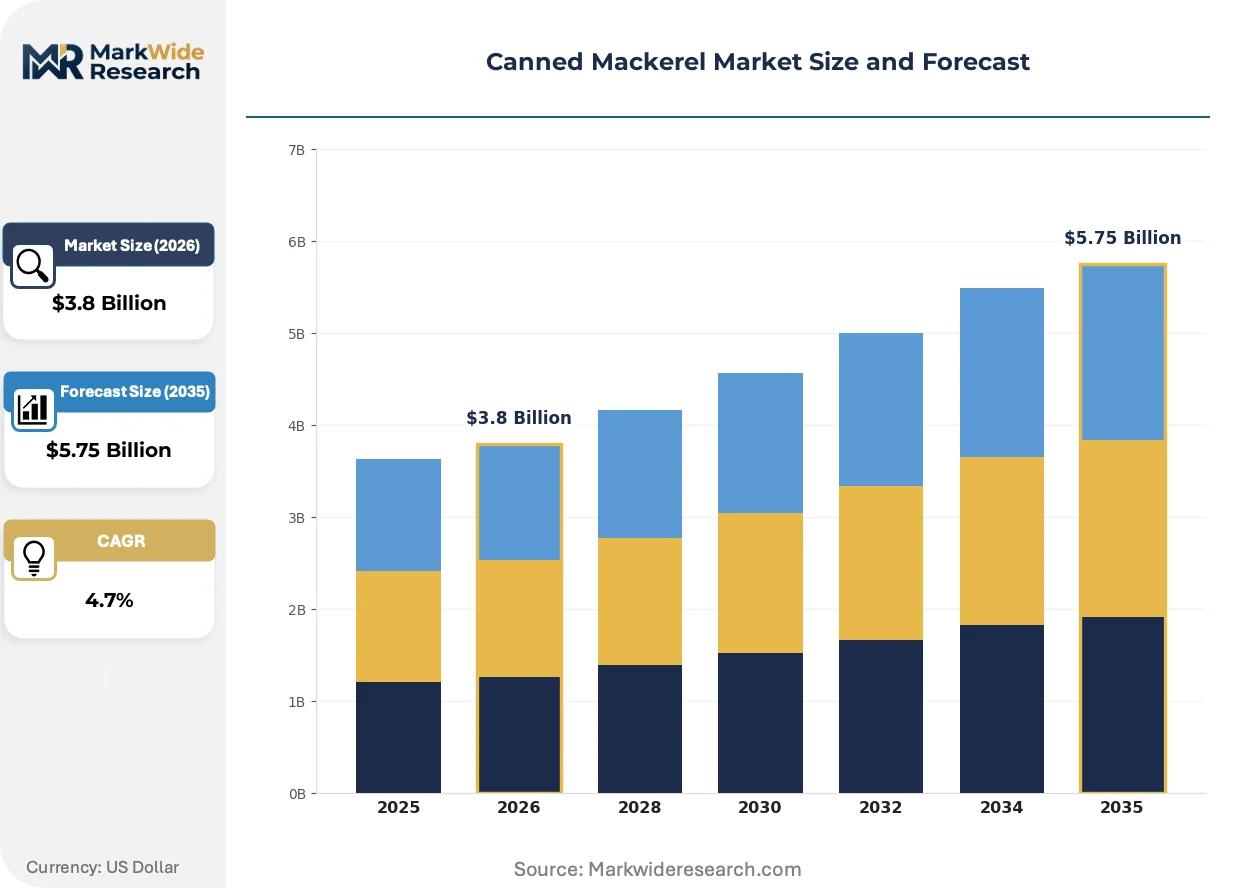
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Oil, In Water, In Tomato Sauce, In Brine Packaging Type: Tin Can, Glass Jar, Flexible Pouch, Carton Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale End User: Households, Restaurants, Food Manufacturers, Canneries |
| Companies Covered | Bolton Group, Diavena, Thai Union Group PCL, Marushin Canneries Malaysia, Universal Canning Inc., Maruha Nichiro Corporation, Brunswick, LDH (La Doria) Ltd, FCF Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Mackerel Market Strategic Shifts
Processing automation and packaging format diversification are compressing unit economics while opening new channel access points for differentiated product positioning.
Retort pouch sterilization technology is supplanting traditional tin can lines in Southeast Asian export facilities. Japanese retail buyers are accelerating qualification timelines for flexible formats. The shift enables shelf-space efficiency gains in urban convenience channels while reducing shipping cube by approximately forty percent versus cylindrical metal containers.
EU F-Gas Regulation phase-down schedules are mandating hydrofluorocarbon replacement in blast freezing operations. Thai Union Group facilities face compressor retrofit decisions before 2027 compliance deadlines. Processors with captive cold-chain infrastructure are consolidating supply relationships with artisanal fleets to amortize capital costs across higher throughput volumes.
Urban household purchasing is fragmenting across single-serve and family-size formats simultaneously. Convenience store chains in Tokyo and Osaka are expanding grab-and-go shelf sets while hypermarkets maintain multi-can promotional packs. This bifurcation forces processors to maintain dual SKU portfolios without scale economies from format standardization.
Canned Mackerel Market Segmentation
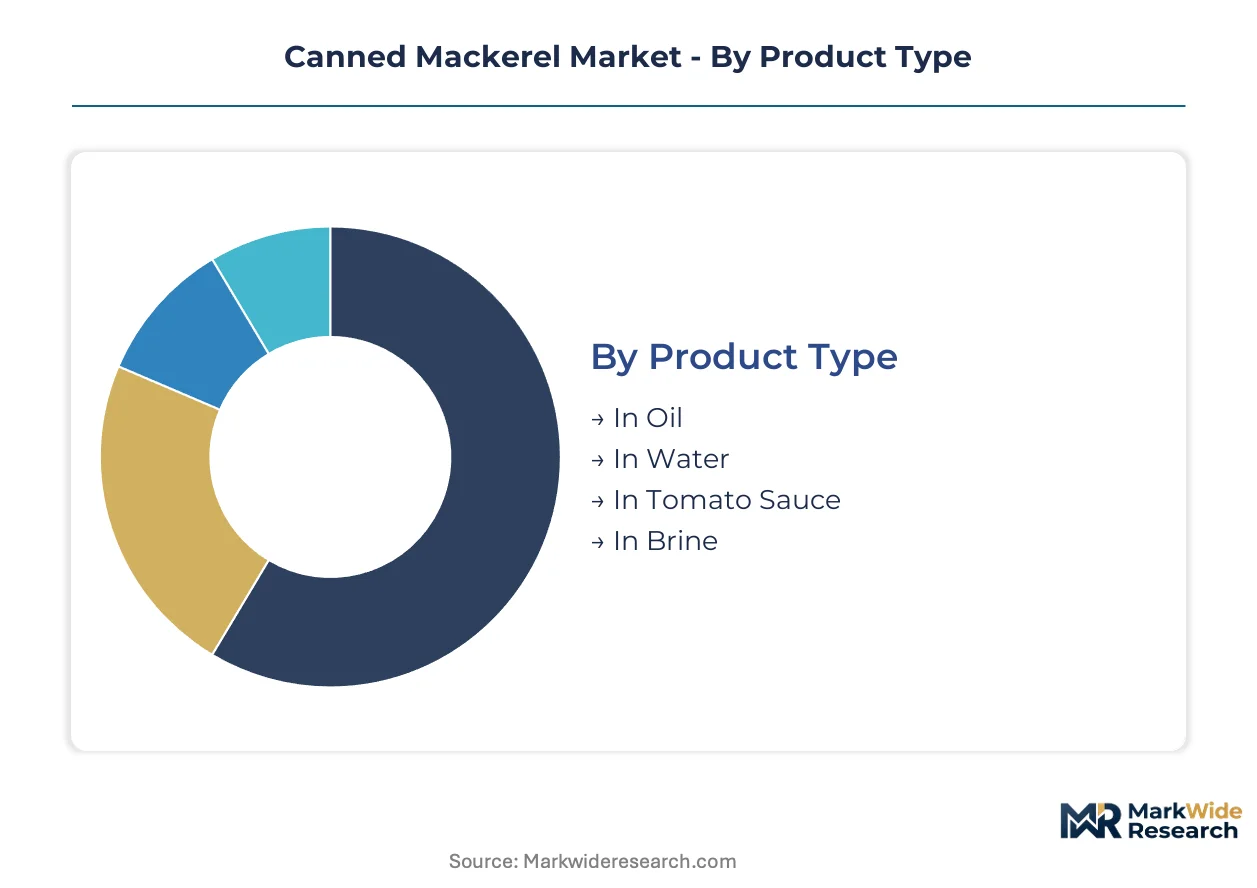
Segmentation in canned mackerel reveals how substitution pressures and channel evolution reshape competitive priorities across product formats. Understanding these divides clarifies where processors must defend volume against flexible packaging alternatives and where premium positioning sustains margin.
Product Type:
Substitution pressure from fresh and frozen fish alternatives concentrates most intensely in value-oriented segments where price sensitivity dominates pantry decisions.
- In Oil:Olive or vegetable oil immersion creates flavor intensity that commands shelf price premiums in Italian and Spanish retail. Mediterranean recipe alignment drives repeat purchase among households seeking omega-3 retention above 1.5 grams per 100 grams.
- In Water:Brine-based preservation minimizes caloric density for health-conscious urban consumers in Tokyo and Osaka convenience channels. Clean-label positioning attracts dual-income households managing sodium intake without sacrificing protein accessibility.
- In Tomato Sauce:Tomato-based variants target Southern European pantry traditions with ready-meal convenience.
- In Brine:Salt-solution preservation offers the lowest unit cost entry point for budget-conscious bulk purchasing.
In Oil anchors the volume base while In Water gains share at the steepest rate.
Packaging Type:
Cost tier stratification separates capital-intensive metal infrastructure from polymer formats that reduce shipping cube and retail shelf footprint.
- Tin Can:Cylindrical metal containers retain dominant retail share through established EU recycling infrastructure and transport durability. REACH-compliant coating chemistries create barrier-to-entry advantages for certified European suppliers.
- Flexible Pouch:Retort-sterilized polymer formats reduce shipping cube by approximately forty percent versus metal equivalents. Japanese convenience store chains accelerate qualification timelines for single-serve urban consumption.
- Glass Jar:Transparent presentation supports premium positioning in specialty retail channels.
- Carton:Paper-based outer packaging with inner barrier films targets sustainability-conscious supermarket private-label programs.
Tin Can maintains the installed production base while Flexible Pouch expands most quickly in channel access.
Distribution Channel:
Volume concentration in modern trade formats determines processor SKU proliferation requirements and promotional investment intensity.
- Supermarkets:Multi-can promotional packs and private-label programs dominate household pantry stocking in Japan and South Korea. Retail scanner data confirms repeat purchase rates above ambient protein alternatives.
- Convenience Stores:Grab-and-go shelf sets in Tokyo and Osaka favor single-serve formats with minimal preparation requirements.
- Online Retail:E-commerce penetration accelerates in South Korean urban markets with subscription-based replenishment models.
- Wholesale:Foodservice and institutional volume moves through cash-and-carry formats serving restaurant and cannery procurement.
Supermarkets anchor the volume base while Convenience Stores gain share at the steepest rate.
End User:
Customer type segmentation separates recession-resistant household purchasing from cyclical foodservice demand and industrial raw material offtake.
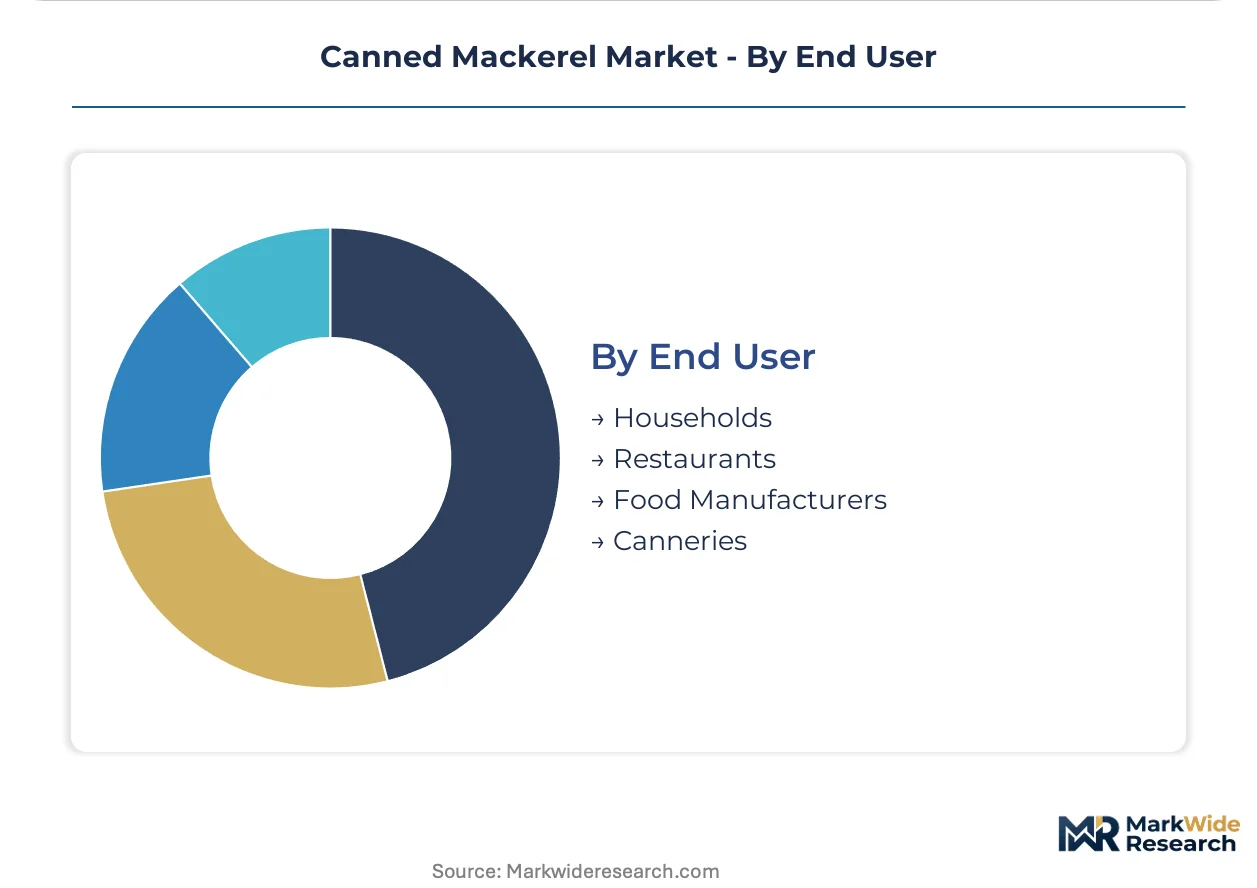
- Households:Dual-income urban families sustain baseline volume through recession-resistant protein purchases with shelf stability exceeding thirty-six months.
- Restaurants:Foodservice operators in Mediterranean markets leverage canned mackerel for recipe consistency and labor cost reduction.
- Food Manufacturers:Industrial processors incorporate mackerel as ingredient input for ready-meal and pet food formulations.
- Canneries:Secondary processors repack bulk supply into private-label or specialty formats for regional distribution.
Households anchor the volume base while Food Manufacturers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance anchors European market access for canned mackerel processors, while Japan's JIS standards and Thailand's FDA-equivalent regulations shape quality thresholds across Asia-Pacific supply chains.
Japan
Dual-income households in Tokyo and Osaka sustain recession-resistant pantry stocking with repeat purchase rates exceeding ambient protein alternatives. METI oversees food-contact material standards that govern retort pouch adoption in convenience store channels. Kanto region processors face JIS drained weight tolerance testing that extends product approval cycles for domestic retail entry.
Thailand
Export-oriented canneries leverage HACCP certification to access Middle Eastern supermarket supply chains with growing volume commitments. The country's FDA-equivalent national food regulator enforces cold-chain compliance mandates ahead of EU F-Gas Regulation alignment deadlines. Samut Sakhon province hosts integrated processing clusters where Thai Union Group facilities face 2027 compressor retrofit decisions.
Italy
Mediterranean recipe traditions drive premium positioning for in-oil variants through olive oil immersion and flavor intensity differentiation. ECHA REACH coating chemistries create barrier-to-entry advantages for certified suppliers serving supermarket private-label programs. Southern port cities concentrate secondary processing operations that repack bulk supply into regional distribution formats.
South Korea
Urban families maintain baseline canned mackerel volume through shelf-stable protein accessibility exceeding thirty-six months. MFDS regulates omega-3 retention labeling claims that processors must verify through thermal sterilization protocols. Seoul metropolitan area hypermarkets anchor multi-can promotional pack distribution while convenience stores test single-serve flexible pouch formats.
Malaysia
Artisanal fleet crew availability constrains raw material throughput to industrial processors during peak catch seasons. The national food safety authority enforces HACCP certification parallel to Thai standards for export market access. Penang and Selangor cannery clusters face F-Gas compliant refrigeration capital demands that exceed smaller processor liquidity reserves.
Canned Mackerel Market Competitive Environment
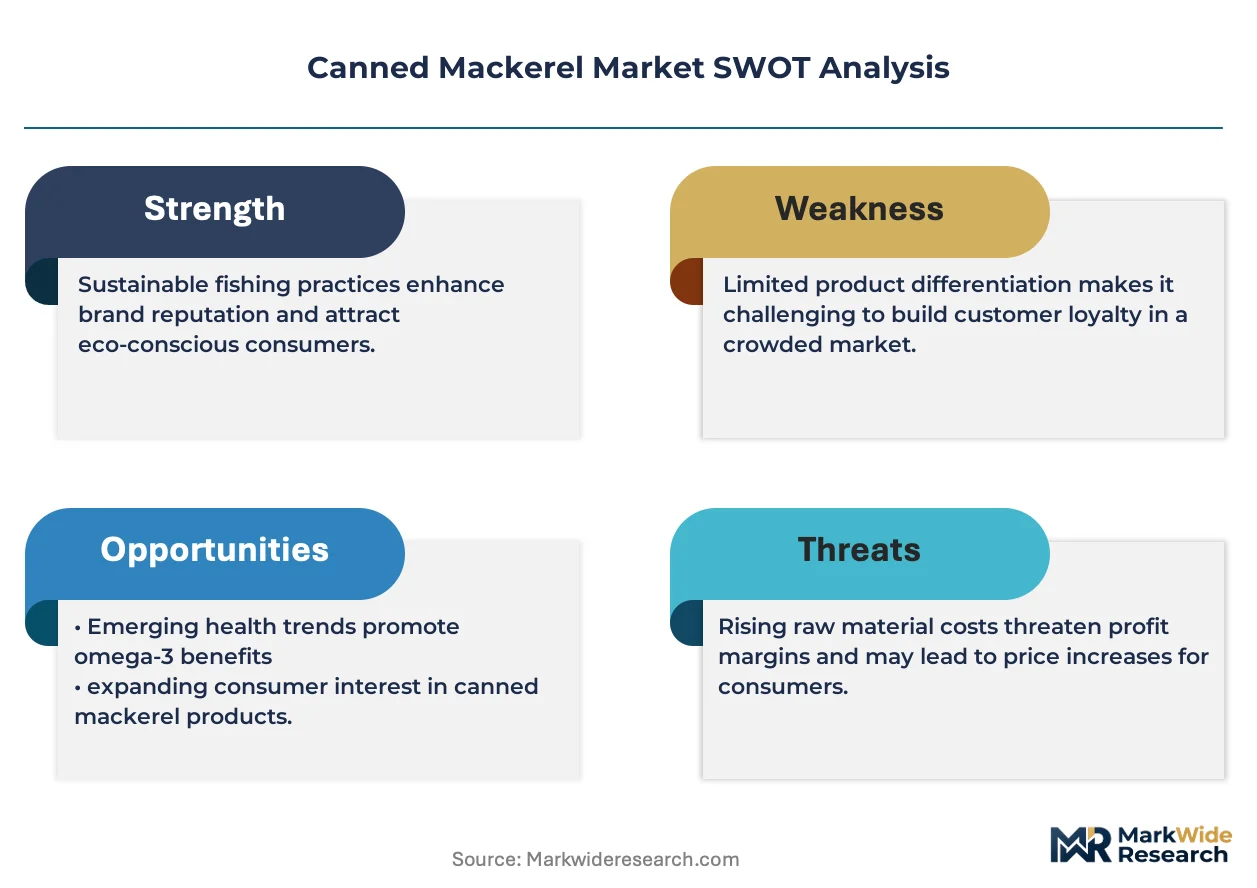
A small set of integrated leaders sits above a broader specialist tier that concentrates on species-specific protocols or regional recipe formats. The upper tier controls captive cold-chain infrastructure and backward integration into fishery operations. Specialists compete through Mediterranean sourcing networks or Southeast Asian export clustering. Consolidation pressures favor processors with capital reserves for F-Gas retrofit compliance, while smaller operators seek strategic partnerships to amortize equipment costs.
Within the integrated leader tier, Thai Union Group PCL and Maruha Nichiro Corporation exemplify divergent geographic anchoring strategies. Bolton Group occupies a position bridging European retail presence with Mediterranean sourcing networks. Among specialist operators, Marushin Canneries Malaysia and Universal Canning Inc. represent Southeast Asian export-focused archetypes. FCF Co., Ltd. sits within the supply-chain intermediary tier that concentrates raw material procurement for downstream cannery clients.
| Leading Market Players |
|---|
| Bolton Group |
| Diavena |
| Thai Union Group PCL |
| Marushin Canneries Malaysia |
| Universal Canning Inc. |
| Maruha Nichiro Corporation |
| Brunswick |
| LDH (La Doria) Ltd |
| FCF Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Cannery utilization rates above eighty percent in Thailand and Malaysia compress per-unit fixed costs while establishing price floors that smaller artisanal processors cannot match. Scale concentration among integrated operators with captive cold-chain infrastructure creates asymmetric pricing power against dispersed fleet suppliers.
Pricing Analysis
Price spreads between Mediterranean-sourced in-oil variants and Southeast Asian brine formats reflect olive oil input premiums and transport cost differentials. Three-tier pricing structure across premium, standard, and economy levels segments on omega-3 certification grade and REACH coating compliance. Pricing pressure stems from tinplate steel coil volatility that Thai processors pass through contractually. Budget-conscious households in South Korea exhibit highest price sensitivity; Japanese convenience channels show lowest.
Supply Chain Analysis
Thailand and Malaysia anchor global cannery output through export-oriented clusters in Samut Sakhon and Penang. Raw material draws from artisanal mackerel fleets, imported tinplate steel coils, and vegetable oil supply contracts. Single-source vulnerability concentrates in Thai Union Group's cold-chain infrastructure dominance. Distribution runs through supermarket private-label programs, Middle Eastern wholesale importers, and Japanese convenience store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort pouch interoperability with existing supermarket shelf sets creates platform-economics inflection as Japanese retailers accelerate flexible format qualification timelines.
For Market Incumbents: Shield installed tin can capacity by securing REACH-compliant coating chemistries before ECHA enforcement tightens. Consolidate relationships with artisanal fleets through pre-season offtake agreements that lock raw material throughput. Cold-chain retrofit capex demands favor processors with liquidity reserves for F-Gas compressor upgrades.
For New Entrants and Emerging Players: Thailand's FDA-equivalent HACCP fast-track certification opens Middle Eastern supermarket supply chains with lower barrier-to-entry than Japanese JIS approval cycles. Target South Korean e-commerce subscription models with single-serve pouch formats. Lead with omega-3 retention protocol transparency as nutritional labeling differentiator.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with retort pouch sterilization capability and established retailer qualification relationships. Five-to-ten year viability hinges on extended producer responsibility framework readiness for tin recycling infrastructure. Watch EU packaging waste directive implementation timelines as consolidation catalyst signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Line Conversion | Japanese convenience store qualification accelerates shelf-space efficiency gains versus cylindrical metal containers. |
| Backward Integration into Fleet Operations | Captive raw material sourcing amortizes F-Gas cold-chain capex across higher throughput volumes. |
| REACH Coating Certification Investment | ECHA compliance creates barrier-to-entry advantages for European supermarket private-label programs. |
| Middle Eastern Distribution Partnership | Thai HACCP certification passports into growing supermarket volume commitments in Gulf markets. |
| Omega-3 Retention Protocol R&D | Thermal sterilization above 116°C preserves fatty acid profiles enabling premium nutritional labeling claims. |
Study Parameters
Operator-level perspectives from cannery production managers, cold-chain logistics coordinators, supermarket category buyers, and artisanal fleet owners anchored the qualitative base. Secondary validation drew from Thai FDA-equivalent export certification records, ECHA REACH food-contact material filings, Japanese JIS drained weight tolerance standards, and customs trade data for tinplate steel coil imports. Bottom-up volume modeling triangulated against top-down protein consumption trend analysis.
Sensitivity analysis tested forecast robustness across the projection horizon through alternative catch-volume scenarios and tinplate price trajectory assumptions. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user category alongside regional regulatory cluster alignment. CAGRs derived from logistic growth curve fitting to historical volume data, with omega-3 retention protocol adoption rates and flexible pouch penetration curves as industry-specific inputs.
Underlying assumptions cover sustained working household pantry stocking behavior and F-Gas compliance deadline adherence, with deviation risk concentrated in fishery labor availability during peak catch seasons. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Shellfish Extract Market
Seafood
Fish Maw Market
Seafood
Asia-Pacific Seafood Market
Seafood
Canned Sardines Market
Seafood
Sea Biscuits Market
Seafood
Shellfish Market
Seafood
Seafood Takeout Market
Seafood
Europe Shrimp Market
Seafood
Krill Meal Market
Seafood
Seafood Powders Market
Seafood
Octopus Market
Seafood
Canned Seafood Market
Seafood
United States Seafood Market
Seafood
Japan Lobster Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Canned Salmon Market