
 Antibiotic Free Meat Market | 2026-2036
Antibiotic Free Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotic Free Meat Market Insights
Market Dynamics and Competitive Landscape
Veterinary antibiotic stewardship expertise is collapsing across North American livestock regions, forcing processors to internalize compliance capabilities or partner with certified ranch networks. Tyson Foods leverages vertically integrated poultry operations to guarantee no-antibiotics-ever supply chains from hatchery to retail case. Perdue Farms anchors its competitive position through farmer education programs that convert conventional contract growers to antibiotic-free protocols. JBS S.A. competes by operating dedicated antibiotic-free beef processing lines in Brazilian facilities serving export markets.
Product Architecture and Segment Stratification
Antibiotic free meat denotes animal protein derived from livestock raised without subtherapeutic or therapeutic antibiotic administration, verified through veterinary record audits and residue testing protocols. The category serves retail and foodservice buyers seeking to mitigate antimicrobial resistance liability and meet procurement pledges. Poultry dominates volume due to shorter grow-out cycles that reduce disease risk exposure, while beef commands premium positioning because of extended verification timelines and higher input costs. Supermarkets occupy the largest margin pool by controlling shelf placement and private-label certification standards, whereas online retail represents the fastest-growing channel as direct-to-consumer subscription models expand.
Regulatory Environment and Strategic Outlook
USDA Process Verified Program auditors enforce chain-of-custody documentation for antibiotic-free claims, while FDA veterinary feed directive rules restrict over-the-counter antibiotic access that indirectly pressures conventional producers toward conversion. EU Green Deal farm-to-fork targets and REACH-aligned veterinary pharmaceutical restrictions shape export eligibility for non-European suppliers. Stakeholders must monitor evolving residue testing thresholds and certification reciprocity agreements between national accreditation bodies to preserve market access.
Market Dynamics
Veterinary antibiotic stewardship expertise is collapsing across North American livestock regions, forcing processors to internalize compliance capabilities or partner with certified ranch networks. This structural talent shortage concentrates supply power among vertically integrated operators who can guarantee no-antibiotics-ever chain-of-custody documentation from hatchery to retail case.
Growth Catalysts
- EU Green Deal farm-to-fork targets:REACH-aligned veterinary pharmaceutical restrictions are tightening export eligibility requirements, compelling Brazilian and Australian suppliers to accelerate no-antibiotics-ever certification to maintain European market access.
- Institutional foodservice procurement pledges:Hospital systems and university dining contracts now mandate certified antibiotic-free proteins, creating guaranteed offtake volumes that de-risk grower conversion investments.
- CRISPR-based disease resistance breeding:Gene-edited livestock lines are reducing pathogen susceptibility without antibiotic intervention, shortening the economic payback period for antibiotic-free protocol adoption.
Market Restraints
- Feed input cost volatility:Non-medicated feed formulations rely on higher-grade protein sources and specialized additives, exposing margins to soybean meal and fishmeal price swings in Brazilian and US Midwest markets.
- Processing capacity concentration:Dedicated antibiotic-free slaughter and fabrication lines remain limited to Tyson Foods, JBS S.A., and Perdue Farms facilities, creating bottlenecks during seasonal demand spikes.
- Veterinary therapeutic access restrictions:FDA veterinary feed directive rules prohibit over-the-counter antibiotic use for disease treatment, forcing producers to absorb higher mortality losses or invest in expensive biosecurity infrastructure.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retail platforms are bypassing supermarket slotting fees, enabling regional antibiotic-free producers to capture full retail margin through monthly meat box deliveries.
- Cell-cultured protein convergence:Precision fermentation-derived growth factors combined with scaffold bioreactor technology are creating hybrid products that satisfy antibiotic-free labeling requirements while achieving price parity with conventional cuts.
- USDA Process Verified Program expansion:The federal audit framework is adding blockchain-based chain-of-custody verification, reducing certification costs for mid-size ranch networks seeking retail shelf placement.
Industry Challenges
- Veterinary record audit expertise scarcity:Qualified third-party certifiers capable of validating no-antibiotics-ever claims remain concentrated in Texas, Iowa, and São Paulo, creating inspection backlogs that delay market entry.
- Biosecurity infrastructure capex intensity:Converting conventional barns to antibiotic-free protocols requires all-in/all-out facility designs, advanced air filtration, and water acidification systems that strain grower balance sheets.
- Residue testing protocol fragmentation:Incompatible analytical methods between USDA, EU reference laboratories, and private certifiers force exporters to maintain multiple testing regimens, increasing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotic Free Meat Market |
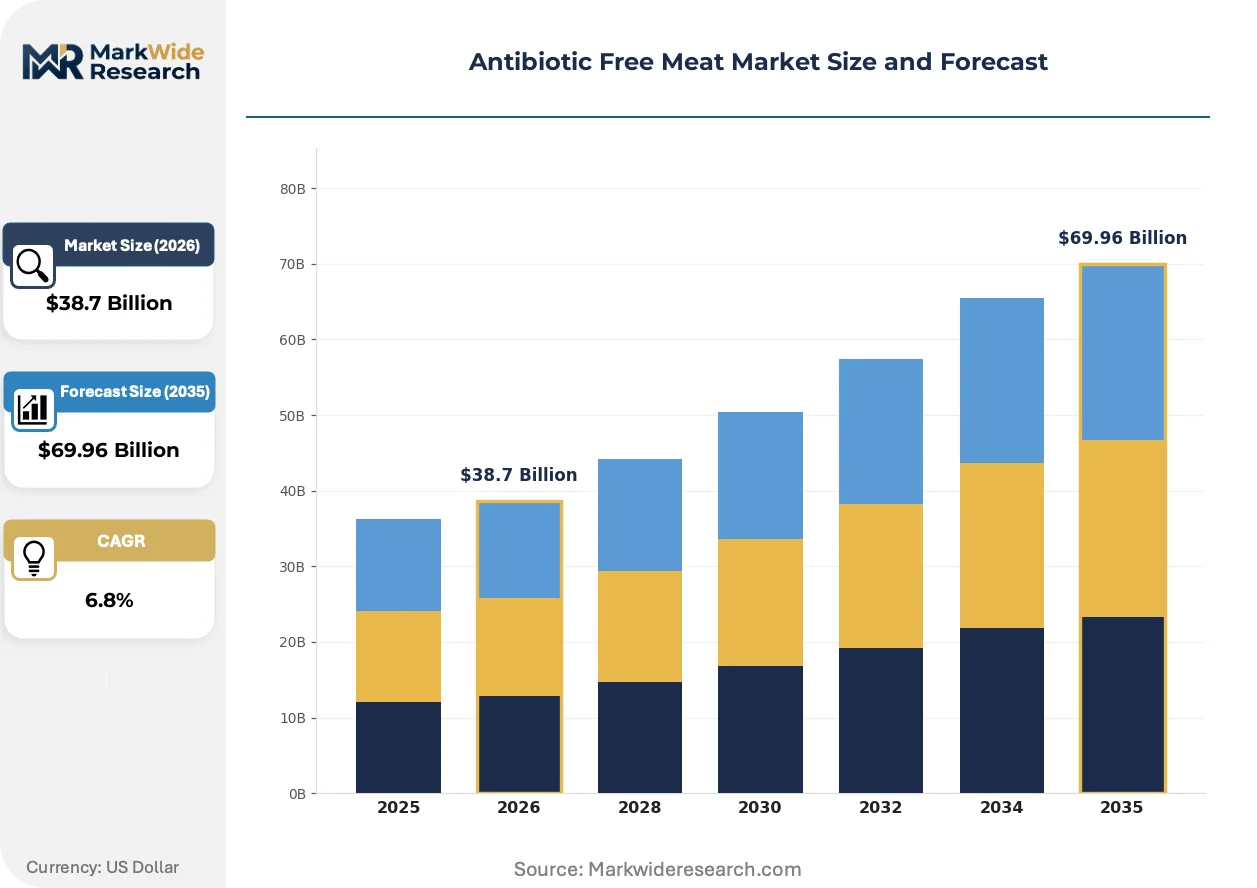
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Consumer Type: Health-Conscious Consumers, Families, Chefs, Restaurants Packaging Type: Vacuum Sealed, Trayed, Canned, Bulk |
| Companies Covered | Cargill Incorporated, Tyson Foods, Inc., JBS S.A., Hormel Foods Corporation, Perdue Farms Inc., American Foods Group, LLC, Koch Foods, Inc., Smithfield Foods, Inc., Foster Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotic Free Meat Market Trends and Innovations
Precision livestock monitoring systems and alternative health management protocols are actively displacing prophylactic antibiotic dependence across poultry, pork, and beef operations. These innovations compress disease detection timelines and enable preemptive intervention without pharmaceutical residues.
Machine vision-based early disease detection systems are displacing visual barn checks by livestock handlers. Contract growers in Georgia and Arkansas are deploying camera networks that identify respiratory distress indicators 48-72 hours before clinical symptoms appear. This compression in detection latency is displacing the economic rationale for mass medication protocols that previously served as insurance against outbreak losses.
EU Green Deal farm-to-fork targets are mandating 50% reduction in agricultural antimicrobial use by 2030, with EFSA establishing maximum residue limits that exceed Codex Alimentarius stringency. Brazilian beef exporters serving European foodservice accounts are reconfiguring feedlot operations to eliminate metaphylactic tylosin administration. Australian lamb processors are pursuing dual EU-Australian certification to capture premium positioning in German and Dutch retail channels.
Foodservice procurement departments are consolidating supplier lists around single-source antibiotic-free verification, eliminating blended procurement that commingled conventional and certified products. Major restaurant chains in the United States are requiring dedicated cold chain segregation from slaughter through distribution, displacing mixed-load logistics that previously commingled inventory. This specification tightening is most visible in California and New York state institutional purchasing, where school district nutrition directors now reject delivery vehicles without prior-load documentation.
Antibiotic Free Meat Market Segmentation
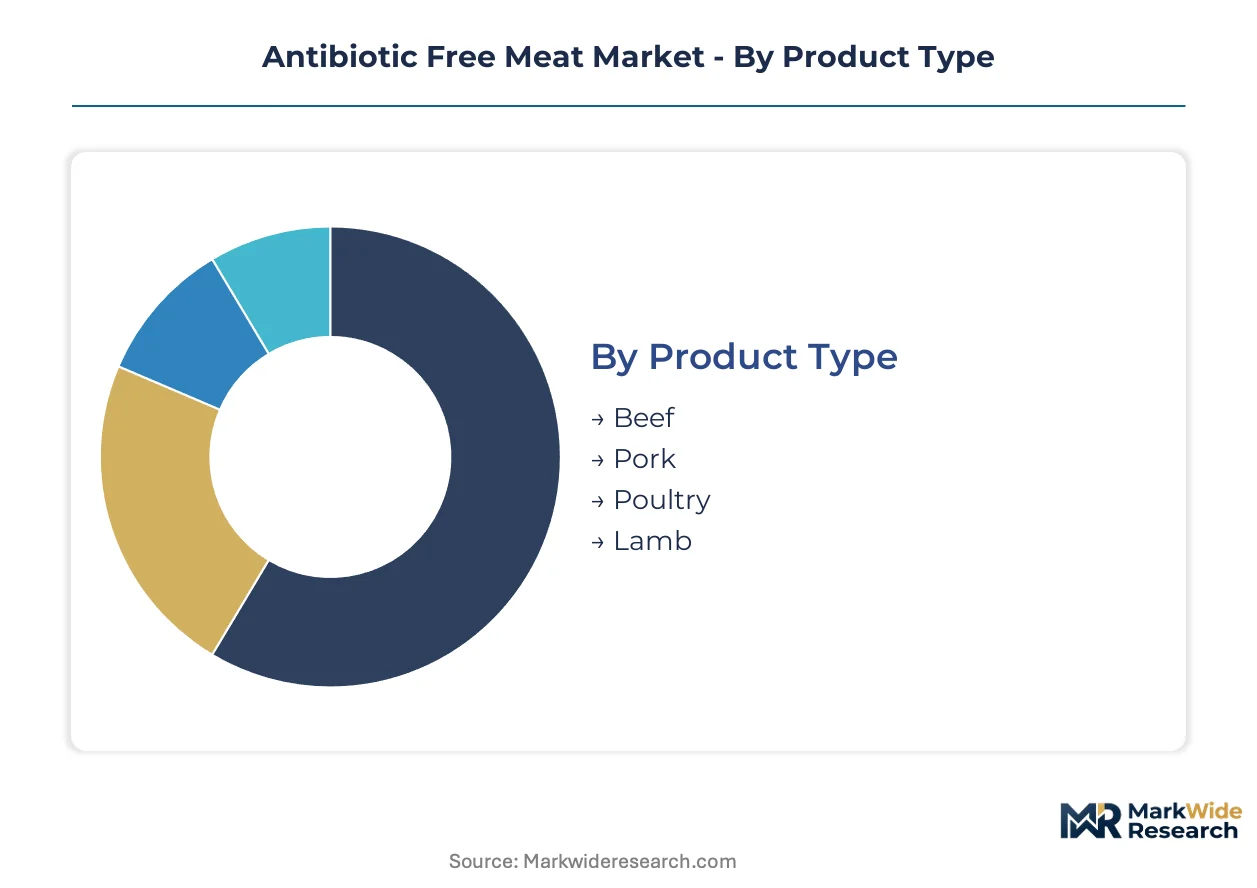
Antibiotic-free meat segmentation reveals how certification tiers, channel access, and buyer sophistication stratify pricing power across the value chain. Each dimension exposes distinct margin capture mechanisms and conversion barriers for producers exiting conventional protocols.
Product Type:
Premium positioning concentrates in species with extended verification timelines and higher mortality risk during antibiotic-free transition.
- Poultry:Shorter grow-out cycles of 6-8 weeks reduce disease exposure windows, enabling faster protocol conversion and volume scaling. US contract growers in Georgia and Arkansas dominate supply, driven by Tyson Foods and Perdue Farms procurement guarantees that de-risk grower capital commitments.
- Beef:Extended 18-24 month verification timelines and metaphylactic tylosin elimination in feedlots create steep entry barriers. Brazilian exporters serving EU foodservice accounts command premium positioning due to pasture-based finishing systems that minimize therapeutic intervention needs.
- Pork:Respiratory pathogen susceptibility in confined finishing barns elevates biosecurity infrastructure costs for antibiotic-free conversion.
- Lamb:Smaller-scale production and limited dedicated processing capacity constrain supply expansion despite strong EU and Middle Eastern demand.
The dominant share belongs to poultry, while beef is closing the gap fastest through Brazilian and Australian export certification acceleration.
Distribution Channel:
Channel selection determines certification cost recovery velocity and buyer education requirements.
- Supermarkets:Private-label certification standards and shelf placement fees concentrate margin capture among retail chains. Kroger and Whole Foods Market procurement teams enforce dedicated cold chain segregation and prior-load documentation that eliminates commingled inventory risks.
- Online Retail:Direct-to-consumer subscription models bypass slotting fees and enable regional producers to capture full retail margin. ButcherBox and Porter Road demonstrate monthly meat box economics that sustain smaller ranch networks outside conventional wholesale channels.
- Specialty Stores:Higher service intensity and educated consumer bases support premium pricing for local and heritage breed verification.
- Direct Sales:Farmers market and on-farm slaughter operations minimize certification overhead but limit volume scalability.
Supermarket channels anchor volume throughput, though online retail demonstrates the steepest expansion trajectory as subscription logistics mature.
Consumer Type:
Buyer sophistication and procurement scale determine tolerance for price premiums and verification documentation demands.
- Restaurants:Institutional foodservice contracts from hospital systems and university dining operations mandate certified antibiotic-free proteins, creating guaranteed offtake volumes. Chipotle and Panera Bread supply chain specifications require chain-of-custody documentation from slaughter through distribution.
- Health-Conscious Consumers:Antimicrobial resistance awareness and clean-label preferences drive willingness to absorb 15-40% price premiums for verified products.
- Families:Budget constraints and inconsistent retail availability limit penetration despite stated preference for antibiotic-free claims.
- Chefs:Menu storytelling value and ingredient provenance requirements support specialty sourcing from named ranch operations.
Restaurant procurement concentrates guaranteed demand, while health-conscious consumers expand the addressable market through retail trial.
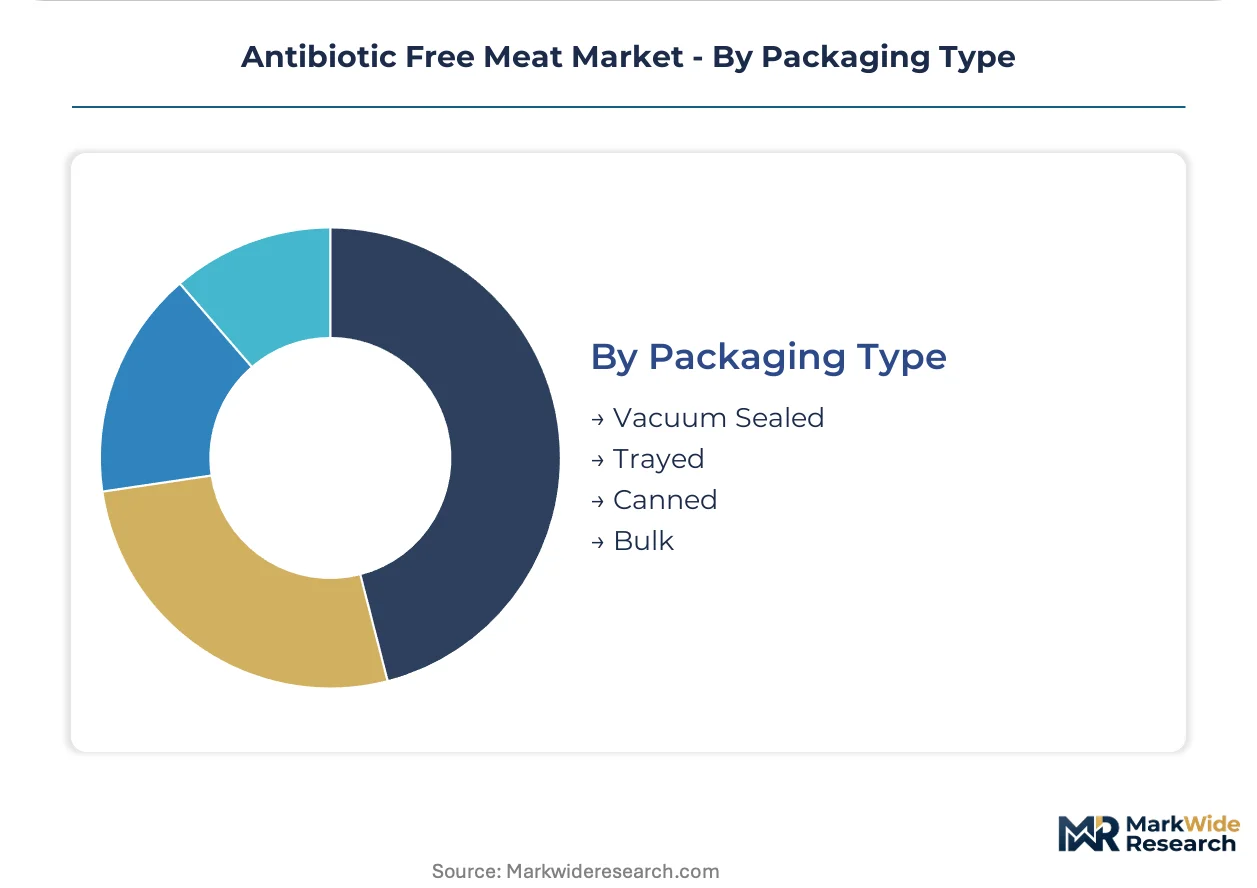
Packaging Type:
Packaging selection reflects shelf-life requirements, retail format constraints, and foodservice portion control needs.
- Vacuum Sealed:Extended shelf stability and reduced oxidation support national distribution networks and export logistics. Modified atmosphere configurations enable 21-35 day retail case life that justifies premium positioning in conventional grocery.
- Trayed:Overwrap and foam tray formats dominate conventional retail case presentation with lower unit costs but compressed shelf life.
- Bulk:Foodservice case lots and institutional procurement minimize per-pound packaging overhead for high-volume buyers.
- Canned:Shelf-stable preservation enables emergency preparedness and remote distribution but carries processed food perception penalties.
Vacuum sealed configurations command the dominant share, while bulk formats gain traction fastest through institutional procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium capture in the United States runs 20-35% above Brazilian export realizations, while Australian pasture-based systems command intermediate positioning through EU dual-certification advantages.
United States
USDA Process Verified Program auditors enforce chain-of-custody documentation that supermarket buyers demand for private-label certification. The FDA veterinary feed directive restricts over-the-counter antibiotic access, pressuring conventional producers toward conversion. Georgia and Arkansas contract growers supply Tyson Foods and Perdue Farms through vertically integrated poultry operations that guarantee no-antibiotics-ever documentation from hatchery to retail case.
Brazil
Pasture-based finishing systems in Mato Grosso and São Paulo minimize therapeutic intervention needs for export-oriented beef processors. ANVISA residue monitoring protocols align with EU Green Deal farm-to-fork targets, enabling European foodservice market access. JBS S.A. operates dedicated antibiotic-free processing lines in Brazilian facilities serving German and Dutch retail channels.
Australia
Dual EU-Australian certification requirements drive premium positioning in German and Dutch retail channels for lamb and beef exporters. The Department of Agriculture enforces export eligibility standards that exceed Codex Alimentarius stringency on residue limits. Queensland and New South Wales processors are reconfiguring feedlot operations to eliminate metaphylactic antibiotic administration.
Germany
EFSA maximum residue limits and REACH-aligned veterinary pharmaceutical restrictions create import barriers that favor certified suppliers. Retail chains in Bavaria and North Rhine-Westphalia enforce dedicated cold chain segregation and prior-load documentation that eliminates commingled inventory risks. German foodservice procurement departments are consolidating supplier lists around single-source antibiotic-free verification.
China
SAMR food safety standards and GB certification requirements are tightening domestic market entry for imported antibiotic-free proteins. Yangtze River Delta and Pearl River Delta urban consumers absorb 15-25% price premiums for verified products through e-commerce subscription channels. NMPA-aligned residue testing protocols force exporters to maintain multiple analytical regimens, increasing compliance overhead.
Antibiotic Free Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated poultry operators controlling verification documentation while pasture-based beef specialists capture premium export positioning. The market structures around three tiers: multinational protein conglomerates with captive supply networks, mid-scale regional processors with certified ranch partnerships, and direct-to-consumer subscription platforms bypassing conventional wholesale channels. Dominant competitive moves include backward integration into hatchery and feed operations, and geographic expansion through EU and Middle Eastern certification acquisition.
Among US-based protein conglomerates, Tyson Foods, Perdue Farms, and Cargill Incorporated occupy positions that exemplify the vertically integrated archetype, each representing distinct approaches to farmer education and contract grower conversion protocols. Tyson Foods anchors the scale-driven segment through poultry operations, Perdue Farms exemplifies the farmer-education model for contract grower transition, and Cargill Incorporated sits within the diversified protein portfolio tier spanning multiple species and geographic markets.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tyson Foods, Inc. |
| JBS S.A. |
| Hormel Foods Corporation |
| Perdue Farms Inc. |
| American Foods Group, LLC |
| Koch Foods, Inc. |
| Smithfield Foods, Inc. |
| Foster Farms |
| Others |
Pricing and Supply Chain Analysis
Processing capacity utilization rates above 85% in dedicated antibiotic-free slaughter facilities create scale advantages that compress per-unit certification costs while establishing price floors resistant to conventional commodity pressure. Tyson Foods and JBS S.A. leverage captive supply networks to internalize veterinary audit expenses that smaller processors must outsource, concentrating margin capture among operators with hatchery-to-retail documentation capabilities.
Pricing Analysis
The customization-premium spread between standard USDA Process Verified certification and EU dual-certified product lines runs 18-30% at wholesale, with pasture-based Brazilian beef commanding the upper bound. Three-tier pricing structure across premium, standard, and economy levels stratifies by verification intensity: no-antibiotics-ever claims with blockchain documentation capture top positioning, while reduced-antibiotic transitional products occupy mid-market slots. Pricing pressure stems from feed input cost volatility in soybean meal markets, compressing grower margins despite stable retail premiums. Restaurant procurement departments show least price sensitivity due to menu storytelling value, whereas family segment buyers concentrate demand in promotional periods.
Supply Chain Analysis
Inventory lead times for antibiotic-free beef extend 45-60 days beyond conventional product due to dedicated cold chain segregation requirements and prior-load documentation protocols. Geographic supply concentration centers on the United States, Brazil, and Australia, with Mato Grosso pasture systems and Georgia poultry operations anchoring export volume. Raw material dependencies draw from non-medicated feed formulations, veterinary audit services concentrated in Iowa and São Paulo, and specialized air filtration equipment for biosecurity conversion. Single-source vulnerability in third-party certification capacity creates inspection backlogs that delay market entry. Distribution runs through vertically integrated processor networks for retail and foodservice, with direct-to-consumer subscription platforms bypassing conventional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
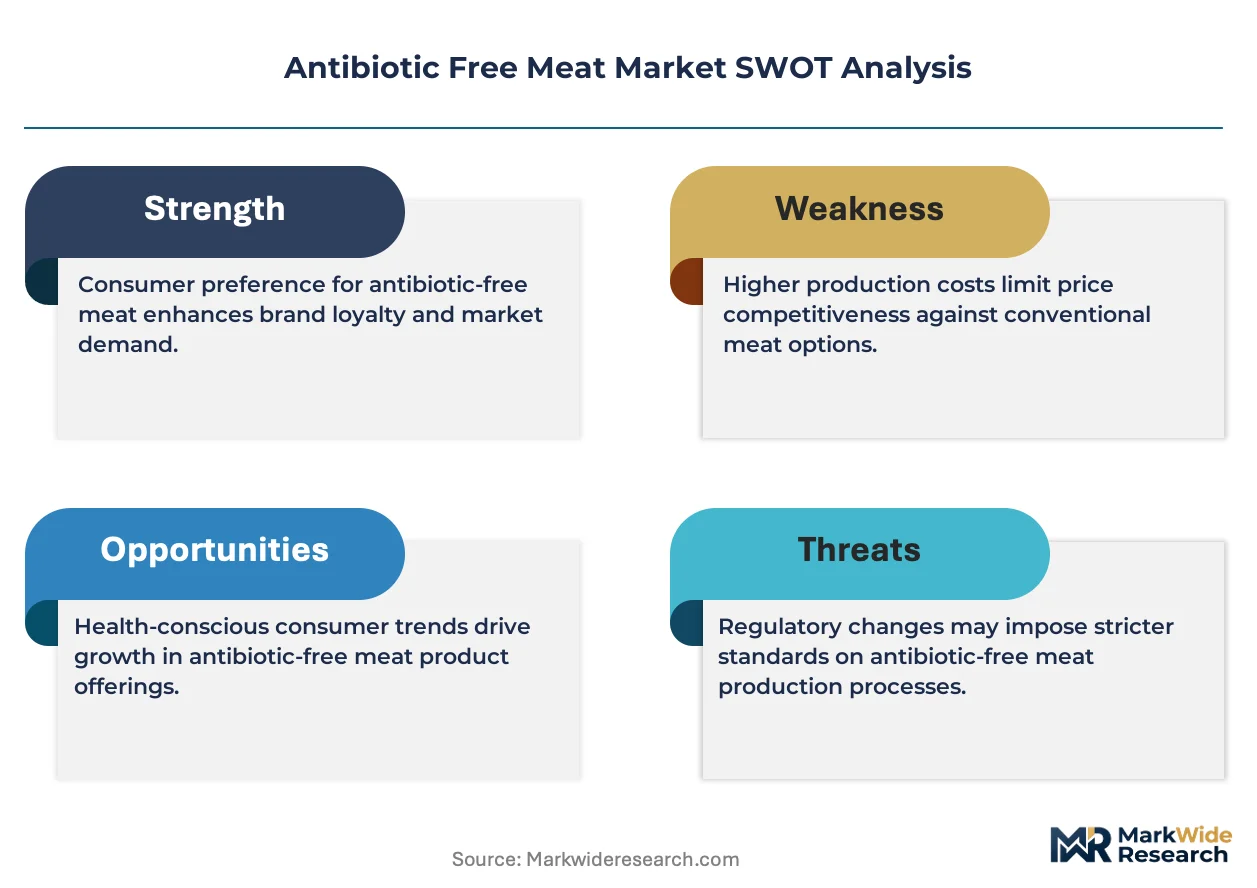
The antibiotic-free meat market operates as a defensive-moat story where regulatory entrenchment through USDA Process Verified Program certification creates switching costs that lock in institutional foodservice contracts and resist price-based displacement.
For Market Incumbents: Compound certification advantages by acquiring veterinary audit firms in Texas and São Paulo to internalize compliance capabilities and eliminate third-party bottlenecks. Expand dedicated processing capacity in Mato Grosso and Queensland to capture EU export demand acceleration. Cell-cultured protein substitutes represent the primary substitution threat requiring monitoring through precision fermentation partnership stakes. For New Entrants and Emerging Players: USDA Process Verified Program fast-track certification enables market entry through online retail subscription channels that bypass supermarket slotting fees and capture full retail margin. White-space targets concentrate in heritage breed pork and lamb segments where supply constraints prevent incumbent scale advantages. Direct-to-consumer monthly meat box models offer the most penetrable go-to-market angle, leveraging ButcherBox logistics templates for regional ranch network aggregation. For Investors and Strategic Acquirers: Mid-scale regional processors with certified ranch partnerships in underpenetrated species categories represent the primary acquisition target archetype for portfolio diversification. Long-term viability hinges on regulatory divergence between EU and US residue standards creating dual-certification premiums. Monitor EU Green Deal farm-to-fork implementation velocity as the critical inflection signal for Brazilian and Australian export volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hatchery Operations | Tyson Foods controls no-antibiotics-ever documentation from genetic stock through retail case. |
| EU Dual-Certification Acquisition | Australian lamb processors capture German retail premium through EFSA-aligned residue protocols. |
| Blockchain Chain-of-Custody Implementation | USDA Process Verified Program expansion reduces audit costs for mid-size ranch networks. |
| Direct-to-Consumer Subscription Launch | Porter Road demonstrates monthly meat box economics sustaining regional producer margins. |
| CRISPR Disease Resistance Partnership | Gene-edited livestock lines shorten payback periods for antibiotic-free protocol conversion. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with supply chain directors at protein processors, veterinary compliance officers, foodservice procurement managers, and retail category buyers; and secondary validation through USDA Process Verified Program audit records, FDA veterinary feed directive filings, ANVISA residue monitoring reports, and EU EFSA maximum residue limit documentation. Bottom-up triangulation aggregated grower conversion rates and processing capacity utilization by facility, while top-down cross-checks applied macro-level protein consumption trends and certification penetration rates across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by species type, certification tier, distribution channel, and buyer archetype. CAGRs were derived from trend extrapolation of grower conversion economics and institutional procurement contract velocity. Industry-specific forecast inputs incorporated feed cost index trajectories and EU Green Deal implementation schedules for agricultural antimicrobial reduction targets.
Underlying assumptions cover stable regulatory enforcement of antibiotic-free claims, with deviation risk concentrated in residue testing protocol fragmentation between USDA, EU reference laboratories, and private certifiers. Black swan factors include CRISPR regulatory reclassification or feed input commodity price spikes beyond historical volatility bands. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Beef Meat Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Meat Paste Market
Meat Products
Global Duck Meats Market
Meat Products
Bacon Market
Meat Products
North America Canned Meat Market
Meat Products
Beef Tallow Market
Meat Products
Global Red Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Beef Liver Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Meat Products Market
Meat Products
Europe Bacon Market
Meat Products
Poultry Processing Meat Market
Meat Products
Reconstituted Meat Market