
 Processed Seafood and Seafood Processing Equipment Market | 2026-2036
Processed Seafood and Seafood Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Seafood and Seafood Processing Equipment Market Analysis
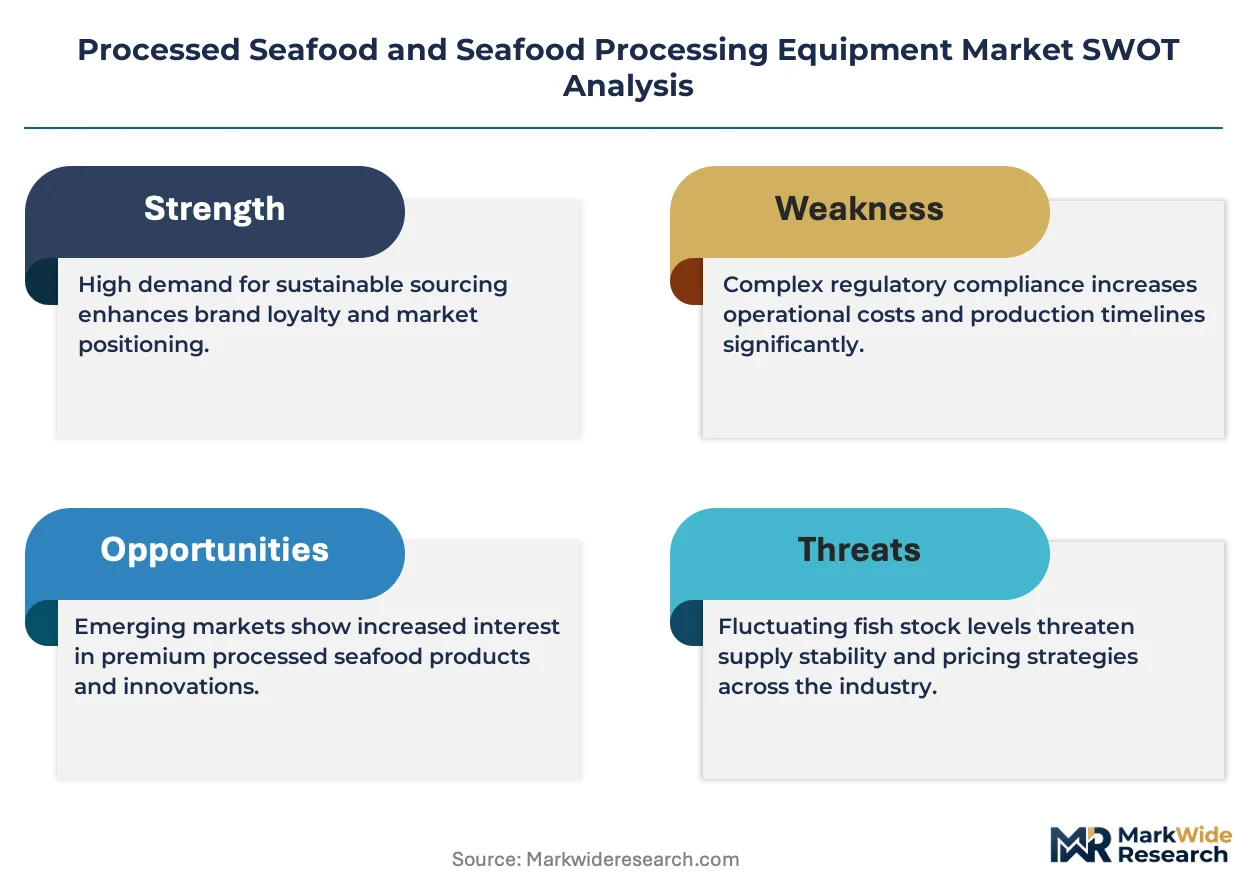
Multi-source procurement from coastal processing hubs is repositioning how equipment buyers contract filleting and refrigeration systems. Marel leverages its Nordic engineering base to sustain technology leadership in automated whitefish processing lines. GEA Group Aktiengesellschaft anchors its portfolio with thermal processing and cooking equipment for high-volume canneries. JBT Corporation competes through integrated freezing and packaging solutions that span crustacean and pelagic species.
Processed seafood and seafood processing equipment encompasses the transformation of raw marine and aquaculture harvests into shelf-stable, frozen, or value-added products through mechanical, thermal, and chemical preservation methods, typically operating at temperatures between minus 40 degrees Celsius for blast freezing and 121 degrees Celsius for retort sterilization. The equipment serves to maximize yield recovery, ensure microbiological safety, and extend distribution reach beyond fresh catch perishability windows. Frozen seafood commands the largest volume position among product types due to its retention of sensory attributes and suitability for distant export markets. Canning technology maintains entrenched demand in regions with limited cold chain infrastructure, while smoking as a processing method is gaining premium positioning in European retail and food service channels. Filleting machines represent the most capital-intensive equipment category, with margin pools concentrating among suppliers offering species-specific blade configurations and yield optimization software.
The FDA's Seafood Hazard Analysis Critical Control Point regulation mandates pathogen controls and supplier verification for all seafood processors distributing in the United States. The EU's EFSA and DG SANTE enforce maximum residue limits for histamine and heavy metals, directly shaping import eligibility and processing standards for third-country suppliers. Japan's METI and Food Sanitation Act impose additional testing protocols that filter market access for frozen and dried product entrants. Stakeholders must monitor how cumulative compliance burdens across these jurisdictions influence equipment specification priorities and facility location decisions.
Market Dynamics
EU DG SANTE traceability mandates are forcing processing facilities to retrofit legacy lines with integrated data-capture systems, compressing equipment replacement cycles and favoring vendors with modular upgrade architectures.
Growth Catalysts
- EU Common Fisheries Policy reform:Tightened import documentation requirements are accelerating investments in blockchain-enabled traceability modules across Vietnamese and Thai processing clusters.
- Blast freezing at minus 40 degrees Celsius:Cold chain infrastructure expansion in Indonesia and Philippines is pulling demand for high-capacity plate freezers and IQF tunnels.
- Retail private-label expansion:Southeast Asian supermarket chains are building captive processing capacity, directly contracting equipment for whitefish and shrimp value-added lines.
Market Restraints
- Energy cost volatility:Thermal processing and refrigeration equipment faces margin pressure from natural gas and electricity price swings in European coastal zones.
- Yield optimization software concentration:Species-specific blade configuration algorithms remain concentrated among Nordic engineering suppliers, limiting procurement options for mid-scale Asian processors.
- Histamine testing protocols:Japan's Food Sanitation Act imposes additional analytical burdens that filter market access for smaller Vietnamese canned tuna exporters.
Strategic Opportunities
- Smoked seafood premiumization:European retail and food service channels are creating white space for small-batch smoking equipment with precise humidity and temperature control.
- Cannery automation in Africa:Limited cold chain infrastructure in West African markets sustains demand for retort sterilization systems operating at 121 degrees Celsius.
- PLI scheme alignment:India's production-linked incentive framework for food processing offers capital subsidy pathways for seafood equipment localization.
Industry Challenges
- Species-specific blade engineering talent:Filtration machine programming for yield optimization requires scarce cross-trained technicians fluent in both marine biology and automation protocols.
- Multi-jurisdiction compliance stacking:Simultaneous FDA HACCP, EU EFSA residue limits, and METI testing protocols create documentation bottlenecks extending facility commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Seafood and Seafood Processing Equipment Market |
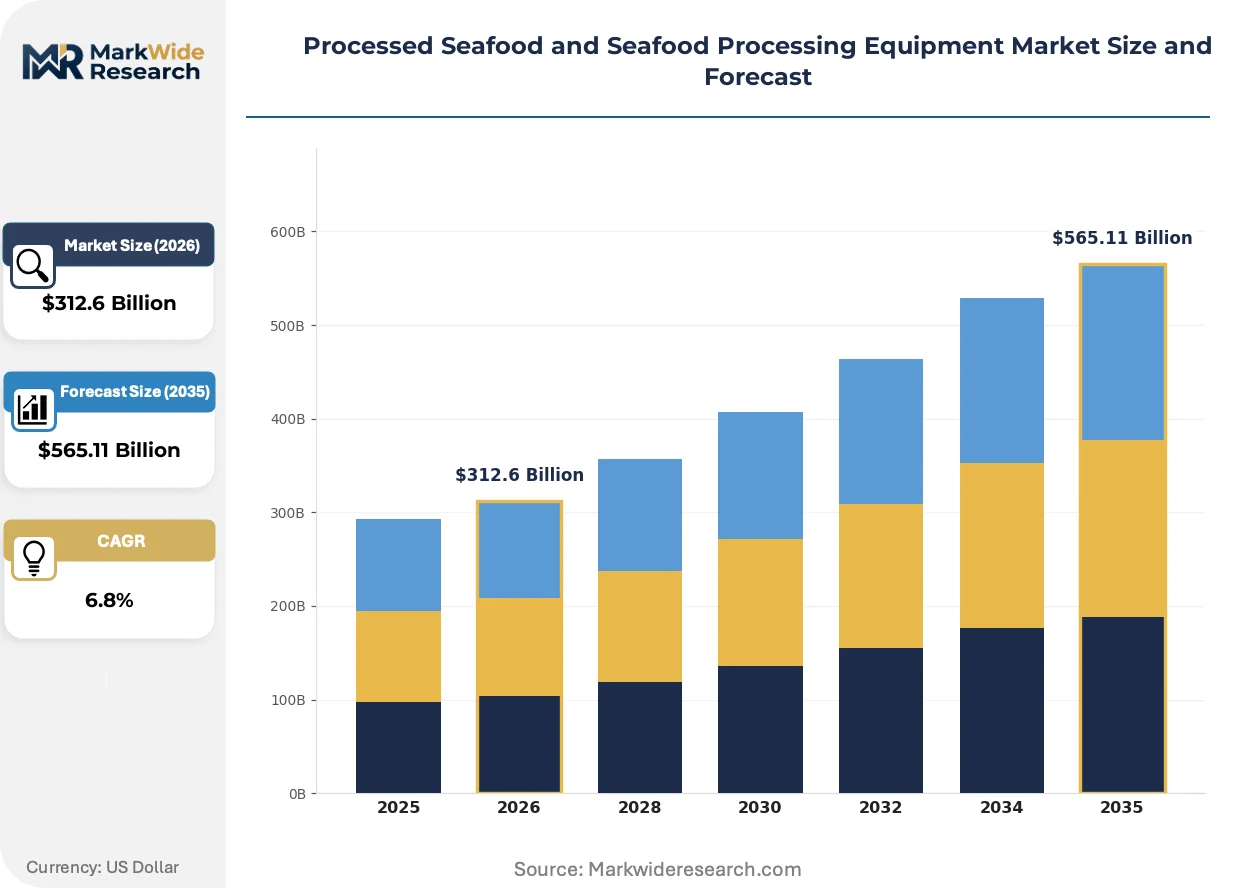
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Seafood, Smoked Seafood, Frozen Seafood, Dried Seafood Processing Technology: Freezing, Salting, Smoking, Canning End User: Retailers, Restaurants, Food Service, Distributors Equipment Type: Filleting Machines, Cooking Equipment, Packaging Machines, Refrigeration Units |
| Companies Covered | BAADER Group, Marel, GEA Group Aktiengesellschaft, JBT Corporation, Carsoe Group A/S, CTB Inc, Ross Industries, Key Technology, Peruza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Seafood and Seafood Processing Equipment Market Emerging Trajectories
Automation architectures are compressing labor dependency while sensor density is rewriting maintenance economics across thermal and mechanical processing lines.
Hyperspectral imaging systems for real-time flesh quality assessment are overtaking manual grading stations in high-volume whitefish facilities. Nordic processing cooperatives are deploying these units at line speeds exceeding 200 fillets per minute. The technology is overtaking traditional candling methods by detecting parasites and bruising through skin, eliminating downstream rework and premium downgrades.
REACH chemical restrictions on processing aids are forcing reformulation of brines and glazing solutions used in frozen seafood preservation. ECHA substance evaluations are targeting phosphates and sulfites common in shrimp processing. European importers are responding by qualifying enzyme-based alternatives and clean-label dipping protocols that satisfy retailer sustainability scorecards.
Consolidated procurement by retail chains is compressing vendor counts and unbundling after-sales service contracts. Southeast Asian supermarket groups now specify equipment with remote diagnostics capability and penalize downtime through liquidated damages clauses. Vietnam's Mekong Delta processing cluster exhibits the most aggressive contract terms, with buyers demanding 48-hour spare parts availability guarantees.
Processed Seafood and Seafood Processing Equipment Market Segmentation
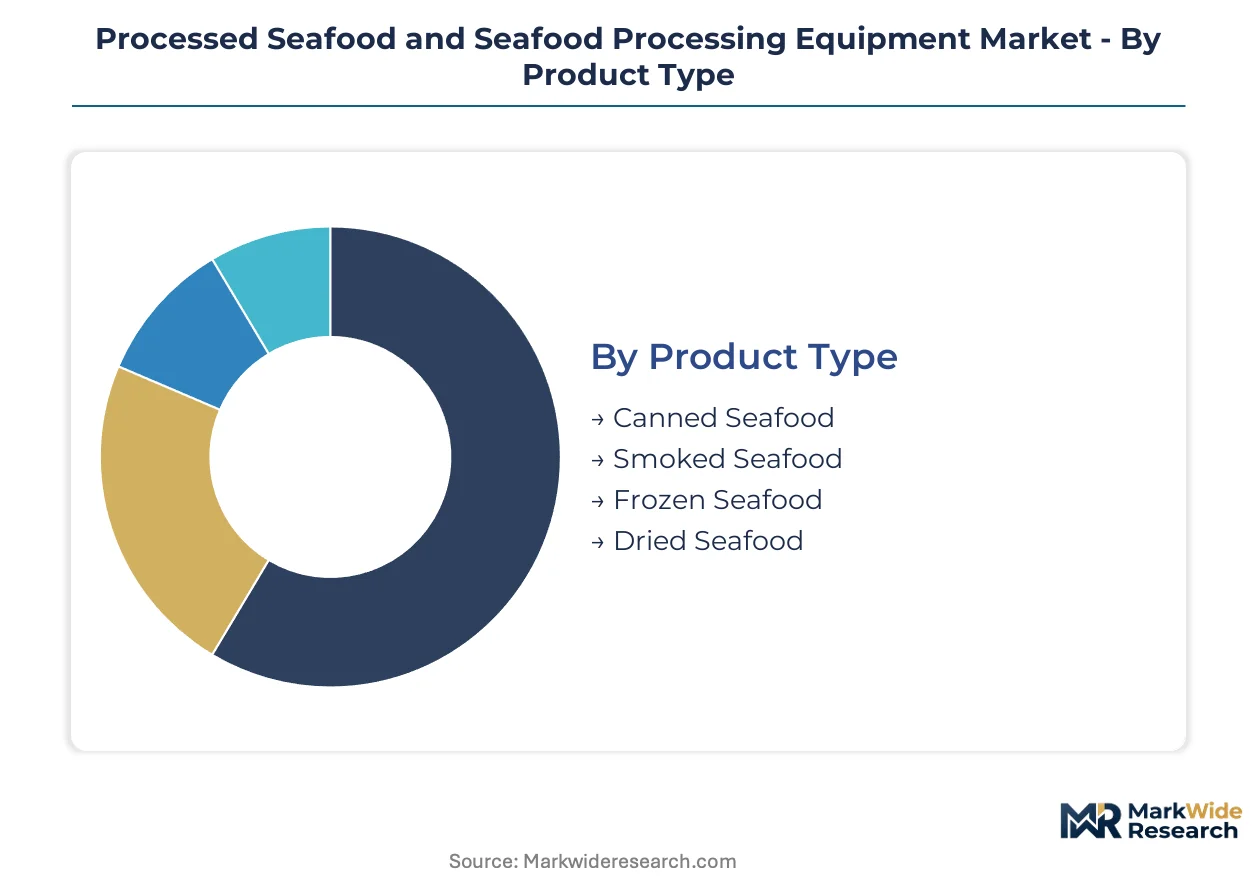
Equipment buyers and seafood processors navigate procurement through distinct technical and commercial lenses. Product form factors dictate preservation chemistry and cold chain requirements. Processing technologies separate capital-intensive automation from labor-dependent traditional methods.
Product Type:
Standardization dominates shelf-stable formats while frozen lines demand species-specific customization for yield recovery.
- Frozen Seafood:Blast freezing at minus 40 degrees Celsius preserves cellular structure for distant export markets. Vietnamese Mekong Delta processors concentrate demand here, driven by EU DG SANTE traceability mandates requiring integrated data-capture compatibility.
- Canned Seafood:Retort sterilization at 121 degrees Celsius delivers ambient stability where cold chains fail. Thai and Indonesian canneries anchor volume, constrained by Japan's Food Sanitation Act histamine testing protocols that filter smaller exporters.
- Smoked Seafood:European retail channels drive premium positioning through precise humidity-controlled small-batch equipment.
- Dried Seafood:Traditional sun-drying and mechanical dehydration serve East Asian ingredient markets with minimal capital requirements.
Leading the category by volume: Frozen Seafood. Expanding most quickly: Smoked Seafood.
Processing Technology:
Capital intensity separates thermal processing from mechanical preservation, with automation penetration varying by labor cost structures.
- Freezing:IQF tunnels and plate freezers represent the highest equipment spend per ton of throughput. Indonesian cold chain expansion pulls demand, though energy cost volatility in European coastal zones compresses margins.
- Canning:Retort systems maintain entrenched demand in West African markets with limited refrigeration infrastructure.
- Smoking:Clean-label enzyme-based alternatives to phosphate brines are qualifying under ECHA REACH restrictions.
- Salting:Low-barrier entry preserves artisanal scale, concentrated in Mediterranean and East Asian traditional supply chains.
Dominant by installed base: Freezing. Steepest expansion trajectory: Smoking.
End User:
Procurement scale and technical specification authority diverge sharply across buyer types.
- Retailers:Southeast Asian supermarket chains are building captive processing capacity with unforgiving contract terms. Vietnam's buyers demand 48-hour spare parts guarantees and remote diagnostics capability, penalizing downtime through liquidated damages.
- Food Service:Whitefish and shrimp value-added lines concentrate specification power with QSR chains and contract caterers.
- Restaurants:Premium positioning drives small-lot procurement of smoked and specialty dried products.
- Distributors:Consolidated procurement compresses vendor counts across frozen and canned bulk formats.
Controlling largest procurement volumes: Retailers. Gaining specification authority fastest: Food Service.
Equipment Type:
Yield optimization software concentration creates procurement bottlenecks for mid-scale processors seeking species-specific blade configurations.
- Filleting Machines:Species-specific blade engineering with yield optimization algorithms commands premium pricing. Nordic engineering suppliers dominate, limiting options for Asian processors seeking alternatives to Marel configurations.
- Refrigeration Units:High-capacity plate freezers and blast freezing systems anchor cold chain infrastructure builds. Philippines and Indonesia exhibit strongest pull, constrained by natural gas and electricity price swings.
- Cooking Equipment:Thermal processing lines for canneries operate at 121 degrees Celsius with integrated retort sterilization.
- Packaging Machines:Integrated freezing-to-packaging solutions span crustacean and pelagic species handling.
Highest capital intensity: Filleting Machines. Fastest replacement cycles: Refrigeration Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Barents Sea whitefish harvests anchor Nordic processing infrastructure, while Mekong Delta aquaculture operations feed Southeast Asian equipment demand. Cold chain investments in Indonesia and Philippines reshape procurement patterns across equatorial zones.
Vietnam
Mekong Delta shrimp and pangasius processing clusters drive equipment procurement for blast freezing and IQF tunnel systems. The country's Ministry of Agriculture and Rural Development enforces EU-aligned traceability standards through blockchain-enabled export documentation. Ho Chi Minh City processing zones concentrate demand for automated filleting lines with yield optimization software.
Indonesia
Archipelagic distribution challenges pull investment into compact, high-capacity plate freezers for island-based canneries. The national food and drug regulator mandates HACCP compliance for all seafood exporters targeting Japanese markets. Bitung and Makassar harbor zones anchor tuna processing infrastructure with integrated retort sterilization capacity.
Norway
Atlantic cod and haddock landings sustain whitefish processing technology leadership. The Norwegian Food Safety Authority enforces strict residue limits that shape equipment specification for third-country suppliers. Ålesund and Bergen coastal engineering bases concentrate filleting machine R&D and species-specific blade configuration expertise.
Thailand
Shrimp value-added processing and canned tuna canneries anchor dual-equipment demand streams. The country's national food regulator aligns with EU DG SANTE protocols for histamine testing and heavy metal screening. Samut Sakhon processing corridors concentrate private-label capacity for European retail chains.
United States
Alaska pollock and Pacific whiting surimi operations drive high-volume mechanical separation equipment demand. The FDA's Seafood HACCP regulation mandates pathogen controls and supplier verification for all processing facilities. Seattle and Anchorage serve as procurement hubs for North Pacific catcher-processor fleets.
Processed Seafood and Seafood Processing Equipment Market Vendor Landscape
Global majors compete with regional champions across automation intensity and species specialization vectors. Market structure tilts toward consolidated premium-tier suppliers for filleting and freezing equipment, with fragmented competition in thermal processing and packaging ancillaries. Engineering-intensive archetypes dominate yield optimization software, while scale-driven fabricators anchor refrigeration and canning lines. Competitive moves concentrate on modular upgrade architectures and captive service network expansion.
Within the Nordic engineering tier, Marel and BAADER Group exemplify species-specific blade configuration leadership. GEA Group Aktiengesellschaft anchors thermal processing positioning for high-volume cannery applications. JBT Corporation occupies integrated freezing-to-packaging territory spanning crustacean and pelagic handling requirements.
| Leading Market Players |
|---|
| BAADER Group |
| Marel |
| GEA Group Aktiengesellschaft |
| JBT Corporation |
| Carsoe Group A/S |
| CTB Inc |
| Ross Industries |
| Key Technology |
| Peruza |
| Others |
Supply Flow & Price Mechanics
Retail chain consolidation in Southeast Asia concentrates procurement leverage among Vietnamese and Thai supermarket groups, compressing vendor margins and unbundling after-sales service contracts into separately priced modules. Equipment buyers now penalize downtime through liquidated damages clauses, transforming warranty coverage from standard inclusion into a negotiable cost center.
Pricing Analysis
After-sales service unbundling dominates equipment transactions, with remote diagnostics capability and 48-hour spare parts guarantees now priced as premium add-ons. Pricing stratifies across premium, standard, and economy tiers based on yield optimization software sophistication and EU DG SANTE traceability compliance certification. Pricing pressure stems from energy cost volatility in European coastal zones, compressing margins on thermal processing lines. Mid-scale Asian processors exhibit highest price sensitivity due to limited alternatives to Nordic-engineered filleting configurations.
Supply Chain Analysis
Workforce scarcity for cross-trained technicians fluent in marine biology and automation protocols constrains production scaling in Ålesund, Bergen, and Ho Chi Minh City engineering bases. Equipment manufacturing concentrates in Norway, Denmark, and Vietnam, drawing from stainless steel alloys, precision servo motors, and food-grade polymer components. Single-source vulnerability in species-specific blade algorithm suppliers creates procurement bottlenecks. Distribution runs through captive service networks with regional spare parts depots anchoring aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EU DG SANTE traceability mandates erect barrier-to-entry moats favoring processors with blockchain-enabled documentation systems already deployed.
For Market Incumbents: Extend modular upgrade architectures to capture retrofit demand from Vietnamese facilities facing compressed replacement cycles. Deepen captive service network density in Mekong Delta processing corridors to lock in multi-year maintenance contracts. Threat substitution from hyperspectral imaging suppliers demands accelerated R&D in real-time flesh quality assessment integration. For New Entrants and Emerging Players: Begin with small-batch smoking equipment for European premium retail channels, where precise humidity control requirements remain underpenetrated by scaled incumbents. Target West African cannery automation where retort sterilization demand outstrips established supplier presence. Qualify enzyme-based brine alternatives under ECHA REACH restrictions as clean-label entry wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor yield optimization software specialists with species-agnostic platform architectures in Nordic engineering clusters. Long-term viability hinges on regulatory compliance automation as persistent value driver. Watch Japan METI testing protocol expansion as inflection signal for filtration equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | EU DG SANTE compliance mandates accelerate Vietnamese processor retrofit investments. |
| Yield Optimization Software Licensing | Species-agnostic algorithms displace Nordic-engineered blade configurations in Asian markets. |
| Hyperspectral Imaging Deployment | Real-time parasite detection eliminates manual candling at line speeds exceeding 200 fillets per minute. |
| Enzyme-Based Brine Reformulation | ECHA REACH restrictions on phosphates pull clean-label alternatives into shrimp processing. |
| Captive Cold Chain Infrastructure | Indonesian archipelagic distribution challenges drive compact plate freezer demand. |
Methodological Framework
Document review covered customs and trade data, SEC filings from listed equipment manufacturers, EU regulatory submissions, and industry association reports, complemented by interviews with plant engineers at Vietnamese processing facilities, procurement leads at Southeast Asian retail chains, aftermarket service heads at Nordic engineering suppliers, and regulatory affairs specialists at Thai cannery operations. Bottom-up triangulation across facility-level capacity data and top-down validation against trade flow statistics anchored volume estimates.
Cross-referencing historical equipment shipment patterns against panel input from procurement executives established baseline growth trajectories across the projection horizon. Segmentation modeling spanned product form factors, processing technology categories, equipment types, and end-user procurement scale tiers. CAGRs derived from slope consensus across multiple scenario assumptions, with cold chain infrastructure buildout rates and regulatory compliance deadline schedules serving as primary forecast inputs.
Regulatory enforcement intensity shifts, energy price volatility spikes, and supply chain disruptions for precision automation components are the dominant revision risks to modeled outputs. Material deviation in named triggers warrants pause and re-evaluation of facility location and equipment specification assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Organic Shrimp Market
Seafood
Crayfish Market
Seafood
Salmon Fish Market
Seafood
Sea Bream Market
Seafood
Striped Bass Market
Seafood
Fish Oil Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Fish Powder Market
Seafood
Europe Salmon Market
Seafood
Groundfish Market
Seafood
Global Commercial Fishing Market
Seafood
Global White Shrimp Market
Seafood
Europe Dried Scallop Market
Seafood
Saudi Arabia Seafood Market
Seafood
Fish Protein Concentrate Market
Seafood
Europe Shrimp Market