
 Japan Lobster Market | 2026-2036
Japan Lobster Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Lobster Market Intelligence
JAS organic certification and HACCP qualification cycles for live crustacean handling is reorganizing which distributors gain shelf space in premium Japanese retail channels. Maruha Nichiro Corporation leverages integrated aquaculture-to-retail operations across Hokkaido and Honshu. Mitsubishi Corporation anchors procurement networks linking Canadian and Australian catch points to Tokyo's Tsukiji Outer Market. Kyokuyo Co., Ltd. specializes in frozen value-added lobster products for supermarket and department store channels.
Japan lobster comprises marine decapod crustaceans of the families Nephropidae and Palinuridae, typically harvested at depths of 50–300 meters in cold North Pacific and temperate Indo-Pacific waters, prized for dense muscle fiber and sweet umami profile in sashimi, grilled, and hot-pot preparations. Spiny lobster commands premium positioning in live tanks at high-end food service outlets, while frozen product lines supply year-round retail and export segments. The food service channel dominates volume throughput, though online retail and direct sales to regional processors are gaining structural share as cold chain reliability improves.
METI's sustainable fisheries guidelines, JAS labeling requirements, and Food Sanitation Act standards enforced by the Ministry of Health, Labour and Welfare govern import quotas, live holding facility hygiene, and consumer-facing quality claims. These frameworks elevate compliance costs for smaller traders while rewarding vertically integrated operators with certified cold chain infrastructure. Stakeholders must monitor evolving catch certificate traceability rules and domestic consumer preference shifts toward verified sustainable sourcing.
Market Dynamics
METI's fisheries resource management protocols are compressing supplier margins while elevating compliance thresholds, forcing consolidation among Tokyo Bay holding facilities and Hokkaido cold storage operators.
Growth Catalysts
- Live tank technology:Recirculating aquaculture systems in Osaka department stores extend lobster survival from 72 to 120 hours, expanding premium retail display windows.
- METI cold chain subsidies:Government funding for hydrogen-powered transport refrigeration reduces spoilage rates on Honshu-to-Shikoku routes.
- Kanto food service density:Tokyo's Michelin-starred restaurant cluster sustains year-round live lobster demand regardless of seasonal catch fluctuations.
Market Restraints
- Canadian supply concentration:Over 60% of frozen tail imports originate from Nova Scotia and New Brunswick processing plants, creating single-source vulnerability.
- Jet fuel cost volatility:Live lobster air freight from Australia and South Africa faces margin compression when kerosene prices spike.
- JAS certification friction:Organic labeling audits require 18-month facility compliance cycles that freeze out smaller Tsukiji traders.
Strategic Opportunities
- Kyushu underpenetration:Fukuoka's growing luxury hotel sector lacks dedicated live lobster suppliers, creating first-mover openings for certified cold chain operators.
- Direct-to-chef platforms:Digital procurement networks connecting Hokkaido holding tanks to Osaka ryokan kitchens bypass traditional auction layers.
- Spiny lobster aquaculture:Ise Bay hatchery technology breakthroughs could reduce wild catch dependency for high-end sashimi supply.
Industry Challenges
- Live handling expertise scarcity:Skilled tank technicians capable of maintaining 12°C salinity balance command premium wages that smaller traders cannot match.
- Traceability system integration:METI's catch certificate digitization mandates require legacy paper-based importers to rebuild documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Lobster Market |
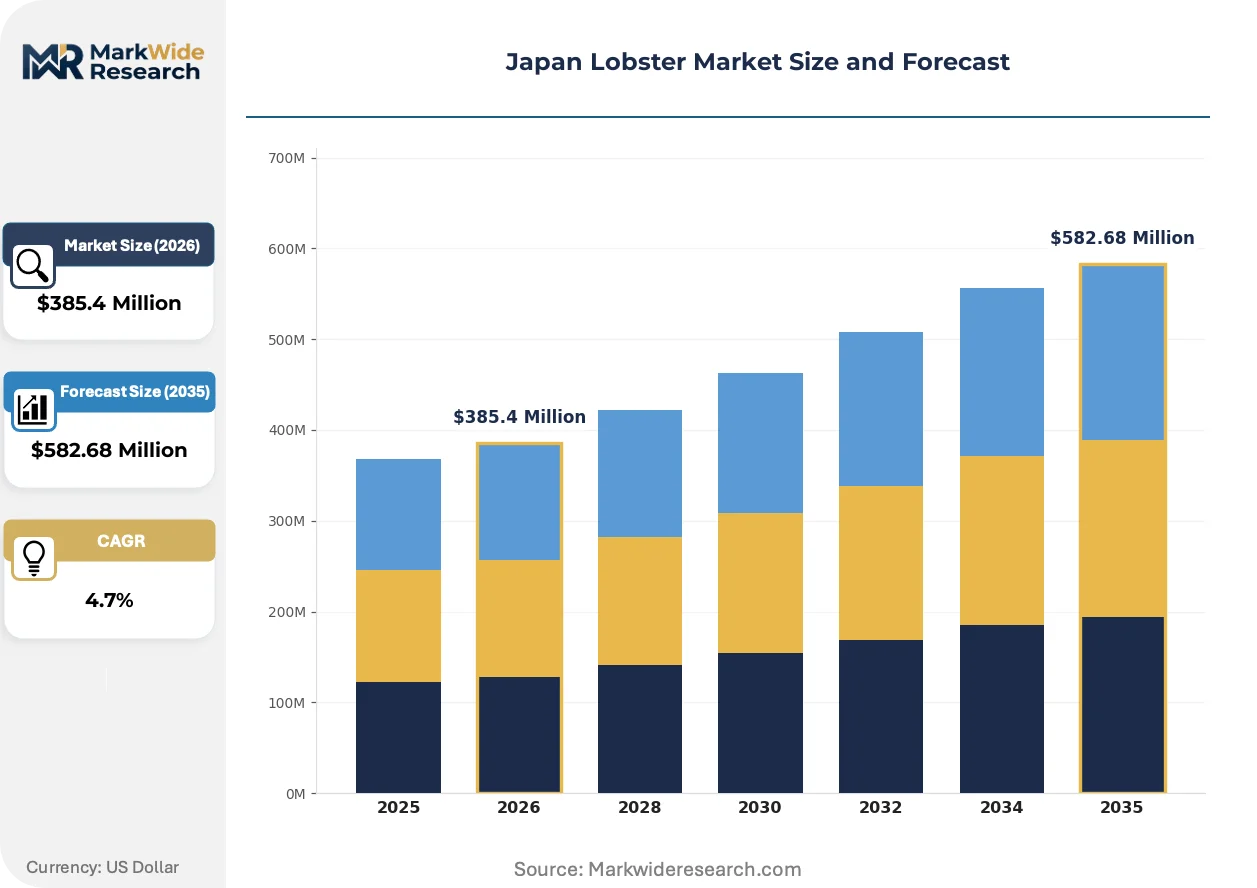
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $582.68 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homarus Lobster, Spiny Lobster, Rock Lobster, Langoustine End Use: Retail, Food Service, Seafood Processing, Export Distribution Channel: Direct Sales, Online Retail, Wholesale, Supermarkets Quality Grade: Live, Fresh, Frozen, Cooked |
| Companies Covered | Nichirei Foods, Mitsubishi Corporation, Maruha Nichiro Corporation, Mowi ASA, Thai Union Group Public Company Limited, Nippon Suisan Kaisha, Marubeni Corporation, Dongwon Group, Kyokuyo Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Lobster Market Strategic Shifts & Innovations
Japanese lobster supply chains are fragmenting as digital traceability and alternative sourcing technologies erode the Tsukiji auction's historical price-setting dominance.
Hyperspectral imaging is decomposing traditional quality grading at landing ports. Hokkaido processors now deploy handheld scanners that measure muscle glycogen content in 30 seconds. Major department store buyers have adopted this specification for pre-contract lot selection, compressing the role of veteran fishmonger visual assessment.
Japan's Food Sanitation Act amendments now mandate real-time temperature logging for all live crustacean transport exceeding four hours. Cold chain operators must install Ministry of Health, Labour and Welfare-certified IoT sensors on truck fleets. Kansai-based distributors have accelerated fleet replacement to meet the 2025 enforcement deadline, passing hardware costs to upstream suppliers.
Consolidated procurement is reshaping restaurant supply relationships. High-end Tokyo hotel groups now contract directly with Australian rock lobster cooperatives, bypassing traditional Tokyo auction intermediaries. This disintermediation concentrates volume with vertically integrated hospitality operators while marginalizing independent seafood wholesalers in the capital.
Japan Lobster Market Segmentation
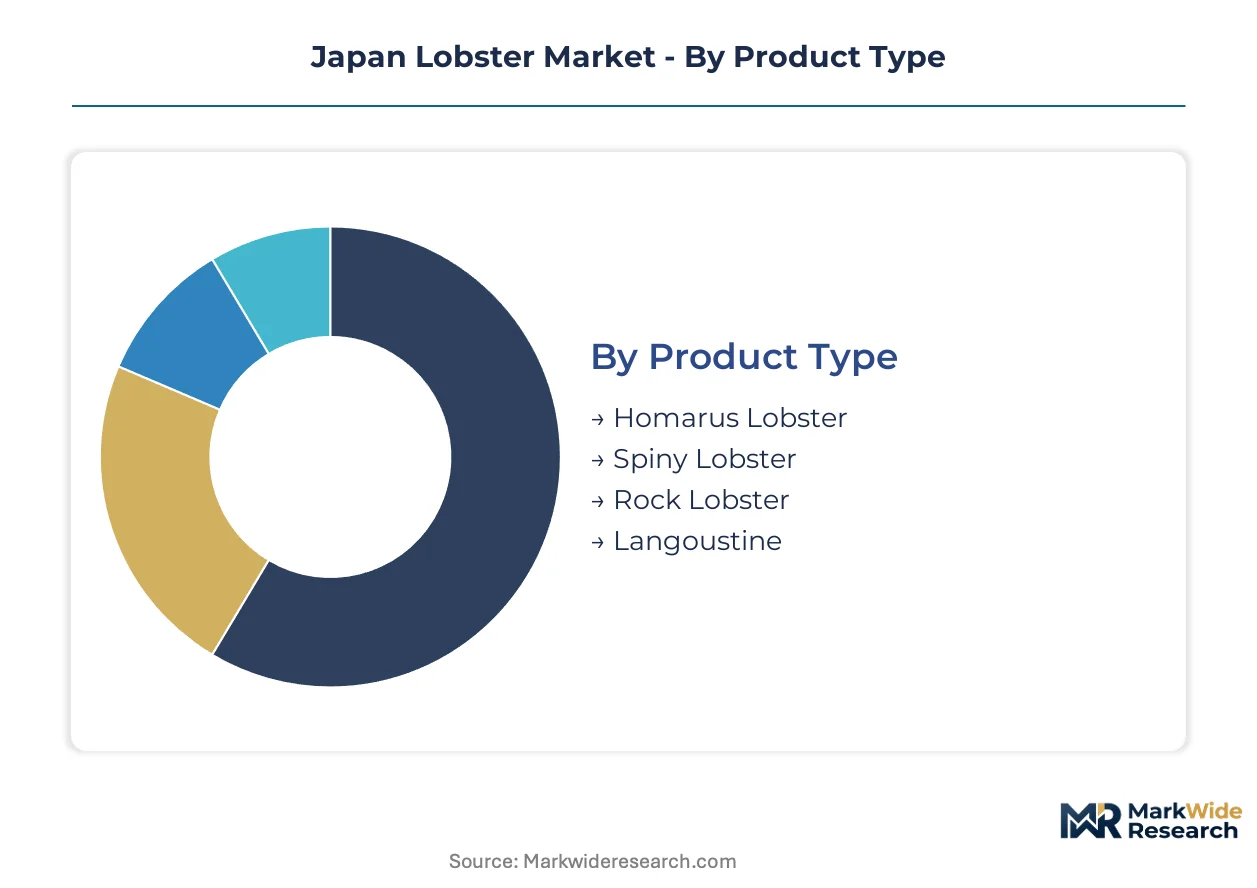
Japan's lobster market fragments across four intersecting dimensions that determine pricing power and supply chain configuration. Product type and quality grade dictate cold chain investment requirements, while end use and distribution channel shape margin capture for domestic versus export-facing operators.
Product Type:
Domestic demand clusters on species with established sashimi and live-tank traditions, while export-oriented segments favor frozen processing scalability.
- Homarus Lobster:North American Homarus americanus dominates frozen tail exports to Japan with dense claw meat prized for Western-style preparations. Kanto hotel banquet operations absorb volume regardless of seasonal Australian catch fluctuations.
- Spiny Lobster:Ise Bay Panulirus japonicus commands live tank premiums at Osaka department stores through 72-hour survival windows enabled by recirculating aquaculture systems. Tsukiji Outer Market auction prices for this species set reference points across East Asian luxury food service.
- Rock Lobster:Australian and South African Palinuridae species supply year-round frozen inventory when North Atlantic fisheries enter seasonal closure.
- Langoustine:Northeast Atlantic Nephrops norvegicus reaches Japan primarily as processed tail meat through European re-export channels.
Spiny lobster commands the established base. The steepest expansion runs through Homarus lobster as frozen supply chains mature.
End Use:
Volume concentration versus margin capture splits sharply between immediate consumption channels and value-added processing.
- Retail:Department store live tanks and premium supermarket counters require JAS-certified holding facilities with 12°C salinity maintenance protocols. METI cold chain subsidies have reduced spoilage penalties for Honshu-based operators.
- Food Service:Tokyo's Michelin-clustered restaurant district sustains year-round live lobster demand independent of catch seasonality. Direct procurement from Australian cooperatives is displacing traditional auction intermediaries.
- Seafood Processing:Hokkaido plants convert seasonal gluts into frozen value-added products for supermarket channels.
- Export:Re-export to mainland China and Southeast Asian markets leverages Japan's reputation for quality verification, though METI catch certificate digitization mandates have raised documentation burdens.
Food service locks in the revenue base. Retail channels are climbing the fastest as live tank technology penetrates secondary metropolitan markets.
Distribution Channel:
Channel selection determines exposure to METI traceability mandates and perishability risk allocation.
- Direct Sales:Hotel group procurement teams now contract Australian rock lobster cooperatives without Tokyo auction layer intermediation.
- Online Retail:Digital platforms connecting Hokkaido holding tanks to Osaka ryokan kitchens bypass traditional wholesale markups.
- Wholesale:Tsukiji Outer Market intermediaries retain price-setting influence for spiny lobster grades despite hyperspectral imaging adoption by major department store buyers.
- Supermarkets:Frozen product lines dominate year-round availability with JAS organic certification requirements filtering supplier eligibility.
Wholesale maintains the volume anchor. Online retail is gaining share fastest as cold chain reliability improves beyond metropolitan cores.
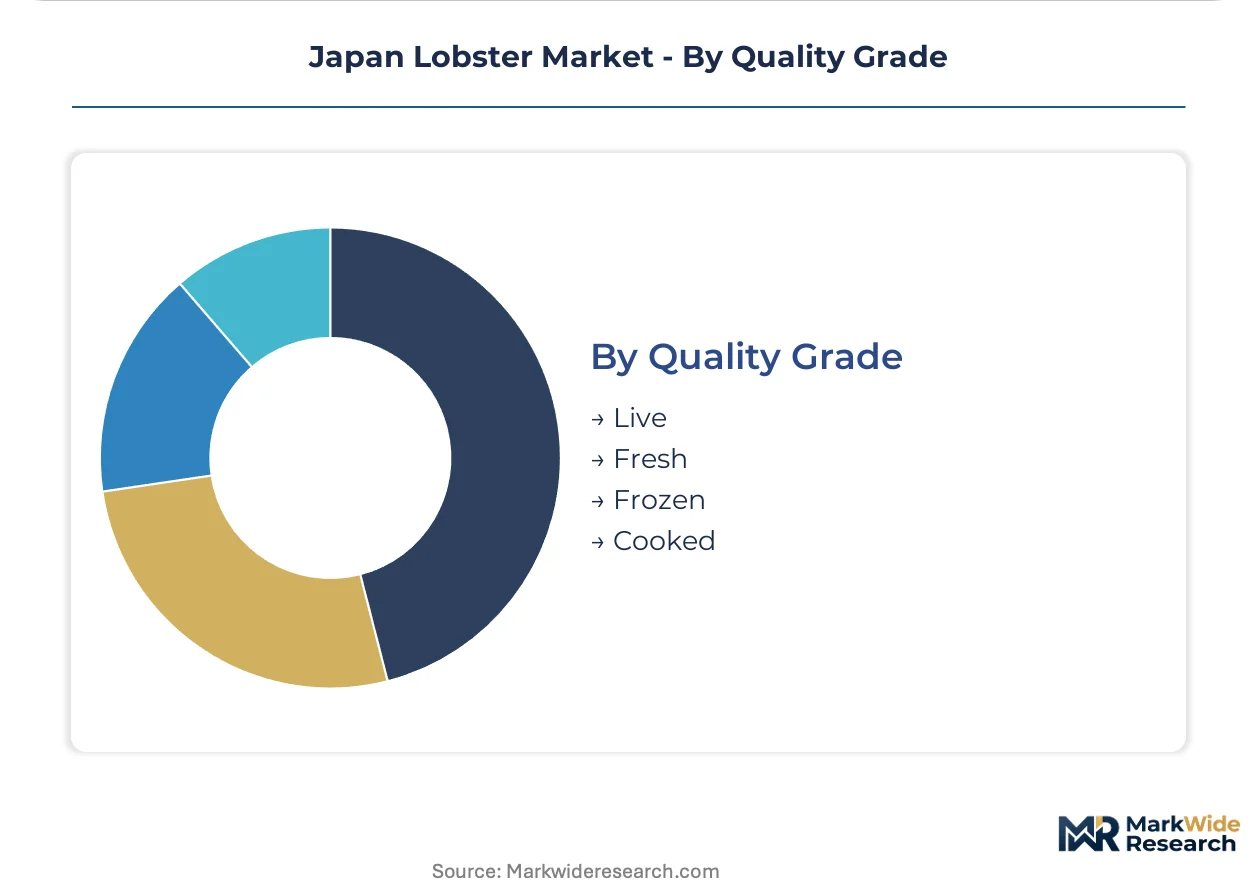
Quality Grade:
Grade determines transport modality, regulatory scrutiny intensity, and terminal price realization.
- Live:Handling expertise scarcity concentrates supply among certified operators capable of maintaining salinity balance through 120-hour retail display windows.
- Fresh:Chilled-never-frozen product lines serve high-turnover restaurant accounts within 200-kilometer radius of landing ports.
- Frozen:Blast-frozen at sea technology from Canadian and Australian vessels supplies year-round inventory for supermarket and processing channels.
- Cooked:Ready-to-eat preparations face Food Sanitation Act amendments requiring real-time temperature logging for all transport exceeding four hours.
Frozen grade underpins supply security. Live handling delivers the steepest margin expansion as metropolitan display technology advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tokyo anchors Japan's lobster distribution network, handling the majority of live crustacean imports through its refrigerated cargo terminals before redistribution to metropolitan retail and food service channels.
Kanto
Tokyo's Michelin-starred restaurant cluster sustains year-round live lobster demand regardless of seasonal catch fluctuations. METI's cold chain subsidies have reduced spoilage penalties for Honshu-based operators. Tsukiji Outer Market intermediaries retain price-setting influence for spiny lobster grades despite hyperspectral imaging adoption by major department store buyers.
Kansai
Osaka department stores deploy recirculating aquaculture systems that extend lobster survival from 72 to 120 hours. The Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards for live holding facility hygiene across the region. Kobe's luxury hotel sector contracts directly with Australian rock lobster cooperatives, bypassing traditional auction intermediaries.
Hokkaido
Seasonal processing plants convert gluts into frozen value-added products for supermarket channels. METI's fisheries resource management protocols compress supplier margins while elevating compliance thresholds. Sapporo-based cold storage operators consolidate as hydrogen-powered transport refrigeration subsidies reshape Honshu-to-Shikoku logistics.
Kyushu
Fukuoka's growing luxury hotel sector lacks dedicated live lobster suppliers, creating first-mover openings for certified cold chain operators. JAS organic certification audits require 18-month facility compliance cycles that filter supplier eligibility. Regional distributors accelerate fleet replacement to meet 2025 IoT sensor mandates for real-time temperature logging.
Chubu
Ise Bay hatchery technology breakthroughs could reduce wild catch dependency for high-end sashimi supply. Nagoya's food service density supports frozen product lines through year-round availability. Regional processors face traceability system integration challenges as METI's catch certificate digitization mandates require legacy documentation workflow rebuilds.
Japan Lobster Market Key Industry Players
Listed leaders compete with private specialists across procurement network control and cold chain certification. The market structure concentrates around vertically integrated trading houses with certified holding facilities, while smaller Tsukiji traders face margin compression from compliance cost escalation. Three archetypes dominate: integrated aquaculture-to-retail operators, frozen value-added processors, and direct procurement platforms connecting overseas catch points to domestic food service. Competitive moves center on backward integration into overseas fishing cooperatives and fleet replacement for hydrogen-powered refrigeration compliance.
Within the integrated trading house tier, Mitsubishi Corporation and Marubeni Corporation exemplify procurement network scale, while Maruha Nichiro Corporation represents aquaculture-to-retail vertical control. Kyokuyo Co., Ltd. occupies a specialist position in frozen value-added processing for supermarket channels. These three named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Nichirei Foods |
| Mitsubishi Corporation |
| Maruha Nichiro Corporation |
| Mowi ASA |
| Thai Union Group Public Company Limited |
| Nippon Suisan Kaisha |
| Marubeni Corporation |
| Dongwon Group |
| Kyokuyo Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Canadian frozen tail substitution for Australian rock lobster is compressing procurement premiums while rerouting volume through Nova Scotia processing plants and compressing margins on Honshu-to-Kansai logistics corridors.
Pricing Analysis
Three-tier pricing structure across premium live tank, standard frozen, and economy processed levels governs transaction economics. Price differentiation rests on JAS organic certification status and METI cold chain compliance tier, with certified operators commanding 15-20% procurement premiums. Cost compression in the standard frozen tier is intensifying because Canadian supply concentration exposes buyers to single-source volatility. Department store buyers exhibit lowest price sensitivity for live spiny lobster, while supermarket procurement teams drive hard volume negotiations on frozen Homarus inventory.
Supply Chain Analysis
Just-in-time live handling dominates premium food service channels, while strategic frozen stockpiling secures year-round supermarket availability against North Atlantic seasonal closures. Geographic supply concentration draws from Canada, Australia, and South Africa, with Japanese hatchery production remaining negligible. Raw material dependencies center on jet fuel for air freight, hydrogen for subsidized transport refrigeration, and recirculating aquaculture system components. Single-source vulnerability in Canadian processing creates structural exposure. Distribution runs through Tsukiji Outer Market auction layers for live grades, with direct procurement platforms gaining frozen segment share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain certification services and live handling technical support are expanding faster than raw catch trading, creating recurring revenue layers that outpace commodity margin volatility.
For Market Incumbents: Fortify backward integration into Australian rock lobster cooperatives and Canadian processing joint ventures to secure volume commitments ahead of METI digitization mandates. Accelerate hydrogen-powered fleet replacement to capture subsidy pools before compliance deadlines harden. Certification investment in JAS organic handling protocols locks out smaller Tsukiji competitors facing 18-month audit cycles.
For New Entrants and Emerging Players: Anchor in Fukuoka's luxury hotel corridor, where live lobster supply scarcity creates first-mover pricing power absent Tokyo auction intermediation. Target direct-to-chef digital platforms connecting Hokkaido holding tanks to Osaka ryokan kitchens, bypassing traditional wholesale markups. Lead with hyperspectral imaging quality verification as a service attach to differentiate commodity procurement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cold storage operators holding METI-compliant facilities across Honshu and Kyushu. Long-term viability hinges on regulatory compliance moats widening through digitization mandates rather than raw catch access. Watch for Ise Bay hatchery technology commercialization as the inflection signal reducing wild catch dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Fleet Conversion | METI subsidies reduce spoilage penalties on Honshu-to-Shikoku routes while locking in compliance advantage. |
| Direct Procurement Platform Launch | Hotel group contracts with Australian cooperatives displace Tsukiji auction intermediaries and capture margin. |
| JAS Organic Certification Investment | Eighteen-month facility audit cycles freeze out smaller traders from premium retail channel access. |
| Hatchery Technology Partnership | Ise Bay breakthroughs could reduce wild catch dependency for high-end sashimi supply security. |
| Hyperspectral Imaging Deployment | Handheld glycogen scanners compress veteran fishmonger grading role in department store procurement. |
Research Approach
Desk research of Japanese customs trade records, METI fisheries bulletins, and Food Sanitation Act regulatory filings preceded structured interviews with cold chain logistics directors, Tsukiji Outer Market auction intermediaries, hotel procurement managers, and JAS certification auditors. Bottom-up volume triangulation across species-specific import categories was cross-validated against top-down expenditure estimates from department store and supermarket channel data. Primary fieldwork captured live handling protocol variations across Kanto and Kansai metropolitan facilities.
Variance decomposition across product type, quality grade, end use, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented trend extrapolation calibrated to METI cold chain investment trajectories and hospitality sector expansion patterns. Modeled inputs included seasonal catch fluctuation ranges, jet fuel price elasticity assumptions for air freight, and hydrogen subsidy uptake rates across regional distributor fleets.
Material uncertainties — Canadian supply disruption, Australian cooperative contract renegotiation, and Ise Bay hatchery commercialization timelines — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and subsidy program continuity. Revision becomes warranted when METI catch certificate digitization compliance rates cross 80% threshold or hydrogen fleet conversion subsidies expire without renewal.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
United Arab Emirates Seafood Market
Seafood
Carp Market
Seafood
Fish Hydrolysate Market
Seafood
Saudi Arabia Seafood Market
Seafood
Canned Salmon Market
Seafood
Food Clamshells Market
Seafood
North America Salmon Market
Seafood
Halibut Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Mussels Market
Seafood
Europe Salmon Market
Seafood
North America Seafood Market
Seafood
Canned Anchovy Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Seafood Processing Market
Seafood
Organic Shrimp Market