
 Fish Hydrolysate Market | 2026-2036
Fish Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Hydrolysate Market Foresight
The EU Green Deal's nutrient management protocols is consolidating procurement standards across North European agriculture. Hofseth BioCare leverages its Norwegian coastal processing infrastructure to supply enzymatically refined hydrolysates for premium aquaculture feeds. Omega Protein anchors Gulf of Mexico menhaden sourcing to sustain volume throughput for agricultural customers. SOPROPECHE competes through specialized cod-derived formulations targeting French organic viticulture.
Fish hydrolysate comprises enzymatically digested marine biomass yielding peptides, free amino acids, and micronutrients in standardized nitrogen profiles, produced through controlled temperature hydrolysis with protease catalysts for plant nutrition and animal feed fortification. Liquid concentrate dominates commercial volumes due to ease of fertigation integration, while dry powder commands margin premiums from greenhouse operators seeking freight-efficient inputs. Bio-stimulants represent the fastest-expanding application channel as European crop growers substitute synthetic growth regulators with marine-derived signaling compounds.
EMA and EFSA frameworks govern animal feed safety thresholds for biogenic amines, while REACH compliance shapes chemical registration pathways for imported hydrolysate formulations. The EU F-Gas Regulation indirectly steers investment toward cold-chain processing alternatives that preserve volatile bioactive fractions. Stakeholders must monitor evolving organic certification criteria from national bodies and aquaculture stewardship councils that will determine market access tiers.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing synthetic fertilizer quotas across North European agriculture, forcing crop growers toward certified marine bio-stimulants and restructuring procurement standards for enzymatically refined inputs.
Growth Catalysts
- REACH-compliant cold-chain processing:The EU F-Gas Regulation redirects capital toward low-temperature enzymatic methods that preserve volatile peptide fractions for premium aquaculture applications.
- Atlantic salmon aquaculture corridor:Norway's concentrated smolt production and on-growing sites generate sustained demand for standardized nitrogen-profile hydrolysates in feed fortification.
- Organic viticulture expansion:French and German vineyard operators are substituting synthetic growth regulators with cod-derived signaling compounds under tightening biostimulant certification protocols.
Market Restraints
- Menhaden supply volatility:Gulf of Mexico fishery quotas and seasonal biomass fluctuations create input cost instability for volume-grade agricultural hydrolysate production.
- Biogenic amine thresholds:EMA and EFSA animal feed safety frameworks impose strict residue limits that complicate formulation standardization and batch release timelines.
- Protease catalyst cost structure:Specialized enzymatic hydrolysis requires temperature-controlled reactor infrastructure that elevates fixed costs versus acid-hydrolysis alternatives.
Strategic Opportunities
- Greenhouse operator dry powder adoption:Freight-efficient solid formulations command margin premiums from Dutch and Belgian controlled-environment agriculture seeking reduced logistics expenditure.
- Organic certification tier differentiation:National body criteria variations create market access segmentation where premium stewardship council endorsements unlock price stratification.
- Precision fertigation integration:Liquid concentrate compatibility with automated dosing systems opens channel expansion into large-scale Spanish and Italian vegetable production operations.
Industry Challenges
- Peptide standardization skill scarcity:Analytical chemists capable of validating free amino acid profiles against nitrogen specifications remain concentrated near coastal processing clusters.
- Multi-jurisdiction certification timelines:Divergent organic approval pathways between German BNN, French ECOCERT, and EU-level frameworks extend product registration cycles.
- Legacy acid-hydrolysis asset stranding:Existing thermal processing infrastructure faces obsolescence risk as enzymatic methods displace conventional production for bioactive-sensitive applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Hydrolysate Market |
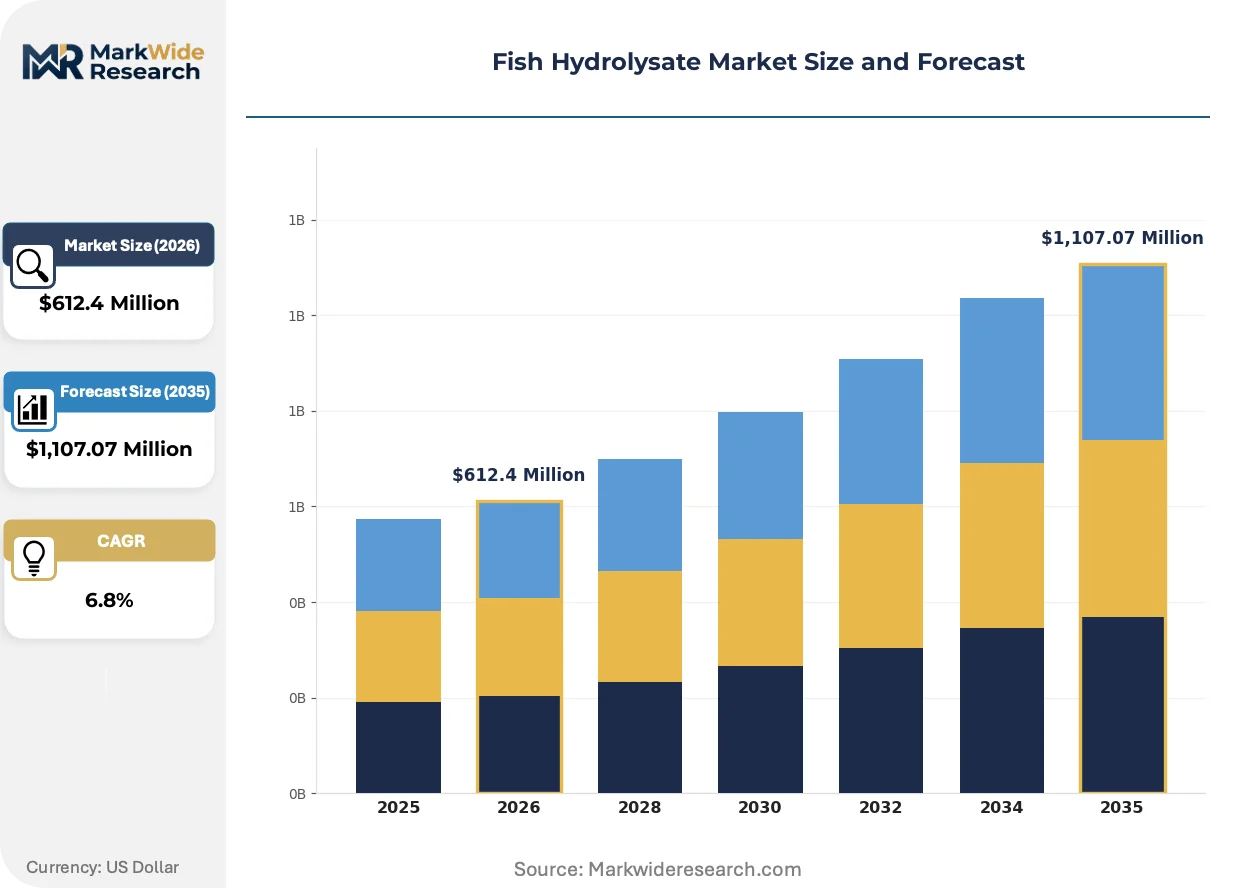
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrate, Dry Powder, Granular, Soluble, Emulsified Application: Agricultural Fertilizers, Animal Feed Additives, Aquaculture Nutrition, Bio-stimulants, Soil Conditioners End User: Crop Growers, Poultry Producers, Fish Farmers, Horticulturists, Greenhouse Operators Packaging Type: Drums, Bulk Containers, Sachets, Bottles, Bags |
| Companies Covered | Hofseth BioCare, Copalis Sea Solutions, Scanbio Marine Group, SOPROPECHE, Diana Group, Bio-marine Ingredients Ireland, Janatha Fish Meal & Oil Products, Omega Protein, Alaska Protein Recovery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Hydrolysate Market Shifts & Advancements
Enzymatic refinement technologies are displacing thermal processing across marine biomass valorization, while regulatory tightening on synthetic inputs accelerates substitution patterns in crop nutrition and feed formulation.
Low-temperature protease catalysis is rewriting extraction economics for volatile bioactive preservation. Norwegian coastal processors deploy controlled enzymatic hydrolysis to isolate standardized peptide fractions for Atlantic salmon smolt diets. This technology is compressing batch-to-batch variation and enabling premium pricing for aquaculture-grade hydrolysates.
REACH chemical registration pathways are reshaping import compliance for formulated hydrolysates entering European agricultural channels. ECHA substance evaluation protocols now require full toxicological dossiers for peptide-based biostimulants previously classified as simple fertilizers. German and Dutch formulators are responding by consolidating supply relationships with EU-registered production facilities.
Certification-driven purchasing is fragmenting buyer segments across organic crop production. French viticulture cooperatives now mandate ECOCERT or equivalent stewardship council endorsement as a gatekeeping criterion for biostimulant procurement. This behavioral shift is visible most acutely in Champagne and Bordeaux appellations where synthetic input reduction targets are binding on certified growers.
Fish Hydrolysate Market Segmentation
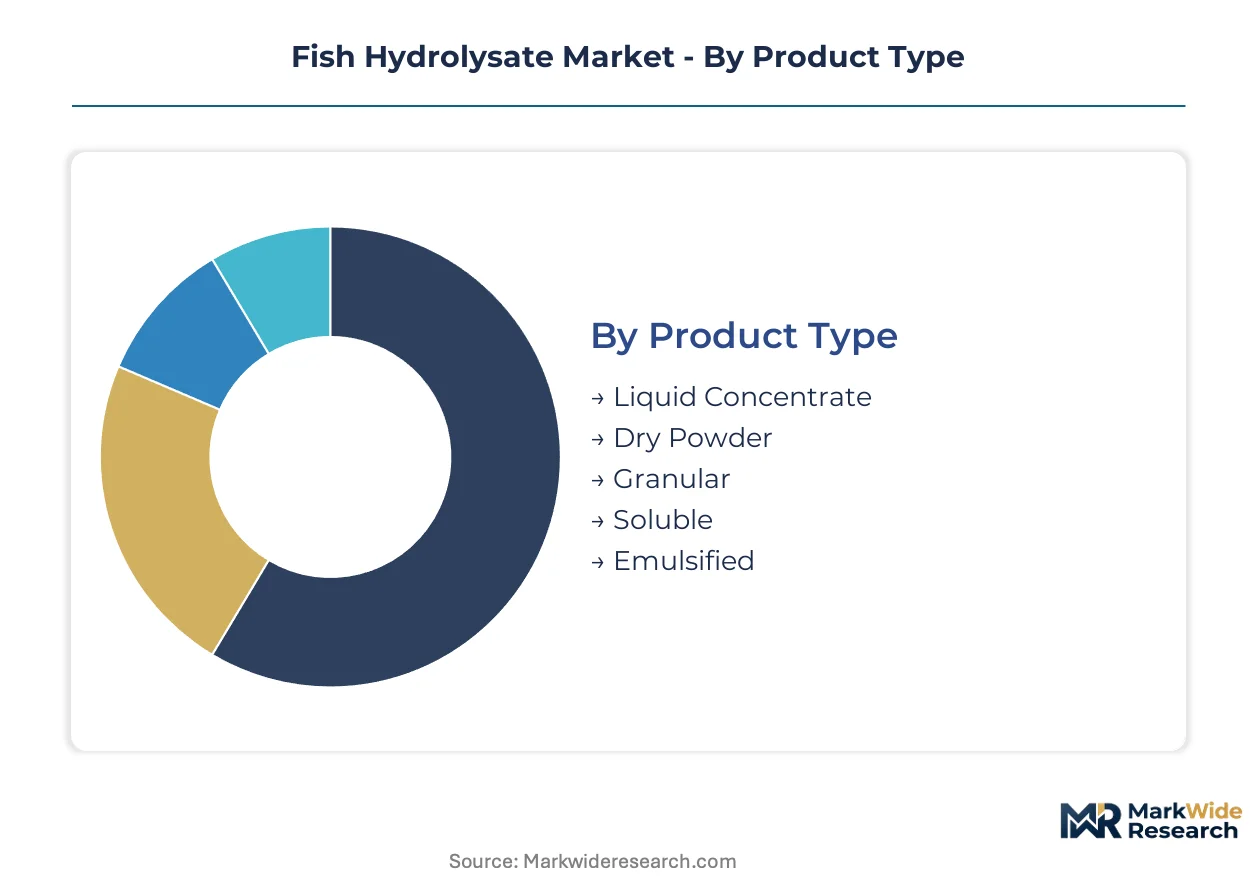
Fish hydrolysate segmentation reflects divergent supply chain economics across physical states, application intensities, and customer procurement patterns. Each category exhibits distinct margin structures and regulatory exposure that reshape competitive positioning.
Product Type:
The customization-to-standardization spectrum runs from bulk liquid formulations to precision-engineered emulsions requiring stabilizer chemistry and shear-resistant processing.
- Liquid Concentrate:Enzymatically refined marine biomass in aqueous suspension with standardized nitrogen profiles of 8-12% total N. Dutch and Belgian greenhouse operators drive procurement volumes through automated fertigation systems that demand pumpable viscosity and batch-to-batch consistency.
- Dry Powder:Spray-dried peptide fractions with moisture content below 5% for freight-efficient long-haul distribution. Spanish and Italian vegetable producers absorb premium pricing to offset logistics expenditure from Norwegian and Icelandic processing origins.
- Granular:Agglomerated powder with controlled dissolution rates for broadcast application equipment.
- Soluble:Micronized particles engineered for complete dissolution in cold water without residue.
- Emulsified:Lipid-stabilized suspensions preserving volatile omega fractions for premium aquaculture feeds.
Most installed capacity flows through Liquid Concentrate. Expansion is steepest in Dry Powder.
Application:
Application intensity correlates with regulatory pressure on synthetic substitutes, creating tiered pricing power across crop nutrition versus feed fortification channels.
- Bio-stimulants:Marine-derived signaling compounds triggering stress tolerance and nutrient uptake pathways in plants. French organic viticulture cooperatives mandate ECOCERT certification as procurement gatekeeping, compressing supplier qualification timelines.
- Aquaculture Nutrition:Standardized peptide hydrolysates for Atlantic salmon smolt diets with validated free amino acid profiles. Norwegian coastal processors anchor supply relationships through cold-chain enzymatic methods that preserve bioactive fractions.
- Agricultural Fertilizers:Nitrogen-supplementing soil amendments for conventional crop production systems.
- Animal Feed Additives:Poultry and livestock ration fortification subject to EFSA biogenic amine thresholds.
- Soil Conditioners:Microbial substrate applications improving cation exchange capacity in degraded soils.
Volume concentrates in Aquaculture Nutrition. Bio-stimulants are climbing the fastest.
End User:
Customer scale and technical sophistication determine formulation specifications, from greenhouse precision dosing to commodity feed blending.
- Greenhouse Operators:Controlled-environment agriculture requiring dry powder freight efficiency and liquid concentrate fertigation compatibility. Dutch operators consolidate procurement through cooperative purchasing structures that compress supplier margins.
- Fish Farmers:Norwegian Atlantic salmon producers demanding batch-certified peptide standardization for smolt and on-growing diets. REACH-compliant documentation requirements extend qualification cycles for non-EU suppliers.
- Crop Growers:Field-scale operators balancing application labor costs against input performance premiums.
- Poultry Producers:Integrated operations seeking volume-grade hydrolysates for ration protein supplementation.
- Horticulturists:Specialty crop producers with fragmented demand and high service requirements.
Procurement scale peaks with Fish Farmers. Technical specification intensity is highest among Greenhouse Operators.
Packaging Type:
Packaging configuration tracks customer scale and handling infrastructure, from bulk marine terminal delivery to retail sachet distribution.
- Bulk Containers:Intermediate bulk containers and flexitanks for marine freight from Norwegian processing facilities to continental European formulators. Unit cost efficiency drives adoption among large-scale aquaculture feed compounders.
- Drums:Standard 200-liter steel and polyethylene containers for liquid concentrate distribution to agricultural cooperatives and mid-scale greenhouse operations.
- Bags:Multi-wall paper and woven polypropylene for dry powder horticultural supply.
- Bottles:Retail-scale packaging for specialty bio-stimulant products.
- Sachets:Single-use soluble portions for precision application in smallholder and home gardening segments.
Freight volume concentrates in Bulk Containers. Value-added packaging growth centers on Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian coastal processors pioneered enzymatic hydrolysis for Atlantic salmon feed fortification during the 1990s aquaculture expansion. This technology lineage now extends across North European marine biomass valorization clusters.
Norway
Atlantic salmon smolt production and on-growing sites concentrate demand for standardized peptide hydrolysates with validated free amino acid profiles. The EU F-Gas Regulation redirects capital toward low-temperature enzymatic methods that preserve volatile bioactive fractions. Coastal processing facilities in Møre og Romsdal and Nordland anchor supply relationships through cold-chain infrastructure.
Germany
Organic crop growers in Lower Saxony and Bavaria scale purchases of certified bio-stimulants as synthetic fertilizer quotas compress under the EU Green Deal's Farm to Fork strategy. German BNN certification criteria create procurement gatekeeping that extends supplier qualification timelines. The Rhine-Ruhr industrial corridor hosts formulators consolidating supply relationships with EU-registered production facilities.
France
Viticulture cooperatives in Champagne and Bordeaux mandate ECOCERT endorsement as binding criteria for biostimulant procurement under synthetic input reduction targets. ECHA substance evaluation protocols require full toxicological dossiers for peptide-based products previously classified as simple fertilizers. The Atlantic coastline from Brittany to La Rochelle supports cod-derived formulation specialists.
Netherlands
Greenhouse operators in Westland and Aalsmeer drive dry powder adoption for freight-efficient distribution through cooperative purchasing structures. Automated fertigation systems demand pumpable liquid concentrate viscosity with batch-to-batch consistency. Dutch controlled-environment agriculture absorbs premium pricing to offset logistics expenditure from distant processing origins.
United States
Gulf of Mexico menhaden fishery quotas create input cost instability for volume-grade agricultural hydrolysate production serving poultry and livestock ration fortification. EPA and state-level fishery management frameworks govern seasonal biomass fluctuations that complicate procurement planning. Omega Protein anchors coastal processing infrastructure in Louisiana and Virginia to sustain throughput for agricultural customers.
Fish Hydrolysate Market Competitive Landscape
Capital-heavy coastal processors compete with asset-light formulation specialists across the fish hydrolysate value chain. The vendor base separates between integrated marine biomass operators with cold-chain enzymatic infrastructure and regional formulators blending imported peptide fractions for crop nutrition channels. Three archetypes dominate: Norwegian aquaculture-grade specialists, French organic viticulture formulators, and Gulf Coast volume-grade producers. Competitive moves concentrate on backward integration into fishery sourcing and certification tier differentiation for premium market access.
Among Norwegian coastal processors, Hofseth BioCare and Scanbio Marine Group exemplify the integrated production archetype with enzymatic refinement capabilities. SOPROPECHE occupies a position within the French formulation tier targeting certified organic channels. Omega Protein anchors the North American volume-grade segment with Gulf of Mexico sourcing infrastructure.
| Leading Market Players |
|---|
| Hofseth BioCare |
| Copalis Sea Solutions |
| Scanbio Marine Group |
| SOPROPECHE |
| Diana Group |
| Bio-marine Ingredients Ireland |
| Janatha Fish Meal & Oil Products |
| Omega Protein |
| Alaska Protein Recovery |
| Others |
Supply & Pricing Matrix
Backward integration into Norwegian coastal fishery infrastructure anchors supply security and premium pricing power for aquaculture-grade hydrolysate producers. Cold-chain enzymatic processing assets in Møre og Romsdal and Nordland counties tether input cost control to volatile peptide fraction preservation, compressing margin exposure for integrated operators while forcing non-integrated formulators toward spot-market menhaden procurement with attendant price instability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies fish hydrolysate procurement. Certification tier—ECOCERT, BNN, or aquaculture stewardship council endorsement—drives price differentiation alongside volume scale and cold-chain integrity guarantees. Cost compression in the economy tier intensifies because Gulf of Mexico menhaden quota volatility feeds input cost instability. Greenhouse operators in the Netherlands exhibit highest price sensitivity due to cooperative purchasing structures, while Norwegian salmon farmers absorb premium pricing for batch-certified peptide standardization.
Supply Chain Analysis
Qualification gating through REACH registration and EFSA biogenic amine documentation extends supplier onboarding cycles and fragments procurement options. Supply concentrates in Norway, Iceland, and the United States, with Norwegian coastal processors anchoring premium peptide fraction output. Raw material flows draw from Atlantic cod residuals, Gulf menhaden landings, and salmon processing bycatch. Single-source vulnerability runs through protease catalyst supply anchored to specialized biotechnology producers. Distribution runs through bulk marine terminals to continental European formulators, with dry powder freight efficiency commanding logistics arbitrage for distant greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fish hydrolysate market functions as a geographic-arbitrage play where Norwegian cold-chain processing infrastructure commands premium pricing against Gulf Coast volume-grade production facing EPA fishery quota constraints.
For Market Incumbents: Acquire enzymatic refinement reactor capacity in Norwegian coastal zones to lock in Atlantic salmon feed compounder relationships. Defensive consolidation requires backward integration into fishery sourcing to offset menhaden supply volatility, while certification investment in ECOCERT and BNN tiers creates procurement gatekeeping against emerging acid-hydrolysis competitors facing asset stranding risk. For New Entrants and Emerging Players: Enter via dry powder formulation for Dutch and Belgian greenhouse cooperatives seeking freight-efficient alternatives to liquid concentrate imports. The most penetrable segment sits in Spanish and Italian precision fertigation channels where automated dosing system compatibility remains underdeveloped. A technical service-led go-to-market angle emphasizing batch-to-batch nitrogen profile validation unlocks qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where peptide standardization analytical chemistry capabilities concentrate near coastal processing clusters, creating acquisition scarcity for validated production assets. Long-term viability hinges on enzymatic method displacement of acid-hydrolysis infrastructure across bioactive-sensitive applications. The signal to watch is divergence in national organic certification timelines between German BNN, French ECOCERT, and EU-level frameworks as inflection indicator for market access tier fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishery Sourcing | Captive menhaden and cod residual supply secures input cost control against Gulf quota volatility. |
| Cold-Chain Enzymatic Capacity Expansion | Low-temperature reactor investment in Norway preserves volatile peptide fractions for salmon feed premiums. |
| Multi-Tier Certification Investment | ECOCERT, BNN, and stewardship council endorsements unlock price stratification in organic crop channels. |
| Dry Powder Logistics Optimization | Spray-dried formulation engineering reduces freight expenditure for Dutch greenhouse cooperative procurement. |
| Precision Fertigation Compatibility Development | Pumpable viscosity standardization opens automated dosing penetration in Spanish vegetable production. |
Research Methodology
Coverage spans Norway, Germany, France, the Netherlands, and the United States, with primary inputs from each market cluster combining executive interviews with aquaculture feed compounders, organic crop cooperative procurement managers, coastal processing plant operators, and marine fishery quota administrators. Secondary validation draws from EFSA safety threshold publications, ECHA REACH registration databases, EU Green Deal Farm to Fork strategy documents, and national fishery landings statistics. Bottom-up volume modeling triangulates against top-down value estimates across enzymatic and acid-hydrolysis production routes.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions modeled include physical state, application intensity, end-user scale, and packaging configuration, with additional granularity on certification tier and cold-chain integrity. CAGRs derive from historical production capacity trajectories, fishery quota allocation patterns, and substitution elasticity estimates for synthetic fertilizer displacement. Industry-specific forecast inputs incorporate protease catalyst cost curves and automated fertigation adoption rates in controlled-environment agriculture.
Inputs from EFSA, ECHA, and national fishery management frameworks were available through the study window; gaps in batch-level peptide standardization validation data introduce uncertainty bands around aquaculture nutrition segment projections. Forecasts reflect documented assumptions on enzymatic method adoption curves and organic certification timeline convergence. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or Gulf of Mexico menhaden quota allocation methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Tuna Market
Seafood
China Crustaceans Market
Seafood
South America Canned Seafood Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
United States Seafood Market
Seafood
Fish Maw Market
Seafood
Global Seafood Market
Seafood
Tinned Fish Market
Seafood
Wild Pollock Market
Seafood
Herring Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Global White Shrimp Market
Seafood
Global Smoked Fish Market
Seafood
Tuna Fish Market
Seafood
Sea Bream Market
Seafood
Salmon Market