
 United Arab Emirates Seafood Market | 2026-2036
United Arab Emirates Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Seafood Market Analytics
Subscription-based cold-chain monitoring is repositioning how seafood freshness gets guaranteed across UAE import channels. International Fish Farming Holding (Asmak) leverages its integrated hatchery-to-retail infrastructure to dominate local production of seabream and hamour. Al Islami Foods anchors its market presence through halal-certified processing lines that sustain retail shelf placement across Gulf Cooperation Council markets. The Deep Seafood Company competes on European direct-sourcing relationships, controlling air-freight lanes from Norway and Scotland into Dubai International Airport's perishable cargo terminal.
United Arab Emirates Seafood comprises marine and aquaculture-derived protein products—fish, shellfish, crustaceans, and mollusks—harvested, processed, and distributed under strict temperature-controlled protocols, typically maintained between minus 18 degrees Celsius for frozen product and 0 to 4 degrees Celsius for fresh chilled goods, serving protein supply needs for domestic consumption and re-export trade. Fresh seafood occupies the premium price tier in UAE retail, reflecting consumer preference for same-day catch display at fish markets and high-end restaurant procurement. Frozen seafood sustains volume throughput through supermarkets and institutional food service, where storage stability supports inventory planning across seasonal supply fluctuations. Online retail represents the fastest-growing distribution channel, as platform investments in last-mile chilled logistics unlock direct-to-household delivery of previously restaurant-exclusive species.
MOHAP enforces Hazard Analysis Critical Control Point compliance across all seafood import and processing facilities, while the UAE's National In-Country Value program directs federal procurement toward domestic aquaculture expansion. Dubai Municipality's Food Safety Department operates port-of-entry testing laboratories that screen for histamine, mercury, and veterinary drug residues, shaping supplier qualification standards for entering the market. Stakeholders must monitor how Abu Dhabi's aquaculture zone development at Al Dhafra interacts with evolving import substitution targets and water-use licensing frameworks.
Market Dynamics
MOHAP's cold-chain traceability mandates are compressing supplier qualification timelines while elevating compliance costs for import-dependent distributors serving Dubai's hospitality corridor.
Growth Catalysts
- Hotel and resort procurement:Premium shellfish and crustacean volumes are accelerating across Dubai and Abu Dhabi as five-star properties expand their seafood-forward dining concepts.
- MOHAP food safety protocols:Updated Hazard Analysis Critical Control Point compliance requirements are filtering out informal traders and consolidating volume with certified importers.
- Al Dhafra aquaculture zone:Abu Dhabi's water-use licensing frameworks for domestic seabream and hamour production are reducing import dependency ratios.
Market Restraints
- Air-freight cost volatility:Perishable cargo rates on European direct-sourcing lanes from Norway and Scotland fluctuate with jet fuel pricing and capacity constraints at Dubai International Airport.
- Freshwater scarcity:Inland aquaculture expansion faces hard limits from the UAE's groundwater depletion and desalination energy costs.
- Histamine testing bottlenecks:Dubai Municipality's port-of-entry laboratory capacity creates clearance delays during peak seasonal import windows.
Strategic Opportunities
- Last-mile chilled logistics:Platform investments in direct-to-household delivery are unlocking online retail penetration for previously restaurant-exclusive species.
- National In-Country Value program:Federal procurement directives are channeling capital toward domestic hatchery infrastructure and processing facility upgrades.
- Halal-certified processing:Gulf Cooperation Council retail shelf placement requirements create export arbitrage potential for UAE-based processors.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration engineering and temperature monitoring expertise lags behind the speed of distribution network expansion.
- Mercury residue compliance:Dubai Municipality's screening protocols for large pelagic species require extended supplier documentation and batch testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Seafood Market |
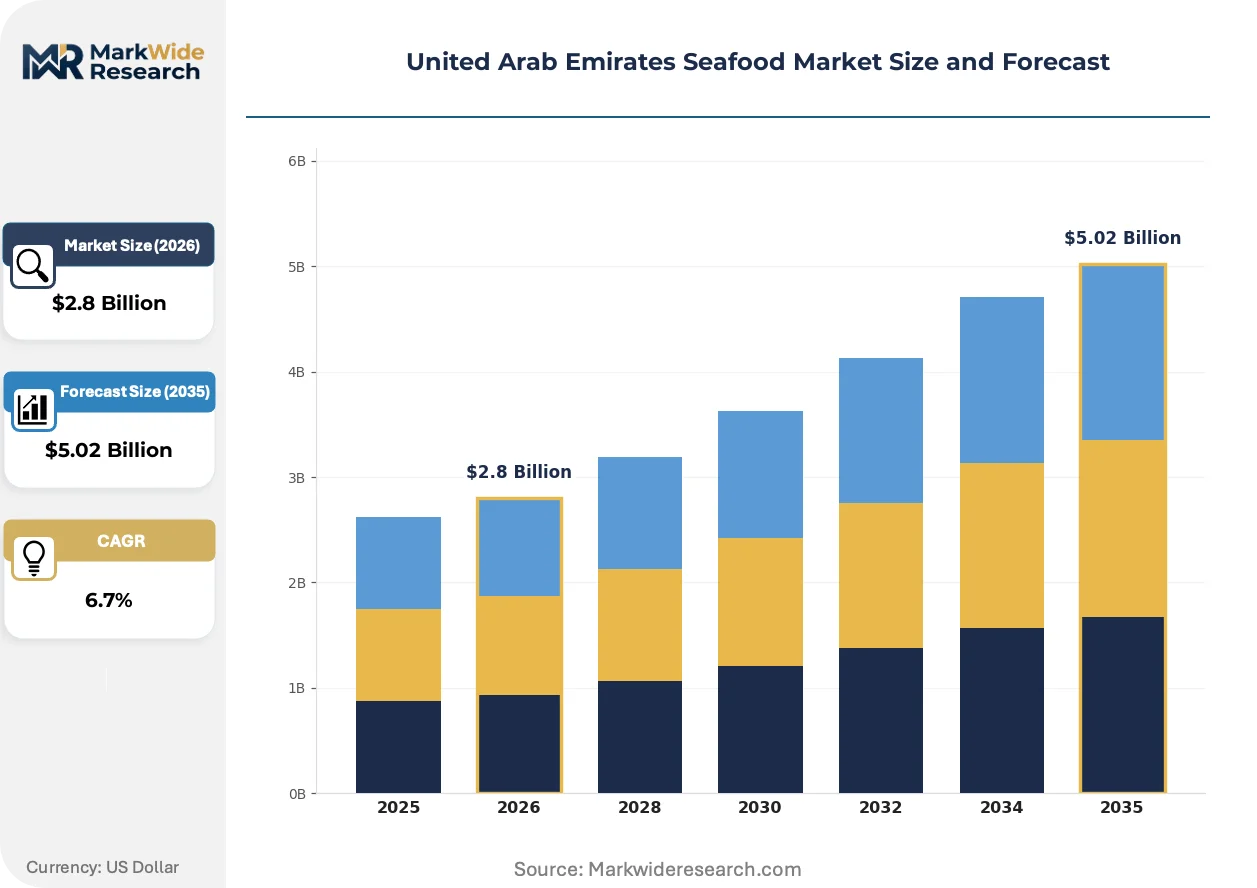
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Seafood, Frozen Seafood, Canned Seafood, Dried Seafood Distribution Channel: Supermarkets, Fish Markets, Online Retail, Restaurants Seafood Type: Fish, Shellfish, Crustaceans, Mollusks End User: Households, Food Service, Exporters, Retailers |
| Companies Covered | Golden Dunes General Trading LLC, Abu Dhabi Fishermen Cooperative Society, Al Islami Foods, KEZAD Group, Aqua Development, International Fish Farming Holding (Asmak), Al Munajem Foods, Environment Agency Abu Dhabi, The Deep Seafood Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Seafood Market Evolving Landscape
Subscription-based freshness verification systems are displacing spot-check quality assurance across UAE import channels, while regulatory digitization and direct-to-consumer platform economics rewrite distribution economics.
Blockchain-enabled traceability platforms are expanding into end-to-end catch documentation, linking Norwegian and Scottish harvest vessels through Dubai International Airport's perishable cargo terminal to hotel procurement systems. Major hospitality groups in Dubai's hospitality corridor are mandating supplier participation. This technology is compressing dispute resolution cycles and reducing insurance premiums for high-value crustacean shipments.
MOHAP's digitized import permit system is accelerating clearance workflows while embedding real-time temperature logging requirements into customs documentation. Processing facilities must now upload continuous cold-chain data before physical inspection. Smaller traders lacking integrated monitoring infrastructure are exiting the market, consolidating volume with technology-capable distributors.
Household purchasing of same-day chilled seafood through platform apps is displacing traditional fish market visits among affluent Dubai and Abu Dhabi consumers. Last-mile refrigerated vehicle networks now support 90-minute delivery windows for premium shellfish previously restricted to restaurant supply. This channel shift is most visible in Dubai's residential towers, where subscription seafood boxes are capturing repeat purchase loyalty from dual-income households.
United Arab Emirates Seafood Market Segmentation
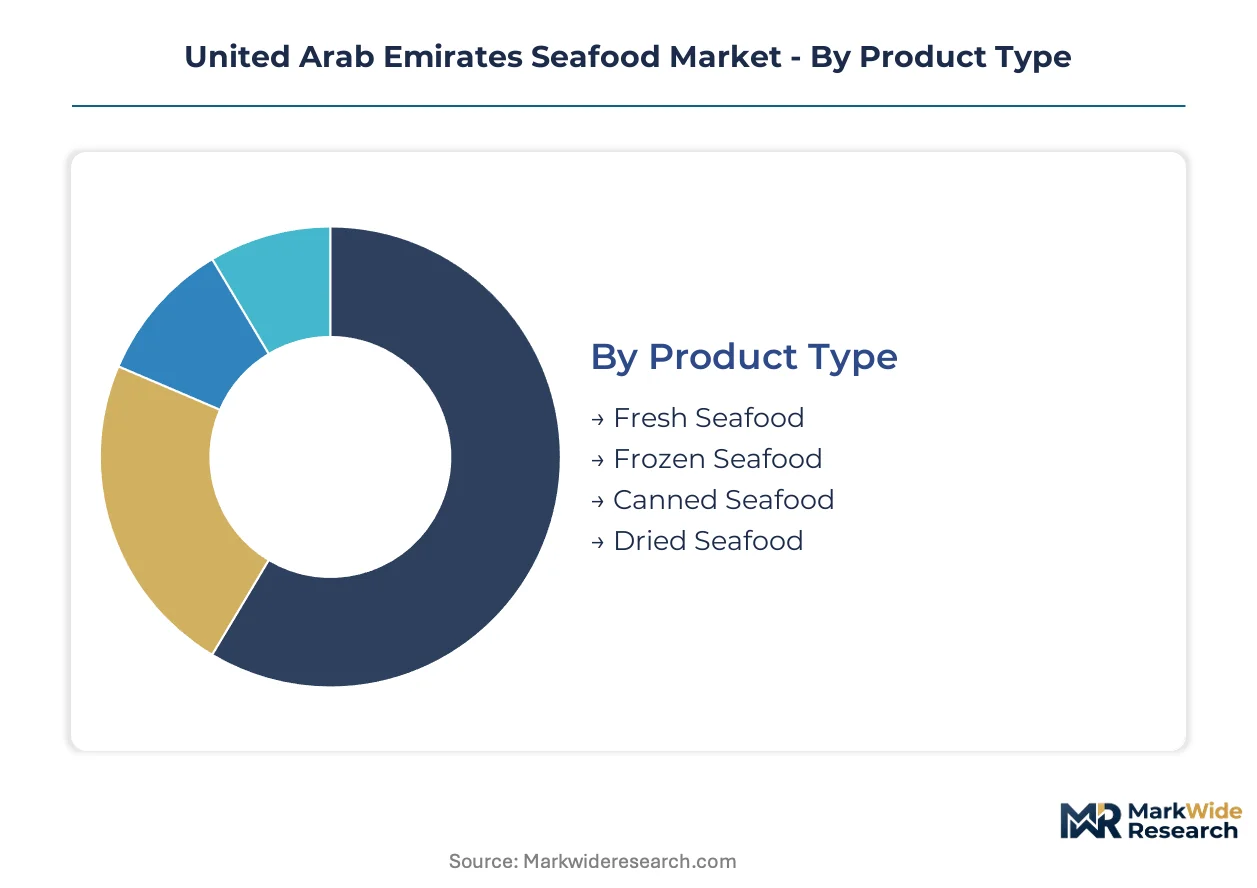
Segmentation in the UAE seafood market reveals how cold-chain capabilities and hospitality procurement priorities allocate value across product formats and channels. Understanding these divisions exposes where compliance costs concentrate and where logistics investments unlock premium positioning.
Product Type:
Supply concentration tilts toward temperature-controlled formats that align with Dubai's hospitality corridor procurement standards and MOHAP traceability mandates.
- Fresh Seafood:Same-day catch display at Dubai fish markets and restaurant procurement dominates this tier. Hotel and resort food service channels drive premium shellfish and crustacean volumes across the emirates.
- Frozen Seafood:Minus 18 degrees Celsius storage stability supports inventory planning across seasonal supply fluctuations. Supermarkets and institutional food service sustain volume throughput where air-freight volatility from European sourcing lanes creates procurement hedging demand.
- Canned Seafood:Shelf-stable formats serve price-sensitive household segments and emergency procurement for offshore catering operations.
- Dried Seafood:Traditional preservation methods retain niche demand among specific demographic communities and re-export trade to Asian markets.
Today's leader: Fresh Seafood. Tomorrow's challenger: Frozen Seafood.
Distribution Channel:
Channel economics reflect last-mile infrastructure maturity and the speed at which temperature integrity gets guaranteed to end consumers.
- Supermarkets:Frozen product volume throughput anchors this channel, with MOHAP-compliant cold-chain documentation now required for shelf placement. Retail consolidation favors certified importers over informal traders.
- Online Retail:Platform investments in 90-minute chilled delivery windows are unlocking direct-to-household penetration for species previously restricted to restaurant supply. Subscription seafood boxes capture repeat purchase loyalty from dual-income households in Dubai's residential towers.
- Fish Markets:Same-day catch display retains cultural significance and price transparency for traditional consumers.
- Restaurants:Five-star property expansion of seafood-forward dining concepts concentrates procurement power among hospitality groups mandating blockchain-enabled traceability participation.
Distribution gravity centers on Online Retail for trajectory, Restaurants for absolute value capture.
Seafood Type:
Biological category boundaries align with import dependency ratios and domestic aquaculture substitution potential at Al Dhafra.
- Crustaceans:Premium shrimp and lobster shipments face Dubai Municipality histamine testing bottlenecks during peak seasonal windows. Air-freight lane control from Norway and Scotland determines supplier competitiveness.
- Shellfish:High-value oyster and scallop procurement accelerates across Abu Dhabi and Dubai hospitality properties. Blockchain traceability mandates from major hotel groups are filtering supplier pools.
- Fish:Seabream and hamour production from Asmak's integrated hatchery-to-retail infrastructure reduces import dependency for key local species.
- Mollusks:Clam and mussel volumes serve mid-tier restaurant segments with less stringent certification requirements than crustacean categories.
Margin accretion concentrates in Crustaceans. Volume scaling favors Fish.
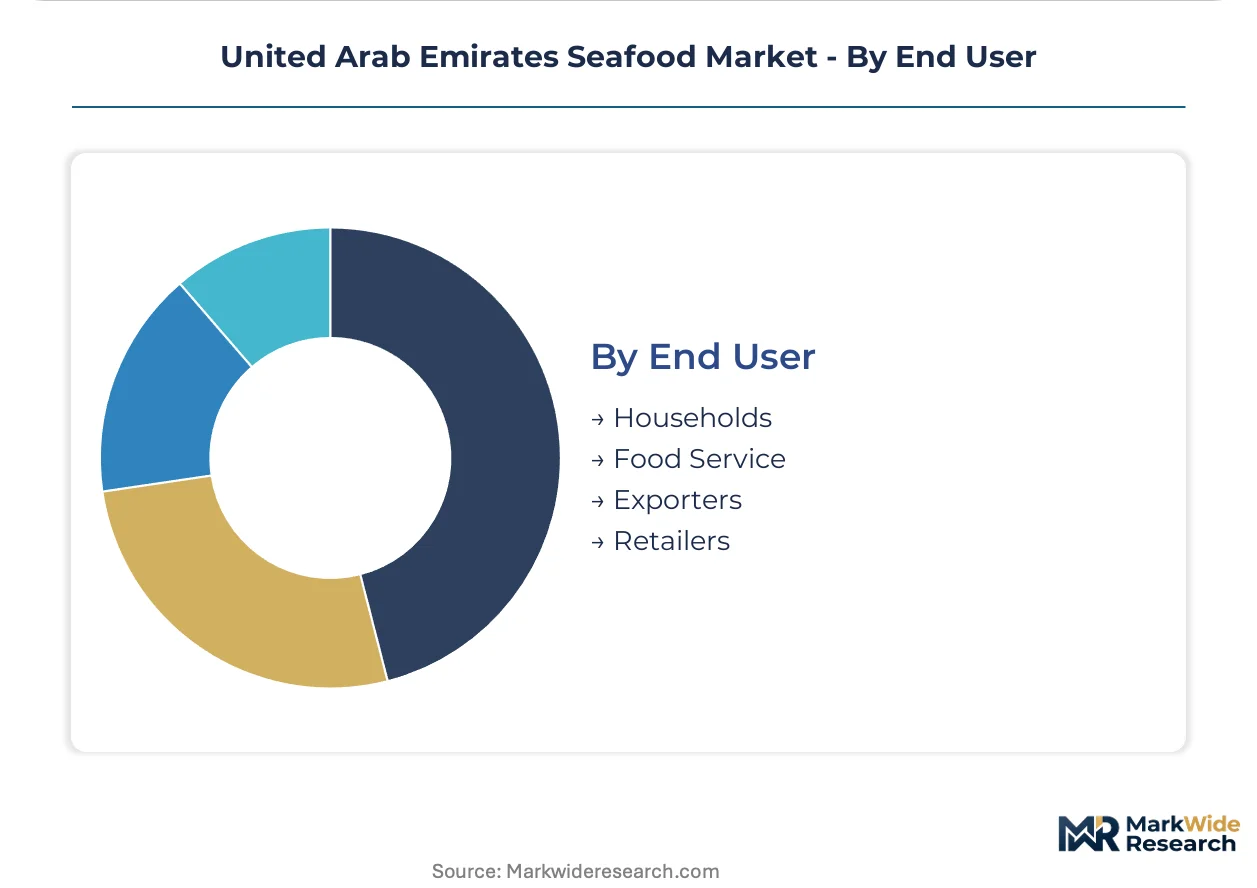
End User:
Customer-type segmentation exposes where National In-Country Value program procurement directives channel capital versus where import substitution meets resistance.
- Food Service:Hotel and resort procurement dominates value capture, with halal-certified processing requirements creating GCC export arbitrage potential for UAE-based processors.
- Households:Platform app penetration is displacing traditional fish market visits among affluent Dubai and Abu Dhabi consumers. Last-mile refrigerated vehicle networks now support subscription models.
- Exporters:Re-export trade to Gulf Cooperation Council markets depends on halal certification and MOHAP-compliant documentation standards.
- Retailers:Supermarket chains consolidate volume with technology-capable distributors as MOHAP's digitized import permit system accelerates clearance workflows.
Food Service commands pricing power. Households represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's aquaculture expansion outpaces Qatar's import-dependent hospitality procurement, while both Emirates anchor Gulf seafood trade through divergent regulatory frameworks and infrastructure investments.
Dubai
Five-star hotel groups along Sheikh Zayed Road drive premium shellfish and crustacean procurement volumes. Dubai Municipality's Food Safety Department enforces port-of-entry histamine and mercury screening at Jebel Ali and Dubai International Airport cargo terminals. The Dubai Multi Commodities Centre seafood trading cluster concentrates re-export operations serving Gulf Cooperation Council markets.
Abu Dhabi
Al Dhafra aquaculture zone development targets domestic seabream and hamour production substitution for key restaurant species. The Environment Agency Abu Dhabi administers water-use licensing frameworks governing hatchery expansion and desalination energy allocation. Yas Island hospitality properties and Saadiyat Island resort developments concentrate high-value procurement demand.
Sharjah
Mid-tier food service distributors serving northern emirates industrial zones sustain frozen seafood volume throughput. Sharjah's Hamriyah Free Zone offers cold-chain warehousing capacity for re-export trade to Oman and Bahrain. The emirate's fish market infrastructure supports traditional retail channels with same-day catch display operations.
Northern Emirates
Fujairah and Ras Al Khaimah fishing harbors supply local consumption with small-scale pelagic and reef fish landings. Federal Ministry of Climate Change and Environment regulations govern artisanal fleet licensing and seasonal catch quotas. Port infrastructure limitations restrict air-freight perishable exports compared to Dubai and Abu Dhabi terminals.
Saudi Arabia
Red Sea coastal aquaculture projects at Jazan and Al-Lith target regional seabream and shrimp production scale. The Saudi Food and Drug Authority enforces Hazard Analysis Critical Control Point alignment with Gulf Cooperation Council standards. NEOM development plans incorporate integrated mariculture systems for projected hospitality demand.
United Arab Emirates Seafood Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hatchery-to-retail operators commanding domestic production while import distributors compete on European air-freight lane control. Market structure tilts toward consolidation as MOHAP digitized permit requirements filter smaller traders lacking cold-chain monitoring infrastructure. Three archetypes dominate: domestic aquaculture integrators with federal In-Country Value program alignment, European direct-sourcing specialists controlling perishable cargo terminal access, and halal-certified processors leveraging GCC retail shelf placement. Competitive moves concentrate on strategic partnerships with hospitality groups mandating blockchain traceability and capacity expansion at Al Dhafra zone facilities.
Among domestic production specialists, International Fish Farming Holding exemplifies integrated hatchery-to-retail infrastructure dominance in seabream and hamour categories. Al Islami Foods anchors halal-certified processing capabilities serving GCC export arbitrage opportunities. The Deep Seafood Company occupies a position among European direct-sourcing distributors leveraging Norway and Scotland air-freight relationships into Dubai International Airport's perishable cargo terminal.
| Leading Market Players |
|---|
| Golden Dunes General Trading LLC |
| Abu Dhabi Fishermen Cooperative Society |
| Al Islami Foods |
| KEZAD Group |
| Aqua Development |
| International Fish Farming Holding (Asmak) |
| Al Munajem Foods |
| Environment Agency Abu Dhabi |
| The Deep Seafood Company |
| Others |
Value Network & Pricing Analysis
European air-freight spot rates for chilled seafood cargoes cascade through Dubai International Airport's perishable terminal into three distinct procurement tiers: hospitality groups absorbing premium crustacean costs, supermarkets hedging frozen inventory against seasonal volatility, and direct-to-consumer platforms compressing last-mile margins to capture household subscriptions.
Pricing Analysis
Capacity additions in Saudi Arabia's Red Sea aquaculture zones are reshaping price floors for seabream and shrimp categories previously dominated by European imports. Three-tier pricing structure across premium, standard, and economy levels segments by cold-chain certification grade and traceability documentation depth. Cost compression in the standard tier is intensifying as Al Dhafra zone production scales, while hospitality procurement shows least price sensitivity due to menu margin absorption.
Supply Chain Analysis
Direct-to-hospitality channels handle hyperscale buyer demand from Dubai's five-star property clusters, while supermarket distributors manage frozen volume throughput across seasonal fluctuations. Supply concentrates in Norway, Scotland, and domestic Al Dhafra facilities for fresh categories; Thailand and India anchor processed shrimp feeds. Single-source vulnerability runs through Dubai International Airport's perishable cargo terminal capacity constraints during peak import windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE seafood market functions as a geographic-arbitrage play between European air-freight sourcing costs and Saudi aquaculture zone production economics, with MOHAP's digitized compliance mandates creating regulatory differentiation that favors capitalized distributors over informal traders.
For Market Incumbents: To counter Saudi Red Sea capacity expansion, secure long-term offtake agreements with Norwegian and Scottish harvest vessels while embedding blockchain traceability infrastructure to meet hospitality group procurement mandates. Channel control through Dubai Multi Commodities Centre trading cluster membership sustains re-export arbitrage into Gulf Cooperation Council markets. For New Entrants and Emerging Players: Platform technology partners offer the fastest penetration vector into Dubai residential tower subscription models, where 90-minute chilled delivery capability unlocks household segments previously restricted to restaurant supply. White-space concentrates in mid-tier shellfish processing for Sharjah's northern emirates industrial food service corridors, with halal certification investment enabling GCC retail shelf placement. For Investors and Strategic Acquirers: Consolidation pressure builds where MOHAP's cold-chain monitoring mandates exceed smaller trader technical capabilities, filtering volume toward technology-capable distributors. Long-term viability favors integrated hatchery-to-retail operators aligned with Abu Dhabi's National In-Country Value program procurement directives. The signal to watch is Dubai Municipality port-of-entry laboratory capacity expansion timelines, which determine clearance velocity during seasonal peak windows.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Major hospitality groups now mandate supplier participation, compressing dispute cycles for high-value crustacean shipments. |
| Al Dhafra Zone Capacity Expansion | Domestic seabream and hamour production reduces import dependency ratios under Environment Agency Abu Dhabi licensing. |
| Last-Mile Chilled Logistics Investment | Platform-enabled 90-minute delivery windows unlock direct-to-household penetration for previously restaurant-exclusive species. |
| Halal-Certified Processing Line Upgrades | Gulf Cooperation Council retail shelf placement requirements create export arbitrage potential for UAE-based processors. |
| European Air-Freight Lane Control | Norway and Scotland direct-sourcing relationships determine competitive positioning in premium shellfish categories. |
Research Methodology
Multiple input streams — structured interviews with seafood import procurement managers, aquaculture operations directors, and hospitality group supply chain executives, alongside customs trade databases, MOHAP regulatory filings, and Dubai Municipality Food Safety Department inspection records — were reconciled through bottom-up volume triangulation against top-down value estimates across product type, distribution channel, and emirate-level demand clusters.
Historical import volume trajectories were cross-referenced against panel-based projections from cold-chain logistics operators and hotel procurement officers across the analysis window. Segmentation dimensions modeled include temperature format, biological category, distribution channel maturity, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of hospitality corridor expansion rates and domestic aquaculture substitution ratios.
Revisions become necessary when Saudi Red Sea production scales faster than projected, Dubai International Airport perishable terminal capacity constraints intensify, or MOHAP traceability mandate enforcement timelines accelerate. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fresh Fish Market
Seafood
Fish Fermentation Market
Seafood
Krill Meal Market
Seafood
Alaskan Salmon Market
Seafood
Canned Anchovy Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Fish Oil Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Global Seafood Market
Seafood
Fish Protein Hydrolysate Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Crustacean Market
Seafood
Crayfish Market
Seafood
Tuna Fish Market
Seafood
Canned Tuna Market