
 Vetronics Market | 2026-2036
Vetronics Market Size, Share, and Industry Trends Forecast 2026-2036
Vetronics Market Intelligence
Defense industrial expansion in Eastern European nations is fragmenting the traditional supplier base for vetronics systems. This shift creates opportunities for new entrants alongside established prime contractors. BAE Systems leverages its deep integration within UK and US armored vehicle programs to secure long-term contracts. Thales Group competes on the strength of its diversified portfolio in communication and surveillance systems across multiple platforms.
Vetronics refers to the integrated suite of electronic systems within military vehicles, often utilizing a high-speed data backbone like Gigabit Ethernet for communication between subsystems. The primary purpose of these systems is to improve situational awareness, lethality, and survivability for vehicle crews. Within the product landscape, Communication Systems and Combat Management Systems constitute core investments for defense forces. While Armored Vehicles remain the primary application, the Unmanned Ground Vehicles segment is poised for significant expansion.
Product development is governed by stringent military standards, including US MIL-STD specifications and NATO Standardization Agreements (STANAGs) for interoperability. Frameworks like the UK's Generic Vehicle Architecture (GVA) mandate open systems to reduce lifecycle costs and vendor lock-in. Future procurement decisions will hinge on the trade-offs between fully integrated, proprietary systems and the flexibility offered by modular, open-architecture solutions.
Market Dynamics
The central dynamic is the conflict between vendor-proprietary systems and military-mandated open architectures like GVA. This structural tension dictates product strategy and procurement models, forcing incumbents to adapt to increased modularity and interoperability demands from defense agencies.
Growth Catalysts
- Unmanned Ground Vehicles:Expanding UGV deployment for reconnaissance and logistics creates demand for compact, remotely operated vetronics suites.
- Modernization Mandates:National armored vehicle modernization programs in the United States and United Kingdom drive demand for upgraded communication and combat management systems.
- Eastern European Defense Spending:Increased military budgets among NATO's eastern flank nations are driving new procurements of armored vehicles and their electronics.
Market Restraints
- High Qualification Costs:Certifying systems against military standards like US MIL-STD-810 is expensive and time-consuming, creating high barriers to entry.
- Long Development Cycles:The multi-year lifecycle for military hardware limits the adoption of the latest commercial-off-the-shelf processing and networking technologies.
- Component Obsolescence:Long service lives of military platforms create persistent challenges in managing electronic component obsolescence, forcing costly redesigns.
Strategic Opportunities
- Retrofit and Upgrade Programs:Upgrading legacy vehicle fleets with modular vetronics extends their operational life at a lower cost than new platforms.
- AI-Enabled Sensor Fusion:Developing artificial intelligence to fuse sensor data provides superior situational awareness and automated threat detection.
- Export Market Penetration:Suppliers can target emerging defense markets in Southeast Asia and the Middle East modernizing their ground forces.
Industry Challenges
- Systems Integration Complexity:Ensuring interoperability between new subsystems and legacy platforms under open frameworks like GVA is a significant technical hurdle.
- Cybersecurity Vulnerabilities:Networked vehicle subsystems introduce attack surfaces that require continuous hardening against sophisticated cyber threats from state-level actors.
- Specialized Talent Shortage:A scarcity of engineers with expertise in both military standards and modern IT practices constrains innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vetronics Market |
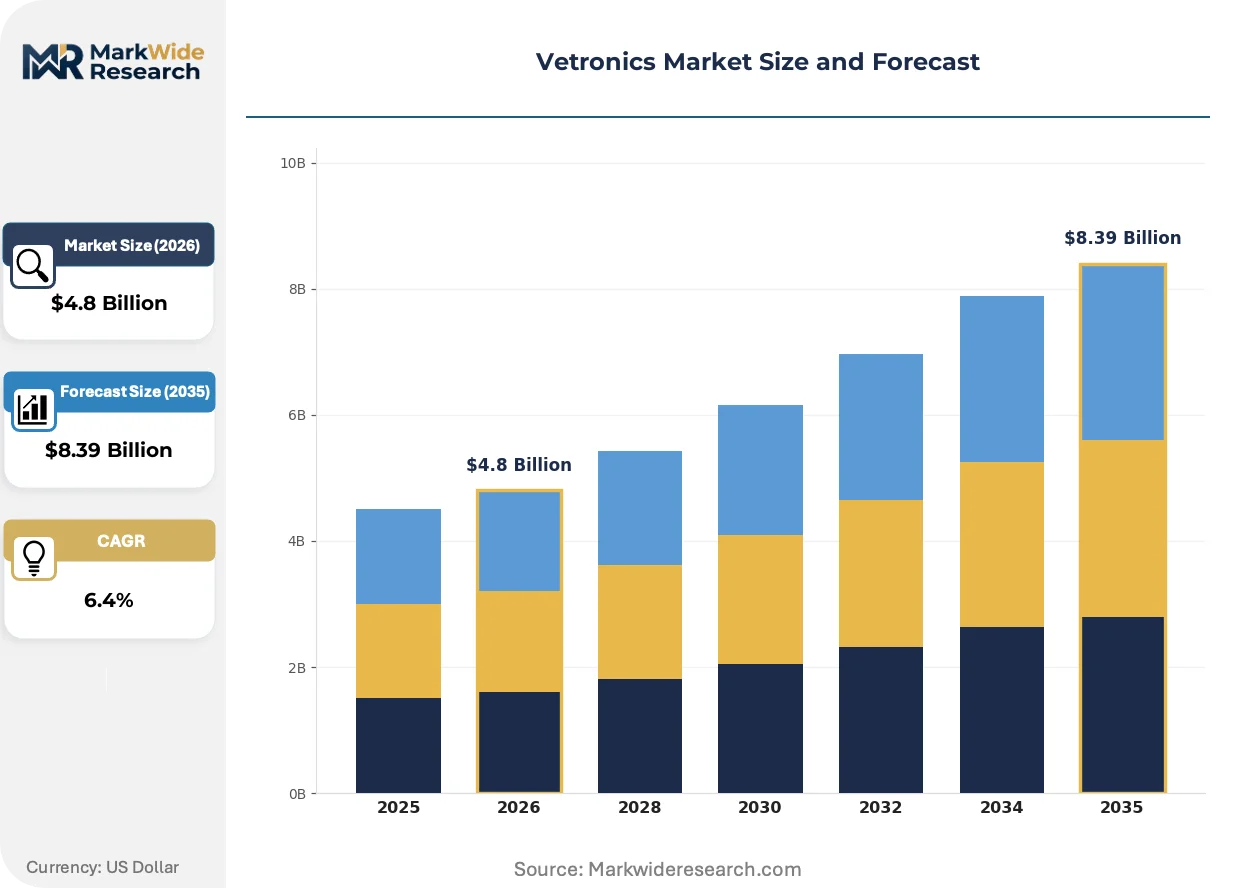
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Systems, Navigation Systems, Surveillance Systems, Electronic Warfare Systems, Combat Management Systems Technology: Radar, Lidar, Thermal Imaging, Signal Processing, Electronic Countermeasures, Optoelectronics Application: Armored Vehicles, Unmanned Ground Vehicles, Military Aircraft, Naval Ships, Tactical Operations End User: Defense Forces, Tactical Command Units, Border Patrol, Intelligence Agencies, Peacekeeping Organizations |
| Companies Covered | Lockheed Martin Corporation, General Dynamics Corporation, BAE Systems, Thales Group, Rheinmetall AG, Raytheon Technologies Corporation, Curtiss-Wright Corporation, Leonardo S.p.A, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vetronics Market Strategic Shifts & Innovations
A fundamental shift toward software-defined vehicle capabilities is redefining vetronics architecture. The convergence of sensor, communication, and processing functions onto a common computing backbone enables rapid capability updates independent of hardware replacement cycles.
Edge computing hardware, including AI accelerators, provides powerful local processing for onboard sensor data. Unmanned ground vehicle programs are rapidly adopting this technology to enable autonomous navigation and target recognition. This adoption is hybridizing the vehicle's function, transforming it from a mere platform into an intelligent, networked node capable of independent decision support on the tactical edge.
NATO Standardization Agreements, particularly STANAG 4754 which codifies the Generic Vehicle Architecture, are compelling a move towards open systems. This forces suppliers to design components with standard physical and logical interfaces, breaking vendor lock-in. The combat management systems segment is most directly impacted, now required to integrate with diverse third-party applications and hardware from allied nations.
Defense acquisition models are evolving from single-prime vehicle contracts to a "best-of-breed" component procurement strategy. This allows military buyers to select superior individual subsystems, like radios or displays, from different specialized vendors. This purchasing behavior is prominent in US and UK modernization efforts, leveraging open standards to foster competition.
Vetronics Market Segmentation
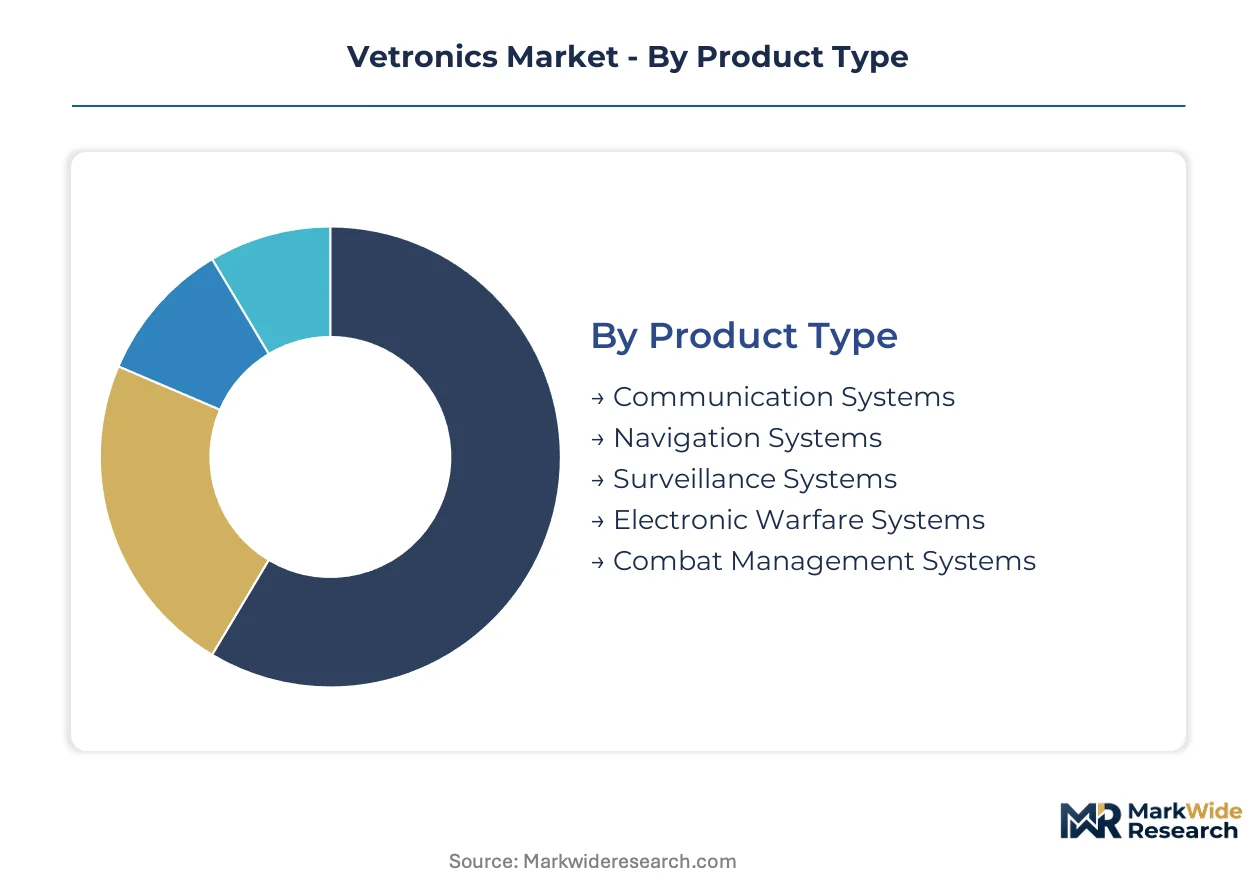
The Vetronics Market segmentation provides a granular view of distinct product types, underlying technologies, diverse applications, and specific end-user groups. This detailed breakdown helps identify areas of concentrated demand and specialized requirements within military vehicle electronics.
Product Type:
The after-sales service intensity within product types varies significantly, driven by system complexity and operational criticality.
- Communication Systems:Integrated radio and data link solutions provide secure, real-time voice and data exchange between vehicles and command centers. Demand concentrates in US and UK modernization programs for robust interoperability.
- Combat Management Systems:Platforms integrate sensor data, weapon control, and situational awareness for a unified operational picture. Demand is high in Eastern European nations for coordinated tactical engagements.
- Navigation Systems:Provide precise positioning, timing, and heading for vehicle movement, often integrating GPS/GNSS.
- Surveillance Systems:Cameras, thermal imagers, and acoustic sensors enhance crew's ability to detect and track threats.
- Electronic Warfare Systems:Detect, jam, and deceive enemy signals, providing critical self-protection for military platforms.
By volume, Communication Systems leads the market. By growth pace, Combat Management Systems is ahead.
Technology:
Technology segmentation highlights the diverse methods employed to achieve critical vetronics functions across various military applications.
- Radar:Active sensor systems emit radio waves to detect and track targets, providing long-range surveillance and fire control. Demand concentrates in unmanned ground vehicles for autonomous navigation.
- Thermal Imaging:Passive sensors create images based on heat signatures, enabling detection in low-light or obscured conditions. Modernization in the United States drives demand for enhanced night vision.
- Lidar:Optical remote sensing uses pulsed laser light to generate precise 3D maps for navigation and object detection.
- Signal Processing:Manipulates analog and digital signals from sensors, enhancing data quality and extracting intelligence.
- Electronic Countermeasures:Actively disrupt enemy electronic systems, protecting vehicles from guided munitions and surveillance.
- Optoelectronics:Combines optics and electronics to develop sensors and displays, providing high-fidelity visual information.
Supply concentration for Radar technology is high due to specialized manufacturing requirements. Conversely, Optoelectronics benefits from a more diversified supplier base.
Application:
The cost tier for vetronics applications reflects the complexity, integration requirements, and mission-criticality associated with each platform type.
- Armored Vehicles:Represents the traditional and largest application for vetronics, encompassing tanks and infantry fighting vehicles. Demand is robust in the United States and UK for retrofit programs.
- Unmanned Ground Vehicles:Vetronics for UGVs focuses on compact, energy-efficient systems for autonomous navigation and remote control. Expanding UGV deployment creates significant demand.
- Military Aircraft:Integrates communication, navigation, and targeting systems, ensuring mission effectiveness.
- Naval Ships:Involves complex integrated bridge systems and communication suites for maritime operations.
- Tactical Operations:Includes portable and deployable vetronics solutions supporting dismounted troops.
Customer types for Armored Vehicles are typically national defense ministries. Unmanned Ground Vehicles attract a broader range of defense procurement agencies.
End User:
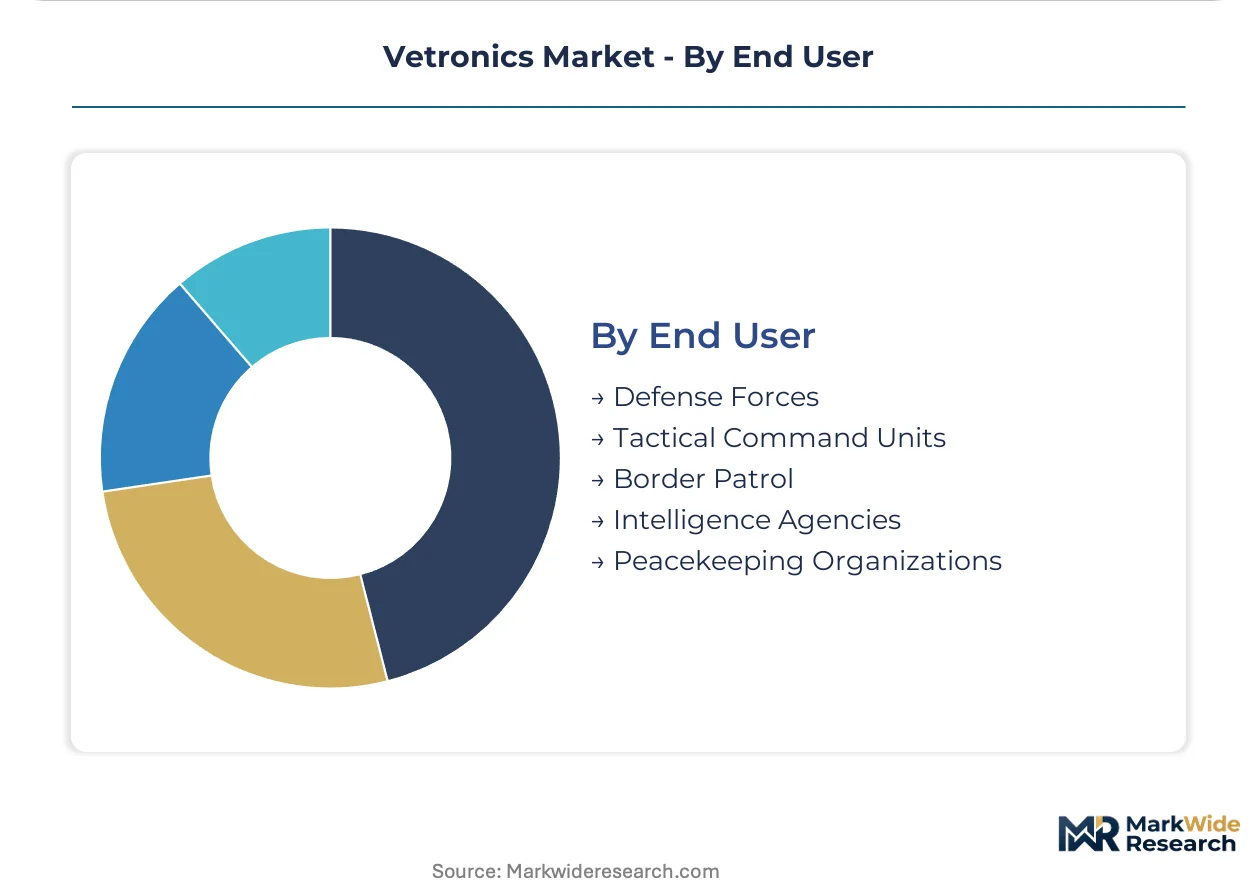
End-user maturity in vetronics adoption varies significantly, influencing procurement cycles and the demand for advanced, integrated solutions.
- Defense Forces:National defense forces are primary end-users, procuring vetronics for their military vehicle fleets. Modernization mandates from the US military drive substantial investment.
- Tactical Command Units:Require highly integrated vetronics for real-time situational awareness and command-and-control. Increased military budgets in Eastern European nations fuel demand.
- Border Patrol:Utilizes vetronics for surveillance, communication, and navigation in ground vehicles.
- Intelligence Agencies:Demand highly secure, specialized vetronics for covert surveillance and electronic intelligence.
- Peacekeeping Organizations:Supports peacekeeping missions through reliable communication, navigation, and situational awareness.
Margin profiles for Defense Forces contracts are often stable due to long-term programs. Intelligence Agencies, however, command higher margins for specialized, low-volume solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A robust defense industrial base, particularly in key ground vehicle manufacturing hubs, underwrites global vetronics market development. National security priorities and ongoing military modernization efforts in several countries drive significant demand for advanced electronic systems. This market development is concentrated in areas with established defense spending and strategic procurement programs.
United States
National armored vehicle modernization programs and expanding Unmanned Ground Vehicle deployment create substantial demand in the United States. The Department of Defense mandates open architecture standards, such as the US Army's VICTORY (Vehicular Integration for C4ISR/EW Interoperability) standard, to ensure system interoperability. Major defense contractors in states like Virginia and Texas actively develop and integrate next-generation vetronics solutions.
United Kingdom
Ongoing armored vehicle upgrade initiatives and a strong emphasis on interoperability drive the United Kingdom vetronics market. The Ministry of Defence actively promotes the Generic Vehicle Architecture (GVA) framework to reduce vendor lock-in and lifecycle costs. Defense technology clusters around cities like Bristol and Farnborough lead innovation in modular vetronics components.
Poland
Increased military budgets and new procurements of armored vehicles fuel demand for vetronics systems in Poland. The nation's defense spending, aligned with NATO commitments, prioritizes advanced combat management and communication systems. Defense industry hubs in Warsaw and Poznań are expanding their capabilities to support domestic and regional ground vehicle programs.
South Korea
Significant investments in defense technology and the development of indigenous armored platforms propel the South Korean vetronics market. The Defense Acquisition Program Administration (DAPA) supports local industry in developing advanced communication and surveillance systems. Technology parks in Daejeon and Gyeonggi province foster research and development in integrated electronic warfare capabilities.
Saudi Arabia
Modernization of ground forces and strategic defense initiatives drive vetronics demand in Saudi Arabia. The Kingdom's Vision 2030 aims to localize defense manufacturing, encouraging technology transfer and domestic production. Riyadh and Jeddah are emerging centers for defense technology integration, focusing on enhancing situational awareness and vehicle survivability.
Vetronics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical subsystems for military vehicles. The vetronics market exhibits a tiered structure, with a few large prime contractors dominating vehicle integration and numerous specialized firms supplying modular components. Strategic partnerships and technology licensing are dominant competitive moves, enabling smaller innovators to access broader defense programs.
Within the prime contractor archetype, Lockheed Martin Corporation and BAE Systems exemplify companies with deep integration into major defense programs. Thales Group, a diversified European conglomerate, occupies a position leveraging its broad portfolio in communication and surveillance systems. These entities often serve as lead system integrators, managing complex projects and ensuring interoperability across diverse subsystems.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| BAE Systems |
| Thales Group |
| Rheinmetall AG |
| Raytheon Technologies Corporation |
| Curtiss-Wright Corporation |
| Leonardo S.p.A |
| Saab AB |
| Others |
Cost & Logistics Intelligence
Specialized component manufacturing for military-grade semiconductors and optoelectronics concentrates margin pools within upstream suppliers. This concentration impacts the final system cost and the flexibility of prime contractors to source diverse components.
Pricing Analysis
US MIL-STD specifications dictate the pricing tier structure for many vetronics components, reflecting stringent qualification requirements. Pricing models often involve contract-based long-term offtake agreements with defense ministries. Price differentiation stems from the level of customization for specific platforms and the provision of integrated after-sales service. Pricing pressure arises from military mandates for open architectures, fostering competition among modular component suppliers. Intelligence Agencies typically exhibit the least price sensitivity, while modernization programs seeking cost efficiency show higher sensitivity.
Supply Chain Analysis
Upstream feedstock for advanced vetronics components primarily originates from specialized manufacturers in the United States, South Korea, and Germany. The supply chain draws from critical inputs like high-performance integrated circuits, ruggedized displays, and specialized optical sensors. Component obsolescence presents a structural supply chain risk, necessitating costly redesigns for long-lifecycle military platforms. Distribution of vetronics systems primarily runs through direct channels to prime defense contractors and national defense procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vetronics Market presents a high-growth disruption, driven by the widespread adoption of open architecture standards like GVA and VICTORY. These standards are fundamentally reshaping how military vehicle electronics are designed, procured, and upgraded.
For Market Incumbents: Harden core competencies in systems integration, particularly for complex software-defined vehicle architectures. Deepen existing integration with major defense programs in the United States and the United Kingdom through co-development initiatives. Invest in R&D for AI-enabled sensor fusion to counter the threat from specialized niche players. Bolster certification capabilities against evolving military standards to maintain market access.
For New Entrants and Emerging Players: Build out specialized capabilities in modular, open-architecture compliant components for Unmanned Ground Vehicles. Target emerging defense markets in Eastern Europe and Southeast Asia, where modernization programs are accelerating. Focus on providing cost-effective, COTS-based vetronics solutions for specific subsystems like advanced displays or compact communication modules. Leverage agile development methodologies to outpace traditional defense contractors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized component manufacturers and software-defined vetronics developers, offering attractive long-term viability. The market benefits from sustained military modernization spending and the expansion of autonomous ground platforms. Target firms with strong intellectual property in sensor fusion, cybersecurity for networked vehicles, or expertise in GVA/VICTORY implementation. The signal to watch is the increasing share of open-architecture compliant systems in new procurement contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Open Architecture R&D | Accelerates compliance with GVA and VICTORY, reducing vendor lock-in for defense agencies. |
| Pursue UGV Vetronics Specialization | Captures expanding demand from autonomous ground vehicle programs in the United States. |
| Localize Production in Emerging Markets | Supports defense localization efforts in countries like Saudi Arabia, fostering new market access. |
| Develop AI-Enhanced Sensor Fusion | Provides superior situational awareness and automated threat detection for vehicle crews. |
| Secure Long-Term Service Contracts | Ensures recurring revenue streams and deepens integration with defense force maintenance programs. |
Research Approach
Operator-level perspectives from defense procurement officers, systems integrators, vetronics engineers, and military vehicle commanders anchored the qualitative base. Primary interviews were cross-referenced with extensive secondary research, including US MIL-STD specifications, NATO STANAGs, defense ministry budget reports, and industry association publications. The methodology employed both bottom-up market sizing and top-down validation to ensure data accuracy.
Scenario-bracketing framing informed the analytical framework across the analysis window, considering various geopolitical and technological trajectories. Segmentation dimensions modeled included product type, underlying technology, diverse applications, end-user groups, and regional defense spending patterns. Compound annual growth rates were derived from historical trends, expert consensus, and projected modernization program timelines, incorporating military budget allocations and armored vehicle production forecasts.
Stress conditions across military budget fluctuations and technology adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding geopolitical stability and the pace of technological integration within defense programs. Cross-checking against national defense white papers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Autonomous Aircraft Market