
 Unmanned Sea System Market | 2026-2036
Unmanned Sea System Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Sea System Market Analysis
Modular payload architecture is recalibrating buyer choice across the unmanned sea system sector. Kongsberg Gruppen ASA leverages its Nordic maritime heritage to dominate autonomous underwater vehicle propulsion design. L3Harris Technologies, Inc. sustains competitive position through integrated sonar and communications suites for naval end users. BAE Systems plc anchors its portfolio in British defense procurement cycles with mine countermeasure and reconnaissance configurations.
Unmanned sea systems comprise self-propelled marine platforms operating without continuous human presence aboard, typically incorporating pressure-rated hulls, autonomous navigation algorithms, and multi-sensor arrays for submerged or surface missions. These systems execute military reconnaissance, subsea infrastructure inspection, and oceanographic data collection in environments hazardous to crewed vessels. Unmanned underwater vehicles lead product type demand due to deep-diving requirements for seabed mapping and anti-submarine warfare. Autonomous navigation technology commands premium positioning as navies reduce operator workload and satellite link dependency. Research applications represent a growing segment as academic institutions deploy gliders for long-duration ocean monitoring.
The US Navy and DOD shape procurement through unmanned maritime autonomy standards and cybersecurity mandates for networked undersea operations. NATO STANAG protocols establish interoperability benchmarks that constrain non-compliant suppliers from allied defense contracts. Lloyd's Register and Bureau Veritas classification rules increasingly address autonomous vessel certification for commercial shipping integration. Stakeholders must monitor how emerging liability frameworks for uncrewed maritime collisions alter insurance and operator accountability structures.
Market Dynamics
Autonomous navigation algorithms are compressing operator-to-vehicle ratios across naval fleets, forcing procurement officers to revalue platform endurance and sensor fusion capabilities over raw hull specifications.
Growth Catalysts
- NATO STANAG interoperability protocols:Allied navies mandate common communication frameworks, compelling non-compliant suppliers to retrofit systems for defense contract eligibility.
- Offshore wind farm inspection:Energy operators in the North Sea deploy autonomous underwater vehicles for subsea cable monitoring, creating commercial demand independent of military cycles.
- Sensor miniaturization:Shrinking sonar and optical payloads enable smaller hull designs, reducing per-unit procurement costs for research institutions.
Market Restraints
- Lithium-sulfur battery supply concentration:Pressure-rated energy storage depends on Chinese rare earth processing, exposing European and North American builders to input volatility.
- Deep-sea pressure hull fabrication:Only three certified suppliers globally produce titanium alloy spheres rated below 6,000 meters, constraining production scaling.
- Undersea spectrum allocation:ITU frequency coordination delays acoustic modem certification, slowing cross-border fleet deployments.
Strategic Opportunities
- Norwegian continental shelf expansion:Equinor and Aker BP tender long-term autonomous inspection contracts for subsea infrastructure aging beyond crewed dive limits.
- Glider-oceanography convergence:Academic institutions in the United Kingdom deploy buoyancy-driven platforms for multi-month climate monitoring, opening civilian procurement channels.
- EU Green Deal maritime incentives:Carbon-reduction credits for uncrewed vessels displace crewed survey ships in European Economic Zone operations.
Industry Challenges
- Autonomy software certification:Lloyd's Register and Bureau Veritas lack harmonized test protocols for unsupervised collision avoidance, prolonging type-approval timelines.
- Subsea communications integration:Satellite link dropouts at high latitudes force navies to maintain expensive acoustic gateway networks for command continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Sea System Market |
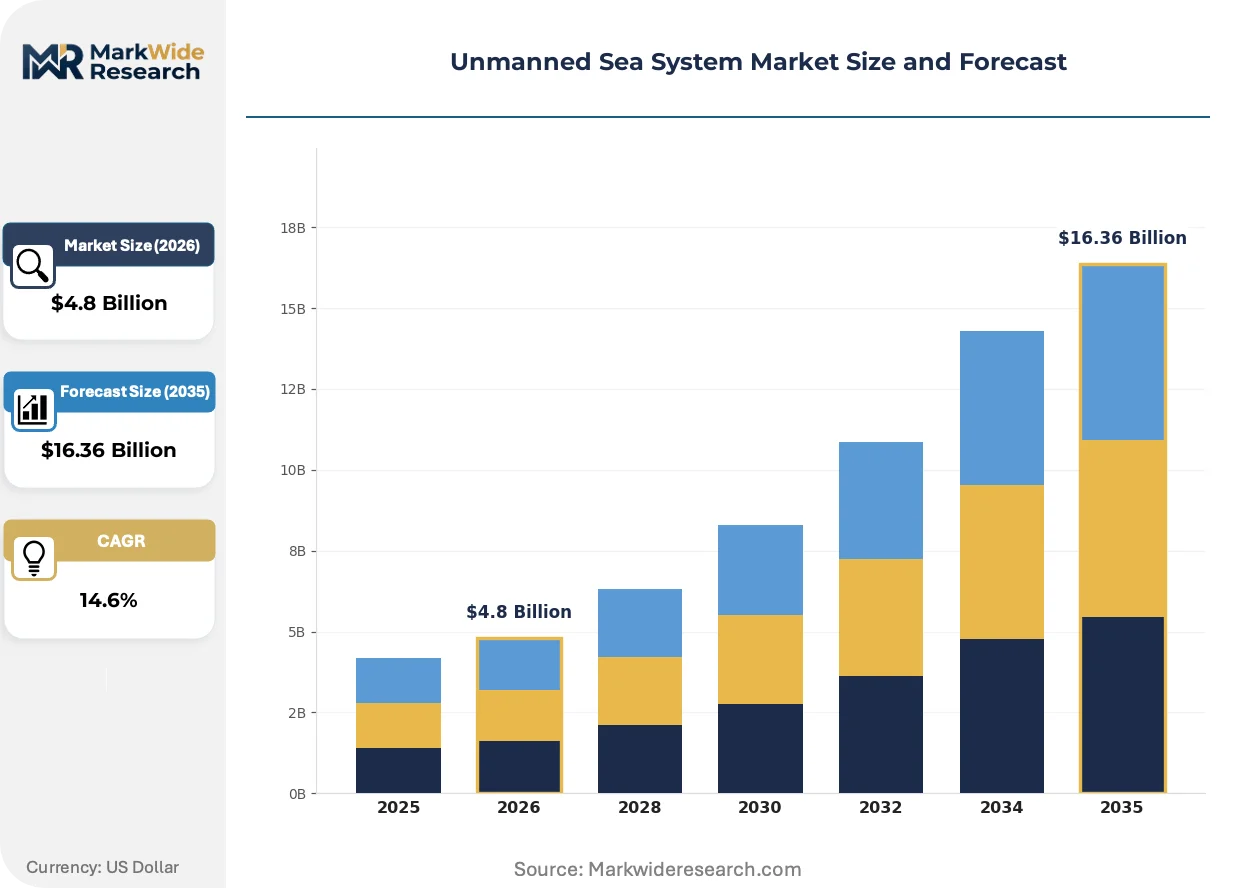
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Surface Vehicles, Unmanned Underwater Vehicles, Hybrid Systems, Aerial Drones Technology: Remote Control, Autonomous Navigation, Sensor Integration, Communication Systems Application: Surveillance, Research, Environment Monitoring, Search and Rescue End User: Military, Commercial Shipping, Environmental Agencies, Research Institutions |
| Companies Covered | Kongsberg Gruppen ASA, L3Harris Technologies, Inc., BAE Systems plc, General Dynamics Corporation, Teledyne Technologies Incorporated, Lockheed Martin Corporation, Northrop Grumman Corporation, Oceaneering International, Inc., The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Sea System Market Emerging Trajectories
Edge computing architectures are redistributing processing loads from shore stations to onboard systems, enabling real-time decision-making in GPS-denied environments without tethered data links.
Distributed acoustic sensing is decentralizing seabed surveillance networks. Fiber-optic cables previously used for telemetry now double as passive listening arrays, with the US Navy and British Royal Navy retrofitting existing infrastructure. This compression of dedicated sensor hardware reduces fleet capital requirements while expanding coverage footprints.
EU AI Act liability frameworks are reclassifying autonomous maritime systems as high-risk applications, triggering mandatory conformity assessments for navigation algorithms. Naval procurement offices in France and Germany now require explainable decision logs for collision avoidance software, slowing deployment timelines but creating certification barriers for non-European suppliers.
Leasing models for survey-grade autonomous underwater vehicles are displacing outright purchase in commercial geophysics. PGS and TGS in Norway now contract vessel-hours rather than owning platforms, transferring obsolescence risk to Kongsberg and L3Harris. This shift concentrates in the North Sea where project durations match typical lease windows.
Unmanned Sea System Market Segmentation
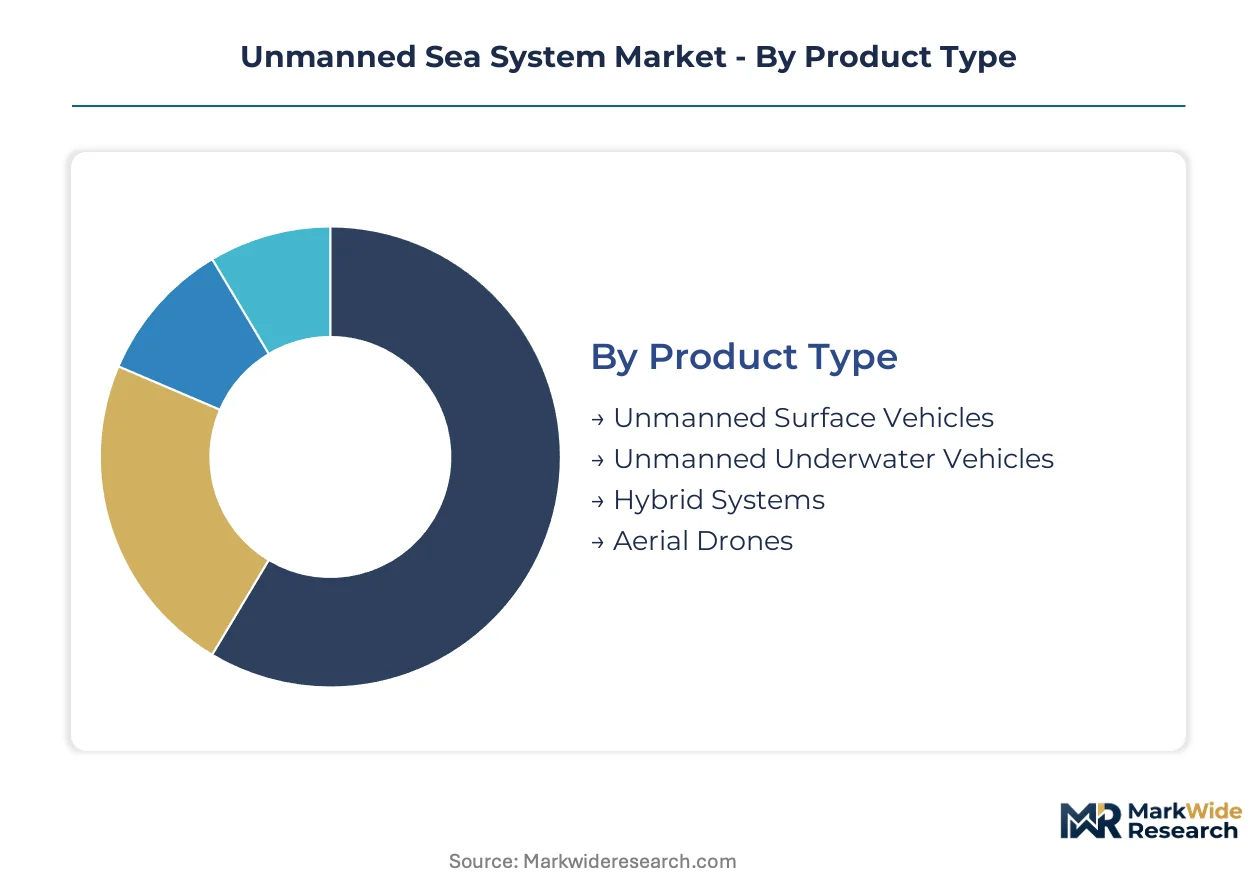
Segmentation in unmanned sea systems reveals how capital deployment, mission requirements, and procurement authority fragment across platform types and operational domains. Buyers allocate budgets differently based on pressure rating needs, autonomy levels, and regulatory compliance burdens.
Product Type:
Capital intensity peaks with deep-rated pressure hulls and integrated autonomy stacks, while surface platforms spread investment across sensor suites and communications infrastructure.
- Unmanned Underwater Vehicles:Self-propelled submerged platforms rated for depths exceeding 6,000 meters incorporate titanium alloy pressure spheres and lithium-sulfur battery arrays. Naval procurement in the United States and Norway concentrates here for anti-submarine warfare and seabed mapping missions where crewed alternatives face physiological limits.
- Unmanned Surface Vehicles:Wave-piercing hulls and solar-electric propulsion systems dominate persistent maritime surveillance applications. Commercial shipping operators in the North Sea deploy these for route optimization and emissions monitoring under EU Green Deal frameworks.
- Hybrid Systems:Cross-domain platforms transition between surface and submerged operations using variable-buoyancy architectures.
- Aerial Drones:Rotary-wing unmanned aircraft extend over-the-horizon targeting and communications relay for coordinated fleet operations.
Most installed capacity flows through Unmanned Underwater Vehicles. Expansion is steepest in Unmanned Surface Vehicles.
Technology:
Procurement officers weight technology segments by operator-to-vehicle ratio targets and satellite dependency reduction mandates.
- Autonomous Navigation:Onboard decision algorithms process multi-beam sonar and optical sensor feeds without continuous shore-based oversight. NATO STANAG protocols and EU AI Act liability frameworks now mandate explainable decision logs for collision avoidance software, extending certification timelines but creating compliance barriers for non-European suppliers.
- Sensor Integration:Miniaturized synthetic aperture sonar and hyperspectral cameras compress payload volumes while expanding detection ranges. Research institutions in the United Kingdom prioritize this capability for long-duration oceanographic glider deployments.
- Communication Systems:Acoustic modem networks and satellite link redundancy maintain command continuity in GPS-denied environments.
- Remote Control:Tethered or line-of-sight operation modes persist in mine countermeasure applications requiring human-in-the-loop authorization.
Autonomous Navigation commands the largest share of R&D expenditure. Sensor Integration is gaining share fastest as payload miniaturization accelerates platform downsizing.
Application:
Mission type determines procurement channel—defense budgets dominate surveillance while research grants and commercial contracts split environmental monitoring.
- Surveillance:Subsea infrastructure protection and anti-submarine warfare drive classified procurement through national defense ministries. Distributed acoustic sensing networks now repurpose existing fiber-optic cables as passive listening arrays, reducing dedicated hardware capital requirements for the US Navy and British Royal Navy.
- Environment Monitoring:Buoyancy-driven gliders execute multi-month climate data collection missions. Academic institutions deploy these for carbon cycle research, with EU Green Deal maritime incentives displacing crewed survey vessels in European Economic Zone operations.
- Research:Oceanographic institutions contract for bathymetric mapping and benthic habitat assessment.
- Search and Rescue:Rapid-deployment surface platforms extend visual and thermal detection coverage in coastal emergency response.
Surveillance absorbs the majority of defense-linked procurement. Environment Monitoring is expanding most quickly as climate research funding diversifies beyond traditional naval customers.
End User:
Customer type segmentation maps to contract structure—military programs favor multi-year development agreements while commercial operators increasingly prefer leased vessel-hours.
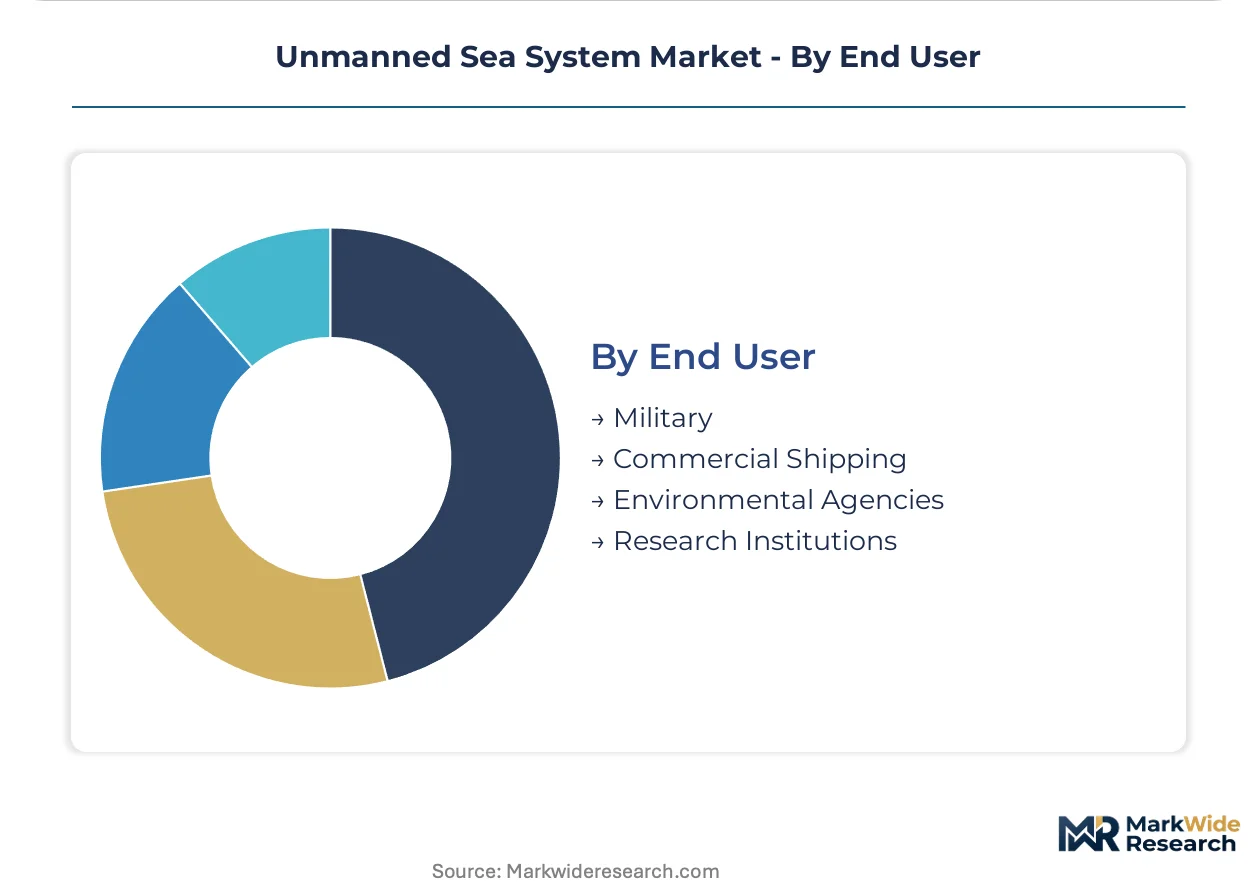
- Military:National navies and coast guards procure through defense procurement offices with cybersecurity mandates for networked undersea operations. The US Navy and DOD unmanned maritime autonomy standards shape system requirements, with NATO interoperability benchmarks constraining non-compliant suppliers from allied contracts.
- Research Institutions:Universities and oceanographic institutes deploy gliders and autonomous underwater vehicles for long-duration data collection. Leasing models from Kongsberg and L3Harris now displace outright purchase in this segment, transferring obsolescence risk to equipment vendors.
- Commercial Shipping:Energy operators and maritime logistics companies automate hull inspection and route survey functions.
- Environmental Agencies:Government conservation bodies monitor marine protected areas and pollution incidents.
Military end users anchor procurement volume. Research Institutions are climbing the fastest as academic deployment scales and financing models shift toward operational expenditure structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous underwater vehicle development traces its commercial roots to Norwegian fjord testing facilities in the 1990s, where Kongsberg pioneered pressure-rated hull designs for North Sea oil inspection. Naval research programs in the United States and United Kingdom subsequently scaled defense applications, establishing the tripartite demand centers that now structure procurement flows.
United States
The US Navy's Unmanned Maritime Autonomy standards and DOD cybersecurity mandates shape system requirements for anti-submarine warfare platforms. The Department of Defense procurement offices enforce NATO interoperability benchmarks that constrain non-compliant suppliers from allied contracts. Greater San Diego and Newport News host the primary naval R&D clusters where General Dynamics and Northrop Grumman anchor submarine surveillance program development.
Norway
Equinor and Aker BP tender long-term autonomous inspection contracts for subsea infrastructure aging beyond crewed dive limits on the Norwegian continental shelf. The Norwegian Maritime Authority applies Lloyd's Register classification rules for autonomous vessel certification in commercial shipping integration. Kongsberg's headquarters in Kongsberg city anchors a supplier ecosystem that exports propulsion systems to NATO navies and offshore energy operators.
United Kingdom
British Royal Navy mine countermeasure programs and academic oceanographic institutions drive dual demand for reconnaissance configurations and long-duration climate monitoring gliders. The UK Maritime and Coastguard Agency implements EU AI Act liability frameworks that mandate explainable decision logs for collision avoidance software. Plymouth and Southampton harbor research clusters where Teledyne Technologies and university consortia deploy buoyancy-driven platforms for carbon cycle research.
France
Naval Group procurement and Ifremer research programs sustain demand for deep-rated pressure hulls and seabed mapping systems in the Bay of Biscay and Mediterranean. The French Maritime Authority enforces EU Green Deal maritime incentives that award carbon-reduction credits for uncrewed vessels displacing crewed survey ships. Toulon and Brest concentrate defense-industrial capacity where Thales and Safran supply sensor miniaturization components.
Japan
Japan Maritime Self-Defense Force anti-submarine warfare requirements and deep-sea resource exploration programs drive procurement of titanium alloy pressure spheres rated below 6,000 meters. METI's dual carbon goals channel public research funding toward battery efficiency improvements for long-duration missions. Yokosuka and Kobe host the primary industrial clusters where Mitsubishi Heavy Industries and Kawasaki Heavy Industries fabricate hull structures.
Unmanned Sea System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across pressure-rating certification and autonomy software integration depth. The vendor base concentrates around three tiers: integrated defense conglomerates with naval procurement relationships, specialized maritime technology firms with Nordic heritage, and emerging commercial survey operators leasing vessel-hours rather than owning platforms. Strategic archetypes include full-stack system integrators, component specialists in sonar and propulsion, and service-based operators transferring obsolescence risk to clients. Dominant competitive moves encompass portfolio diversification into hybrid surface-submerged platforms and strategic partnerships with offshore energy operators for long-term inspection contracts.
Within the integrated defense tier, Kongsberg Gruppen ASA and L3Harris Technologies occupy positions that exemplify divergent geographic anchoring strategies. Kongsberg represents the Nordic heritage archetype, leveraging proximity to North Sea energy operators and Norwegian naval procurement cycles. L3Harris exemplifies the US defense-contractor model, sitting within the Pentagon's unmanned maritime autonomy standards framework. BAE Systems plc anchors the British defense-procurement vector, positioned within mine countermeasure and reconnaissance configuration markets tied to Royal Navy modernization programs. These three entities collectively illustrate how national industrial policy shapes competitive positioning in pressure-rated autonomous platforms.
| Leading Market Players |
|---|
| Kongsberg Gruppen ASA |
| L3Harris Technologies, Inc. |
| BAE Systems plc |
| General Dynamics Corporation |
| Teledyne Technologies Incorporated |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Oceaneering International, Inc. |
| The Boeing Company |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed defense contractors and Nordic family-owned maritime specialists anchor supply discipline through long-cycle procurement contracts, insulating premium-tier pricing from commodity volatility while compressing margins in commercial leasing segments.
Pricing Analysis
Project-based contracting with multi-year service agreements dominates defense procurement, while vessel-hour leasing spreads through commercial geophysics. Price differentiation rests on pressure-rating certification depth and autonomy software explainability under EU AI Act mandates. Cost compression in surface-platform tiers intensifies as energy operators consolidate inspection spend. Research institutions exhibit highest price sensitivity; navies with NATO STANAG mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements for titanium alloy pressure hulls and lithium-sulfur battery arrays compel builders to qualify suppliers across Norway, Japan, and the United States. Raw material dependencies center on Chinese rare earth processing for high-density energy storage and Russian-origin titanium sponge for deep-rated spheres. Single-source vulnerability in acoustic modem chipsets threatens cross-border fleet deployments. Distribution runs through defense procurement offices and energy operator tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
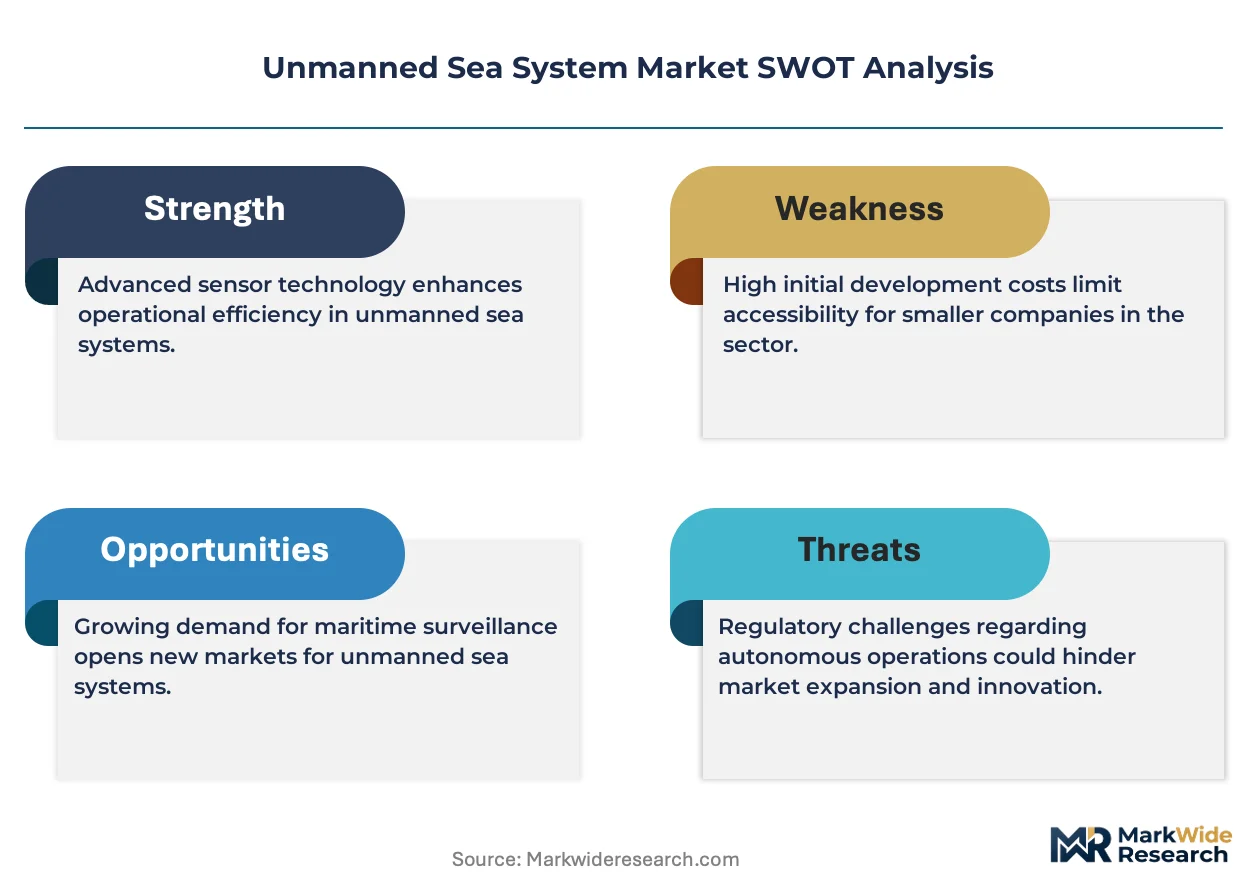
Margin expansion in unmanned sea systems derives from sensor miniaturization reducing per-unit payload costs and premium-tier autonomy software commanding compliance-linked pricing power.
For Market Incumbents: Acquire certified titanium hull fabrication capacity to secure supply continuity against single-source concentration. Lock in multi-year autonomy software certification pipelines with Lloyd's Register and Bureau Veritas before EU AI Act assessments harden. Defend against emerging commercial leasing operators by embedding predictive maintenance modules that transfer obsolescence risk back to vendors. For New Entrants and Emerging Players: Edge computing architectures for GPS-denied navigation offer entry into naval retrofit programs. White-space concentrates in buoyancy-driven glider oceanography for UK academic institutions and Norwegian continental shelf inspection contracts. Go-to-market through operational expenditure structures displaces capital-heavy platform sales. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists in sonar miniaturization and propulsion systems lacking full-stack integration. Long-term viability favors suppliers with NATO STANAG compliance and offshore energy operator relationships. Watch Norwegian continental shelf tender volumes as inflection signal for commercial demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Hull Certification Investment | Deep-rating approval with Lloyd's Register unlocks naval procurement eligibility. |
| Autonomy Software Conformity Assessment | EU AI Act compliance creates defensible pricing tiers for European defense contracts. |
| Offshore Energy Partnership | Long-term inspection agreements with Equinor anchor revenue visibility. |
| Sensor Miniaturization R&D | Shrinking sonar payloads enable smaller hull designs with lower per-unit costs. |
| Leasing Model Expansion | Vessel-hour contracting transfers obsolescence risk from PGS and TGS to vendors. |
Methodological Framework
Direct dialogue with naval program officers, autonomous systems engineers, offshore energy procurement leads, and maritime classification surveyors grounded qualitative insights. Secondary validation drew from NATO STANAG documentation, US Navy unmanned maritime autonomy standards, SEC filings from listed defense contractors, and Lloyd's Register certification registries. Bottom-up platform deployment tallies triangulated against top-down defense budget appropriations.
Installed base projections and revenue estimates across the modeling period reflect segmentation by platform type, autonomy level, pressure rating tier, and end-user procurement channel. CAGRs were derived from historical fleet deployment trajectories and announced procurement timelines. Industry-specific inputs included NATO interoperability mandate schedules and Norwegian continental shelf infrastructure aging curves.
The model holds under stable defense procurement cycles and continued EU Green Deal maritime incentive enforcement; deviation in lithium-sulfur battery supply chain disruption or ITU acoustic spectrum allocation delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Rotary-Wing Lidar Drone Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market