
 Autonomous Drone Market | 2026-2036
Autonomous Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Drone Market Insights
Market Context
Modular payload configurations is rebalancing buyer choice across defense and commercial segments, allowing operators to swap sensors, communications packages, and power modules without platform replacement. Anduril Industries leverages vertical integration in autonomous software and hardware to sustain pricing power in military contracts. Skydio anchors its position through advanced computer vision stacks that differentiate consumer and enterprise offerings. DJI Innovations dominates manufacturing scale across rotary-wing categories, controlling component sourcing for global distribution networks.
Technical Definition and Structural Segments
An autonomous drone is an unmanned aerial vehicle capable of self-directed flight, navigation, and mission execution without continuous human piloting, typically integrating inertial measurement units, GPS/GNSS receivers, and onboard processing architectures for real-time decision-making in commercial, defense, and civilian applications. Rotary-wing systems occupy the largest installed base due to vertical takeoff flexibility and hovering precision in confined environments, while hybrid configurations represent the fastest-expanding category as operators demand extended range combined with multirotor maneuverability. AI and machine learning technology layers command concentrated R&D investment because obstacle avoidance and path optimization algorithms determine operational safety certifications and insurance underwriting standards.
Regulatory Framework and Outlook
FAA Part 107 and emerging beyond-visual-line-of-sight rulemakings in the United States, alongside EASA drone regulation frameworks in Europe, shape airspace access, pilot qualification thresholds, and product liability standards that manufacturers must satisfy for market entry. ISO 21384-3 unmanned aircraft systems standards and ASTM F38 committee guidelines further codify design assurance and operational risk management requirements across jurisdictions. Stakeholders must monitor regulatory divergence between permissive experimental corridors and restrictive urban airspace policies to align certification roadmaps with addressable market expansion.
Market Dynamics
Defense procurement acceleration from agencies like the US Department of Defense is compressing development cycles and forcing dual-use technology convergence between military and commercial autonomous platforms.
Growth Catalysts
- Beyond-visual-line-of-sight rulemaking:FAA Part 107 waiver expansion in the United States is unlocking commercial operations in infrastructure inspection and agricultural monitoring corridors.
- Precision agriculture:Large-scale farm operators across Brazil and Australia are deploying autonomous spraying and mapping fleets to reduce input costs and optimize yield per hectare.
- Computer vision maturation:Onboard neural processing units are enabling real-time obstacle detection without ground station dependency, satisfying insurance underwriting requirements for autonomous flight certification.
Market Restraints
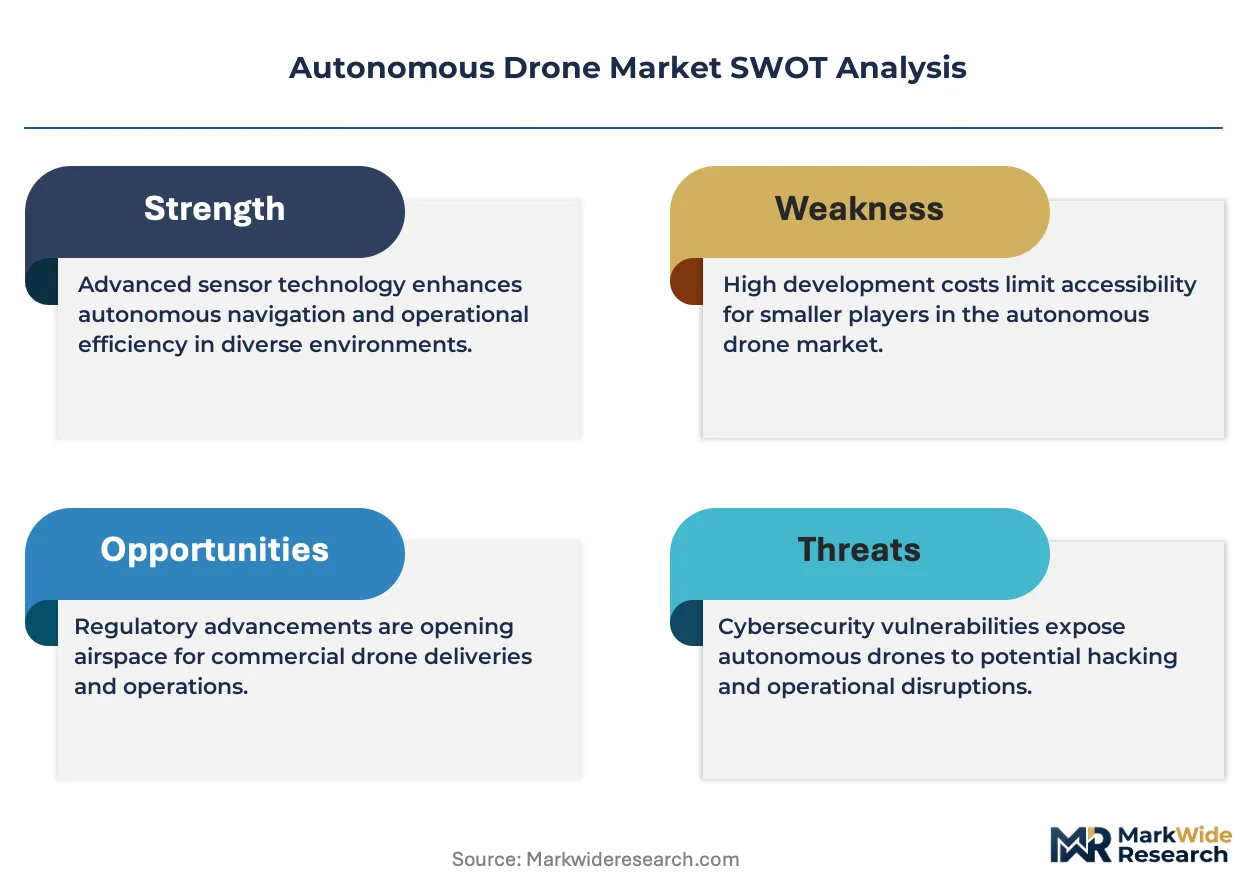
- GNSS signal vulnerability:GPS spoofing and jamming incidents near conflict zones and critical infrastructure are forcing redundant navigation investments that inflate platform costs.
- Component supply concentration:Advanced lithium-polymer battery cell production clusters in East Asian manufacturing hubs create single-source dependencies for extended-endurance platforms.
- Airspace fragmentation:Divergent national implementation of ICAO unmanned aircraft systems frameworks is multiplying certification burdens for cross-border operators.
Strategic Opportunities
- Urban air mobility corridors:Singapore and Dubai are establishing designated low-altitude highways for autonomous cargo delivery, creating regulated testbeds for beyond-visual-line-of-sight commercialization.
- Swarming coordination protocols:Integration of mesh networking with distributed AI is enabling coordinated multi-drone operations for search-and-rescue and wildfire suppression applications.
- Digital twin integration:Construction and mining operators are demanding autonomous drones that feed real-time point clouds into building information modeling systems for progress monitoring.
Industry Challenges
- Autonomy software certification:EASA's SAIL II/III operational risk categories and FAA's means-of-compliance pathways for detect-and-avoid systems are creating 18-24 month approval timelines that delay revenue recognition.
- Sensor fusion engineering:Integrating LiDAR, thermal, and hyperspectral payloads with real-time kinematic positioning requires scarce embedded systems talent concentrated in aerospace engineering clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Drone Market |
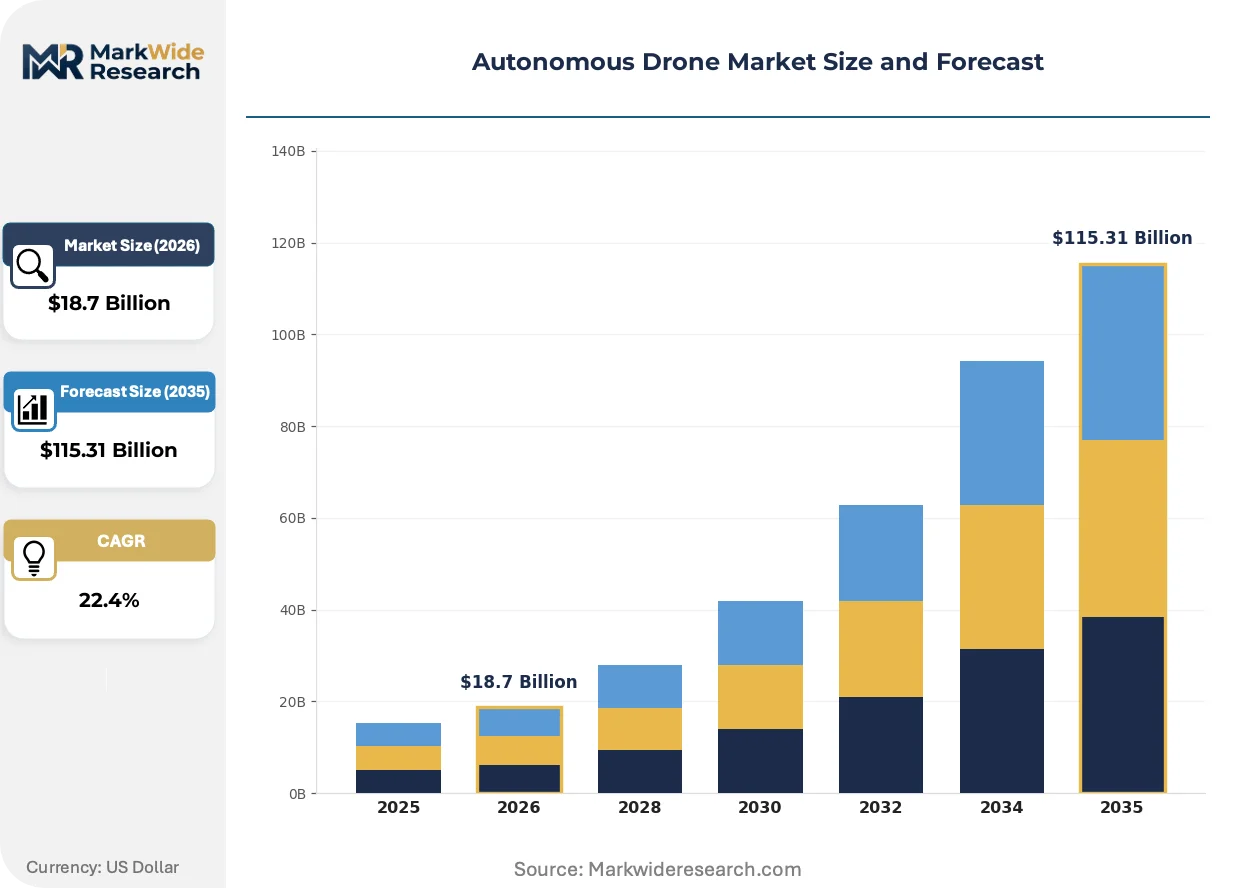
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano Drones, Micro Drones Technology: Computer Vision, LiDAR, GNSS, AI & Machine Learning, Obstacle Avoidance Application: Precision Agriculture, Infrastructure Inspection, Emergency Response, Surveying & Mapping, Security Surveillance End User: Agribusiness, Construction Firms, Disaster Management Teams, Surveying Companies, Security Agencies |
| Companies Covered | Anduril Industries, XAG, DJI Innovations, Red Cat Holdings, EHang, Skydio, Kratos Defense, Draganfly, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Drone Market Trends and Innovations
Autonomous flight architectures are converging around edge-computing substrates that reduce latency-dependent ground links, while regulatory sandboxes in multiple jurisdictions are compressing the path from experimental waiver to operational certification.
Edge AI inference engines are consolidating flight control, obstacle avoidance, and mission planning onto single-system-on-chip architectures. Defense contractors and precision agriculture operators are adopting these consolidated platforms to reduce SWaP (size, weight, and power) constraints and extend mission endurance. This consolidation is compressing the supplier base for flight computers and forcing legacy avionics vendors to pivot toward software-defined autonomy stacks.
EASA's drone regulation framework and the EU AI Act's risk-based classification for autonomous systems are imposing algorithmic transparency requirements on safety-critical flight software. Manufacturers must now document training data provenance and decision-logic interpretability for high-risk operational categories. European infrastructure inspection and emergency response segments are responding by segregating AI development teams from legacy hardware engineering functions to accelerate compliance documentation.
Equipment-as-a-service contracting is displacing capital purchase models in commercial segments with high fleet-utilization variance. Agricultural cooperatives and construction project managers are subscribing to autonomous drone capacity with per-acre or per-flight-hour pricing rather than owning depreciating hardware. This shift is most visible in Australian broadacre farming and Nordic offshore wind maintenance, where seasonal demand spikes make fixed-asset ownership economically inefficient.
Autonomous Drone Market Segmentation
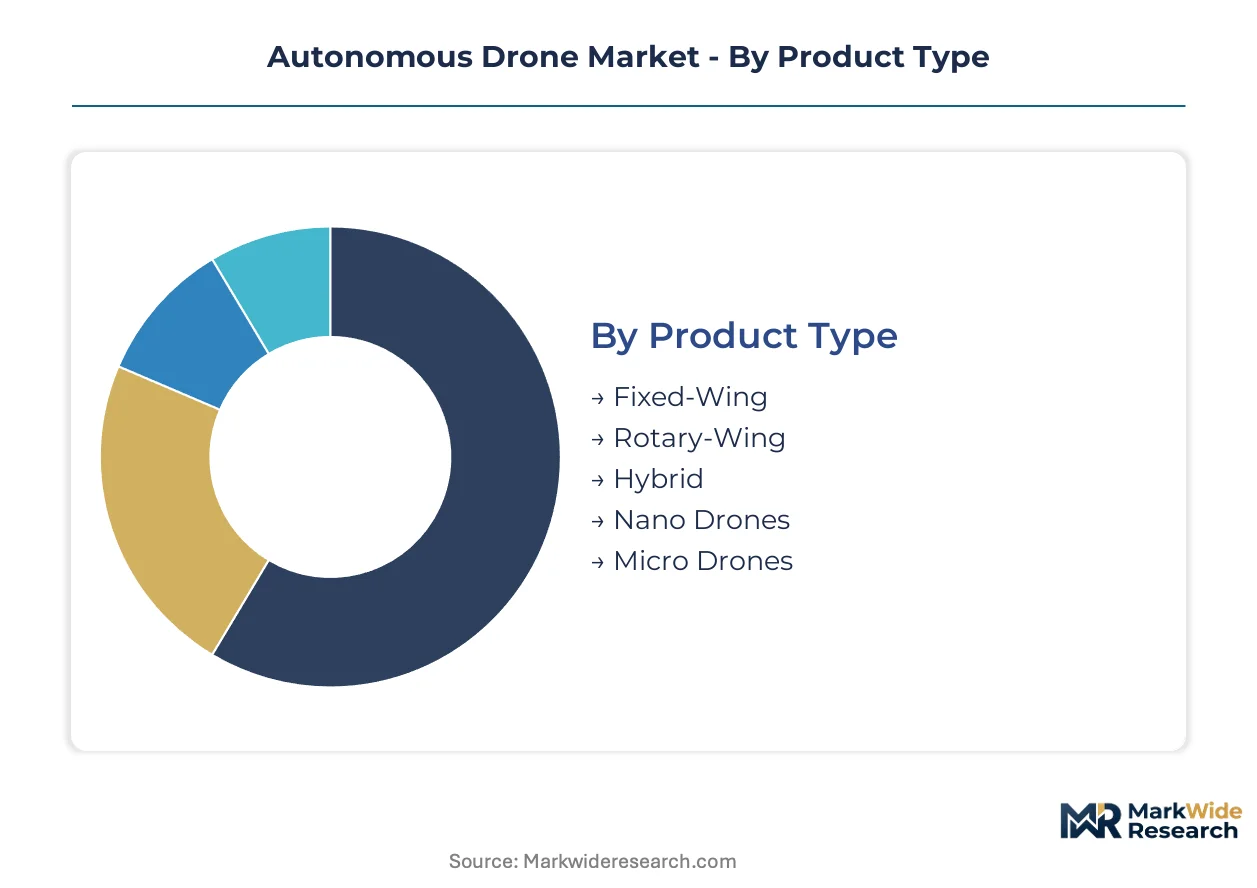
Autonomous drone procurement patterns diverge sharply across operational environments, with defense agencies prioritizing extended endurance while commercial operators emphasize payload flexibility and regulatory compliance. Understanding these segment boundaries reveals where technology investment concentrates and which buyer categories command premium pricing.
Product Type:
Buyers in this category differentiate primarily by mission duration requirements versus maneuverability constraints in confined airspace.
- Rotary-Wing:Multirotor configurations dominate vertical takeoff and hovering applications where precision positioning matters more than range. Brazilian agribusiness operators deploy these systems for autonomous spraying in irregular field geometries where fixed-wing platforms cannot operate.
- Hybrid:Tiltrotor and tail-sitter architectures combine multirotor agility with fixed-wing efficiency, attracting infrastructure inspection contractors across Australian mining corridors who require extended range without sacrificing hover capability for detailed asset examination.
- Fixed-Wing:Conventional wing designs maximize endurance for large-area surveying missions where straight-line efficiency outweighs maneuverability needs.
- Nano Drones:Sub-250 gram platforms exploit regulatory weight thresholds for reduced certification burdens in urban reconnaissance and confined-space inspection.
- Micro Drones:Pocket-sized systems serve tactical military applications and indoor emergency response where payload capacity is sacrificed for portability and acoustic discretion.
Rotary-wing systems lead volumes today; hybrid configurations are gaining share fastest.
Technology:
Investment intensity in this category tracks directly with insurance underwriting requirements and airworthiness certification timelines.
- AI & Machine Learning:Neural processing architectures enable real-time decision-making without ground station dependency. EASA's SAIL III operational risk categories now mandate algorithmic transparency documentation for training data provenance, forcing European manufacturers to segregate AI development from hardware engineering functions.
- Computer Vision:Onboard optical processing stacks anchor consumer and enterprise differentiation through obstacle detection and target tracking capabilities. Skydio's proprietary vision systems demonstrate how software-defined autonomy displaces hardware-heavy sensor payloads in price-sensitive segments.
- LiDAR:Laser ranging systems generate dense point clouds for precision mapping and digital twin integration in construction progress monitoring.
- GNSS:Multi-constellation receivers provide positioning backbone, though GPS spoofing vulnerabilities near conflict zones are forcing redundant navigation investments.
- Obstacle Avoidance:Integrated sensor fusion architectures satisfy FAA detect-and-avoid compliance pathways for beyond-visual-line-of-sight operations.
Computer vision layers anchor current installed base; AI and machine learning stacks show steepest expansion trajectory.
Application:
Commercial viability in this category hinges on regulatory sandbox access and seasonal demand predictability.
- Precision Agriculture:Autonomous spraying and multispectral mapping fleets reduce input costs for large-scale operators. Australian broadacre farming cooperatives increasingly subscribe to drone capacity through equipment-as-a-service contracts rather than owning depreciating hardware.
- Infrastructure Inspection:Automated asset examination of power lines, pipelines, and offshore wind installations replaces manual methods in hazardous environments. Nordic operators favor per-flight-hour pricing models that accommodate seasonal demand spikes without fixed-asset inefficiency.
- Emergency Response:Search-and-rescue and wildfire suppression operations leverage swarming coordination protocols with mesh networking and distributed AI.
- Surveying & Mapping:Photogrammetry and LiDAR-based topographic data collection serves construction planning and mining exploration with centimeter-level accuracy requirements.
- Security Surveillance:Perimeter monitoring and event security applications face strict operational restrictions in European urban airspace under EU AI Act risk classifications.
Precision agriculture commands largest revenue pool; infrastructure inspection climbs fastest as equipment-as-a-service models mature.
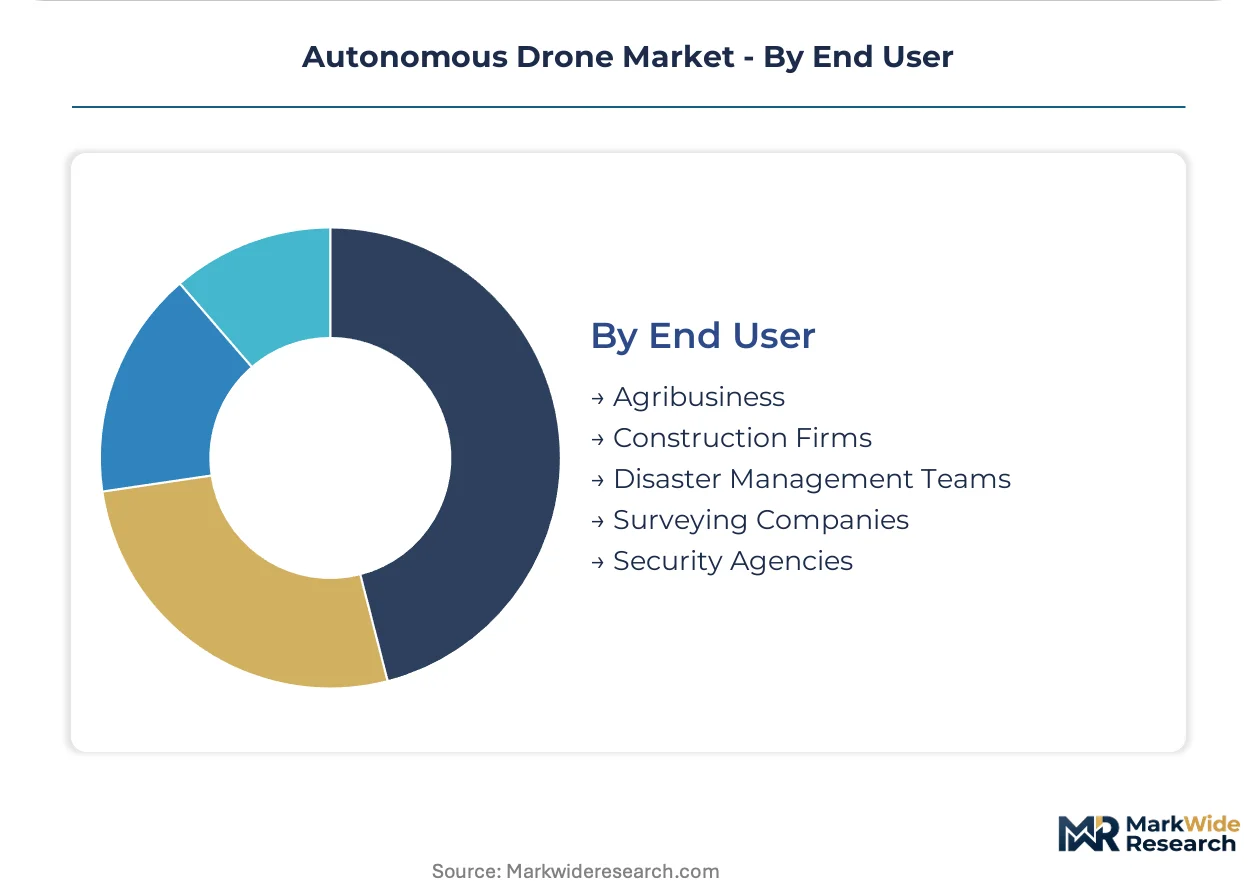
End User:
Procurement sophistication in this category separates volume buyers with dedicated flight operations from occasional users seeking outsourced capacity.
- Agribusiness:Corporate farming enterprises and agricultural cooperatives operate the largest commercial fleets, with Brazilian and Australian operators driving rotary-wing and hybrid platform demand for autonomous crop management.
- Construction Firms:Project managers integrate drone-generated point clouds directly into building information modeling systems for progress monitoring and earthwork volume calculations.
- Security Agencies:Defense and law enforcement buyers prioritize vertical integration of autonomy software and hardware to sustain pricing power in military contracts.
- Surveying Companies:Professional geospatial service providers demand real-time kinematic positioning integration with LiDAR and hyperspectral payloads for cadastral and topographic applications.
- Disaster Management Teams:Government emergency services adopt swarming protocols for coordinated multi-drone search operations in post-disaster environments.
Agribusiness dominates current procurement volumes; construction firms represent the fastest-expanding customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous drone development originated in Israeli defense laboratories during the 1980s before migrating to Silicon Valley commercialization hubs and Shenzhen manufacturing clusters. Today procurement concentrates in defense corridors and precision agriculture belts across five distinct national markets.
United States
Defense procurement from the Department of Defense and Department of Homeland Security drives demand for extended-endurance platforms with swarming coordination capabilities. FAA Part 107 waivers and emerging beyond-visual-line-of-sight rulemakings reshape operational permissions for commercial operators. Austin and San Diego anchor dual-use technology development where military contractors adapt battlefield autonomy stacks for agricultural and infrastructure inspection applications.
China
Domestic precision agriculture demand across Xinjiang cotton belts and Hubei rice paddies absorbs rotary-wing manufacturing output at unmatched scale. MIIT drone regulations and GB standards certification requirements govern airworthiness and export compliance. Shenzhen's Nanshan District hosts vertically integrated supply chains where flight controllers, gimbals, and lithium-polymer cells move through captive production networks.
Australia
Broadacre farming cooperatives in Queensland and Western Australia deploy autonomous spraying fleets across wheat and canola belts exceeding ten thousand hectares per operator. CASA remotely piloted aircraft regulations and instrument flight rules exemptions enable beyond-visual-line-of-sight grain monitoring. Perth's technology corridor concentrates equipment-as-a-service providers offering per-acre pricing models that displace capital purchase economics.
Germany
Industrial inspection contractors serving Ruhr Valley chemical complexes and Bavarian automotive plants demand AI-certified platforms satisfying EASA SAIL III operational risk categories. EU AI Act algorithmic transparency requirements impose documentation burdens on safety-critical flight software developers. Munich's aerospace engineering cluster segregates AI development teams from legacy hardware functions to accelerate compliance certification timelines.
Brazil
Agribusiness operators across Mato Grosso soybean belts and São Paulo sugarcane regions deploy autonomous mapping and variable-rate application systems. ANAC unmanned aircraft systems regulations and ANVISA agricultural chemical application standards govern platform certification and operational permissions. Piracicaba's agricultural technology hub hosts service providers integrating drone-generated multispectral data into precision farming decision systems.
Autonomous Drone Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-defined autonomy stacks versus hardware-assembly operations. The vendor base stratifies into three tiers: vertically integrated defense contractors controlling captive component supply, consumer-electronics scale manufacturers leveraging Shenzhen manufacturing density, and specialized autonomy software houses licensing navigation algorithms across airframe categories. Consolidation pressure concentrates on flight-computer suppliers as edge-AI inference engines displace legacy avionics architectures. Geographic expansion and strategic partnerships dominate competitive moves as regulatory divergence multiplies certification burdens.
Within the defense-contractor archetype, Anduril Industries and Kratos Defense occupy positions sustained by military procurement acceleration and dual-use technology convergence. Among commercial-scale manufacturers, DJI Innovations anchors manufacturing density through rotary-wing platform dominance and component sourcing control. On the software-specialist vector, Skydio exemplifies computer-vision differentiation that displaces hardware-heavy sensor payloads in enterprise segments. These three anchors illustrate how vertical integration, manufacturing scale, and algorithmic specialization partition addressable market access across procurement categories.
| Leading Market Players |
|---|
| Anduril Industries |
| XAG |
| DJI Innovations |
| Red Cat Holdings |
| EHang |
| Skydio |
| Kratos Defense |
| Draganfly |
| AeroVironment |
| Others |
Pricing and Supply Chain Analysis
Defense procurement agencies operating under FAA Part 107 waiver frameworks command premium pricing for certified beyond-visual-line-of-sight platforms, anchoring the market around performance-tiered contracts rather than commoditized hardware sales. Agricultural cooperatives in Australian broadacre farming and Brazilian soybean belts drive equipment-as-a-service adoption, compressing upfront capital requirements into per-acre subscription economics that reshape supplier cash flow patterns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and payload sophistication. Premium tiers attach to EASA SAIL III and FAA detect-and-avoid compliant platforms with algorithmic transparency documentation, while economy tiers serve sub-250 gram recreational categories exempt from operational risk assessments. Cost compression in mid-tier rotary-wing systems is intensifying because Shenzhen manufacturing density enables component sourcing arbitrage. Agricultural cooperatives exhibit highest price sensitivity, whereas defense contractors absorb premium markups for swarming coordination and encrypted datalink capabilities.
Supply Chain Analysis
Airworthiness certification gating concentrates flight controller and autopilot module production in Shenzhen's Nanshan District, where GB standards compliance and MIIT drone regulations create captive supplier ecosystems. Advanced lithium-polymer cell production clusters in China, South Korea, and Japan feed extended-endurance platform assembly, with multi-constellation GNSS receivers drawing from Taiwanese semiconductor fabrication. Single-source vulnerability in neural processing unit supply chains threatens edge-AI inference engine availability for real-time obstacle avoidance systems. Distribution runs through vertically integrated defense contractors and authorized agricultural equipment dealers serving regional farming cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Autonomous Drone Market functions as a stable compounder underpinned by regulatory sandbox expansion that progressively unlocks beyond-visual-line-of-sight commercial operations across precision agriculture and infrastructure inspection corridors.
For Market Incumbents: Lock in algorithmic certification advantages by segregating AI development teams from legacy hardware engineering functions to accelerate EASA SAIL III and FAA means-of-compliance documentation. Invest in captive lithium-polymer cell supply agreements to mitigate East Asian manufacturing concentration risks. Defend against software-defined autonomy entrants by deepening embedded systems talent pools in aerospace engineering clusters. For New Entrants and Emerging Players: Direct-to-farm digital channels offer the most penetrable route for equipment-as-a-service platforms targeting Australian broadacre cooperatives with seasonal demand spikes. Target Nordic offshore wind maintenance segments where per-flight-hour pricing models displace capital purchase inefficiency. Pursue urban air mobility corridor access in Singapore and Dubai as regulated testbeds for autonomous cargo commercialization. For Investors and Strategic Acquirers: Defense contractors pursuing dual-use technology convergence are the most active acquirers in this space, seeking computer vision and swarming coordination capabilities applicable to both military and agricultural automation. Long-term viability rests on software-defined autonomy stacks that displace hardware-heavy sensor payloads. Watch FAA beyond-visual-line-of-sight rulemaking velocity as the critical inflection signal for commercial addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Certification Investment | EASA SAIL III compliance unlocks premium infrastructure inspection contracts in German industrial corridors. |
| Equipment-as-a-Service Platform Launch | Per-acre pricing models displace capital purchase economics for Australian broadacre farming cooperatives. |
| Dual-Use Technology Partnership | Military autonomy stacks adapted for agricultural spraying accelerate Brazilian agribusiness fleet deployment. |
| Urban Air Mobility Corridor Access | Singapore and Dubai designated low-altitude highways enable autonomous cargo delivery commercialization. |
| Edge-AI Inference Engine Consolidation | Single-system-on-chip architectures reduce SWaP constraints for extended-endurance defense platforms. |
Research Methodology
Direct dialogue with flight operations managers at agricultural cooperatives, procurement leads at defense contractors, autonomy software engineers, and CASA regulatory affairs specialists grounded the qualitative framework. Secondary validation drew from FAA Part 107 waiver databases, EASA drone regulation frameworks, SEC filings of listed unmanned systems vendors, and ANAC unmanned aircraft systems certification records. Bottom-up fleet deployment estimates across Brazilian and Australian agricultural corridors triangulated against top-down defense procurement budget allocations.
Segmented outputs across rotary-wing, hybrid, fixed-wing, nano, and micro product categories combined with technology stacks spanning AI and machine learning, computer vision, LiDAR, GNSS, and obstacle avoidance systems. Application dimensions modeled precision agriculture, infrastructure inspection, emergency response, surveying and mapping, and security surveillance. End-user archetypes included agribusiness enterprises, construction firms, security agencies, surveying companies, and disaster management teams. CAGRs derived from regression analysis against regulatory sandbox expansion timelines and equipment-as-a-service adoption curves.
GPS spoofing incidents near conflict zones, divergent national ICAO framework implementation, and lithium-polymer supply concentration in East Asian manufacturing hubs are the dominant revision risks. Deviation in FAA beyond-visual-line-of-sight rulemaking velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Europe Aerostat Systems Market