
 High Altitude Aeronautical Platform Stations Market | 2026-2036
High Altitude Aeronautical Platform Stations Market Size, Share, and Industry Trends Forecast 2026-2036
High Altitude Aeronautical Platform Stations Market Foresight
Multi-source to dual-source supplier strategies is consolidating procurement patterns across the High Altitude Aeronautical Platform Stations industry. Lockheed Martin Corporation leverages its defense heritage to anchor military contracts for persistent surveillance platforms. Airbus S.A.S. sustains European institutional backing through its Zephyr solar-electric program. Thales Group competes on integrated payload systems, combining communications relay with signals intelligence.
High Altitude Aeronautical Platform Stations are unmanned systems operating in the stratosphere, typically between 18 and 50 kilometers altitude, employing solar-electric propulsion, helium lift, or hybrid aerostatic-aerodynamic designs to maintain multi-week station-keeping for communications relay, remote sensing, or environmental monitoring. The telecommunications application leads current deployment activity, driven by mobile network operators seeking to extend coverage without terrestrial infrastructure buildout. Balloon-based technology occupies the fastest-expanding segment, as lighter-than-air platforms achieve duration records at lower cost per flight hour than solar-electric alternatives. Military end users dominate funding flows, though commercial enterprises represent the emerging margin pool as regulatory clarity permits civilian spectrum allocation.
The FAA governs U.S. airspace access through Certificate of Authorization processes that limit operational altitudes and collision-avoidance protocols for stratospheric platforms. EASA's proposed high-altitude platform station framework under the EU Green Deal is shaping European certification timelines and environmental compliance requirements. Stakeholders must monitor spectrum allocation decisions by national regulators and ITU coordination processes, as these will determine which platform technologies achieve scalable commercial deployment.
Market Dynamics
The FAA's beyond-visual-line-of-sight rulemaking for stratospheric operations is forcing platform developers to restructure certification timelines and airspace coordination protocols around specific altitude bands and collision-avoidance mandates.
Growth Catalysts
- Rural connectivity mandates:Telecommunications operators in the United States face coverage obligations that terrestrial infrastructure cannot economically fulfill, pulling stratospheric relay platforms into active procurement cycles.
- Defense persistent surveillance requirements:Military end users fund multi-week station-keeping demonstrations, validating solar-electric and hybrid aerostatic technologies for signals intelligence and border monitoring missions.
- EU Green Deal aviation decarbonization framework:EASA's proposed high-altitude platform station certification pathway creates institutional backing for zero-emission stratospheric alternatives to satellite launches and conventional aircraft.
Market Restraints
- Helium supply concentration:Lighter-than-air platforms depend on helium lift gas sourced from concentrated geological reserves, exposing balloon-based systems to input cost volatility and export restriction risk.
- Spectrum allocation friction:National regulators and ITU coordination processes delay commercial frequency assignments, blocking scalable deployment for civilian communications relay applications.
- Solar-electric payload limitations:Power density constraints on stratospheric platforms restrict real-time data throughput compared to geostationary satellite alternatives, limiting addressable market segments.
Strategic Opportunities
- Environmental monitoring services:Climate research institutions and agricultural ministries represent underpenetrated demand for stratospheric remote sensing of carbon flux, wildfire progression, and crop stress indices.
- Hybrid propulsion convergence:Integration of aerostatic lift with aerodynamic control surfaces and solar-electric propulsion is modularizing platform designs, enabling mission-specific reconfiguration without full redevelopment.
- India's rural broadband initiative:TRAI's exploratory framework for high-altitude platform stations creates a regulatory tailwind for pilot deployments targeting unserved villages in Rajasthan and Madhya Pradesh.
Industry Challenges
- Stratospheric meteorology expertise:Station-keeping algorithms require atmospheric scientists capable of modeling wind shear and diurnal thermal gradients at 20-50 kilometer altitudes, a talent pool concentrated in defense and academic institutions.
- Multi-regional certification burden:Platform developers must satisfy FAA Certificate of Authorization processes, EASA environmental compliance, and ITU spectrum coordination simultaneously, compressing program timelines and inflating validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Altitude Aeronautical Platform Stations Market |
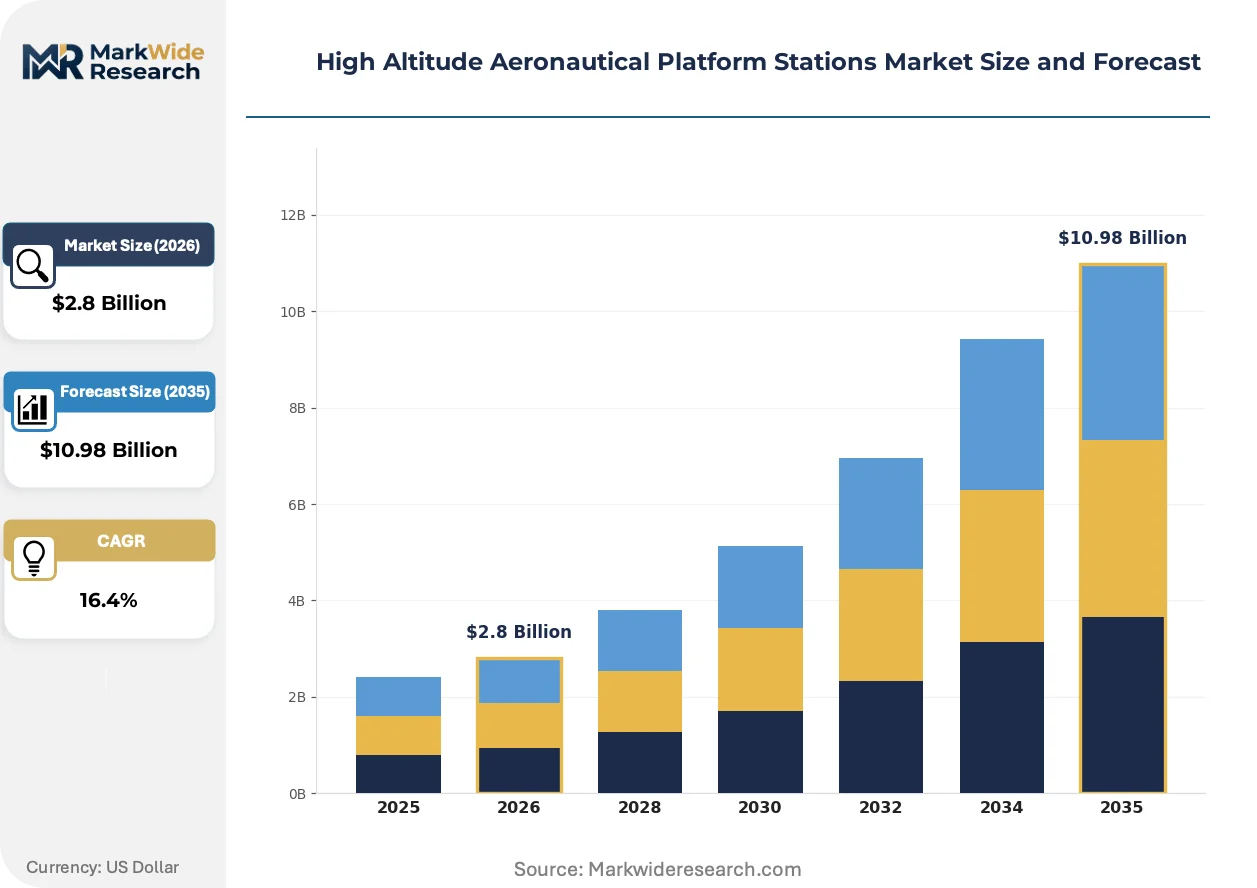
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerial Surveillance, Telecommunications, Disaster Management, Weather Monitoring Technology: Drone-Based, Balloon-Based, Aircraft-Based, Hybrid Systems End User: Military, Civil Government, Commercial Enterprises, Research Organizations Deployment: Temporary, Permanent, On-Demand, Fixed Location |
| Companies Covered | AeroVironment, Inc., Airbus S.A.S., Lockheed Martin Corporation, Thales Group, Prismatic Ltd., Northrop Grumman, General Atomics, World View Enterprises, Inc., Sceye Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Altitude Aeronautical Platform Stations Market Shifts & Advancements
Platform architectures are fragmenting into specialized configurations as mission requirements diverge between persistent surveillance, emergency communications restoration, and precision agriculture sensing.
Solar-electric propulsion systems with modular battery-swapping interfaces are modularizing payload integration timelines. Defense contractors in the United States now specify standardized power and data buses that accommodate signals intelligence, optical imaging, or mesh networking packages within single airframe families. This standardization compresses procurement cycles from custom development to configuration selection.
EASA's draft high-altitude platform station framework under the EU Green Deal mandates life-cycle carbon accounting and end-of-life recovery planning for stratospheric assets. European platform developers must now document manufacturing emissions and de-orbit protocols before type certification, reshaping supply chain sourcing toward recyclable composites and non-toxic propulsion chemistries. Solar-electric programs face accelerated compliance timelines compared to balloon-based alternatives.
Mobile network operators in sub-Saharan Africa and Southeast Asia now specify platform-as-a-service contracts rather than asset ownership, transferring operational risk to specialized stratospheric service providers. This unbundling shifts capital allocation from infrastructure balance sheets to recurring service expenditures, concentrating procurement authority within carrier procurement functions rather than engineering departments. Kenya and Indonesia represent early-adopter markets where this model has achieved contractual closure.
High Altitude Aeronautical Platform Stations Market Segmentation
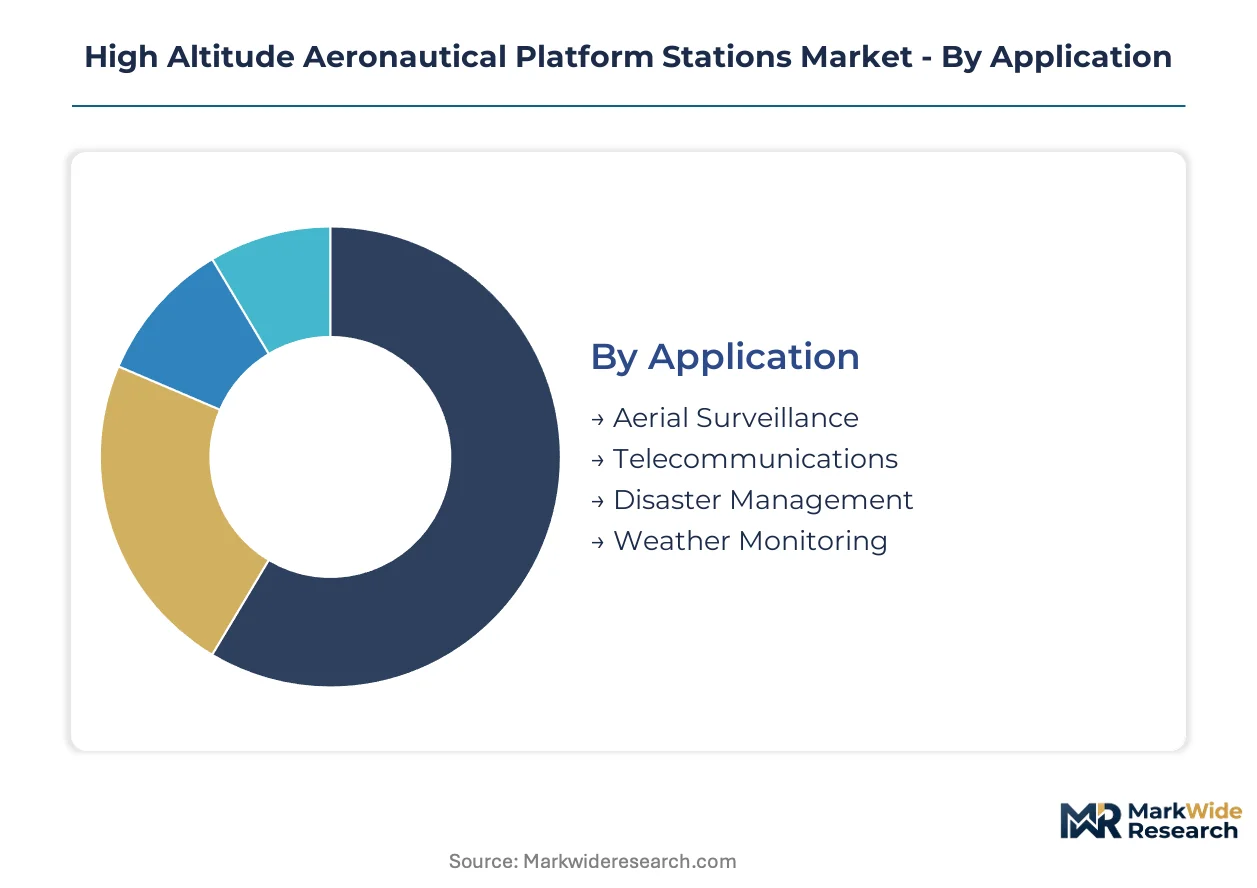
Segmentation in High Altitude Aeronautical Platform Stations reveals how mission duration, payload capacity, and regulatory jurisdiction shape procurement decisions. Buyers prioritize different platform characteristics depending on whether they need persistent surveillance, emergency communications restoration, or environmental monitoring coverage.
Application:
Buyers in this category differentiate by mission criticality and revenue model—defense contracts fund multi-week endurance while commercial operators seek flexible, interruptible service tiers.
- Telecommunications:Stratospheric relay platforms extend mobile coverage to unserved regions without terrestrial tower buildout. Mobile network operators in sub-Saharan Africa and Southeast Asia now contract platform-as-a-service arrangements rather than asset ownership, transferring operational risk to specialized providers.
- Aerial Surveillance:Persistent station-keeping at 18-50 kilometer altitudes enables border monitoring and signals intelligence collection. Military end users in the United States fund solar-electric and hybrid aerostatic demonstrations, validating multi-week endurance for defense applications.
- Disaster Management:Rapid-deployable platforms restore communications infrastructure following terrestrial network failures. Emergency response agencies value on-demand launch capabilities over persistent coverage.
- Weather Monitoring:Stratospheric sensors capture atmospheric data for climate research and agricultural forecasting. Research institutions represent underpenetrated demand for carbon flux and wildfire progression monitoring.
Telecommunications leads volumes today; disaster management is gaining share fastest as climate-related infrastructure failures accelerate procurement cycles.
Technology:
Platform selection hinges on lift mechanism tradeoffs between helium dependency, solar-electric payload constraints, and hybrid flexibility.
- Balloon-Based:Lighter-than-air systems achieve duration records at lower cost per flight hour through helium lift gas. Concentrated geological helium reserves expose operators to input cost volatility and export restriction risk from Qatar and Algeria.
- Drone-Based:Solar-electric propulsion with modular battery interfaces enables rapid payload reconfiguration. Power density constraints restrict real-time data throughput compared to geostationary satellite alternatives, limiting addressable market segments.
- Aircraft-Based:Conventional aerodynamic platforms sacrifice endurance for payload capacity and maneuverability. Defense contractors favor these for signals intelligence missions requiring active repositioning.
- Hybrid Systems:Integration of aerostatic lift with aerodynamic control surfaces and solar-electric propulsion modularizes designs for mission-specific reconfiguration. EASA's EU Green Deal compliance timelines accelerate faster for these platforms than balloon alternatives.
Balloon-based systems dominate current deployment; hybrid configurations are climbing the fastest as developers seek to decouple from helium supply concentration.
End User:
Funding source and procurement authority vary sharply across this category—defense budgets anchor volume while commercial enterprises represent emerging margin pools.
- Military:Persistent surveillance requirements fund technology validation for multi-week station-keeping. Procurement cycles emphasize signals intelligence and border monitoring mission specifications over unit economics.
- Commercial Enterprises:Mobile network operators and agricultural technology firms represent expanding demand as regulatory clarity permits civilian spectrum allocation. Kenya and Indonesia have achieved contractual closure for platform-as-a-service models.
- Civil Government:National broadband initiatives and emergency response agencies procure temporary deployments for rural connectivity and disaster restoration. India's TRAI exploratory framework creates regulatory tailwinds for pilot programs in Rajasthan and Madhya Pradesh.
- Research Organizations:Climate institutions and agricultural ministries seek stratospheric remote sensing for carbon flux and crop stress indices. This segment remains underpenetrated relative to defense and commercial demand.
Military end users anchor current volumes; commercial enterprises show the steepest expansion trajectory as FAA beyond-visual-line-of-sight rules mature.
Deployment:
Operational model selection reflects capital allocation preferences and mission predictability requirements.
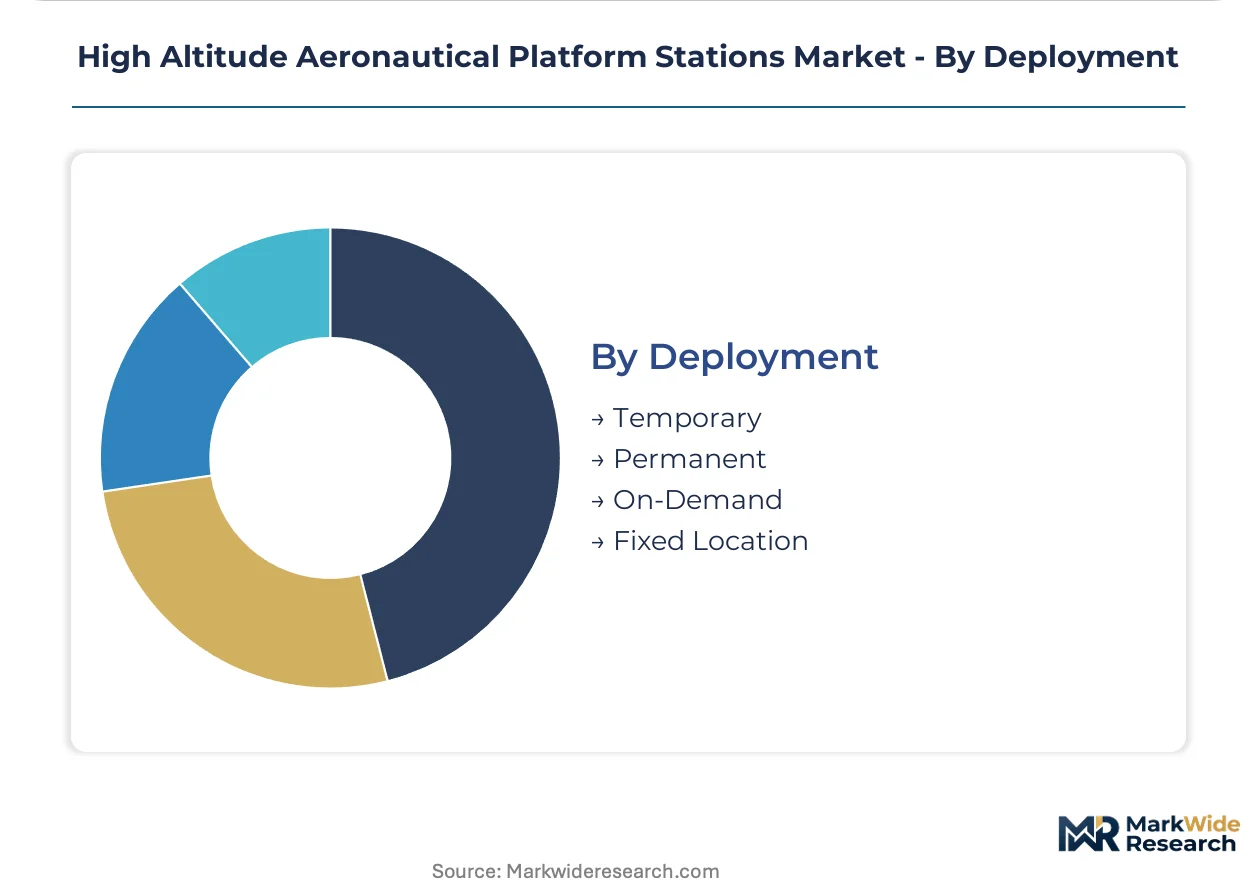
- On-Demand:Launch-when-needed contracts suit disaster response and temporary surveillance missions. Service providers bear weather risk and airspace coordination burden.
- Permanent:Continuous station-keeping for telecommunications relay requires regulatory certainty on spectrum allocation and collision-avoidance protocols. FAA Certificate of Authorization processes currently limit scalable deployment.
- Temporary:Defined-duration missions for agricultural sensing or military exercises balance cost against coverage guarantees. Procurement emphasizes rapid redeployment capabilities.
- Fixed Location:Station-keeping over specific coordinates serves persistent surveillance and dedicated communications relay. Wind shear modeling expertise at 20-50 kilometer altitudes constrains operator supply.
On-demand deployment leads current contract volumes; permanent installations are expanding most quickly as ITU spectrum coordination progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Mexico and Arizona test ranges anchor the global stratospheric platform ecosystem, drawing defense contractors and commercial trial operators to shared airspace corridors and FAA-coordinated launch facilities.
United States
Defense spending and FAA Certificate of Authorization processes concentrate procurement authority around persistent surveillance demonstrations. The FAA's evolving beyond-visual-line-of-sight rules reshape certification pathways for platform developers seeking multi-week station-keeping approvals. New Mexico's White Sands Missile Range and Arizona's Yuma Proving Ground host competing solar-electric and balloon-based trials.
United Kingdom
Climate research institutions drive demand for stratospheric carbon flux monitoring and wildfire progression sensing. The UK Space Agency coordinates with EASA on high-altitude platform station frameworks under EU Green Deal alignment protocols. Cornwall's Spaceport development targets rapid-deployable launch capabilities for emergency communications restoration missions.
France
Military signals intelligence requirements fund hybrid aerostatic-aerodynamic platform validation for border monitoring. EASA's proposed certification pathway accelerates institutional backing for zero-emission stratospheric alternatives. Toulouse aerospace clusters integrate payload systems combining communications relay with environmental sensing capabilities.
India
TRAI's exploratory framework for high-altitude platform stations creates regulatory tailwinds for rural broadband pilots. The rural connectivity mandate targets unserved villages in Rajasthan and Madhya Pradesh with stratospheric relay alternatives to terrestrial tower buildout. Bengaluru aerospace engineering hubs supply station-keeping algorithm talent for wind shear modeling at 20-50 kilometer altitudes.
Japan
METI coordinates spectrum allocation trials for disaster management applications requiring rapid-deployable communications restoration. Solar-electric propulsion developers seek modular battery interfaces for rapid payload reconfiguration. Nagoya aerospace manufacturing clusters produce standardized power and data buses for defense contractor specifications.
High Altitude Aeronautical Platform Stations Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue platform-as-a-service arrangements and environmental monitoring specializations. The vendor base clusters around defense heritage contractors with FAA certification experience and European institutional-backed solar-electric programs. Three archetypes dominate: persistent surveillance specialists leveraging multi-week endurance records, integrated payload system providers combining communications with intelligence capabilities, and lighter-than-air operators optimizing cost per flight hour. Competitive moves concentrate on strategic partnerships with mobile network operators and hybrid propulsion technology licensing to decouple from helium supply concentration.
Among defense-heritage contractors, Lockheed Martin Corporation and Northrop Grumman exemplify the persistent surveillance archetype through military contract anchoring. Airbus S.A.S. occupies a position within European institutional-backed solar-electric development. Thales Group represents the integrated payload system tier, while World View Enterprises, Inc. and Sceye Inc. sit within emerging lighter-than-air and hybrid configuration specialists targeting commercial platform-as-a-service markets.
| Leading Market Players |
|---|
| AeroVironment, Inc. |
| Airbus S.A.S. |
| Lockheed Martin Corporation |
| Thales Group |
| Prismatic Ltd. |
| Northrop Grumman |
| General Atomics |
| World View Enterprises, Inc. |
| Sceye Inc. |
| Others |
Supply & Pricing Matrix
Defense-grade certification tiers versus commercial-service tiers create a bifurcated pricing landscape where FAA Certificate of Authorization holders command persistent-surveillance premiums while platform-as-a-service entrants compete on per-flight-hour economics, with helium supply concentration in Qatar and Algeria directly constraining balloon-based cost structures while solar-electric alternatives absorb polysilicon and battery cell pricing volatility.
Pricing Analysis
Helium input-cost pass-through dominates balloon-based platform economics, with concentrated geological reserves in Qatar and Algeria exposing operators to export restriction risk that compresses margins on lighter-than-air deployments. Solar-electric alternatives face polysilicon and lithium-ion cell pricing cycles that modular battery-swapping interfaces partially mitigate through component standardization. Defense procurement emphasizes multi-week endurance specifications over unit economics, while commercial mobile network operators in sub-Saharan Africa and Southeast Asia exhibit acute price sensitivity to per-flight-hour service tiers. Three-tier pricing structure across defense-certified, commercial-persistent, and on-demand-economy levels separates procurement authority between military program offices and carrier procurement functions.
Supply Chain Analysis
Stratospheric payload logistics hinge on specialized airframe transport to New Mexico and Arizona test ranges, where White Sands Missile Range and Yuma Proving Ground coordinate FAA launch windows that constrain deployment scheduling and inflate freight coordination costs for European and Asian developers. Solar cell manufacturing concentrates in China, South Korea, and Malaysia, while helium extraction remains tethered to natural gas processing in Qatar, Algeria, and the United States. Single-source vulnerability in stratospheric meteorology talent—concentrated in defense and academic institutions—threatens station-keeping algorithm development timelines. Distribution runs through defense contractor procurement channels for military end users and direct platform-as-a-service contracting for commercial mobile network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement authority shifts toward carriers demanding FAA-certified persistent coverage with guaranteed service-level agreements rather than experimental demonstrations.
For Market Incumbents: Anchor multi-year FAA Certificate of Authorization portfolios to block emerging entrants from scalable beyond-visual-line-of-sight approvals, while deepening backward integration into solar-electric propulsion components to offset polysilicon and battery cell pricing volatility. Hybrid aerostatic-aerodynamic platform families should absorb helium supply concentration risk through mission-flexible reconfiguration capabilities.
For New Entrants and Emerging Players: Solar-electric payload modularity offers a technology-first wedge into environmental monitoring services for climate research institutions and agricultural ministries, segments where defense heritage contractors maintain weak presence and procurement cycles favor rapid deployment over endurance records. Kenya and Indonesia platform-as-a-service contracts demonstrate viable go-to-market angles through carrier procurement function relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where FAA certification backlogs exceed 18-month timelines and talent scarcity in stratospheric meteorology constrains station-keeping algorithm development. Long-term viability favors vertically integrated developers with captive solar-electric propulsion manufacturing and established EASA environmental compliance documentation under EU Green Deal frameworks. Watch ITU spectrum coordination progress as the inflection signal determining which platform technologies achieve scalable commercial deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Certification Acceleration | Shortens beyond-visual-line-of-sight approval timelines that currently block permanent telecommunications deployment. |
| Helium Supply Diversification | Reduces input cost volatility exposure from concentrated Qatari and Algerian geological reserves. |
| Hybrid Propulsion Licensing | Enables mission-specific reconfiguration without full airframe redevelopment across surveillance and relay applications. |
| Platform-as-a-Service Expansion | Shifts capital allocation from carrier balance sheets to recurring service expenditures in sub-Saharan Africa and Southeast Asia. |
| EASA Environmental Compliance | Secures institutional backing under EU Green Deal frameworks for zero-emission stratospheric alternatives. |
Research Methodology
Multiple input streams — primary interviews with stratospheric platform engineering directors, FAA certification specialists, and mobile network operator procurement leads; secondary validation through EASA regulatory filings, ITU spectrum coordination records, and defense contract award databases; plus customs data on helium and polysilicon trade flows — were reconciled through bottom-up deployment volume modeling and top-down addressable market sizing across telecommunications, surveillance, and environmental monitoring applications.
Segment-level CAGRs across the projection horizon were derived from technology adoption curves weighted by FAA rulemaking progression and ITU frequency assignment timelines, with balloon-based, solar-electric, and hybrid system configurations modeled separately against mission duration requirements and payload capacity constraints. Helium supply elasticity, solar cell efficiency trajectories, and stratospheric meteorology talent availability served as industry-specific forecast sensitivity inputs.
The model holds under steady FAA beyond-visual-line-of-sight rulemaking progression and ITU spectrum coordination advancement; deviation in regulatory timelines or helium export restrictions would shift deployment volume assumptions and platform technology mix projections. Stakeholders should weight assumptions against their own operating context and certification backlog exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Tethered Drone System Market