
 Subsea Navigation and Tracking Market | 2026-2036
Subsea Navigation and Tracking Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Navigation and Tracking Market Analytics
ISO 13628-8 qualification for subsea production control systems is reorganizing competitive access across the subsea navigation sector. Kongsberg Gruppen leverages its integrated inertial and acoustic positioning stack to dominate Norwegian continental shelf deployments. Teledyne Technologies anchors North American supply through its underwater interconnect and sensor portfolio. Sonardyne International specializes in long-baseline acoustic networks for deepwater field development.
Subsea navigation and tracking encompasses acoustic, inertial, and hybrid positioning technologies that enable real-time geolocation of underwater assets at depths exceeding 3,000 meters, primarily serving offshore energy extraction and seabed infrastructure installation. Active acoustic systems lead installed base volume due to proven reliability in turbid water conditions where optical methods fail. Inertial navigation represents the fastest-expanding technology segment as drift-correction algorithms improve autonomous underwater vehicle endurance. Oil and gas exploration commands the largest application share, though marine research installations are accelerating as academic institutions deploy deeper-rated observatory networks.
The International Maritime Organization governs equipment certification for vessels deploying subsea navigation gear, while the Norwegian Petroleum Safety Authority enforces functional safety standards on the Norwegian continental shelf. The US Bureau of Safety and Environmental Enforcement mandates positioning redundancy for Gulf of Mexico drilling operations, directly shaping procurement specifications. Stakeholders must monitor evolving seabed mining regulations, as emerging jurisdictional frameworks in international waters will determine which tracking technologies gain preferential approval for exploratory contracts.
Market Dynamics
ISO 13628-8 qualification requirements are compressing vendor access and forcing acoustic-inertial hybrid architectures as the default technical specification for Norwegian continental shelf deployments.
Growth Catalysts
- Offshore fleet modernization:North Sea operators are retiring legacy positioning systems ahead of IMO certification deadlines, creating replacement demand for integrated navigation stacks.
- Autonomous underwater vehicle endurance:Drift-correction algorithm improvements extend mission duration beyond 72 hours, opening deepwater inspection contracts previously requiring tethered systems.
- Seabed mining regulatory frameworks:Emerging jurisdictional clarity in international waters is triggering pre-qualification positioning system procurements for exploratory license applications.
Market Restraints
- Titanium alloy cost volatility:Pressure vessel and transducer housing fabrication depends on aerospace-grade titanium supply chains concentrated in Russian and Chinese smelters.
- Acoustic transducer supply concentration:Piezoelectric ceramic manufacturing for deepwater-rated transducers clusters in Japanese and German specialty ceramics producers.
- Optical positioning range limitations:Laser-based underwater navigation fails beyond 50 meters in turbid North Sea conditions, restricting application to clear-water environments.
Strategic Opportunities
- Marine research observatory networks:Academic institutions in Norway and the United States are deploying deeper-rated cabled observatories requiring permanent seabed reference stations.
- Acoustic-inertial convergence:Tight integration of long-baseline acoustic networks with fiber-optic gyroscopes enables drift-free positioning without surface vessel dependency.
- US Bureau of Safety and Environmental Enforcement redundancy mandates:Gulf of Mexico drilling contractors must procure dual-independent positioning systems, doubling equipment attach rates per rig.
Industry Challenges
- Functional safety engineering talent:IEC 61508 certification expertise for subsea control systems is concentrated among Norwegian and Scottish engineering consultancies.
- Extended qualification timelines:ISO 13628-8 pressure cycling and seawater exposure testing adds 18-24 months to product commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Navigation and Tracking Market |
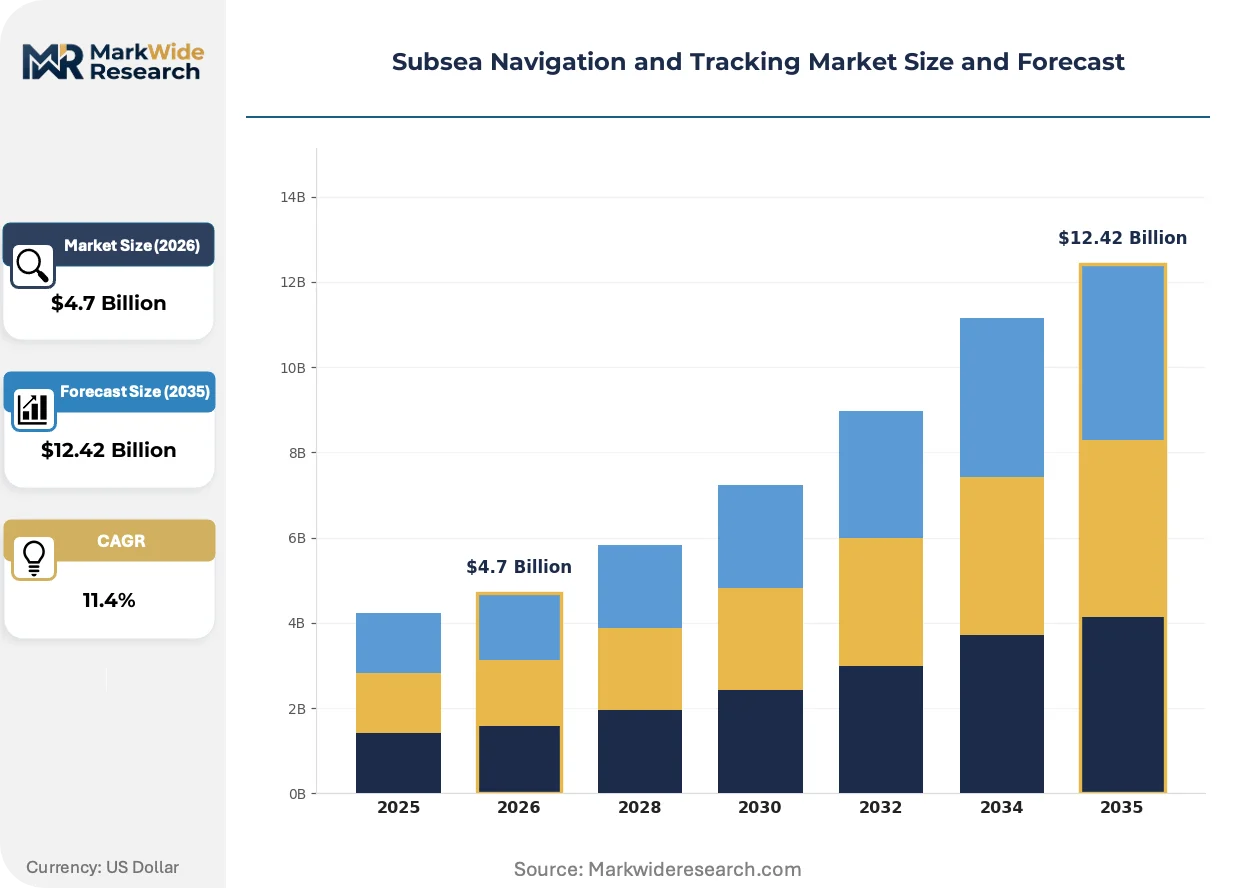
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Acoustic, Inertial Navigation, GPS, Ultra-Wideband Application: Oil & Gas Exploration, Subsea Construction, Marine Research, Environmental Monitoring End User: Subsea Contractors, Research Institutions, Oil Operators, Government Agencies Installation: Fixed Systems, Portable Devices, Underwater Vehicles, Surface Support Units |
| Companies Covered | Kongsberg Gruppen, Teledyne Technologies, Sonardyne International, Exail, EdgeTech, EvoLogics, L3Harris Technologies, Ultra Maritime, Fugro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Navigation and Tracking Market Evolving Landscape
Navigation system architectures are splitting between vessel-tethered precision positioning and fully autonomous seabed-referenced modes, with hybrid configurations emerging as the compromise specification.
Acoustic positioning technology is bifurcating between ultra-short baseline systems for routine operations and long-baseline networks for millimetric-precision construction tasks. Offshore installation contractors in Norway and Brazil are adopting dual-capability stacks to avoid mobilization delays. This technical split is compressing pricing for mid-tier short-baseline equipment while premium long-baseline deployments command sustained margins.
The Norwegian Petroleum Safety Authority has tightened functional safety verification requirements for integrated navigation and drilling control systems. Operators must now demonstrate fault-tolerant positioning redundancy through third-party witnessed failure-mode testing. Subsea construction vessels operating on the Norwegian continental shelf are responding by segregating navigation system procurement from drilling contractor packages.
Buyer consolidation among supermajor oil companies is compressing vendor negotiation cycles and unbundling after-sales service from hardware procurement. Integrated service contracts covering calibration, spare parts, and software updates are displacing transactional equipment sales in the North Sea. This pattern is most visible among Equinor and Shell procurement teams in Stavanger and Bergen.
Subsea Navigation and Tracking Market Segmentation
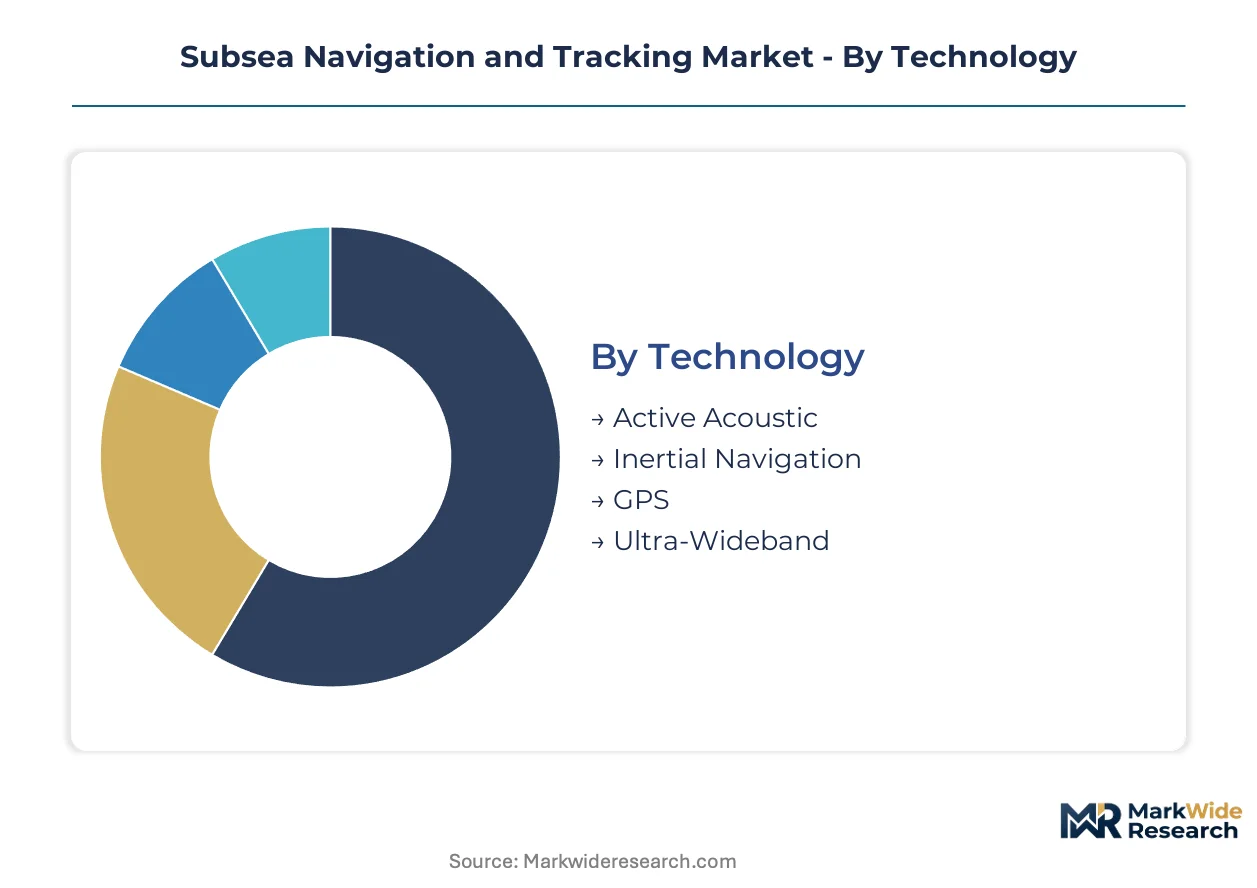
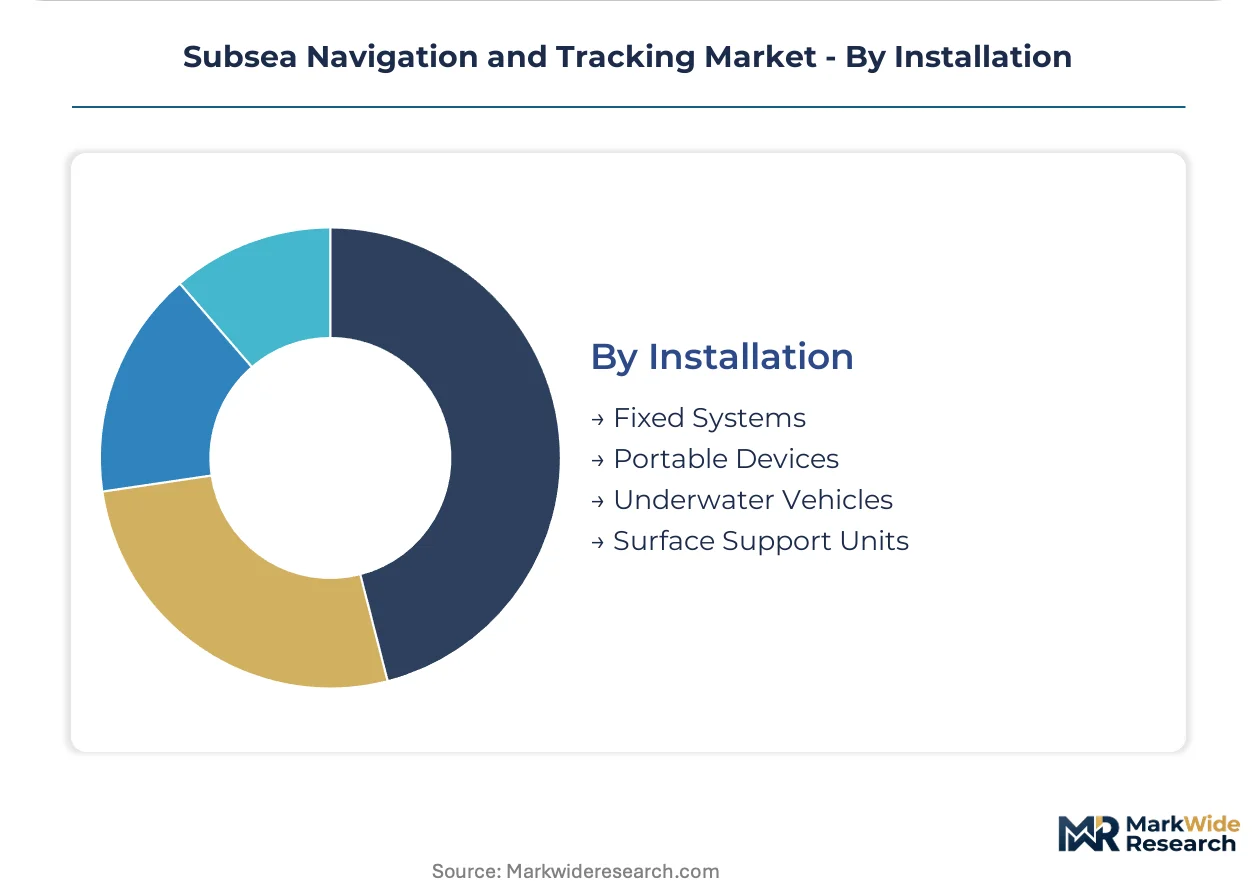
Subsea navigation procurement specifications diverge sharply across regulatory jurisdictions and operational depths. Technology selection, application priority, and installation mode each carry distinct certification requirements that reshape competitive access.
Technology:
Regulatory differentiation in the Norwegian North Sea and US Gulf of Mexico favors acoustic-inertial hybrids over single-technology stacks.
- Active Acoustic:Piezoelectric transducer arrays transmit positioning signals through seawater at depths exceeding 3,000 meters. Norwegian continental shelf operators specify long-baseline configurations for millimetric-precision construction tasks around Stavanger field developments.
- Inertial Navigation:Fiber-optic gyroscopes combined with accelerometers enable dead-reckoning without external references. Drift-correction algorithm advances are extending autonomous underwater vehicle mission duration beyond 72 hours in deepwater inspection contracts.
- GPS:Surface-referenced positioning via satellite constellations requires acoustic relay for subsea translation. Gulf of Mexico drilling contractors deploy GPS-acoustic integration to satisfy Bureau of Safety and Environmental Enforcement redundancy mandates.
- Ultra-Wideband:Short-range electromagnetic pulse systems function in clear-water environments at depths below 50 meters. Marine research institutions deploy ultra-wideband for shallow observatory network calibration where acoustic multipath interference degrades precision.
Established volume favors Active Acoustic; emerging adoption favors Inertial Navigation.
Application:
Cost tier stratification separates capital-intensive energy extraction from grant-funded academic deployments.
- Oil & Gas Exploration:Wellhead positioning and riser installation demand fault-tolerant navigation redundancy. North Sea supermajors procure integrated stacks covering drilling, construction, and intervention phases under single service contracts.
- Subsea Construction:Pipeline laying and platform installation require centimeter-level seabed reference networks. Brazilian pre-salt field developments are accelerating long-baseline acoustic procurement for complex subsea tieback architectures.
- Marine Research:Cabled observatory networks require permanent seabed reference stations for long-duration data collection. Academic institutions in Norway and the United States are deploying deeper-rated systems for hadal zone exploration.
- Environmental Monitoring:Post-decommissioning seabed surveys and pollution tracking utilize portable acoustic positioning. Government agencies specify standardized calibration protocols for cross-jurisdictional data comparability.
Capital commitment intensity peaks in Oil & Gas Exploration; public funding cycles dominate Marine Research.
End User:
Customer type determines procurement complexity, with integrated service contracts displacing transactional sales among consolidated buyers.
- Subsea Contractors:Installation and maintenance specialists maintain multi-technology stacks to avoid mobilization delays. Dual-capability acoustic configurations command premium pricing for construction-grade precision.
- Research Institutions:Academic buyers prioritize modularity and open-interface protocols for instrument integration. Grant funding cycles concentrate procurement in Norwegian and US federal budget windows.
- Oil Operators:Supermajor consolidation is compressing vendor negotiation cycles and unbundling after-sales service from hardware. Equinor and Shell procurement teams in Stavanger and Bergen are pioneering integrated service contracts.
- Government Agencies:Defense and maritime safety authorities specify encrypted positioning links for seabed infrastructure protection. Classification requirements extend qualification timelines by 18-24 months.
Procurement scale concentrates with Oil Operators; specification innovation originates in Research Institutions.
Installation:
Supply concentration in Japanese and German piezoelectric ceramics shapes system architecture tradeoffs.
- Fixed Systems:Permanent seabed transponder arrays provide reference frames for recurring operations. Long-baseline networks in the North Sea require titanium-alloy pressure vessels rated for 25-year service life.
- Portable Devices:Diver-held and ROV-deployed positioning units enable rapid survey mobilization. Ultra-short baseline configurations dominate routine inspection where millimetric precision is unnecessary.
- Underwater Vehicles:Autonomous and remotely operated platforms carry integrated inertial-acoustic navigation stacks. Mission endurance improvements are displacing tethered systems in deepwater inspection markets.
- Surface Support Units:Vessel-mounted acoustic transceivers and inertial reference units bridge satellite and subsea positioning domains. Gulf of Mexico drilling contractors must procure dual-independent surface systems per regulatory mandate.
Capital deployment favors Fixed Systems for field development; operational flexibility favors Portable Devices for survey contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore licensing rounds and decommissioning liabilities are redirecting capital toward subsea positioning infrastructure across four distinct national markets. Norway's regulatory tightening and Brazil's pre-salt expansion dominate procurement volumes, while the United States and United Kingdom concentrate around regulatory compliance and energy transition assets.
Norway
Equinor's field redevelopment programs and Aker BP's installation campaigns drive demand for long-baseline acoustic networks. The Norwegian Petroleum Safety Authority mandates fault-tolerant positioning redundancy through witnessed failure-mode testing. Stavanger and Bergen host consolidated procurement teams unbundling after-sales service from hardware sales.
Brazil
Petrobras pre-salt tieback architectures require millimetric-precision seabed reference networks for complex subsea construction. The national petroleum regulator enforces localization content requirements for offshore service procurement. Rio de Janeiro anchors engineering specification work while Macaé concentrates vessel mobilization and equipment staging.
United States
Gulf of Mexico drilling contractors face dual-independent positioning mandates from the Bureau of Safety and Environmental Enforcement for deepwater operations. Decommissioning liability deadlines accelerate survey contracting for orphaned wellbore documentation. Houston hosts supermajor procurement teams specifying integrated navigation stacks.
United Kingdom
North Sea decommissioning programs and carbon capture storage site characterization create demand for portable acoustic positioning systems. The Health and Safety Executive governs offshore installation vessel certification including navigation equipment standards. Aberdeen maintains subsea engineering consultancy concentration around IEC 61508 functional safety expertise.
Subsea Navigation and Tracking Market Competitive Landscape
Listed leaders compete with private specialists across capital access and contract flexibility dimensions. The vendor base separates into three tiers: integrated maritime conglomerates with inertial-acoustic stacks, acoustic sensor specialists with long-baseline expertise, and survey contractors with captive positioning capabilities. Strategic moves concentrate on acoustic-inertial technology convergence and integrated service contract bundling.
Within the integrated systems tier, Kongsberg Gruppen and Teledyne Technologies exemplify divergent geographic anchoring strategies. Kongsberg represents Norwegian continental shelf dominance through proximity to Stavanger procurement clusters. Teledyne occupies a position bridging North American supply chains with underwater interconnect specialization. Sonardyne International sits within the acoustic network specialist archetype, with its name signaling long-baseline expertise.
| Leading Market Players |
|---|
| Kongsberg Gruppen |
| Teledyne Technologies |
| Sonardyne International |
| Exail |
| EdgeTech |
| EvoLogics |
| L3Harris Technologies |
| Ultra Maritime |
| Fugro |
| Others |
Value Network & Pricing Analysis
Acoustic-inertial hybrid architectures replacing single-technology stacks are redrawing procurement geography toward Norwegian engineering clusters while compressing margins on legacy short-baseline equipment. This substitution dynamic concentrates pricing power with vendors holding integrated certification portfolios and pressures transactional hardware sellers to bundle calibration and software services.
Pricing Analysis
Certification level creates the primary spread, with ISO 13628-8 qualified systems commanding substantial premiums over uncertified alternatives. Pricing stratifies across integrated service contracts covering 25-year field life, project-based hardware procurement, and spot rental for survey mobilization. Cost compression in mid-tier acoustic equipment intensifies because buyer consolidation among North Sea supermajors extracts volume discounts. Research institutions exhibit highest price sensitivity due to grant funding constraints, while Gulf of Mexico drilling contractors show lowest sensitivity given regulatory-mandated redundancy requirements.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade titanium and piezoelectric ceramics dominates inventory strategy given 18-24 month qualification timelines and geopolitical supply risks. Manufacturing concentrates in Japan and Germany for specialty ceramics, Norway and Scotland for systems integration, and Russia and China for titanium smelting. Supply chain risk centers on single-source vulnerability for deepwater-rated transducers. Distribution runs through Stavanger and Bergen procurement clusters for North Sea deployments, Houston for Gulf of Mexico operations, and Rio de Janeiro for Brazilian pre-salt fields.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including calibration, spare parts logistics, and software update subscriptions are expanding faster than hardware sales as supermajors unbundle procurement from lifecycle support. This shift favors vendors with field engineering density over pure equipment manufacturers.
For Market Incumbents: Fortify integrated service contract capabilities through captive calibration laboratory investments in Stavanger and Houston. Certification expertise concentration among Norwegian and Scottish engineering consultancies represents a defendable moat against Asian competitors lacking IEC 61508 track records. Prioritize acoustic-inertial hybrid R&D to maintain technical differentiation as drift-correction algorithms commoditize pure inertial solutions. For New Entrants and Emerging Players: Lead with modular open-interface architectures targeting marine research institutions in Norway and the United States where grant funding cycles concentrate procurement in predictable windows. Seabed mining pre-qualification positioning systems for international waters exploratory licenses represent the most penetrable white space. Pursue partnership-based go-to-market models with established survey contractors to bypass direct supermajor procurement barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated service providers over pure hardware vendors. Long-term viability hinges on positioning within Norwegian continental shelf procurement clusters where regulatory tightening accelerates vendor rationalization. Watch ISO 13628-8 qualification timelines as the critical inflection signal—extended testing delays favor incumbents with certified product portfolios and strain emerging players' capital endurance.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Bundling | Equinor and Shell procurement teams in Stavanger now require 25-year lifecycle coverage. |
| Acoustic-Inertial Hybrid Development | Tight integration enables drift-free positioning without surface vessel dependency. |
| Certification Laboratory Expansion | IEC 61508 expertise concentration in Norway creates geographic moats for compliant vendors. |
| Marine Research Observatory Partnership | Academic deployments in Norway and the United States provide reference site credibility. |
| Seabed Mining Pre-Qualification Positioning | Emerging international waters frameworks trigger exploratory license application procurements. |
Research Methodology
The analysis maps acoustic positioning, inertial navigation, hybrid integration, and surface support technologies, each validated through offshore installation contractors, subsea engineering consultancies, supermajor procurement managers, and marine research principal investigators. Primary fieldwork combined structured interviews with secondary validation against Norwegian Petroleum Safety Authority regulatory filings, International Maritime Organization certification databases, Bureau of Safety and Environmental Enforcement compliance records, and offshore vessel mobilization logs. Bottom-up equipment deployment counts triangulate against top-down energy sector capital expenditure disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology type, application depth tier, installation mode, end-user category, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth rate reconciliation with macro offshore energy investment patterns. Forecast inputs incorporate autonomous underwater vehicle mission endurance improvements and seabed mining jurisdictional framework evolution.
Forecasts assume regulatory continuity in Norwegian continental shelf functional safety regimes, United States Gulf of Mexico redundancy mandates, and Brazilian pre-salt localization requirements; material policy shifts would require re-modeling. Titanium alloy cost volatility, acoustic transducer supply concentration, and extended ISO 13628-8 qualification timelines constitute specific risk factors. Revision becomes warranted when seabed mining regulatory clarity crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Aerostat System Market