
 North America Unmanned Surface Vehicle (USV) Market | 2026-2036
North America Unmanned Surface Vehicle (USV) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Unmanned Surface Vehicle (USV) Market Analytics
Military-grade autonomy standards is collapsing the gap between demonstration platforms and operational deployment. L3Harris Technologies Inc. leverages its defense electronics heritage to anchor naval contract pipelines. Saildrone Inc. competes in long-duration ocean data collection with solar-powered hull architectures. Textron Inc. dominates harbor security applications through its command-and-control integration layer.
An unmanned surface vehicle is a self-propelled watercraft operating without onboard human crew, typically spanning two to twenty meters in length and integrating GPS waypoint navigation with collision-avoidance algorithms. These platforms execute hydrographic survey, perimeter patrol, and subsurface inspection missions where human presence risks safety or cost efficiency. Autonomous-type hulls now capture the dominant share of new procurement as navies phase out tethered remote-controlled units. Military end users concentrate margin pools in encrypted communication modules and hardened sensor payloads, while research institutions drive volume in modular payload bays.
The U.S. Navy's Unmanned Task Force coordinates platform certification with the FAA for beyond-line-of-sight communications in coastal zones. Transport Canada and the U.S. Coast Guard jointly harmonize collision regulations for autonomous vessels transiting the Great Lakes and Atlantic corridors. Stakeholders must track how NHTSA-derived safety protocols migrate into maritime autonomous systems standards. Procurement officers face a structural choice between single-mission platforms and reconfigurable hull families.
Market Dynamics
The U.S. Coast Guard's updated unmanned systems integration mandate is compressing certification timelines and forcing platform builders to front-load hardened communication modules into hull architectures. This regulatory pressure is restructuring procurement patterns across naval defense and commercial maritime applications.
Growth Catalysts
- Naval Autonomy Mandates:The U.S. Navy's Unmanned Task Force coordinates platform certification with the FAA for beyond-line-of-sight coastal communications. This framework accelerates operational deployment timelines for autonomous hulls.
- Great Lakes Regulatory Harmonization:Transport Canada and the U.S. Coast Guard jointly align collision regulations for autonomous vessels transiting shared waterways. This bilateral coordination reduces cross-border operational friction.
- Gulf Coast Shipbuilding Cluster:Concentrated shipyard capacity in Louisiana and Texas enables rapid prototype-to-production scaling. Proximity to offshore energy infrastructure drives commercial test-bed demand.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Dependence on Asian cell manufacturers creates input cost volatility and geopolitical exposure for long-duration solar-electric hulls.
- Encrypted Module Certification Bottlenecks:NSA Type 1 encryption standards impose multi-year validation cycles that delay military platform fielding.
- Tethered Remote-Controlled Legacy Stock:Existing harbor security fleets using cable-tethered architectures resist full autonomy migration due to sunk capital and retraining costs.
Strategic Opportunities
- California Maritime Technology Corridor:Venture-backed autonomy startups clustered in San Diego and Monterey Bay access Navy research partnerships and ocean test ranges.
- Subsea Inspection-as-a-Service:Oil majors in the Gulf of Mexico are unbundling platform maintenance from capital ownership, creating recurring revenue models for USV operators.
- NHTSA-Derived Safety Protocol Migration:Automotive autonomous vehicle standards are transferring to maritime rulemaking, potentially accelerating certification pathways for cross-domain technology suppliers.
Industry Challenges
- Maritime AI Systems Engineering Talent:Shortage of specialists combining naval architecture with machine learning deployment creates recruitment bottlenecks for platform developers.
- Multi-Domain Integration Complexity:Coordinating USV operations with unmanned underwater vehicles and aerial drones demands new command-and-control software architectures that exceed legacy naval IT capabilities.
- Environmental Hardening Capex:Salt spray corrosion protection and extreme weather sensor resilience require specialized materials testing that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Unmanned Surface Vehicle (USV) Market |
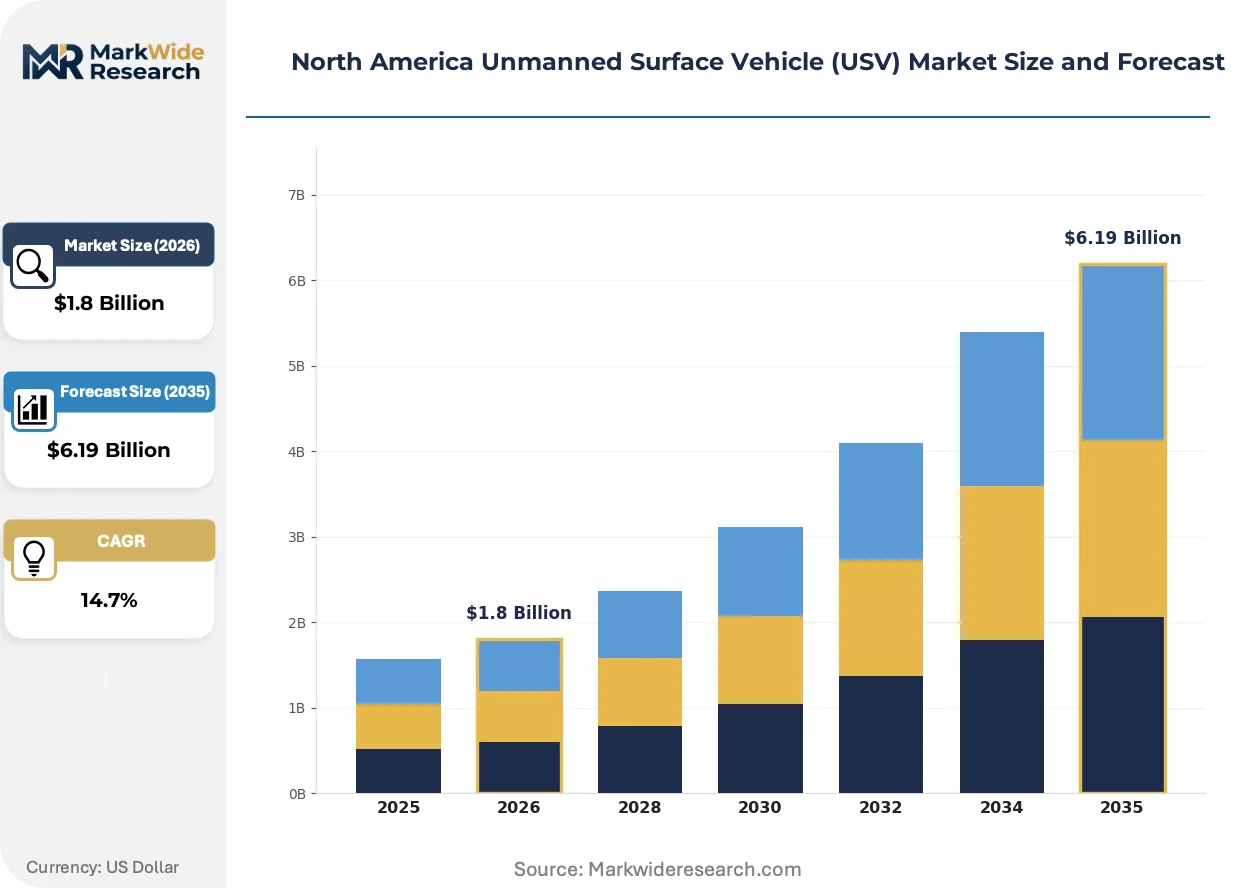
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
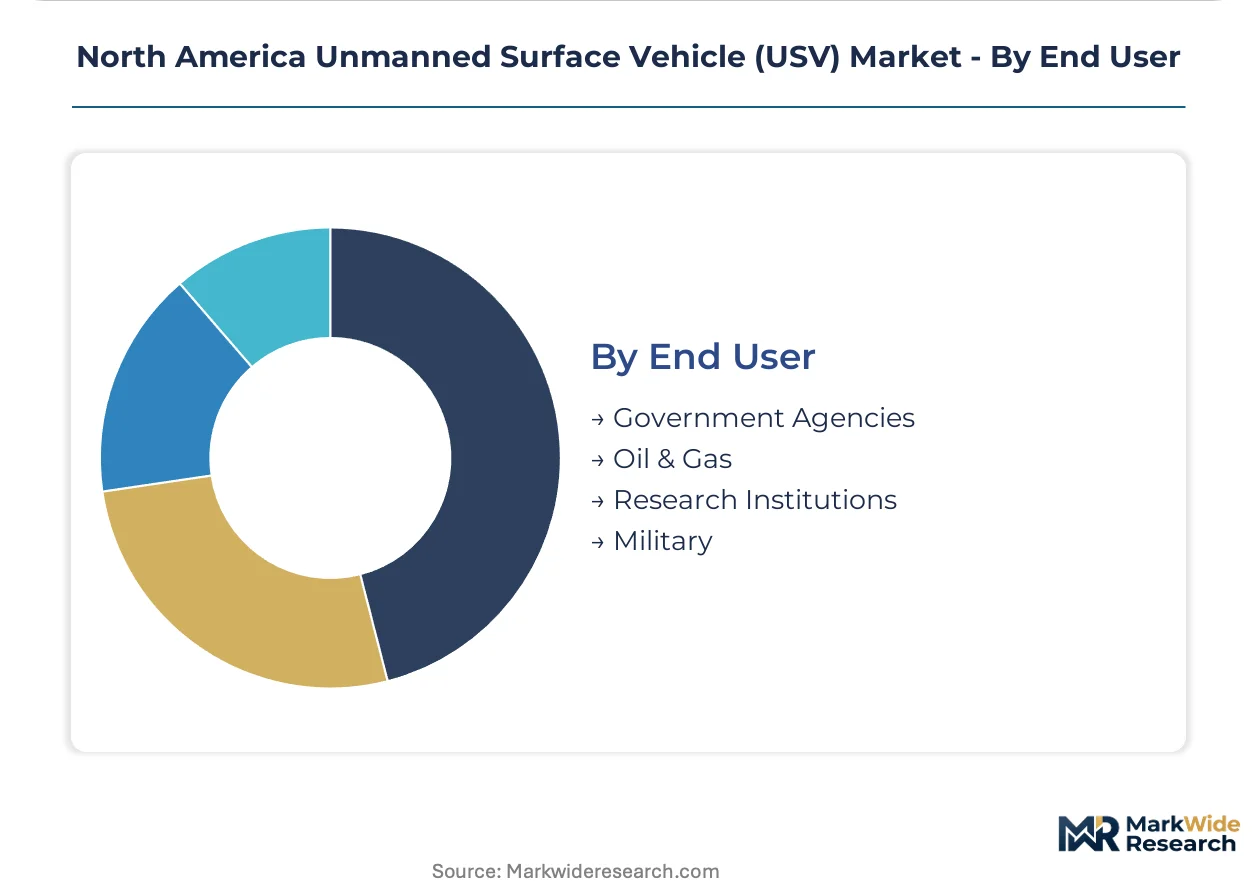
| Segmentation | Application: Marine Research, Surveillance, Search & Rescue, Environmental Monitoring Type: Autonomous, Remote-Controlled, Hybrid, Surface Technology: GPS, IoT, Sonar, LiDAR End User: Government Agencies, Oil & Gas, Research Institutions, Military |
| Companies Covered | Clearpath Robotics Inc., Saildrone Inc., L3Harris Technologies Inc., Maritime Tactical Systems Inc., Maritime Robotics, Textron Inc., SeaRobotics Corp., Ocean Aero, Teledyne Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Unmanned Surface Vehicle (USV) Market Evolving Landscape
Solar-electric propulsion architectures are decomposing traditional diesel-hull design paradigms. Three convergent developments are compressing platform development cycles and reshaping competitive positioning in North American waters.
Photovoltaic-integrated hull surfaces are decomposing the fuel logistics burden for long-duration ocean data collection. Research institutions and offshore energy operators are adopting solar-electric architectures at accelerating pace. This technology shift is compressing operational cost structures and extending mission endurance windows beyond diesel-economy break-even points.
The FAA's beyond-line-of-sight communications framework is migrating into maritime certification protocols through Navy-Coast Guard coordination. This regulatory convergence creates unified air-sea autonomy standards that reduce redundant testing burdens. California and Gulf Coast test ranges are adapting airspace coordination procedures for coastal waterway operations.
Defense procurement officers are unbundling sensor payload specifications from hull platform contracts. This buying-pattern change disrupts integrated system vendors and elevates modular payload specialists. The U.S. Navy's reconfigurable hull family procurement strategy exemplifies this shift across Atlantic and Pacific fleet commands.
North America Unmanned Surface Vehicle (USV) Market Segmentation
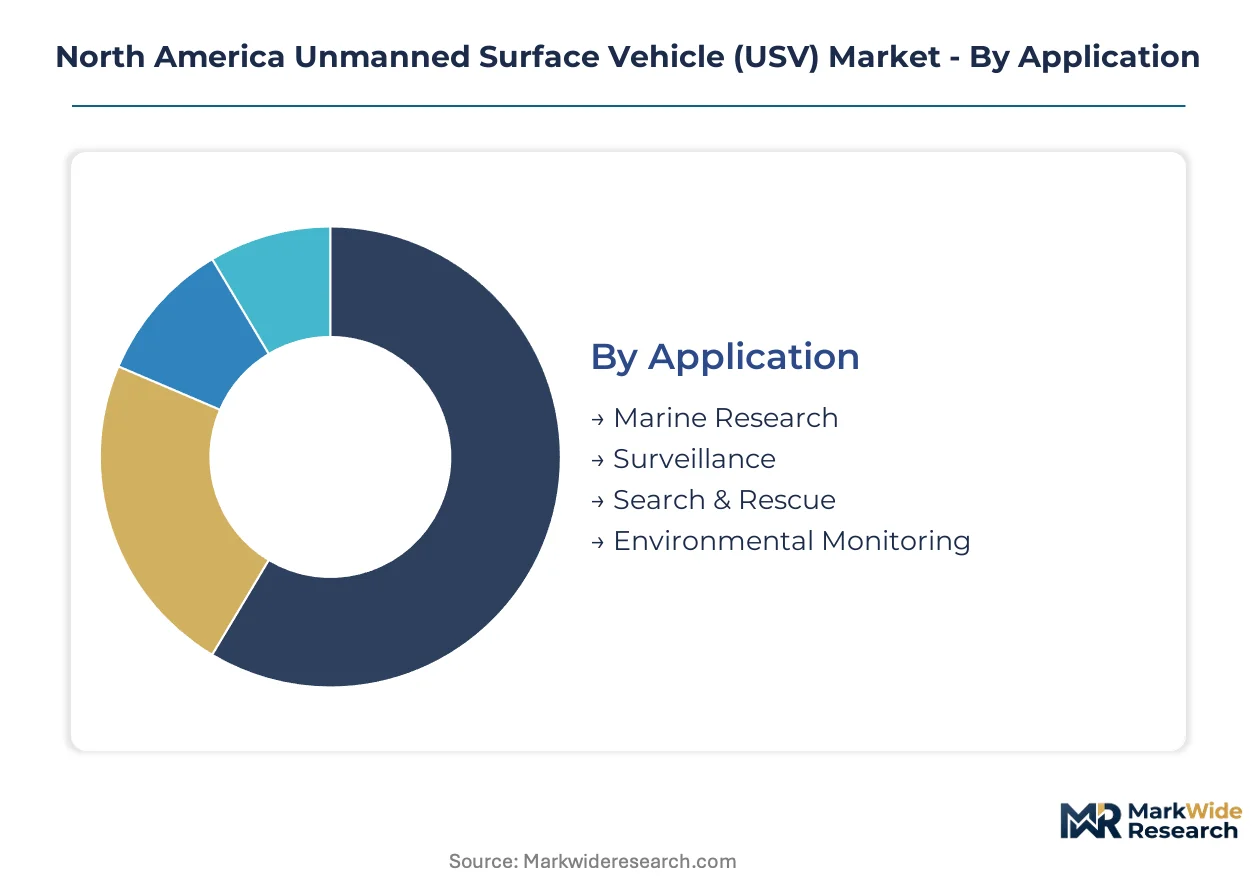
Segmentation in the North America USV market reveals how procurement patterns diverge between defense-grade encrypted platforms and commercial modular systems. Understanding these fault lines exposes where substitution pressures from unmanned underwater vehicles and aerial drones threaten incumbent hull architectures.
Application:
Surveillance platforms face acute substitution pressure from low-altitude unmanned aerial systems in harbor security roles, while marine research applications resist displacement due to payload capacity requirements.
- Marine Research:Long-duration oceanographic data collection demands solar-electric propulsion and modular sensor bays. California's Monterey Bay research cluster and Gulf Coast oceanography programs anchor procurement volumes for hulls exceeding ten meters in length.
- Surveillance:Perimeter patrol and harbor monitoring integrate radar and optical payloads with encrypted communication modules. The U.S. Coast Guard's updated integration mandate is compressing certification timelines for platforms serving Atlantic and Pacific fleet commands.
- Search & Rescue:Rapid deployment hulls prioritize maneuverability over endurance for coastal emergency response.
- Environmental Monitoring:Water quality sampling and spill detection units serve EPA regional offices and state environmental agencies across the Great Lakes corridor.
Marine Research anchors the volume base while Surveillance gains share at the steepest rate.
Type:
Cost tier stratification separates military procurement of hardened autonomous hulls from commercial operators retaining remote-controlled architectures to preserve capital flexibility.
- Autonomous:Self-navigating platforms integrate collision-avoidance algorithms with GPS waypoint systems for beyond-line-of-sight operations. The U.S. Navy's Unmanned Task Force coordinates FAA certification frameworks that accelerate coastal deployment timelines.
- Remote-Controlled:Tethered or radio-linked architectures persist in harbor security fleets where sunk capital and retraining costs resist full autonomy migration.
- Hybrid:Switchable autonomy modes accommodate mixed fleet operations where operators toggle between supervised and unsupervised navigation.
- Surface:Standard displacement hulls without submersible capability dominate commercial test-bed applications in Louisiana offshore energy zones.
Autonomous hulls command the premium tier while Remote-Controlled units retain installed-base dominance in commercial harbors.
Technology:
Technology selection tracks mission endurance requirements, with power-hungry sensors concentrated in military platforms and low-draw systems dominating solar-electric research vessels.
- GPS:Waypoint navigation and geofencing capabilities form the baseline positioning layer for all hull categories. Signal redundancy requirements differ sharply between civilian and encrypted military implementations.
- IoT:Fleet connectivity and real-time data streaming enable coordinated multi-hull operations for offshore energy inspection services in the Gulf of Mexico.
- Sonar:Subsurface mapping and obstacle detection payloads concentrate in research and military end uses requiring bathymetric survey capabilities.
- LiDAR:High-resolution surface scanning supports autonomous navigation in cluttered coastal environments and precision docking maneuvers.
GPS and Sonar together anchor sensor procurement volumes while IoT connectivity expands most quickly across commercial fleet operators.
End User:
Customer type determines margin structure, with military and oil sector buyers funding hardened encrypted modules while research institutions drive volume in standardized payload configurations.
- Government Agencies:Coast Guard and EPA procurement emphasizes regulatory compliance and interoperability with existing fleet management systems. Federal acquisition regulations favor reconfigurable hull families over single-mission platforms.
- Military:Naval procurement concentrates margin pools in NSA Type 1 encrypted communication modules and hardened sensor payloads. The U.S. Navy's Atlantic and Pacific fleet commands drive demand for reconfigurable autonomy standards.
- Oil & Gas:Platform maintenance and subsea inspection-as-a-service models create recurring revenue streams for operators serving Gulf of Mexico infrastructure.
- Research Institutions:Universities and oceanographic institutes prioritize modular payload bays and open software architectures for experimental sensor integration.
Military end users anchor the value pool while Oil & Gas operators are climbing the fastest as unbundled service models displace capital ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform builders cluster along coastal defense corridors and offshore energy zones. Shipyard capacity concentrates in Louisiana and Texas, while autonomy engineering talent pools in California and Atlantic Canada. Procurement flows through federal naval commands and commercial energy operators.
United States
The U.S. Navy's Unmanned Task Force coordinates FAA certification for beyond-line-of-sight coastal communications. EPA regional offices across the Great Lakes corridor deploy water quality sampling hulls for environmental monitoring mandates. California's Monterey Bay and San Diego clusters host venture-backed autonomy startups with direct Navy research partnerships.
Canada
Transport Canada harmonizes collision regulations with the U.S. Coast Guard for autonomous vessels transiting shared Atlantic and Great Lakes waterways. The Canadian Coast Guard integrates USV platforms into Arctic patrol operations under updated unmanned systems procurement guidelines. Atlantic Canada shipyards in Nova Scotia and Newfoundland service offshore energy inspection contracts for Gulf of St. Lawrence infrastructure.
Mexico
Pemex unbundles platform maintenance contracts for Gulf of Mexico offshore infrastructure, creating service-model demand for inspection hulls. The Secretariat of Navy (SEMAR) evaluates autonomous patrol platforms for Pacific and Gulf Coast maritime security zones. Veracruz and Tamaulipas port authorities test harbor security USVs for container terminal perimeter monitoring.
North America Unmanned Surface Vehicle (USV) Market Competitive Landscape
Concentration sits with defense electronics heritage players and solar-electric hull specialists. The market structures around two tiers: integrated system vendors with encrypted communication capabilities and modular platform builders serving commercial research applications. Strategic archetypes include hardened military-grade suppliers, long-endurance ocean data collectors, and harbor security command-and-control integrators. Competitive moves center on sensor payload unbundling from hull contracts and rapid prototype-to-production scaling near offshore energy test beds.
Among defense-anchored suppliers, L3Harris Technologies Inc. and Textron Inc. occupy positions tied to federal procurement pipelines. Saildrone Inc. exemplifies the solar-electric architecture segment serving research and commercial data collection missions. These three entities represent distinct competitive vectors: encrypted module integration, command-and-control layer dominance, and renewable-propulsion endurance leadership.
| Leading Market Players |
|---|
| Clearpath Robotics Inc. |
| Saildrone Inc. |
| L3Harris Technologies Inc. |
| Maritime Tactical Systems Inc. |
| Maritime Robotics |
| Textron Inc. |
| SeaRobotics Corp. |
| Ocean Aero |
| Teledyne Technologies Incorporated |
| Others |
Value Network & Pricing Analysis
Shipyard capacity utilization in Louisiana and Texas shapes both supply concentration and price floors for hull platforms, with Gulf Coast clustering enabling rapid prototype-to-production scaling that compresses cost structures for defense and commercial buyers alike.
Pricing Analysis
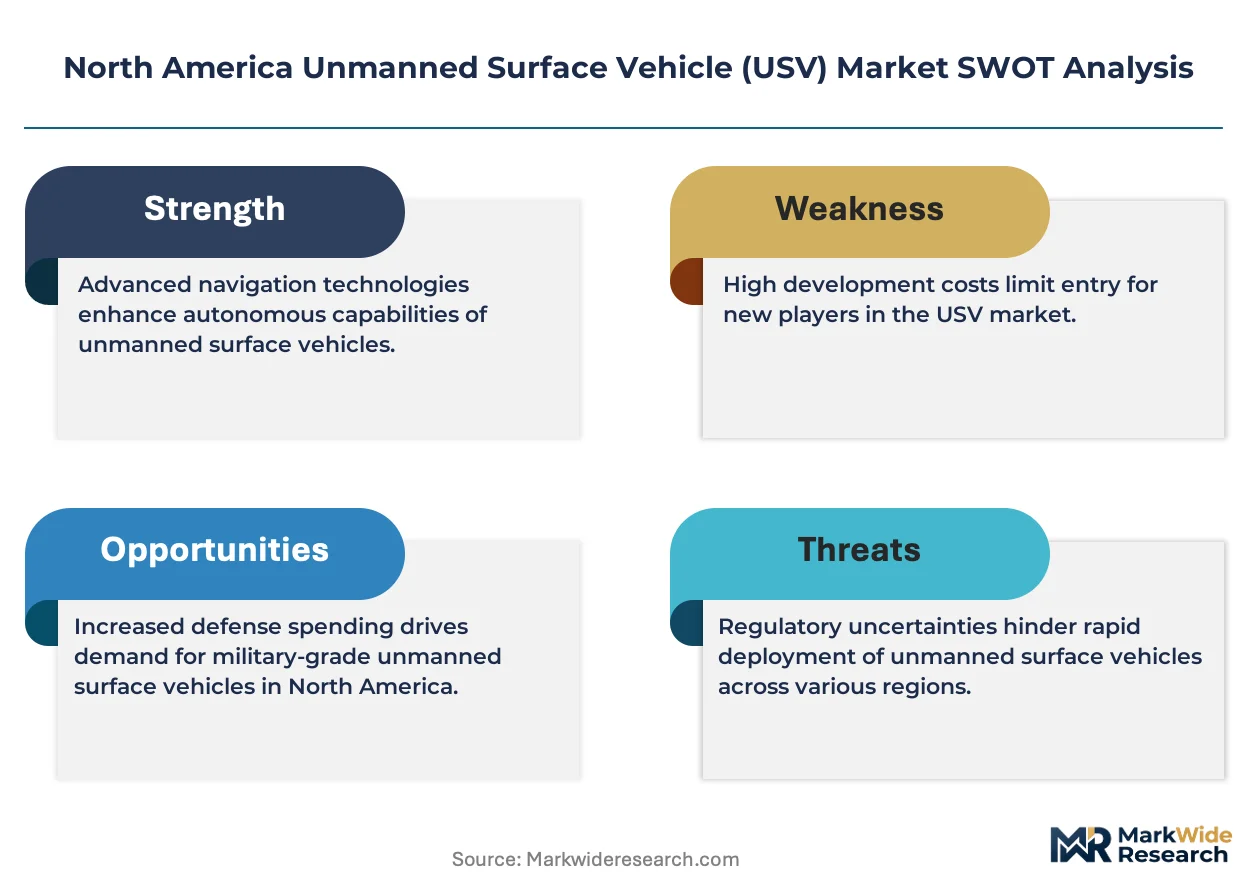
The U.S. Coast Guard's updated unmanned systems integration mandate dictates the pricing tier structure across military and commercial procurement. Three-tier pricing structure across premium, standard, and economy levels separates NSA Type 1 encrypted modules from commercial-grade sensor packages and research-tier modular bays. Cost compression in commercial remote-controlled units is intensifying because Asian lithium-ion cell manufacturers dominate battery supply. Research institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while naval commands prioritize hardened communication modules over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate commercial solar-electric hull assembly, whereas defense procurement favors strategic stockpiles of encrypted communication modules to circumvent multi-year NSA certification bottlenecks. Lithium-ion cells draw from China, South Korea, and Japan, with photovoltaic panels sourcing from Southeast Asian fabrication facilities. Hardened sensor payloads and collision-avoidance algorithms rest on single-source vulnerability for military-grade components. Distribution runs through federal naval acquisition channels and Gulf Coast offshore energy service contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American USV procurement is accelerating through regulatory inflection as the FAA's beyond-line-of-sight communications framework migrates into maritime certification protocols, collapsing deployment timelines for autonomous hull architectures.
For Market Incumbents: Consolidate encrypted module supply through backward integration into domestic semiconductor packaging, reducing exposure to Asian cell manufacturer volatility. Acquire California-based autonomy engineering talent pools to defend against venture-backed startup disruption in long-duration ocean data collection. Priority investment in Great Lakes regulatory harmonization capabilities secures cross-border contract pipelines.
For New Entrants and Emerging Players: Anchor in subsea inspection-as-a-service models for Gulf of Mexico oil majors, where unbundled maintenance contracts create recurring revenue white space. Target marine research institutions in Monterey Bay and Atlantic Canada for modular payload bay penetration. Go-to-market leverage through Navy research partnerships accelerates platform certification timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among solar-electric hull operators serving offshore energy infrastructure. Long-term viability over a multi-year horizon hinges on differentiation in autonomous navigation software rather than hull fabrication. Acquisition focus on firms with FAA-maritime certification coordination capabilities. Signal to monitor: Transport Canada-U.S. Coast Guard regulatory harmonization progress on collision standards.
| Strategic Initiative | Industry Significance |
|---|---|
| NSA Type 1 Module Certification Investment | Accelerates military platform fielding timelines through hardened communication standards. |
| Solar-Electric Hull Architecture Expansion | Extends mission endurance beyond diesel-economy break-even for ocean data collection. |
| California Autonomy Talent Acquisition | Secures machine learning deployment capabilities for collision-avoidance algorithm development. |
| Gulf Coast Shipyard Capacity Scaling | Enables rapid prototype-to-production conversion for offshore energy test-bed demand. |
| Payload-Unbundled Procurement Strategy | Aligns with U.S. Navy reconfigurable hull family buying patterns across fleet commands. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with naval procurement officers, Coast Guard certification specialists, offshore energy maintenance directors, autonomy engineering leads, and shipyard production managers. Secondary validation drew from U.S. Navy Unmanned Task Force coordination documents, FAA maritime certification frameworks, Transport Canada regulatory harmonization bulletins, SEC filings of defense electronics suppliers, and Gulf Coast offshore energy contract databases. Bottom-up hull deployment estimates triangulated against top-down defense budget allocation analysis.
Across the analysis window, projections integrated application-type segmentation by surveillance, marine research, and environmental monitoring missions; technology segmentation across GPS, IoT, sonar, and LiDAR sensor stacks; and end-user differentiation between military encrypted platforms and commercial modular systems. CAGRs were derived from weighted scenario modeling of regulatory acceleration versus certification bottleneck scenarios. Forecast inputs incorporated lithium-ion supply cost trajectories and solar-electric propulsion adoption curves.
Decision-makers should treat outputs as directional under sustained FAA-Coast Guard coordination and stable Asian battery supply assumptions; material deviation would warrant model refresh. Revision becomes warranted when NSA Type 1 encryption validation cycles or lithium-ion geopolitical exposure crosses operational disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Military Robotics Market