
 United States ROV Market | 2026-2036
United States ROV Market Size, Share, and Industry Trends Forecast 2026-2036
United States ROV Market Analytics
Composite pressure housings are repositioning product economics across the United States ROV Market by cutting dry weight versus traditional aluminum and titanium architectures. Oceaneering International Inc leverages its integrated subsea services footprint to anchor work-class ROV deployment contracts in the Gulf of Mexico. Teledyne Technologies Incorporated sustains technology leadership through advanced imaging and sensor payloads that differentiate its systems for scientific and defense applications. Deep Trekker competes in the portable observation segment with battery-powered designs that occupy a distinct niche below heavy work-class platforms.
A remotely operated vehicle (ROV) is an uncrewed underwater system connected to a surface vessel via a tether carrying power, data, and control signals, typically rated for depths from 300 to 6,000 meters depending on hull construction and pressure vessel design. These systems perform visual inspection, physical intervention, and sensor deployment in environments that exceed human diving limits or safety thresholds. Work-class ROVs command the dominant share of value given their hydraulic tooling capacity and role in subsea construction and decommissioning, while inspection ROVs represent the fastest-expanding category as pipeline integrity management requirements tighten across aging offshore infrastructure. Observation ROVs serve a mature but stable demand pool in marine research and media production where cost sensitivity limits upgrade cycles.
The Bureau of Safety and Environmental Enforcement mandates mechanical integrity programs for subsea equipment on the Outer Continental Shelf, directly driving ROV inspection frequency and documentation standards. The National Oceanic and Atmospheric Administration coordinates deep-ocean research missions that expand the addressable base for science-rated systems, while the Department of Defense accelerates undersea warfare and mine countermeasures programs that shape procurement specifications for defense-grade ROVs. Stakeholders must weigh capital intensity against fleet utilization rates when sizing work-class commitments, as day-rate volatility in offshore energy services compresses payback windows faster than technology refresh cycles.
Market Dynamics
Composite pressure housings are compressing vessel weight-to-buoyancy ratios across the United States ROV Market, forcing recalibration of launch and recovery system specifications and tether load calculations. This materials transition is redistributing competitive advantage toward suppliers with in-house composite fabrication capabilities.
Growth Catalysts
- The Infrastructure Investment and Jobs Act:Federal port modernization allocations are expanding the installed base of underwater inspection infrastructure, creating recurring demand for observation-class systems in harbor maintenance contracts.
- Offshore decommissioning liability:Aging Gulf of Mexico platforms are triggering mandatory removal timelines under Bureau of Safety and Environmental Enforcement guidelines, sustaining work-class ROV utilization for cutting and lifting operations.
- Autonomous docking systems:Resident ROV architectures with subsea garage interfaces are eliminating surface weather dependency for continuous inspection campaigns on subsea production equipment.
Market Restraints
- Day-rate volatility:Offshore energy service pricing swings compress fleet payback periods below typical seven-year depreciation schedules, discouraging speculative capacity additions by independent operators.
- High-voltage tether supply:Specialized copper and fiber-optic cable manufacturing concentrates among a limited supplier base, exposing operators to lead-time extensions during upstream raw material constraints.
- Depth rating certification costs:Bureau Veritas and DNV pressure vessel qualification protocols impose six-figure testing expenditures that barrier entry for inspection-class system startups targeting full ocean depth ratings.
Strategic Opportunities
- California offshore wind lease areas:Pacific Coast floating turbine installations will require cable burial and foundation inspection services outside existing Gulf of Mexico operational footprints.
- Hyperspectral imaging convergence:Integration of subsea lidar with machine-vision classification algorithms enables automated corrosion mapping without diver verification, opening subscription-based analytics revenue streams.
- Department of Defense mine countermeasures:Naval procurement specifications for expeditionary undersea warfare are expanding addressable demand for portable, rapidly deployable observation platforms with low magnetic signatures.
Industry Challenges
- Pilot-technician pipeline gaps:ROV operator certification through the Association of Diving Contractors International requires 1,000+ logged dive hours, constraining fleet expansion during demand surges.
- Legacy hydraulic integration:Work-class platforms with 20-year service histories face tooling interface incompatibility with modern electric manipulator architectures, forcing expensive mid-life system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States ROV Market |
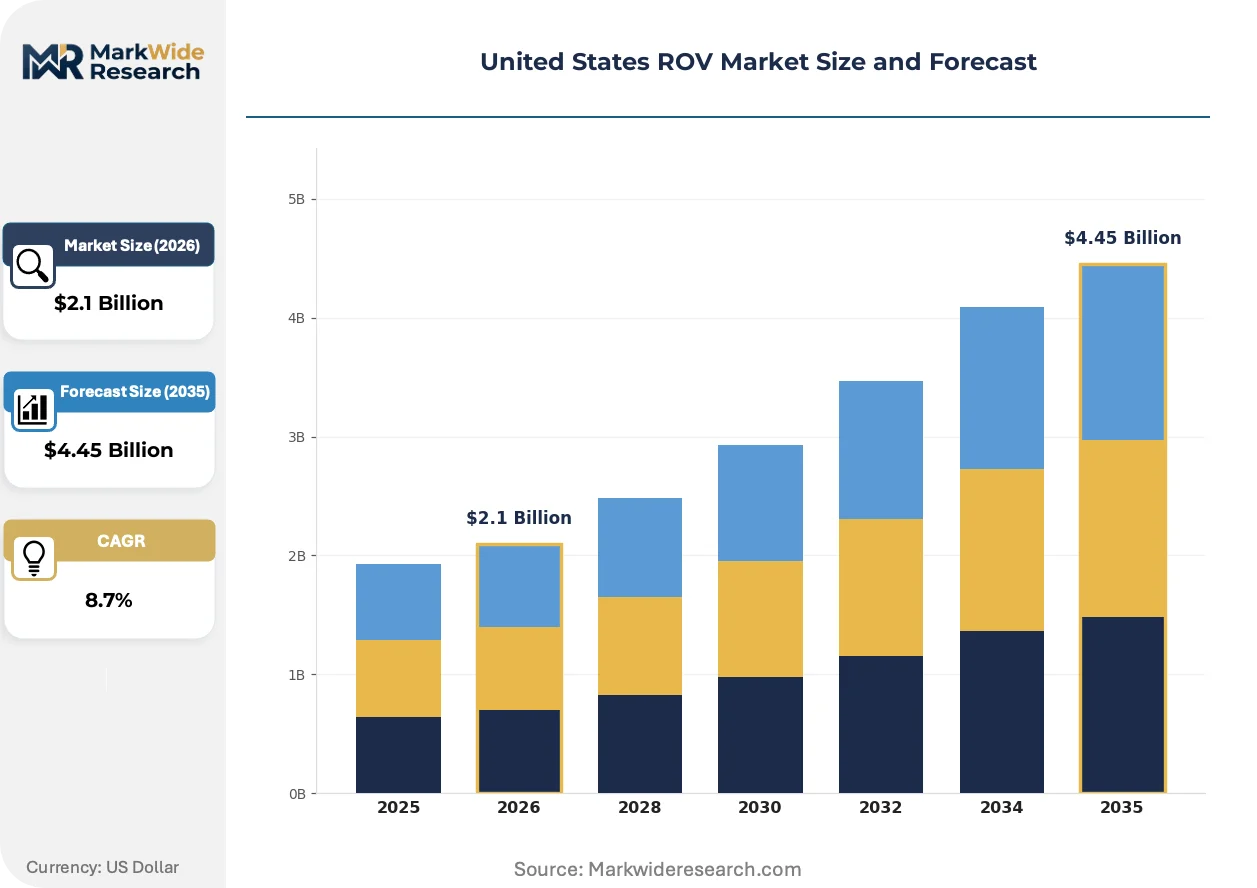
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Observation ROVs, Inspection ROVs, Work-class ROVs, Hybrid ROVs End User: Oil & Gas, Marine Research, Defense, Aquaculture Deployment Type: Surface-launched, Subsea-launched, Tethered, Autonomous Control System: Remote Operated, Autonomous Navigation, Manual Control, Semi-autonomous |
| Companies Covered | VideoRay, Saab Seaeye, Oceaneering International Inc, Exail Technologies, Deep Trekker, TechnipFMC PLC, Teledyne Technologies Incorporated, DOF Subsea AS, Helix Energy Solutions Group Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States ROV Market Evolving Landscape
Artificial intelligence is penetrating subsea operations at the sensor-processing layer, compressing inspection cycle times and enabling predictive maintenance models for subsea infrastructure. These developments are converging with resident ROV architectures to restructure offshore service economics.
Machine-vision defect classification is automating pipeline anomaly detection that previously required human operator interpretation of video feeds. Offshore integrity management contractors are deploying these systems on tethered platforms in the Gulf of Mexico, reducing inspection report generation from days to hours. This compression is automating documentation workflows and shifting labor allocation from piloting to data validation functions.
The Bureau of Safety and Environmental Enforcement has tightened mechanical integrity documentation requirements for subsea safety-critical equipment on the Outer Continental Shelf. Operators must now maintain continuous inspection records with traceable sensor calibration chains, elevating data management to a compliance function. Work-class ROV fleets are responding by integrating blockchain-anchored logging systems to satisfy audit trail mandates.
Charter contracting is displacing traditional equipment purchase models among mid-size offshore operators facing utilization uncertainty. Service providers in Houston are unbundling platform provision from pilot and data analysis services, allowing clients to scale commitment across project phases. This flexibility is most pronounced in post-hurricane infrastructure damage assessment campaigns along the Louisiana and Texas coastlines.
United States ROV Market Segmentation
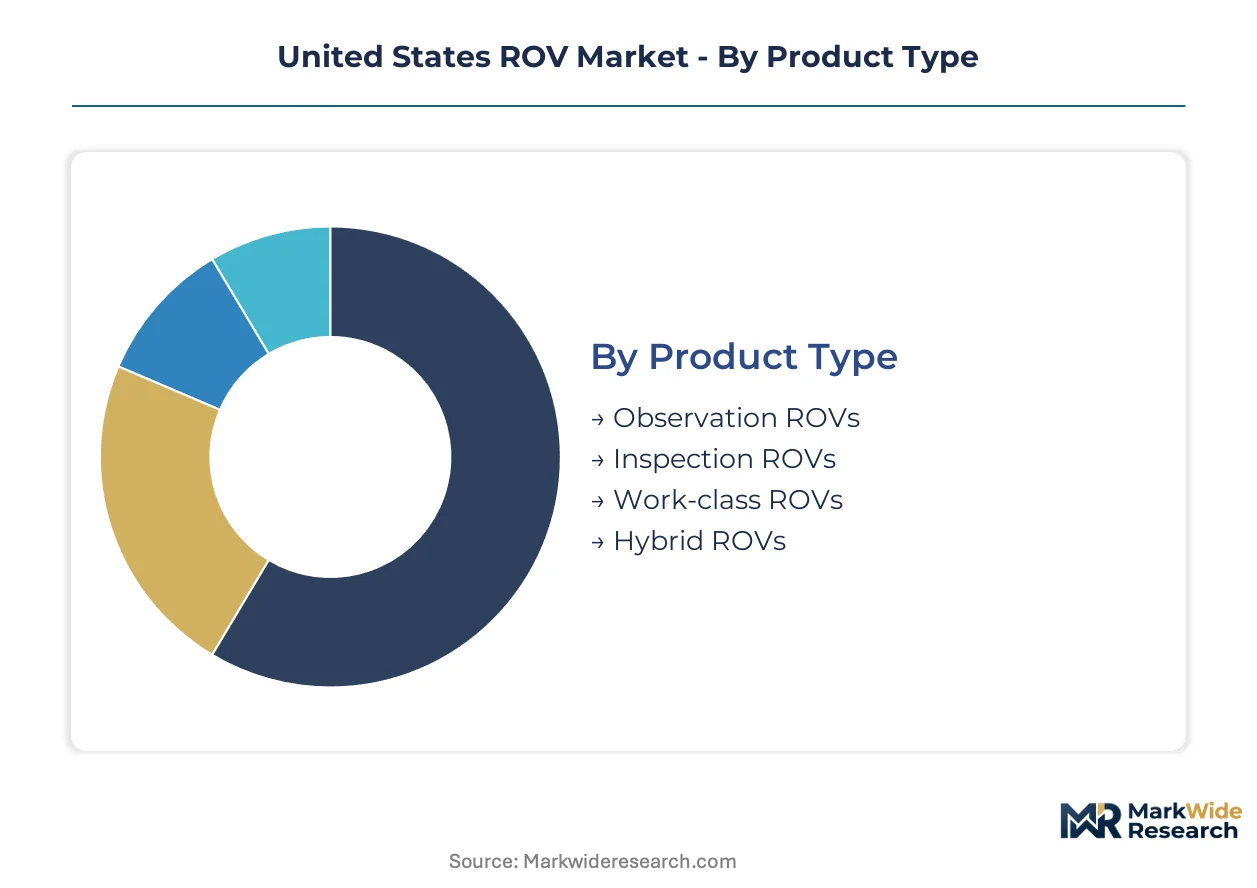
ROV procurement decisions in the United States hinge on depth rating, tooling payload, and regulatory compliance requirements that vary sharply across offshore energy, defense, and scientific applications. Segmentation reveals how capital intensity and operational complexity stratify buyer priorities and vendor specialization.
Product Type:
Capital deployment thresholds and hydraulic power requirements dominate buyer selection across the four product tiers.
- Work-class ROVs:These systems integrate hydraulic manipulators and heavy-lift skids rated for 3,000+ meter operations on subsea construction and decommissioning campaigns. Gulf of Mexico operators anchor fleet utilization here, with Bureau of Safety and Environmental Enforcement mandates sustaining inspection frequency on aging platform infrastructure.
- Inspection ROVs:Electric-thruster platforms with modular sensor payloads target pipeline integrity management where regulatory documentation requirements have tightened. These systems are expanding most quickly as autonomous docking architectures eliminate surface weather dependency for continuous monitoring.
- Observation ROVs:Portable battery-powered units serve marine research and media production with cost sensitivity limiting upgrade cycles to 7-10 year intervals.
- Hybrid ROVs:Dual-mode architectures switch between tethered precision and untethered autonomous operation for mine countermeasures and expeditionary defense applications.
Work-class ROVs lead on scale; inspection ROVs lead on momentum.
End User:
Regulatory pressure and federal funding flows determine addressable demand intensity across verticals.
- Oil & Gas:Offshore operators on the Outer Continental Shelf deploy work-class fleets for subsea tree intervention and platform decommissioning. Mechanical integrity program mandates from the Bureau of Safety and Environmental Enforcement directly specify ROV inspection frequency and sensor calibration chains.
- Defense:Naval procurement for expeditionary mine countermeasures drives demand for low-magnetic-signature observation platforms with rapid deployment protocols. Department of Defense specifications shape pressure vessel and tether electromagnetic requirements.
- Marine Research:National Oceanic and Atmospheric Administration mission allocations fund deep-ocean rated systems for benthic habitat mapping and climate monitoring.
- Aquaculture:Net inspection and mort retrieval operations in Pacific Northwest salmon farms create niche demand for portable observation units with biofouling-resistant coatings.
Oil & Gas commands installed base volume; defense procurement is climbing the fastest.
Deployment Type:
Launch system integration and weather window constraints differentiate operational economics.
- Tethered:Standard power and data umbilical configurations dominate offshore energy services where real-time pilot control is non-negotiable for intervention tasks. High-voltage copper and fiber-optic cable supply concentrates among limited manufacturers, exposing operators to raw material lead-time volatility.
- Autonomous:Untethered architectures with acoustic positioning and onboard power eliminate surface vessel day-rate exposure for survey missions. California offshore wind lease development is accelerating qualification programs for cable burial without continuous surface support.
- Surface-launched:Conventional over-the-side deployment from dynamically positioned vessels remains standard for Gulf of Mexico work-class operations.
- Subsea-launched:Resident garage systems with subsea docking interfaces enable continuous inspection without retrieval through weather windows.
Tethered systems anchor current fleet composition; autonomous architectures are gaining share fastest.
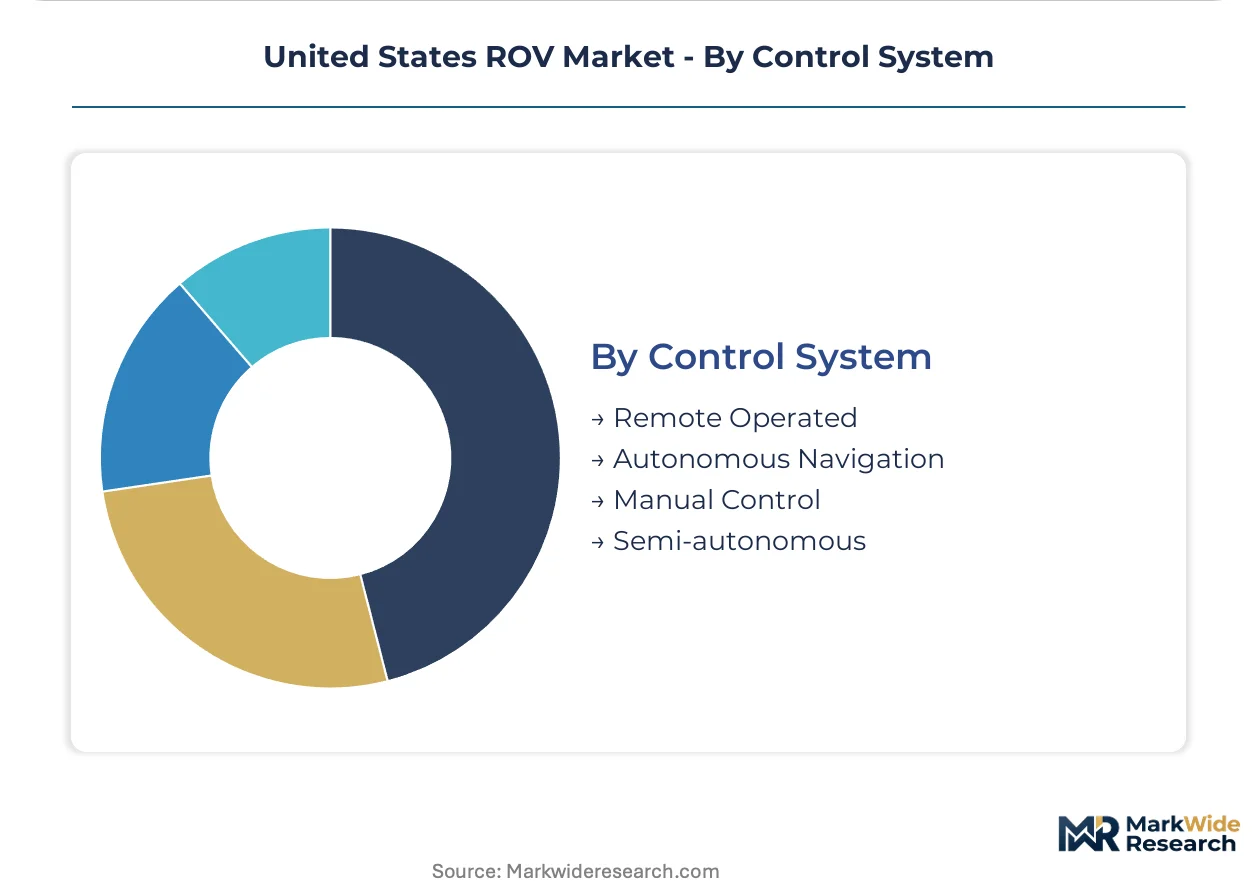
Control System:
Pilot certification pipelines and automation trust thresholds shape adoption curves.
- Remote Operated:Surface pilot control via fiber-optic telemetry remains mandatory for intervention tasks requiring force-feedback manipulator precision. Association of Diving Contractors International certification requirements constrain operator supply during demand surges.
- Autonomous Navigation:Machine-vision waypoint following with collision avoidance enables survey missions without continuous human oversight. Integration of subsea lidar with corrosion classification algorithms is compressing inspection report generation timelines.
- Manual Control:Direct joystick piloting persists in training environments and contingency override protocols.
- Semi-autonomous:Human-supervised automation with intervention-on-demand protocols balances efficiency with liability management for critical infrastructure inspection.
Remote operated control leads on installed base; autonomous navigation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast industrial corridor concentrates United States ROV demand through Houston's integrated subsea services ecosystem. Federal infrastructure spending and offshore energy mandates distribute procurement across coastal states with distinct operational specializations.
Gulf Coast
Offshore oil and gas decommissioning campaigns and subsea tree interventions sustain work-class ROV utilization throughout Louisiana and Texas waters. Bureau of Safety and Environmental Enforcement mechanical integrity programs mandate inspection frequency on aging Outer Continental Shelf infrastructure. Houston anchors the national supplier base, hosting equipment manufacturers and service providers that deploy fleets across the Gulf of Mexico.
California
Pacific Coast offshore wind lease development is accelerating demand for cable burial and floating foundation inspection services outside traditional Gulf operational footprints. State renewable energy mandates and federal lease auctions are channeling capital toward autonomous system qualification programs. San Diego and Los Angeles ports host emerging clusters of survey contractors positioning for floating turbine installation support.
Mid-Atlantic
Port modernization allocations under the Infrastructure Investment and Jobs Act are expanding underwater inspection infrastructure from Norfolk to New York Harbor. Army Corps of Engineers maintenance dredging and bridge foundation assessments create recurring observation-class system demand. Baltimore and Philadelphia industrial zones concentrate harbor maintenance contractors with resident ROV capabilities.
Pacific Northwest
Salmon aquaculture net inspection and mort retrieval operations in Washington and Oregon waters generate niche demand for portable observation units with biofouling-resistant coatings. National Oceanic and Atmospheric Administration deep-ocean research missions out of Seattle expand the addressable base for science-rated systems. The region's marine research institutions anchor a stable demand pool distinct from energy-sector procurement cycles.
United States ROV Market Competitive Landscape
Global majors compete with regional champions across technology tiers and service integration depth, producing a stratified vendor landscape. Work-class platform provision concentrates among integrated subsea service conglomerates with captive fleet deployment capabilities. Three archetypes dominate: full-service contractors bundling equipment with pilot and data services; technology specialists supplying imaging and sensor payloads; and portable system manufacturers serving inspection and observation niches. Competitive dynamics center on charter contracting flexibility and resident ROV architecture development.
Within the integrated services tier, Oceaneering International Inc and TechnipFMC PLC exemplify conglomerate structures that anchor Gulf of Mexico work-class deployment through combined equipment and operational capabilities. Teledyne Technologies Incorporated occupies a position among technology specialists, representing advanced payload integration for defense and scientific applications. Deep Trekker exemplifies the portable observation segment, sitting within battery-powered system manufacturing for cost-sensitive inspection verticals.
| Leading Market Players |
|---|
| VideoRay |
| Saab Seaeye |
| Oceaneering International Inc |
| Exail Technologies |
| Deep Trekker |
| TechnipFMC PLC |
| Teledyne Technologies Incorporated |
| DOF Subsea AS |
| Helix Energy Solutions Group Inc |
| Others |
Value Network & Pricing Analysis
Captive composite fabrication capabilities among integrated subsea service providers anchor both supply security and pricing power across the United States ROV Market. Houston-based conglomerates with in-house pressure vessel manufacturing deflect raw material volatility while independent operators absorb copper tether and fiber-optic cable cost swings through spot market exposure.
Pricing Analysis
Input-cost pass-through from high-voltage tether suppliers concentrates pricing pressure on inspection-class system operators lacking long-term copper cable offtake agreements. Three-tier pricing structure across premium work-class, standard inspection, and economy observation levels separates hydraulic tooling capacity from electric-thruster modularity from portable battery-powered units. Cost compression in the observation tier intensifies because Deep Trekker and VideoRay compete on dry weight and deployment speed rather than depth rating. Federal port contractors exhibit the highest price sensitivity due to Infrastructure Investment and Jobs Act procurement caps, while Department of Defense mine countermeasures programs accept premium positioning for low-magnetic-signature architectures.
Supply Chain Analysis
Freight costs from Norwegian and British subsea component specialists elevate landed costs for Gulf of Mexico operators sourcing resident ROV garage systems and acoustic positioning arrays. The United States ROV Market draws from Canadian composite pressure housing fabricators, Japanese high-density battery cell manufacturers, and German precision hydraulic pump suppliers for work-class manipulator architectures. Single-source vulnerability concentrates in specialized copper and fiber-optic tether manufacturing where a limited supplier base exposes operators to six-month lead-time extensions during upstream raw material constraints. Distribution runs through Houston equipment depots that stage platforms for charter contracting across Louisiana and Texas offshore blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States ROV Market offers margin expansion through composite materials substitution that cuts dry weight and launch system specifications, while resident ROV architectures command premium charter rates by eliminating surface weather dependency.
For Market Incumbents: Lock in composite fabrication capacity through captive production or exclusive offtake from Tier 1 suppliers to defend against tethered-platform commoditization. Expand resident ROV garage deployments across Gulf of Mexico subsea production equipment to capture continuous inspection contracts that autonomous docking systems enable. Bureau of Safety and Environmental Enforcement documentation mandates favor operators with blockchain-anchored logging infrastructure. For New Entrants and Emerging Players: Begin with California offshore wind lease areas where cable burial and floating foundation inspection services lack established Gulf of Mexico operational footprints. Target Pacific Coast survey contractors positioning for floating turbine installation support with autonomous system qualification programs. A direct sales model to state renewable energy authorities bypasses Houston service provider gatekeeping. For Investors and Strategic Acquirers: Consolidation pressure builds where pilot-technician pipeline gaps constrain fleet expansion during demand surges for post-hurricane infrastructure assessment campaigns. Long-term viability centers on technology specialists with advanced imaging payload integration for defense and scientific verticals rather than commodity work-class platform lessors. Watch Association of Diving Contractors International certification waitlist durations as an inflection indicator for labor-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Resident ROV Architecture Deployment | Eliminates surface weather dependency for continuous Bureau of Safety and Environmental Enforcement compliance inspection. |
| Composite Pressure Housing Integration | Reduces dry weight versus aluminum architectures to recalibrate launch and recovery system specifications. |
| Hyperspectral Imaging Payload Development | Enables automated corrosion mapping without diver verification for subscription-based analytics revenue. |
| California Offshore Wind Qualification | Positions contractors for Pacific Coast floating turbine cable burial outside traditional Gulf footprints. |
| Pilot-Technician Certification Pipeline Investment | Addresses Association of Diving Contractors International 1,000-hour logged dive requirements constraining fleet expansion. |
Research Methodology
Multiple input streams — structured interviews with ROV fleet managers and subsea service executives, regulatory filing analysis from the Bureau of Safety and Environmental Enforcement and National Oceanic and Atmospheric Administration, and equipment procurement database tracking — were reconciled through bottom-up and top-down triangulation. Secondary validation incorporated Outer Continental Shelf leasing records, Army Corps of Engineers port modernization contract awards, and Department of Defense naval procurement specifications. Primary fieldwork engaged pilot-technicians, harbor maintenance contractors, and composite pressure vessel fabricators across Houston, San Diego, and Seattle operational clusters.
Historical deployment data cross-referenced against industry panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use vertical, deployment architecture, and control system automation level. CAGRs were derived from fleet utilization rate trajectories, federal infrastructure spending allocation patterns, and offshore decommissioning liability timelines. Forecast inputs incorporated composite materials adoption curves and autonomous docking system qualification progress.
Several conditions sit outside the modeled scope, including unscheduled Bureau of Safety and Environmental Enforcement regulatory revisions, Pacific Coast offshore wind lease auction delays, and copper tether supply chain disruptions beyond documented raw material constraints. Forecasts reflect documented assumptions about pilot certification pipeline expansion and resident ROV architecture commercialization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market