
 Missile Guidance System Market | 2026-2036
Missile Guidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Missile Guidance System Market Outlook
Market Context
Export-credit financing and sovereign-guaranteed leasing vehicles is fragmenting the traditional prime-contractor lock on missile guidance programs, enabling mid-tier suppliers to bid on subsystem development. Raytheon Technologies Corporation leverages its captive radar foundry capacity to dominate seeker production for precision munitions. BAE Systems anchors European supply security through its UK-based guidance electronics manufacturing complex. Lockheed Martin Corporation sustains technology leadership in multi-mode sensor fusion architectures for next-generation interceptors.
Technical Definition and Segment Structure
A missile guidance system comprises integrated sensor arrays, inertial measurement units, flight-control computers, and targeting algorithms that compute trajectory corrections to steer a munition toward its designated objective, typically achieving circular error probable specifications measured in single-digit meters for precision applications. The technology dimension spans radar, infrared, GPS, and laser modalities, with infrared and multi-spectral fusion segments commanding premium engineering margins due to countermeasures resilience requirements. Within the application taxonomy, defense and naval categories absorb the majority of procurement volume, while aerospace applications for hypersonic boost-glide vehicles represent the fastest-expanding demand pool as thermal-management constraints drive specialized guidance packaging.
Regulatory Environment
The US Department of Defense and the US State Department's Directorate of Defense Trade Controls shape market access through International Traffic in Arms Regulations licensing and technology-release protocols, while NATO's Standardization Office harmonizes interoperability requirements across allied procurement programs. The US Missile Defense Agency's test-and-certification mandates for exoatmospheric kill vehicles impose multi-year validation cycles that filter supplier eligibility. Stakeholders must monitor how classified algorithm-export controls evolve as artificial intelligence-enabled target recognition capabilities proliferate through allied defense industrial bases.
Market Dynamics
Hypersonic thermal-management constraints are compressing development cycles and forcing prime contractors to re-architect guidance electronics packaging, while NATO interoperability mandates simultaneously expand addressable contract pools for qualified subsystem suppliers.
Growth Catalysts
- US DoD software certification acceleration:Compressed validation protocols for autonomous targeting algorithms enable faster fielding of precision munitions, expanding procurement velocity for qualified vendors.
- Export-credit financing vehicles:Sovereign-guaranteed leasing mechanisms fragment traditional prime-contractor lock on major programs, opening subsystem bids to mid-tier guidance electronics specialists.
- Multi-spectral fusion resilience:Countermeasures-hardened infrared and radar sensor integration commands premium engineering margins as defense ministries prioritize survivable seeker architectures.
Market Restraints
- Specialized thermal-management materials:Ceramic matrix composites and refractory metallurgy for hypersonic nosecones face concentrated supply from limited foundry capacity, creating input cost volatility.
- ITAR licensing friction:The US State Department's Directorate of Defense Trade Controls imposes multi-year technology-release protocols that filter foreign market access for algorithm-intensive guidance systems.
- Exoatmospheric validation cycles:Missile Defense Agency test-and-certification mandates for kill vehicles impose structural timeline barriers that extend program development.
Strategic Opportunities
- AI-enabled target recognition:Machine-vision algorithm convergence with millimeter-wave radar creates white space for autonomous terminal-homing systems in contested electromagnetic environments.
- UK guidance electronics manufacturing:BAE Systems' captive UK-based complex positions domestic suppliers for NATO standardization office interoperability contracts across European procurement pools.
- Naval hypersonic boost-glide integration:Surface-launched precision-strike applications for maritime platforms represent underpenetrated demand as thermal-management packaging adapts to salt-air corrosion constraints.
Industry Challenges
- Algorithm-export control evolution:Classified artificial-intelligence target-recognition capabilities face tightening bilateral technology-release negotiations, complicating allied industrial base collaboration.
- Legacy sensor fusion integration:Multi-mode architectures must interface with existing platform fire-control systems, creating software-hardware compatibility execution risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missile Guidance System Market |
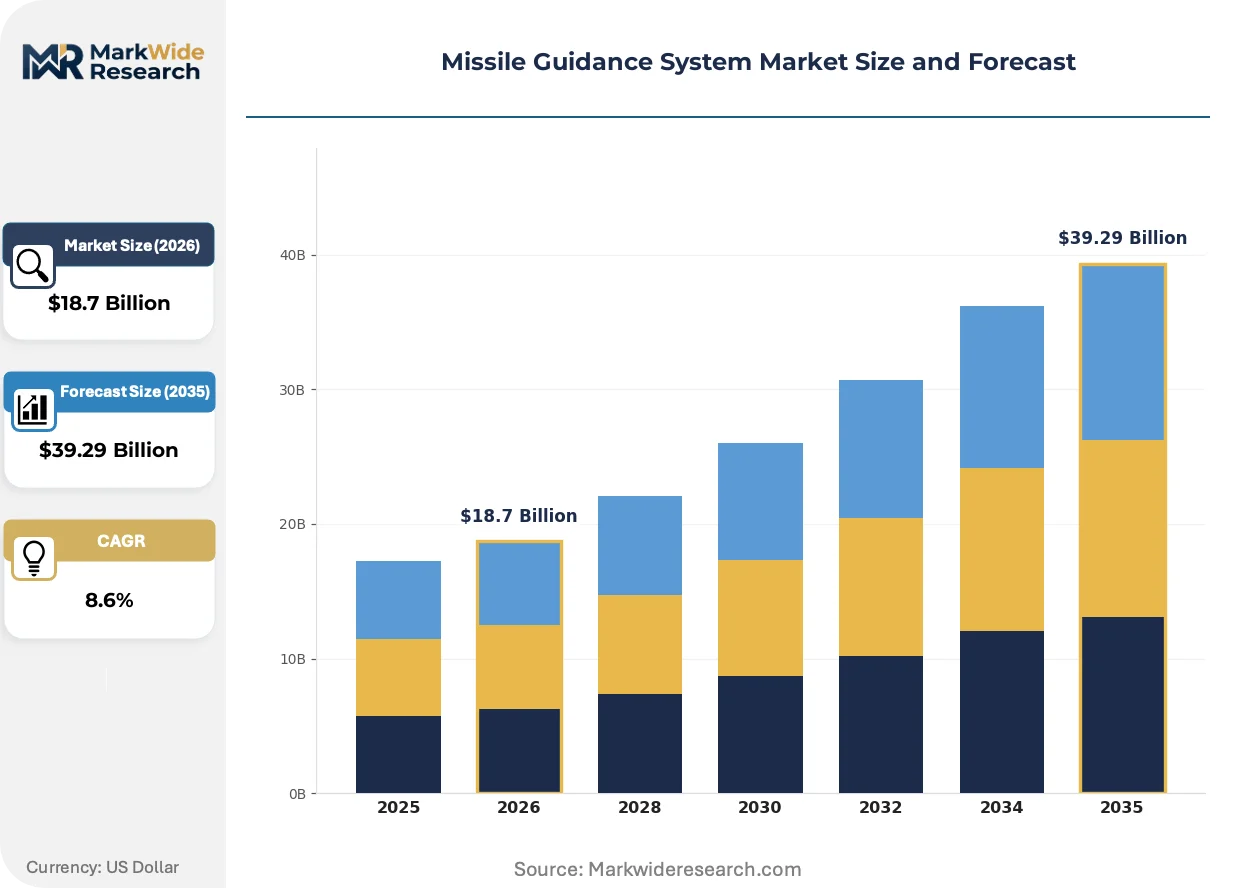
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Infrared, GPS, Laser Application: Defense, Aerospace, Naval, Ground End User: Military, Government, Contractors, OEMs Component: Control Systems, Sensors, Guidance Mechanisms, Software |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, BAE Systems, Northrop Grumman Corporation, The Boeing Company, Thales Group, General Dynamics Corporation, Leonardo S.p.A., Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missile Guidance System Market Strategic Shifts
Active electronically scanned array miniaturization is compressing seeker form factors while thermal-protection material science enables sustained operation in hypersonic flight regimes. These shifts are redefining competitive differentiation around packaging density and environmental survivability.
Silicon-carbide power electronics operate at junction temperatures exceeding silicon limits by 150°C, enabling guidance computer placement closer to aerodynamically heated airframes. Prime contractors are adopting these substrates for next-generation interceptors. Gallium-nitride radar front-ends is rendering obsolete legacy gallium-arsenide transmit-receive modules in precision munitions programs.
The EU AI Act's risk-classification framework for autonomous weapon systems is imposing algorithmic transparency requirements on European defense procurement. Contractors must document training-data provenance and decision-logic interpretability for seeker software. Naval surface-fire applications face the steepest compliance burden as member states transpose the directive into national offset rules.
Multi-year performance-based logistics contracts are displacing transactional spare-part purchases for guidance system sustainment. The Pentagon's weapon-systems acquisition chief mandates availability guarantees rather than component orders. This restructuring concentrates most visibly in US Air Force precision-munitions depot maintenance, where prime contractors assume full subsystem lifecycle responsibility.
Missile Guidance System Market Segmentation
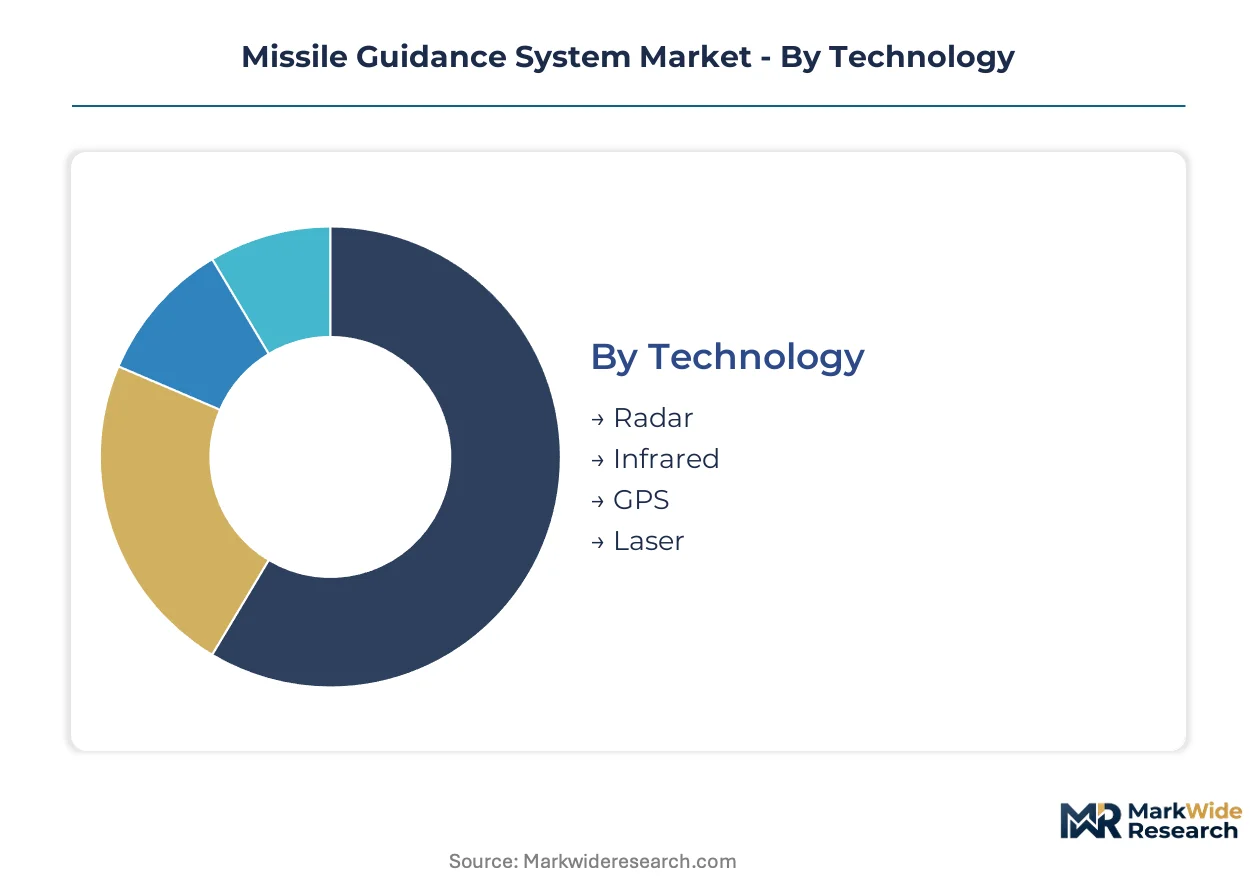
Segmentation in missile guidance systems reveals how procurement priorities diverge across mission profiles and platform constraints. Defense ministries allocate budgets differently for hypersonic interceptors versus precision-strike munitions, while thermal-management requirements reshape component sourcing strategies.
Technology:
Precision-strike missions demand sensor modalities that survive electronic countermeasures and adverse weather, creating tiered performance expectations across guidance architectures.
- Radar:Active electronically scanned arrays with gallium-nitride front-ends deliver all-weather target acquisition for precision munitions. Pentagon procurement for next-generation interceptors concentrates demand in the United States, where software certification acceleration compresses fielding timelines.
- Infrared:Multi-spectral focal plane arrays enable passive target discrimination in contested electromagnetic environments. NATO interoperability mandates expand addressable contract pools for qualified subsystem suppliers across European defense industrial bases.
- GPS:Anti-jam receiver modules with M-code encryption provide resilient position-fixing for satellite-dependent architectures.
- Laser:Semi-active and beam-riding configurations serve short-range precision applications with minimal electronic signature.
The dominant share belongs to Radar, while Infrared is closing the gap fastest.
Application:
Platform integration constraints determine packaging density and thermal-protection requirements, with hypersonic boost-glide vehicles imposing the steepest engineering margins.
- Defense:Surface-to-air and ballistic missile defense interceptors require exoatmospheric kill vehicle architectures with multi-mode sensor fusion. Missile Defense Agency validation cycles extend development timelines for prime contractors pursuing these programs.
- Aerospace:Hypersonic boost-glide vehicles demand ceramic matrix composite nosecones and silicon-carbide power electronics operating at extreme temperatures. Thermal-management material scarcity creates input cost volatility for specialized guidance packaging.
- Naval:Vertical-launch and deck-mounted systems must survive salt-air corrosion while maintaining precision in maritime clutter environments.
- Ground:Mobile launch platforms prioritize rapid alignment and reduced thermal signature for survivable deployment.
Defense commands the largest procurement volume, though Aerospace exhibits the steepest expansion trajectory as hypersonic roadmaps mature.
End User:
Contractual risk allocation differs sharply between sovereign procurement offices and delegated manufacturing arrangements.
- Military:Armed forces operate as direct procurement authorities for operational munitions, with performance-based logistics contracts displacing transactional spare-part purchases.
- Government:Defense ministries manage multi-year hypersonic weapons roadmaps and software certification protocols that shape vendor qualification.
- Contractors:Mid-tier subsystem specialists bid on guidance electronics through sovereign-guaranteed leasing vehicles that fragment traditional prime-contractor lock.
- OEMs:Platform integrators specify seeker interfaces for fire-control system compatibility, creating software-hardware integration execution risks.
Military end users dominate direct procurement, while Contractors gain share fastest through export-credit financing mechanisms.
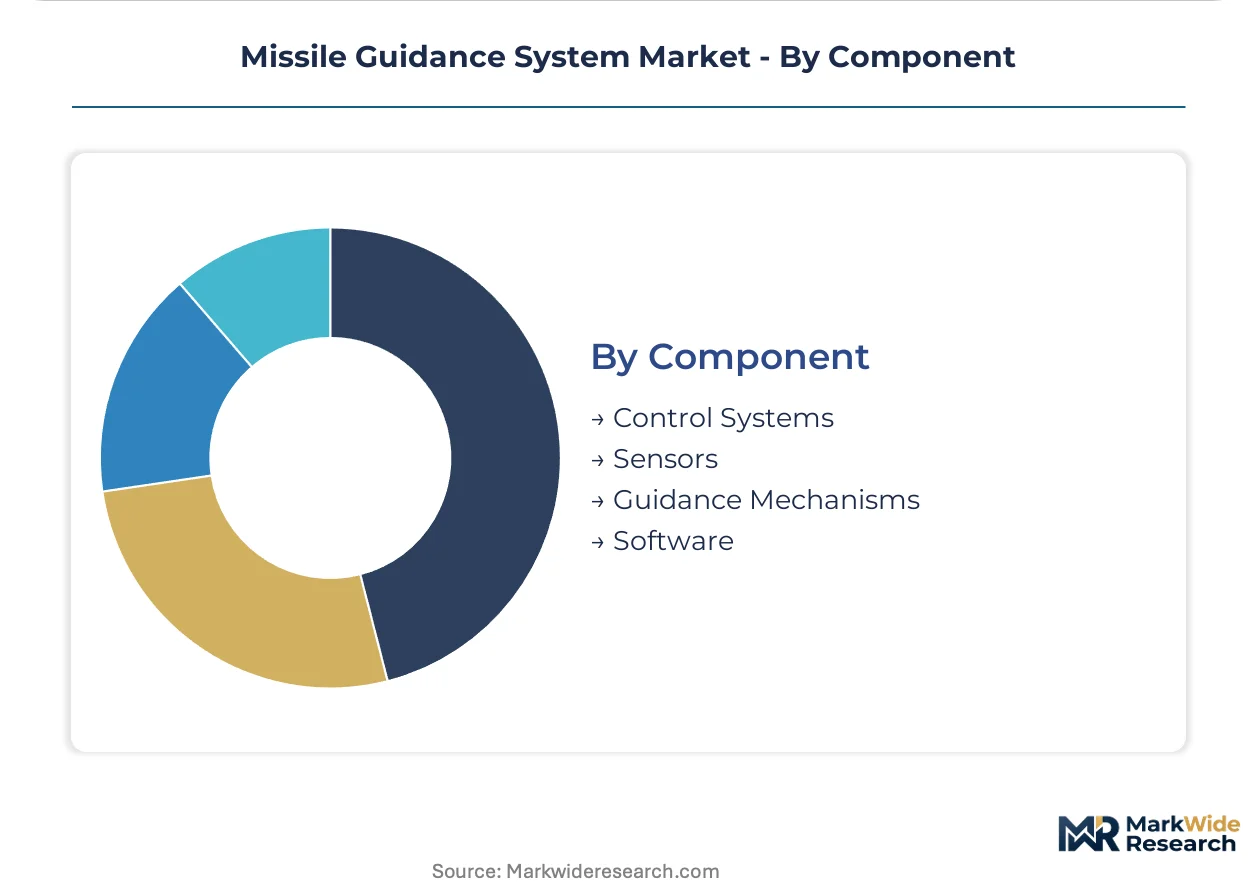
Component:
Value concentration varies across the guidance chain, with algorithm-intensive software commanding premium engineering margins.
- Control Systems:Flight-control computers with silicon-carbide substrates enable placement closer to aerodynamically heated airframes. US Air Force precision-munitions depot maintenance concentrates sustainment responsibility with prime contractors under availability guarantees.
- Sensors:Inertial measurement units and seeker arrays constitute the largest material cost share, with gallium-nitride radar front-ends rendering legacy gallium-arsenide modules obsolete.
- Guidance Mechanisms:Actuator and fin-control hardware interfaces with platform aerodynamics to execute trajectory corrections.
- Software:Autonomous target recognition algorithms face tightening ITAR licensing friction and EU AI Act transparency requirements for European procurement.
Sensors retain the dominant value share, while Software climbs fastest as artificial intelligence-enabled capabilities proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices concentrate demand in sovereign buyers with multi-year hypersonic roadmaps and precision-strike modernization programs. National security imperatives and alliance interoperability mandates shape vendor qualification requirements across NATO and Indo-Pacific partner states.
United States
The Pentagon's accelerated software certification protocols compress development cycles for autonomous targeting systems. The US State Department's Directorate of Defense Trade Controls imposes ITAR licensing requirements that filter foreign market access. Prime contractors cluster in the Washington DC-Virginia corridor and Arizona's defense electronics manufacturing belt.
Germany
The Bundeswehr's precision munitions procurement expands through NATO standardization office interoperability contracts. Germany's Federal Office for Economic Affairs and Export Control enforces dual-use technology licensing for guidance electronics. Industrial capacity concentrates in Bavaria's aerospace cluster and Baden-Württemberg's sensor technology corridor.
United Kingdom
BAE Systems' UK-based guidance electronics manufacturing complex anchors European supply security for allied procurement. The UK Ministry of Defence's hypersonic weapons research program drives investment in thermal-management packaging. Engineering expertise clusters around Bristol's defense aerospace hub and Scotland's electronics manufacturing corridor.
France
Thales Group and Safran S.A. leverage domestic radar and inertial navigation capabilities for European missile programs. France's Direction Générale de l'Armement oversees technology release protocols for algorithm-intensive seeker systems. The Paris-Saclay technology cluster and Toulouse aerospace corridor host specialized guidance electronics development.
Japan
The Japan Ministry of Defense's counterstrike capability roadmap expands procurement for precision-strike munitions with indigenous guidance architectures. METI's defense production base maintenance program subsidizes dual-use sensor technology development. Manufacturing concentrates in the Nagoya aerospace cluster and Kanto region's precision electronics corridor.
Missile Guidance System Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure concentrated around prime contractors with captive foundry capacity and mid-tier subsystem specialists accessing programs through sovereign financing vehicles. The vendor base stratifies into three archetypes: vertically integrated primes with in-house seeker production, specialist guidance electronics manufacturers, and algorithm-focused software houses. Competitive moves center on multi-year performance-based logistics contracts displacing transactional spare-part purchases, and strategic partnerships for thermal-management material sourcing.
Among US-based prime contractors, Lockheed Martin Corporation and Raytheon Technologies Corporation occupy positions exemplifying the integrated-architecture archetype, while BAE Systems anchors the European supply-security tier. These entities represent the channel-control end of the competitive spectrum, with their geographic footprints and corporate structures reflecting national defense industrial base configurations rather than pure commercial positioning.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| BAE Systems |
| Northrop Grumman Corporation |
| The Boeing Company |
| Thales Group |
| General Dynamics Corporation |
| Leonardo S.p.A. |
| Safran S.A. |
| Others |
Value Chain & Pricing Dynamics
Arizona's defense electronics manufacturing belt concentrates gallium-nitride foundry capacity for radar front-ends, creating asymmetric pricing power for prime contractors who control captive wafer supply. Thermal-management material scarcity in ceramic matrix composites feeds cost volatility downstream, compressing margins for subsystem specialists without upstream refractory metallurgy access.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate Pentagon procurement for precision munitions, insulating prime contractors from input volatility while exposing mid-tier suppliers to ceramic matrix composite price swings. Price differentiation separates ITAR-cleared algorithm developers from uncertified competitors, with M-code GPS receiver modules commanding premiums over commercial-grade alternatives. Cost compression in thermal-protection packaging intensifies as hypersonic program volumes strain limited foundry capacity. Government procurement offices exhibit lowest price sensitivity due to sovereign-guaranteed financing vehicles, while export-credit-funded mid-tier bidders face acute margin pressure.
Supply Chain Analysis
Raytheon's captive radar foundry and BAE Systems' UK-based guidance electronics complex concentrate contract manufacturing for seeker arrays and inertial measurement units. Sourcing draws from United States gallium-nitride substrate production, United Kingdom precision machining clusters, and Japanese inertial sensor component suppliers. Single-source vulnerability concentrates in ceramic matrix composite nosecone fabrication, where limited refractory metallurgy capacity creates structural bottlenecks. Distribution runs through prime contractor integration facilities to defense ministry procurement offices, with performance-based logistics contracts displacing transactional spare-part channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Export-credit financing fragmentation creates white-space opportunities for subsystem specialists as sovereign-guaranteed leasing vehicles erode traditional prime-contractor lock on major programs.
For Market Incumbents:Harden algorithm-export control compliance infrastructure against tightening ITAR licensing friction for artificial-intelligence target recognition capabilities. Deepen captive supply of ceramic matrix composite thermal-protection materials through backward integration into refractory metallurgy foundries, insulating against input cost volatility that threatens margin structures in hypersonic guidance packaging.
For New Entrants and Emerging Players:Establish a beachhead in naval hypersonic boost-glide integration, where salt-air corrosion constraints and thermal-management packaging requirements have left surface-launched precision-strike applications underpenetrated. Target NATO standardization office interoperability contracts through BAE Systems' UK-based supplier network, leveraging sovereign-guaranteed leasing vehicles to bypass traditional prime-contractor gatekeeping on European defense procurement.
For Investors and Strategic Acquirers:Long-term, this sits as a consolidation play because export-credit financing fragmentation will eventually concentrate around subsystem specialists with proven ITAR clearance and thermal-management material science capabilities. Acquisition targets should exhibit captive silicon-carbide power electronics packaging expertise and established Missile Defense Agency test-certification relationships. Watch for EU AI Act algorithmic transparency compliance burdens triggering distressed divestitures of European seeker software assets.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Compliance Infrastructure Investment | Accelerates foreign market access for algorithm-intensive guidance systems under State Department technology-release protocols. |
| Ceramic Matrix Composite Backward Integration | Secures refractory metallurgy supply against concentrated foundry capacity creating input cost volatility. |
| Performance-Based Logistics Contracting | Aligns prime contractor incentives with Pentagon availability mandates displacing transactional spare-part purchases. |
| Multi-Spectral Sensor Fusion R&D | Commands premium engineering margins as NATO ministries prioritize countermeasures-resilient seeker architectures. |
| EU AI Act Transparency Compliance | Enables continued European procurement participation as algorithmic documentation requirements tighten for autonomous targeting. |
Study Parameters
Cross-validation between primary interviews with guidance system program managers, defense procurement officers, thermal-materials foundry engineers, and subsystem integration specialists and secondary validation through Pentagon budget justification documents, Missile Defense Agency test schedules, NATO standardization office technical specifications, and ITAR licensing disclosure filings anchors the qualitative findings. Bottom-up build from component-level cost structures and top-down reconciliation against sovereign defense expenditure databases ensures triangulation integrity.
Calibration against historical program cost growth rates in precision munitions and hypersonic interceptor development anchors the analytical framework across the projection horizon. Segmentation dimensions span technology modality, application platform, end-user procurement authority, and component value chain position, with thermal-management packaging density and software certification status as missile guidance-specific stratifiers. CAGRs derive from multivariate regression against defense budget allocation trends and program-of-record fielding timelines, incorporating silicon-carbide substrate adoption curves and gallium-nitride radar front-end penetration rates as technology diffusion inputs.
Sensitivities concentrate around ITAR licensing friction escalation, ceramic matrix composite supply disruptions, and EU AI Act enforcement intensity on algorithmic transparency requirements. Forecasts embed assumptions regarding Pentagon software certification acceleration sustaining and NATO interoperability mandate expansion continuing. Quarterly review of Missile Defense Agency test-certification backlog, State Department technology-release approval velocity, and thermal-management material spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Autonomous Aircraft Market